
 Therapeutic Medical Guidewire Market | 2026-2036
Therapeutic Medical Guidewire Market Size, Share, and Industry Trends Forecast 2026-2036
Therapeutic Medical Guidewire Market Analysis
Nitinol is pivoting toward center stage in guidewire construction as manufacturers trade cobalt-chromium and stainless steel cores for superelastic nickel-titanium alloys that reduce kinking and improve vessel navigation. Boston Scientific Corporation leverages in-house nitinol drawing capabilities to control alloy grain structure across its coronary portfolio. Asahi Intecc Co., Ltd. anchors its competitive stance through proprietary composite core technology that layers stainless steel with platinum alloys for radiopacity. Terumo Medical Corporation dominates hydrophilic coating chemistry, sustaining market presence through proprietary polymer formulations that reduce friction during lesion crossing.
A therapeutic medical guidewire is a thin, flexible instrument typically measuring 0.014 to 0.035 inches in diameter, constructed from a central metal core wire sheathed in polymer or hydrophilic coating, designed to navigate vascular anatomy and establish access for catheter-based interventions. The device transmits rotational torque from the operator's hand to the distal tip while maintaining column strength sufficient to support balloon or stent delivery systems. Coronary guidewires occupy the largest revenue pool given the volume of percutaneous coronary interventions, while neurovascular applications represent the fastest-expanding segment as mechanical thrombectomy protocols widen the treatable stroke window. Hydrophilic coating technology commands premium positioning due to its friction-reducing properties in tortuous anatomy, though polymer-coated alternatives retain cost advantages in high-volume standard procedures.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines, with the latter's enhanced clinical evidence requirements extending certification cycles for coated wire platforms. Japan's PMDA enforces rigorous biocompatibility testing for nitinol alloys, creating a technical barrier that favors established manufacturers with dedicated metallurgical laboratories. Stakeholders must monitor evolving reimbursement thresholds for same-day peripheral interventions, as payor compression in hospital and ambulatory surgical center settings will determine whether premium-coated guidewires retain their price position against standard alternatives.
Market Dynamics
Nitinol alloy substitution for stainless steel cores is compressing manufacturing cost curves while expanding treatable lesion complexity, forcing incumbent suppliers to reconfigure metallurgical capabilities or cede share to integrated nitinol processors.
Growth Catalysts
- Mechanical thrombectomy protocol expansion:Stroke treatment windows now extend to 24 hours in select patients, multiplying neurovascular guidewire deployments in academic medical centers across the United States.
- EU Medical Device Regulation harmonization:MDR's enhanced clinical evidence requirements favor established manufacturers with dedicated regulatory affairs infrastructure, accelerating consolidation among coated-wire specialists.
- Ambulatory surgical center licensure:United States Medicare reimbursement expansion for same-day peripheral interventions is routing volume away from hospital catheterization laboratories into lower-cost outpatient settings.
Market Restraints
- Nitinol raw material concentration:Superelastic nickel-titanium alloy supply concentrates among a handful of specialized melt shops in the United States and Europe, exposing downstream wire manufacturers to input volatility.
- Biocompatibility testing burden:Japan's PMDA enforces extended cytotoxicity and sensitization protocols for nitinol-containing devices, extending certification timelines by 12-18 months versus FDA 510(k) pathways.
- Polymer coating durability limitations:Hydrophilic coatings degrade after single-use sterilization cycles, preventing reprocessing and locking cost structures at premium single-use price points.
Strategic Opportunities
- India peripheral vascular penetration:Diagnostic catheterization volumes in tier-2 Indian cities remain 60-70% below metropolitan benchmarks, creating whitespace for distributor-led guidewire education programs.
- Composite core technology convergence:Layering platinum alloys with stainless steel cores is expanding radiopacity without sacrificing torque transmission, opening coronary chronic total occlusion procedures previously deemed untreatable.
- United States site-of-care arbitrage:Office-based lab accreditation for peripheral interventions is capturing Medicare reimbursement previously reserved for hospital outpatient departments.
Industry Challenges
- Metallurgical talent scarcity:Nitinol grain structure optimization requires specialized materials science expertise concentrated among a shrinking cohort of aging alloy engineers.
- Coating chemistry IP thickets:Proprietary polymer formulations for friction reduction are encumbered by overlapping patent estates, complicating new entrant formulation freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapeutic Medical Guidewire Market |
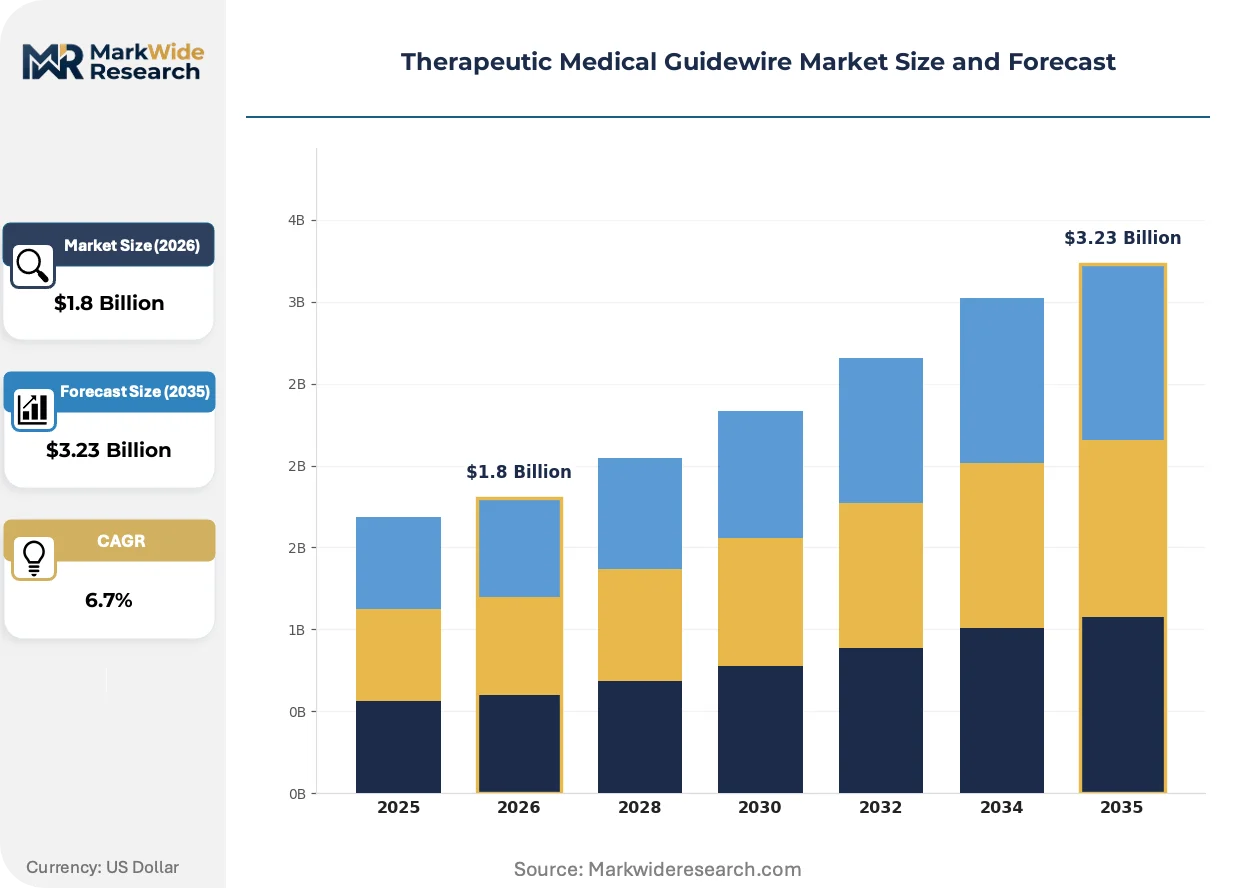
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coronary, Peripheral, Neurovascular, Standard Technology: Hydrophilic, Steel, Polymer, Coated End User: Hospitals, Clinics, Specialty Centers, Ambulatory Surgical Centers Application: Cardiology, Neurosurgery, Interventional Radiology, Urology |
| Companies Covered | Medtronic plc, Cook Medical, Boston Scientific Corporation, Teleflex Incorporated, Cardinal Health, Terumo Medical Corporation, Asahi Intecc Co., Ltd., B. Braun Melsungen AG, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapeutic Medical Guidewire Market Emerging Trajectories
Guidewire construction is bifurcating between premium nitinol platforms for complex lesions and commoditized stainless steel alternatives for standard procedures, with coating chemistry emerging as the primary differentiation vector.
Robotic-assisted percutaneous coronary intervention systems are expanding into high-volume catheterization laboratories, with operators adopting torque-responsive guidewires that transmit haptic feedback through robotic manipulators. Academic medical centers in Germany and the Netherlands are piloting these platforms for chronic total occlusion cases. The technology is expanding into training protocols, compressing the learning curve for complex lesion crossing while raising performance standards for wire trackability.
The EU Medical Device Regulation's enhanced clinical evidence requirements are compressing product development timelines for hydrophilic-coated platforms, forcing manufacturers to front-load biocompatibility studies before design freeze. Small-to-mid-sized wire specialists without dedicated regulatory affairs infrastructure are outsourcing notified body interactions to specialized consultancies. Cardiovascular device categories face the steepest compliance burden, with Class III guidewire extensions requiring post-market clinical follow-up studies that add 18-24 months to commercialization cycles.
Hospital procurement committees are consolidating guidewire purchasing across cardiology and radiology service lines, replacing specialty-specific contracts with enterprise-wide agreements that favor multi-segment suppliers. Integrated delivery networks in the United States are bundling coronary and peripheral wire volumes to extract tiered pricing concessions. This concentration is most visible in the southeastern United States, where regional health systems have reduced active supplier rosters from 6-8 vendors to 2-3 preferred partners.
Therapeutic Medical Guidewire Market Segmentation
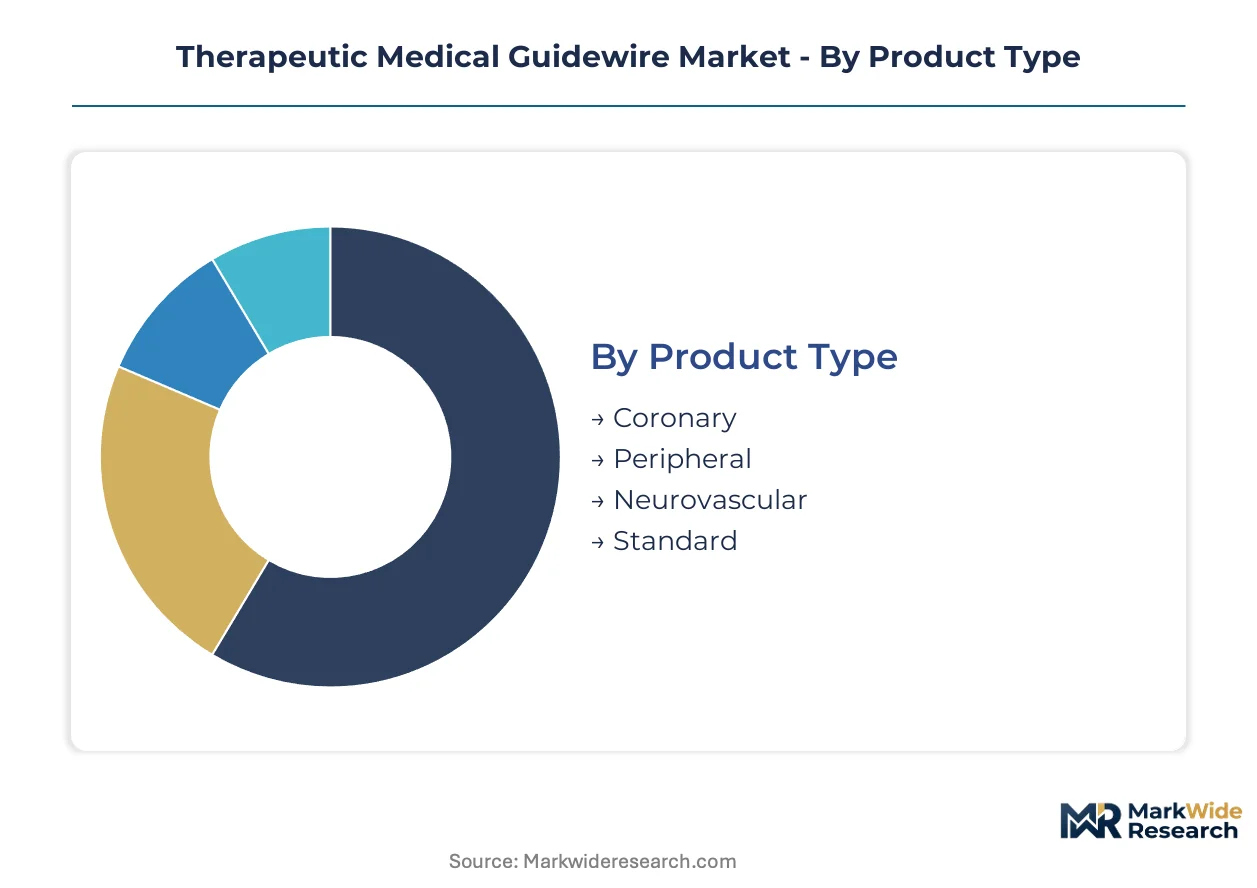
Therapeutic medical guidewire purchasing fragments across clinical specialties with divergent performance requirements. Cardiology suites demand torque-responsive platforms for chronic total occlusion cases, while interventional radiology prioritizes hydrophilic coatings for tortuous peripheral anatomy.
Product Type:
Customization intensity varies sharply across this category, with complex lesion applications demanding bespoke core geometries while standard procedures accept off-the-shelf configurations.
- Coronary:Composite core architectures layer stainless steel with platinum alloys to optimize radiopacity without sacrificing torque transmission. Demand concentrates in United States academic medical centers where mechanical thrombectomy protocols now extend stroke treatment windows to 24 hours in select patients. Nitinol substitution for traditional cores is compressing manufacturing cost curves while expanding treatable lesion complexity.
- Peripheral:Hydrophilic coating chemistry dominates femoral-popliteal interventions where vessel tortuosity exceeds coronary anatomy. Ambulatory surgical center networks across the southeastern United States are broadening access to these procedures through Medicare reimbursement expansion for same-day interventions. Coating durability limitations prevent reprocessing, locking cost structures at premium single-use price points.
- Neurovascular:Superelastic nickel-titanium alloys reduce kinking during intracranial navigation.
- Standard:Stainless steel cores retain cost advantages in high-volume baseline procedures.
Most installed capacity flows through Coronary. Expansion is steepest in Neurovascular.
Technology:
Cost tier stratification separates premium-coated platforms from commodity alternatives, with reimbursement thresholds determining category mix in hospital and outpatient settings.
- Hydrophilic:Proprietary polymer formulations reduce friction coefficients during lesion crossing, commanding premium positioning in tortuous anatomy. Japan's PMDA enforces extended cytotoxicity protocols for coated platforms, extending certification timelines by 12-18 months versus FDA 510(k) pathways. Terumo Medical Corporation dominates this chemistry through captive formulation expertise.
- Steel:Traditional stainless steel cores retain procurement committee favor for standard procedures where coating premiums cannot be recovered through reimbursement. Integrated delivery networks in the United States bundle coronary and peripheral volumes to extract tiered pricing concessions from multi-segment suppliers.
- Polymer:Sheathed constructions balance trackability against column strength requirements.
- Coated:Alternative surface treatments address specific biocompatibility constraints.
Procurement volume concentrates in Hydrophilic. Margin expansion is fastest in Steel as nitinol substitution compresses input costs.
End User:
Site-of-care migration is reshaping customer mix, with procedures shifting from hospital catheterization laboratories toward lower-cost outpatient venues.
- Hospitals:Interventional cardiology suites in United States hospital systems anchor guidewire utilization for percutaneous coronary procedures. Enterprise-wide purchasing agreements are replacing specialty-specific contracts, consolidating supplier rosters from 6-8 vendors to 2-3 preferred partners.
- Ambulatory Surgical Centers:Medicare reimbursement expansion for same-day peripheral interventions is routing volume away from hospital outpatient departments. Office-based lab accreditation is capturing reimbursement previously reserved for hospital settings.
- Clinics:Diagnostic catheterization volumes in tier-2 Indian cities remain below metropolitan benchmarks.
- Specialty Centers:Focused facilities concentrate complex case volumes requiring premium platform capabilities.
Revenue concentration sits with Hospitals. Patient volume is migrating fastest toward Ambulatory Surgical Centers.
Application:
Clinical outcome requirements determine specification intensity, with neurovascular interventions demanding highest performance tolerances.
- Cardiology:Percutaneous coronary intervention volumes drive the largest revenue pool, with operators adopting torque-responsive guidewires that transmit haptic feedback through emerging robotic-assisted platforms. Boston Scientific Corporation leverages in-house nitinol drawing capabilities to control alloy grain structure across this segment.
- Neurosurgery:Mechanical thrombectomy protocol expansion is multiplying neurovascular guidewire deployments as treatable stroke windows widen. Asahi Intecc Co., Ltd. anchors its competitive stance through proprietary composite core technology optimized for intracranial navigation.
- Interventional Radiology:Peripheral vascular interventions require hydrophilic coating durability for femoral access.
- Urology:Specialized access procedures utilize smaller-diameter wire configurations.
Procedure volume concentrates in Cardiology. Technical specification intensity is highest in Neurosurgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minnesota's Twin Cities medical technology corridor anchors therapeutic guidewire production, concentrating nitinol metallurgy expertise and hydrophilic coating R&D facilities that supply interventional suites worldwide.
United States
FDA 510(k) clearance pathways compress regulatory timelines for nitinol-core platforms, accelerating product launches versus European certification cycles. Ambulatory surgical center networks across the southeastern United States are capturing Medicare reimbursement for same-day peripheral interventions, routing volume away from hospital catheterization laboratories. The Twin Cities corridor in Minnesota hosts concentrated guidewire manufacturing and metallurgical testing infrastructure.
Germany
Mechanical thrombectomy protocol expansion in academic medical centers drives neurovascular guidewire deployments as treatable stroke windows extend. The EU Medical Device Regulation's enhanced clinical evidence requirements favor established manufacturers with dedicated regulatory affairs infrastructure, extending certification cycles for coated-wire platforms. The Rhine-Ruhr industrial region houses specialized polymer chemistry facilities serving hydrophilic coating applications.
Japan
PMDA enforces rigorous biocompatibility testing for nitinol alloys, creating technical barriers that favor established manufacturers with dedicated metallurgical laboratories. Superelastic nickel-titanium guidewire demand concentrates in Tokyo and Osaka metropolitan medical centers performing complex chronic total occlusion procedures. The Nagoya industrial corridor supplies precision wire-drawing equipment for core wire fabrication.
India
Diagnostic catheterization volumes in tier-2 cities remain 60-70% below metropolitan benchmarks, creating whitespace for distributor-led guidewire education programs. CDSCO medical device regulations are harmonizing with international standards, streamlining import pathways for coated-wire platforms. The Mumbai-Pune pharmaceutical and medical device cluster is expanding interventional cardiology training infrastructure.
Switzerland
Swissmedic maintains stringent quality system requirements for nitinol-containing devices, reinforcing premium positioning for precision-engineered guidewire platforms. Geneva and Basel host concentrated medical technology R&D facilities focused on composite core architectures. The Swiss Jura watchmaking region supplies micro-precision manufacturing expertise transferable to guidewire tip engineering.
Therapeutic Medical Guidewire Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers scale nitinol drawing capabilities to capture cost advantages from alloy substitution. The vendor base clusters around three strategic archetypes: integrated nitinol processors with captive metallurgy, coating chemistry specialists with proprietary polymer expertise, and diversified cardiovascular device houses with multi-segment purchasing leverage. M&A activity targets regulatory infrastructure assets, while technology licensing agreements unlock coating formulation access for mid-tier entrants.
Among diversified cardiovascular device houses, Medtronic plc and Boston Scientific Corporation exemplify scale-driven positioning through multi-segment purchasing leverage. Terumo Medical Corporation occupies a distinct position as a coating chemistry specialist. Asahi Intecc Co., Ltd. represents precision-engineered composite core expertise. These three anchors illustrate how competitive differentiation vectors split between metallurgical control, surface chemistry, and torque transmission engineering.
| Leading Market Players |
|---|
| Medtronic plc |
| Cook Medical |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Cardinal Health |
| Terumo Medical Corporation |
| Asahi Intecc Co., Ltd. |
| B. Braun Melsungen AG |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Nickel-titanium alloy spot indices cascade through therapeutic guidewire manufacturing, compressing margins for stainless steel-dependent producers while amplifying pricing power for integrated nitinol processors serving complex lesion applications.
Pricing Analysis
Input-cost pass-through from superelastic alloy procurement differentiates three-tier pricing structure across premium, standard, and economy levels. Hydrophilic-coated nitinol platforms command 40-60% premiums over polymer-sheathed alternatives based on coating chemistry IP and Japan PMDA certification tier. Pricing pressure stems from Medicare reimbursement compression in United States ambulatory surgical centers, forcing mid-tier suppliers toward commodity stainless steel cores. Hospital procurement committees exhibit lowest price sensitivity for neurovascular mechanical thrombectomy suites, while peripheral intervention networks in southeastern United States demonstrate acute cost consciousness.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital systems and European notified bodies mandate multi-supplier qualification for nitinol melt shops, polymer coating chemists, and precision wire-drawing facilities. Raw material dependencies center on nickel-titanium alloys from specialized United States and European melt shops, platinum-group metals for radiopaque cores, and proprietary polymer formulations for hydrophilic coatings. Single-source vulnerability concentrates in superelastic alloy grain structure optimization, where metallurgical talent scarcity limits qualified supplier pools. Distribution runs through medical device distributors serving integrated delivery networks, with direct contracts dominating high-volume academic medical center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Therapeutic guidewire demand is shifting toward premium nitinol platforms as mechanical thrombectomy protocols expand treatable stroke windows, rewarding manufacturers with in-house metallurgical capabilities.
For Market Incumbents: Hedge against cobalt-chromium obsolescence by accelerating backward integration into nitinol drawing capabilities or securing long-term offtake agreements with specialized melt shops. Lock in GPO contracts across cardiology and radiology service lines before procurement consolidation reduces vendor rosters from 6-8 suppliers to 2-3 preferred partners. For New Entrants and Emerging Players: Capture whitespace in tier-2 Indian cities where diagnostic catheterization volumes trail metropolitan benchmarks by 60-70%, deploying distributor-led education programs to build clinical familiarity with hydrophilic-coated platforms. Target neurovascular mechanical thrombectomy as the most penetrable premium segment, leveraging CDSCO regulatory harmonization to streamline import pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with coating chemistry specialists possessing proprietary polymer formulations and established PMDA biocompatibility dossiers. Long-term viability favors acquisition targets with captive nitinol metallurgy and regulatory infrastructure assets across FDA 510(k) and EU MDR pathways. Watch for Medicare reimbursement threshold adjustments for same-day peripheral interventions as the inflection signal determining premium-coated guidewire price retention.| Strategic Initiative | Industry Significance |
|---|---|
| Nitinol Drawing Capability Acquisition | Captive metallurgy controls alloy grain structure for chronic total occlusion platforms. |
| Hydrophilic Coating IP Licensing | Polymer formulation access unlocks friction-reducing properties in tortuous anatomy. |
| EU MDR Regulatory Infrastructure Buildout | Enhanced clinical evidence capabilities compress certification cycles for coated-wire platforms. |
| India Distribution Network Expansion | Tier-2 city education programs address 60-70% underpenetration in diagnostic catheterization. |
| Robotic-Assisted PCI Partnership | Torque-responsive guidewire integration with haptic feedback systems raises performance standards. |
Methodological Framework
Direct dialogue with interventional cardiologists, neurovascular surgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers grounded qualitative findings in clinical workflow realities. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, hospital procurement records, and nitinol alloy trade flow data. Bottom-up and top-down triangulation reconciled procedure volume estimates with manufacturer shipment data across coronary, peripheral, and neurovascular segments.
Bottom-up modeling anchored volume projections to per-procedure guidewire utilization rates by intervention type, while top-down cross-checks validated aggregate market sizing against disclosed cardiovascular device revenue. Segmentation dimensions spanned product type, coating technology, end-user site-of-care, and application specialty across the projection horizon. CAGRs derived from weighted procedure growth assumptions, reimbursement trajectory modeling, and nitinol substitution elasticity estimates in chronic total occlusion cases.
Regulatory timeline delays, nickel-titanium alloy supply disruptions, and Medicare reimbursement compression are the dominant revision risks to therapeutic guidewire demand assumptions. Deviation in PMDA biocompatibility testing duration would shift commercialization cycles and competitive positioning materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Therapeutic Bed Market
Diagnostic and Therapeutic Devices
One-Step ELISA Market
Diagnostic and Therapeutic Devices
Global Acute Ischemic Stroke Diagnosis and Treatment Market
Diagnostic and Therapeutic Devices
Germany Smart Healthcare Market
Diagnostic and Therapeutic Devices
Venous Diseases Treatment Market
Diagnostic and Therapeutic Devices
Pelvic Congestion Syndrome Treatment Market
Diagnostic and Therapeutic Devices
Disposable Negative Pressure Wound Therapy Devices Market
Diagnostic and Therapeutic Devices
Global Smart Healthcare Products Market
Diagnostic and Therapeutic Devices
Dental Surgical and Diagnostic Devices Market
Diagnostic and Therapeutic Devices
Acupuncture Needles Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Smart Inhalers Market
Diagnostic and Therapeutic Devices
Dermatology Diagnostic Equipment Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Therapeutic Hypothermia Systems Market