
 Digital Medical Thermometers Market | 2026-2036
Digital Medical Thermometers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Medical Thermometers Market Insights
Remote patient monitoring subscriptions is realigning how digital thermometers generate recurring revenue beyond hardware sales. Omron Corporation leverages its connected health platform to bundle Bluetooth-enabled devices with cloud-based vital tracking. Terumo Corporation anchors its position through hospital-grade calibration services that extend device lifecycle value. Microlife Corporation specializes in fever management algorithms that differentiate its consumer-facing applications.
A digital medical thermometer is an electronic temperature measurement instrument employing thermistors, infrared sensors, or thermocouples to quantify body heat with precision typically within ±0.1°C, designed for clinical screening, home diagnostics, and epidemiological surveillance. Infrared forehead units dominate hospital procurement due to non-contact speed and cross-contamination control, while thermocouple oral devices retain margin strength in home care through low-cost disposability. Pharmacy distribution channels carry the highest volume throughput, though direct sales to health systems capture superior per-unit economics through contract bundling.
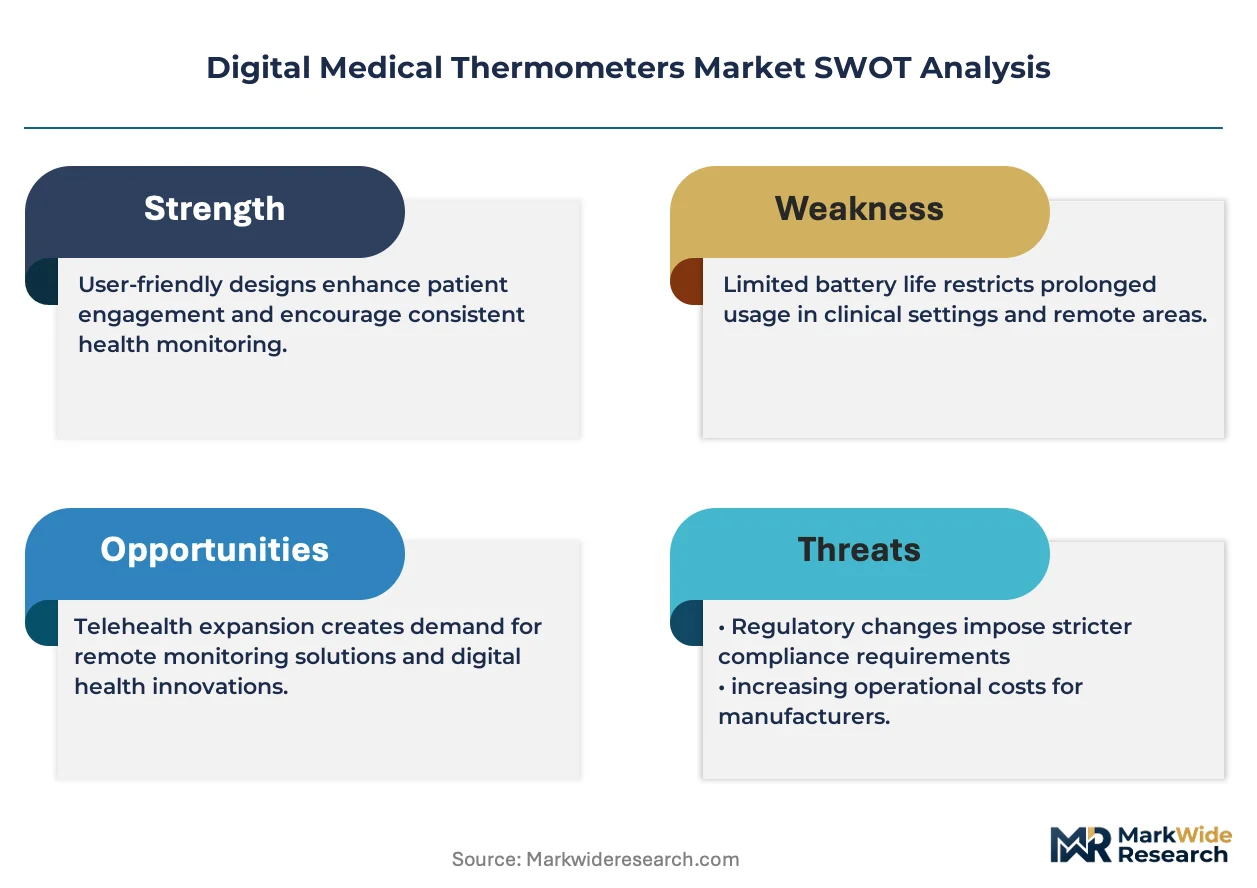
FDA 510(k) premarket notifications and EU MDR conformity assessments impose accuracy validation burdens that filter out uncertified competitors. ISO 80601-2-56 standards for clinical thermometer safety shape design specifications across manufacturing bases. Stakeholders must weigh software validation costs against the margin compression from commoditized hardware segments.
Market Dynamics
FDA 510(k) clearance requirements for clinical accuracy are compressing product development timelines while simultaneously filtering out uncertified competitors, creating a bifurcation between hospital-grade and consumer-grade thermometer segments.
Growth Catalysts
- Home Care Self-Monitoring:Chronic disease management protocols in the United States are expanding household thermometer penetration as aging demographics prioritize preventive health tracking.
- EU MDR Conformity Assessments:Stricter safety validation under the Medical Device Regulation is elevating certified manufacturers above commodity competitors in European procurement.
- Infrared Non-Contact Technology:Cross-contamination control requirements in acute care settings are accelerating hospital procurement of forehead-based temperature measurement systems.
Market Restraints
- Thermistor Input Volatility:Semiconductor supply concentration in East Asian foundries exposes thermometer manufacturers to component pricing fluctuations and allocation constraints.
- Software Validation Burden:ISO 80601-2-56 compliance costs for connected devices are compressing margins in commoditized hardware segments where firmware differentiation is minimal.
- Smartwatch Temperature Substitution:Wearable health monitors with skin-surface thermal sensors are capturing low-acuity consumer temperature checks previously served by dedicated thermometers.
Strategic Opportunities
- Remote Patient Monitoring Integration:Bluetooth-enabled thermometers bundled with cloud-based vital tracking platforms are creating recurring revenue streams beyond one-time hardware sales.
- Pharmacy Direct-to-Consumer Channels:Retail pharmacy distribution networks offer volume throughput expansion for calibrated consumer devices with clinical-grade accuracy claims.
- Fever Management Algorithm Licensing:Proprietary diagnostic software for symptom tracking and medication timing represents white-space monetization in digital health ecosystems.
Industry Challenges
- Firmware Cybersecurity Certification:Connected thermometer platforms face escalating validation requirements for HIPAA-compliant data transmission and cloud storage architectures.
- Hospital Procurement Contract Bundling:Health system volume aggregation is compressing per-unit economics and extending payment cycles for device manufacturers competing on specification compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Medical Thermometers Market |
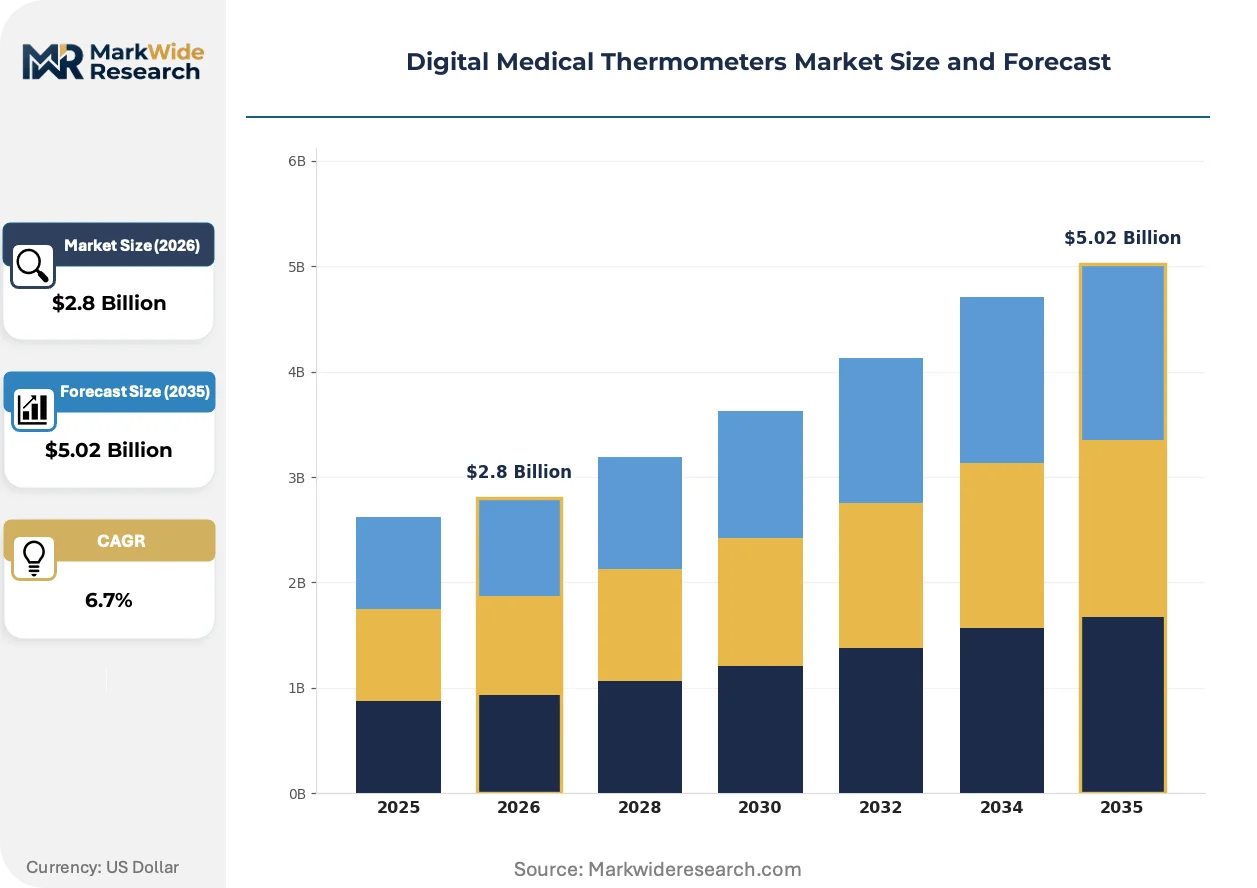
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forehead, Ear, Oral, Axillary Technology: Infrared, Thermocouple, Bimetallic, Digital End User: Hospitals, Home Care, Clinics, Laboratories Distribution Channel: Online, Retail, Pharmacy, Direct Sales |
| Companies Covered | Omron Corporation, Terumo Corporation, A&D Medical, Omega Engineering, Fairhaven Health, Teledyne FLIR, PCE Holding GmbH, RG Medical Diagnostics, Microlife Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Medical Thermometers Market Trends and Innovations
Sensor miniaturization and wireless connectivity protocols are fundamentally restructuring how temperature data flows from measurement point to clinical decision systems, dissolving boundaries between diagnostic hardware and digital health infrastructure.
Infrared thermopile arrays with MEMS fabrication are overtaking single-point infrared sensors in premium hospital thermometers, enabling spatial temperature mapping across forehead surfaces. Acute care procurement teams in the United States are specifying these multi-sensor configurations for emergency department triage workflows. This architectural shift is overtaking legacy single-detector designs and compressing price premiums for basic non-contact units.
The EU MDR's post-market surveillance requirements are mandating real-world performance tracking for clinical thermometers sold in European Economic Area member states. Manufacturers must now maintain vigilance systems documenting accuracy drift across device lifecycles. This regulatory architecture most heavily affects oral thermocouple suppliers serving home care segments where user handling variability complicates validation protocols.
Health system procurement teams are unbundling after-sales calibration services from initial device purchases, creating standalone revenue streams for manufacturers with metrology laboratory capabilities. Hospital biomedical engineering departments in Germany and France are negotiating multi-year service agreements separate from capital equipment budgets. This purchasing pattern is most pronounced in university hospital networks where ISO 17025-accredited calibration traceability is mandatory for regulatory audit compliance.
Digital Medical Thermometers Market Segmentation
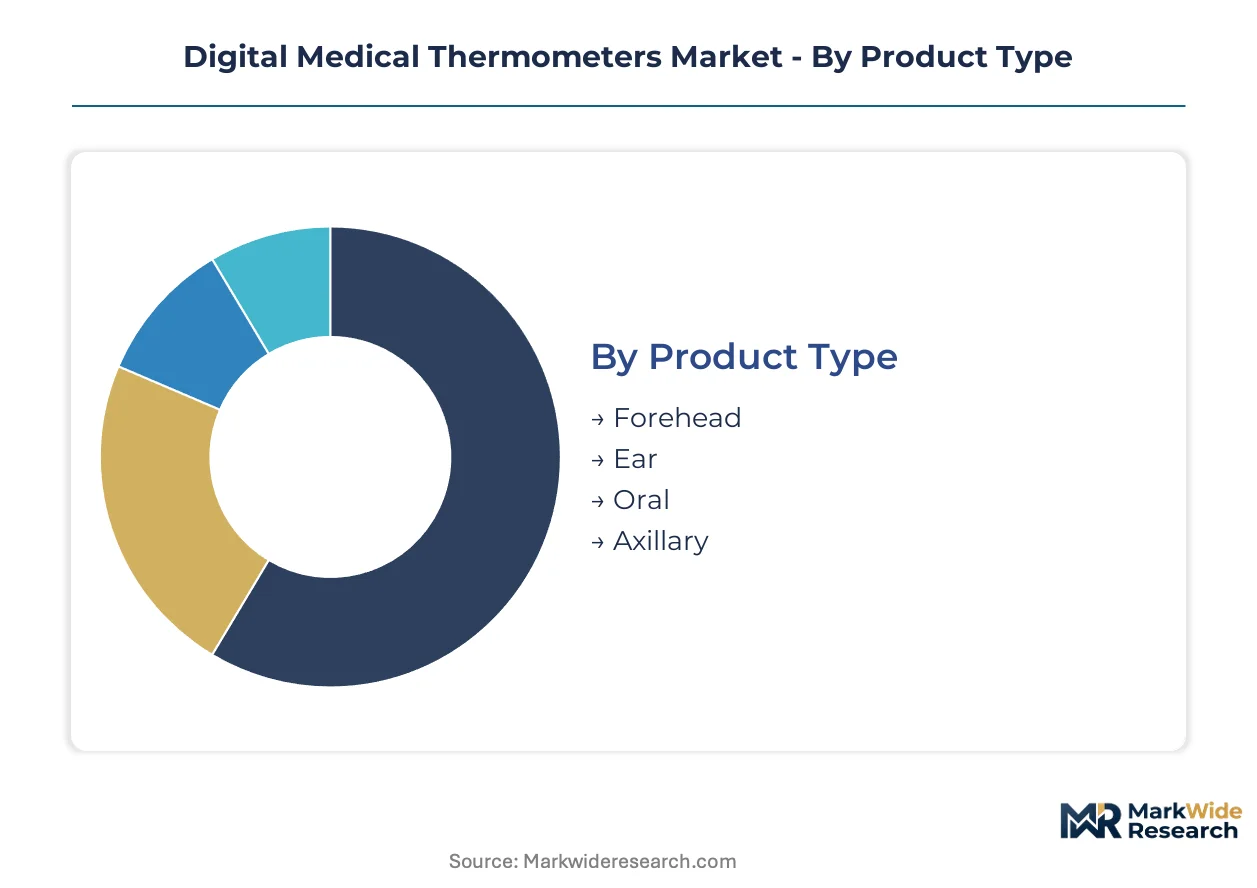
Thermometer manufacturers face divergent capital requirements across measurement modalities, with infrared sensor fabrication demanding semiconductor foundry partnerships while thermocouple assembly runs on conventional electronics lines. Segmentation strategy determines which R&D budgets flow toward FDA 510(k) clinical validation versus consumer-grade industrial design.
Product Type:
Capital intensity peaks with infrared forehead units requiring MEMS thermopile arrays and precision optical calibration, while oral thermocouple devices need minimal tooling investment.
- Forehead:Non-contact infrared sensors with thermopile arrays measure temporal artery temperature without skin contact. Hospital procurement in the United States specifies these units for emergency department triage to eliminate cross-contamination risks. Thermopile fabrication requires semiconductor foundry partnerships that concentrate supply among East Asian contract manufacturers.
- Ear:Tympanic membrane infrared sensors detect core body temperature through the ear canal with ±0.2°C accuracy. Pediatric clinics favor these devices for speed, though cerumen interference and positioning variability create accuracy challenges in home care settings where untrained users operate the equipment.
- Oral:Thermocouple or thermistor probes with waterproof housings for sublingual measurement. Low-cost disposability sustains margin strength in pharmacy retail channels serving price-sensitive households.
- Axillary:Flexible probe thermistors designed for underarm placement, common in infant care and sleep monitoring applications where patient compliance limits invasive methods.
Most installed capacity flows through Forehead. Expansion is steepest in Oral.
Technology:
Technology selection drives regulatory pathway complexity, with infrared platforms facing ISO 80601-2-56 software validation burdens that thermocouple devices largely avoid.
- Infrared:Thermopile or pyroelectric sensors detect thermal radiation emitted by skin surfaces, converting radiant energy to electrical signals. FDA 510(k) submissions for clinical-grade units require extensive accuracy validation against pulmonary artery catheter reference standards, compressing development timelines for manufacturers without predicate device portfolios.
- Thermocouple:Junction of dissimilar metals generates voltage proportional to temperature differential. Hospital-grade calibration services extend device lifecycle value for manufacturers with metrology laboratory capabilities accredited to ISO 17025 standards.
- Bimetallic:Mechanical temperature measurement using differential expansion of bonded metal strips, now largely displaced in clinical settings but persisting in low-cost consumer variants.
- Digital:Solid-state thermistor or semiconductor junction sensors with analog-to-digital conversion and LCD display. Bluetooth-enabled variants bundle with cloud-based vital tracking platforms to generate recurring revenue beyond hardware sales.
Infrared platforms command the highest unit economics. Thermocouple volumes dominate shipment counts.
End User:
End user segmentation determines pricing architecture, with health systems negotiating multi-year service agreements while home care channels compete on retail shelf placement.
- Hospitals:Acute care facilities specify clinical-grade accuracy with calibration traceability for regulatory audit compliance. German university hospital networks unbundle after-sales calibration from capital equipment purchases, creating standalone revenue streams.
- Home Care:Aging demographics in the United States expand household penetration as chronic disease management protocols prioritize preventive health tracking. Pharmacy distribution channels carry highest volume throughput for calibrated consumer devices.
- Clinics:Outpatient settings balance speed and accuracy for high-patient-volume workflows. Pediatric and family practice clinics favor ear and forehead modalities for reduced measurement time.
- Laboratories:Research and reference laboratories demand NIST-traceable calibration for epidemiological surveillance and clinical trial data integrity. Metrology-grade specifications filter out uncertified competitors.
Hospital procurement aggregates contract value. Home care channels expand volume fastest.
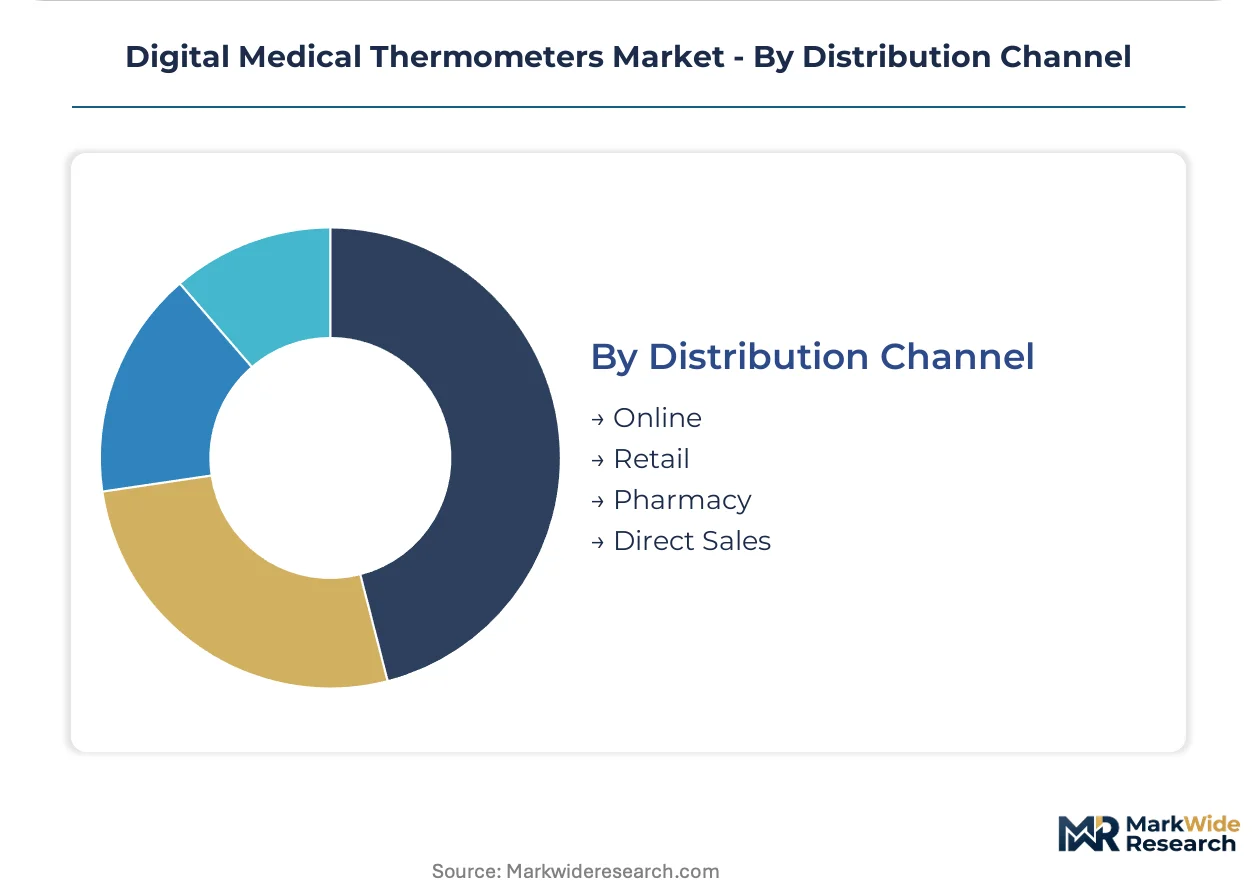
Distribution Channel:
Channel strategy shapes margin capture, with direct sales to health systems yielding superior per-unit economics against retail pharmacy throughput models.
- Online:E-commerce platforms enable direct-to-consumer reach for Bluetooth-connected devices with smartphone app integration. Subscription bundling for remote patient monitoring creates recurring revenue streams.
- Retail:Mass merchandisers and consumer electronics chains prioritize price positioning and packaging differentiation for impulse purchases. Shelf placement fees compress margins for smaller manufacturers.
- Pharmacy:Retail pharmacy networks offer clinical credibility for consumer devices with accuracy claims. Pharmacist recommendation influences brand selection for fever management purchases.
- Direct Sales:Health system procurement teams negotiate contract bundling for hospital-grade specifications. Volume aggregation extends payment cycles while compressing per-unit economics.
Pharmacy channels move the highest unit volumes. Direct sales capture the strongest margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium pricing for FDA-cleared clinical thermometers, while Germany anchors European procurement through unbundled calibration service contracts. Japan and South Korea concentrate infrared sensor fabrication, and China's manufacturing bases supply cost-optimized consumer units.
United States
Aging demographics and chronic disease management protocols drive household thermometer penetration across Medicare Advantage networks. FDA 510(k) premarket notifications filter uncertified competitors from hospital procurement channels. Minneapolis and Boston health systems negotiate multi-year calibration agreements with metrology-accredited suppliers.
Germany
University hospital networks mandate ISO 17025-accredited calibration traceability for regulatory audit compliance. EU MDR post-market surveillance requirements impose real-world performance tracking obligations on device lifecycles. Baden-Württemberg and Bavaria host biomedical engineering clusters specializing in precision temperature measurement systems.
Japan
PMDA clinical-grade approvals sustain premium positioning for hospital procurement teams. METI industrial policy supports MEMS thermopile array development through domestic semiconductor foundry partnerships. Tokyo and Osaka metropolitan areas concentrate headquarters functions for major thermometer manufacturers.
China
NMPA medical device registrations accelerate for infrared forehead units targeting hospital triage applications. GB standards for clinical thermometer safety shape design specifications across Shenzhen and Dongguan manufacturing bases. Yangtze River Delta electronics clusters supply thermistor components to global OEMs.
South Korea
MFDS certification requirements elevate domestic manufacturers above commodity competitors in regional procurement. Government health technology procurement programs prioritize connected devices with cloud integration capabilities. Seoul Capital Area hosts R&D facilities for Bluetooth-enabled vital sign monitoring platforms.
Digital Medical Thermometers Market Competitive Landscape
Top-tier vendors anchor hospital-grade specifications, while mid-tier competitors populate pharmacy retail channels with calibrated consumer devices. The vendor base stratifies across three archetypes: precision sensor fabricators with semiconductor foundry partnerships, connected health platforms bundling hardware with subscription services, and calibration service specialists extending device lifecycle value. Competitive moves concentrate on strategic partnerships for remote patient monitoring integration and geographic licensing of fever management algorithms.
Within the precision instrumentation tier, Omron Corporation and Terumo Corporation exemplify divergent strategic positioning. Omron anchors connected health platform development through Bluetooth-enabled device ecosystems. Terumo occupies a position emphasizing hospital-grade calibration services with metrology laboratory capabilities. Microlife Corporation represents the algorithm-centric archetype, specializing in consumer-facing fever management applications.
| Leading Market Players |
|---|
| Omron Corporation |
| Terumo Corporation |
| A&D Medical |
| Omega Engineering |
| Fairhaven Health |
| Teledyne FLIR |
| PCE Holding GmbH |
| RG Medical Diagnostics |
| Microlife Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor foundry partnerships anchor supply positioning for infrared thermometer manufacturers while simultaneously preserving premium pricing power against commodity competitors. Hospital procurement teams in the United States and Germany pay marked-up contract rates for devices backed by ISO 17025-accredited calibration traceability, a service layer that outsourced manufacturing models cannot replicate.
Pricing Analysis
Capacity additions in China's Yangtze River Delta electronics clusters are reshaping price floors for consumer-grade thermistor devices. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared hospital units from pharmacy retail devices and unbranded direct-import consumer goods. Cost compression in the economy tier intensifies because smartwatch temperature sensors capture low-acuity household checks. Home care channels exhibit highest price sensitivity; hospital systems demonstrate lowest sensitivity due to bundled service contracts.
Supply Chain Analysis
Dual-sourcing requirements from German university hospital networks and United States health systems mandate multi-supplier qualification for MEMS thermopile arrays and precision optical components. Manufacturing draws from China, Japan, and South Korea for sensor fabrication, with final assembly concentrated in Shenzhen and Dongguan. Thermistor input volatility and semiconductor allocation constraints constitute the primary structural risk. Distribution runs through pharmacy retail networks for consumer volumes and direct sales teams for health system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in digital medical thermometers hinges on software validation cost reduction through reusable firmware platforms and the shift toward recurring calibration service revenue. Thermopile array standardization offers a second cost-down pathway for infrared device manufacturers.
For Market Incumbents: Lock in hospital procurement relationships through multi-year ISO 17025-accredited calibration service agreements that extend device lifecycle value. Deepen backward integration into MEMS thermopile fabrication by partnering with domestic semiconductor foundries in Japan or South Korea, reducing exposure to East Asian supply concentration. Smartwatch temperature substitution threatens low-end consumer segments; defend against this through Bluetooth-enabled platform differentiation with cloud-based fever management algorithms. For New Entrants and Emerging Players: Direct-to-consumer e-commerce routes offer the lowest barrier to entry for algorithm-centric fever management applications bundled with white-label hardware. Target pharmacy retail channels in the United States where aging demographics and chronic disease protocols expand household penetration fastest. Pursue EU MDR conformity assessment as a competitive wedge against uncertified commodity competitors in European procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital procurement contract bundling compresses per-unit economics for sub-scale manufacturers lacking metrology laboratory capabilities. Long-term viability favors precision sensor fabricators with semiconductor foundry partnerships and connected health platforms generating recurring subscription revenue. Watch for inflection signals in FDA 510(k) clearance timelines, as accelerated validation capabilities separate acquirable targets from stranded assets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket clearance timelines filter uncertified competitors from hospital procurement channels. |
| Bluetooth Platform Integration | Cloud-based vital tracking from Omron generates recurring revenue beyond hardware sales. |
| ISO 17025 Calibration Service Buildout | German university hospitals unbundle after-sales services from capital equipment purchases. |
| MEMS Thermopile Foundry Partnership | Domestic semiconductor partnerships in Japan reduce supply concentration risk. |
| Fever Management Algorithm Licensing | Proprietary diagnostic software from Microlife creates white-space monetization in digital health ecosystems. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract documentation, and CMS Medicare reimbursement records — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, and regulatory affairs specialists at thermometer manufacturers. Secondary validation incorporated FDA 510(k) premarket notification filings, EU MDR conformity assessment databases, and ISO 80601-2-56 standard documentation. Bottom-up shipment modeling across product type, technology, and end-user segments was cross-checked against top-down market sizing from trade customs data and distributor channel audits.
Historical volume trajectories were cross-referenced against expert panel assessments of technology substitution risks and regulatory pathway changes. Segmentation dimensions modeled include measurement modality, sensor technology, end-user setting, and distribution channel structure. CAGRs were derived from fitted growth curves applied to unit shipment and value data across the projection horizon. Forecast inputs incorporated MEMS thermopile yield improvement assumptions and software validation cost curves for connected devices.
The model assumes a particular technology adoption path; alternative pathways for infrared thermopile arrays versus thermocouple sensors would alter the outlook if hospital cross-contamination protocols shift materially. Deviation in FDA 510(k) clearance timelines or EU MDR post-market surveillance enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurofeedback Systems Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Knee Walkers Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Cervical Fusion Market
Medical Devices
Bunion Correction Systems Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Sialendoscopes Market
Medical Devices
Europe Urinary Catheters Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Micro Balloon Catheter Market
Medical Devices
Digital Respiratory Devices Market