
 Global Hemostasis Valves Market | 2026-2036
Global Hemostasis Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemostasis Valves Market Foresight
Neurovascular interventions are repositioning hemostasis valve demand as stroke thrombectomy volumes rise across tertiary centers. Boston Scientific Corporation leverages integrated catheter platforms to bundle valve sales with guidewire and embolic protection offerings. Teleflex Incorporated anchors its position through dedicated vascular access divisions with direct hospital contracting. Merit Medical Systems competes on manufacturing scale, operating vertically integrated facilities in Utah and Ireland to control cost and delivery timelines.
Hemostasis valves are mechanical pressure-sealing devices installed on introducer sheaths, typically constructed from polycarbonate housings with silicone or elastomeric seals rated to maintain hemostasis during catheter exchanges up to 12 French sizes. Their primary commercial purpose is to minimize blood loss and air embolism risk during percutaneous interventional procedures while permitting repeated instrument passage. Rotating valve configurations lead unit shipments due to ergonomic handling preferences in cardiac catheterization labs, while diaphragm valve designs capture premium positioning for high-pressure interventions requiring superior seal integrity. Double lumen deployment formats are gaining fastest adoption as complex procedures demand simultaneous device delivery without sheath exchange.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for hemostasis valve manufacturers seeking market access. ISO 13485 quality management standards and REACH material compliance obligations further constrain supplier selection and biocompatibility testing protocols across the United States and European markets. Stakeholders must monitor evolving reimbursement thresholds for outpatient interventional procedures, as site-of-service payment differentials between hospital-based and ambulatory settings will determine catheterization volume distribution and corresponding valve consumption patterns.
Market Dynamics
Catheterization procedure volumes in aging populations are concentrating purchasing power within integrated hospital networks, forcing valve manufacturers to restructure pricing and service models around multi-year enterprise contracts rather than transactional sales.
Growth Catalysts
- Stroke thrombectomy expansion:Tertiary neurovascular centers in the United States and Germany are scaling catheter lab capacity, driving demand for double-lumen valve configurations that accommodate simultaneous device delivery during mechanical thrombectomy procedures.
- EU MDR conformity pathways:Stricter clinical evidence requirements for Class IIa medical devices are elevating barriers for marginal suppliers, consolidating procurement decisions toward established manufacturers with robust quality management systems.
- Polycarbonate-elastomer seal advances:Improved material formulations rated to 12 French compatibility are extending valve durability across high-pressure cardiac interventions, reducing per-procedure consumable costs for cath lab operators.
Market Restraints
- Silicone raw material concentration:Medical-grade elastomer supply chains cluster among specialty chemical producers in Germany and Japan, exposing valve manufacturers to input cost volatility and single-source dependency risks.
- REACH material compliance burdens:European chemical registration requirements are lengthening supplier qualification timelines and constraining material substitution flexibility for polycarbonate housing components.
- Reusable valve substitution:Some cost-sensitive hospital systems in India and Brazil are extending sterilization cycles for rotating valve configurations, compressing replacement demand for disposable units.
Strategic Opportunities
- Ambulatory surgical center penetration:United States site-of-service payment differentials are diverting low-complexity cardiac diagnostics to outpatient settings, creating demand for compact, single-use valve kits optimized for smaller procedural volumes.
- Integrated catheter platform bundling:Convergence of hemostasis valves with guidewire and embolic protection devices is enabling comprehensive procedural packages that lock in multi-product purchasing commitments.
- Japan's aging demographic infrastructure:Government investment in regional stroke care networks is expanding cath lab availability beyond Tokyo and Osaka, opening procurement channels in secondary cities.
Industry Challenges
- ISO 13485 auditor scarcity:Limited availability of qualified quality management system assessors is extending certification renewal timelines and delaying product line expansions for mid-tier manufacturers.
- Legacy sheath compatibility:Hospital systems with mixed equipment fleets require valve adapters across multiple introducer manufacturers, complicating inventory management and technical support structures.
- Biocompatibility testing bottlenecks:Cytotoxicity and sensitization protocols for new elastomer formulations are consuming 14-18 month validation windows, compressing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemostasis Valves Market |
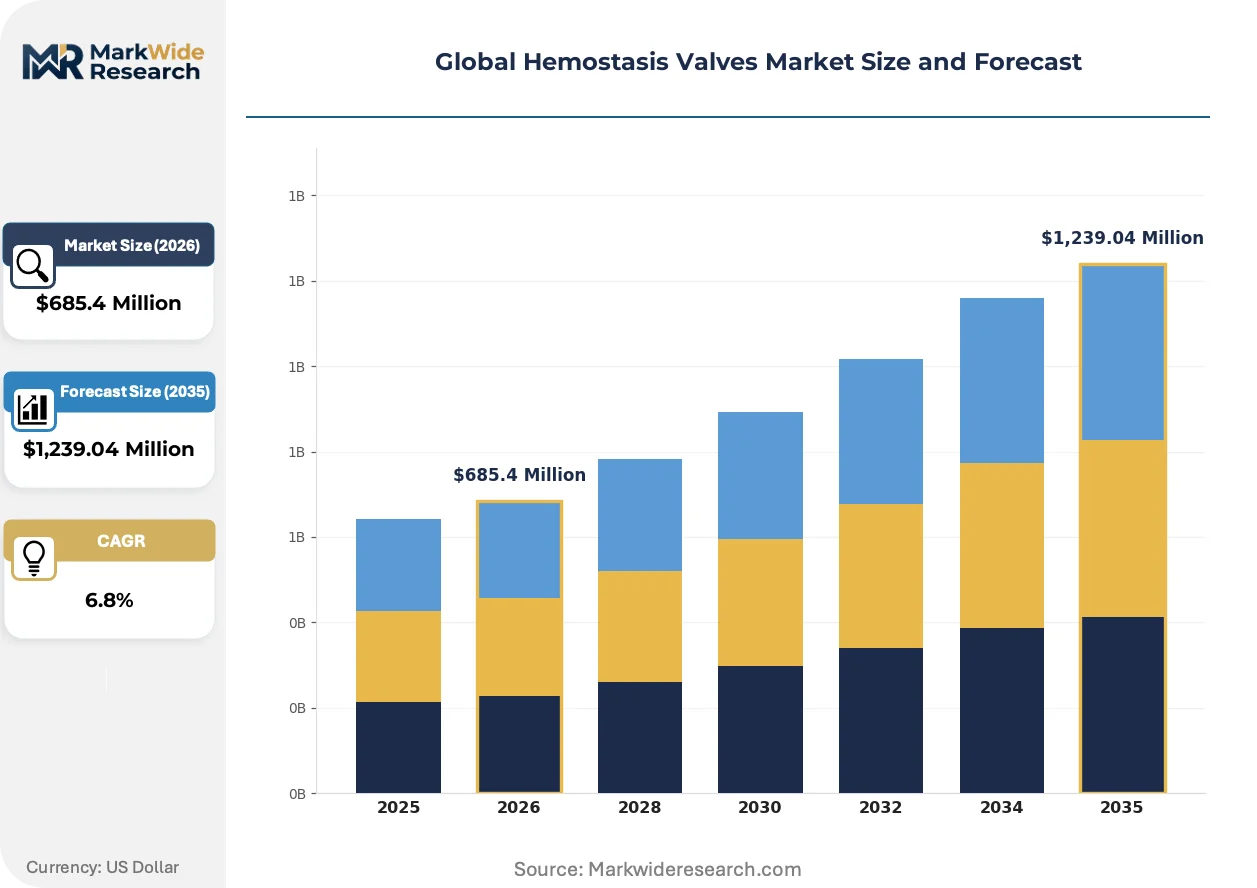
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotating Valve, Stopcock Valve, Flap Valve, Diaphragm Valve, Needle Valve, Ball Valve Application: Cardiac Procedures, Vascular Access, Neurovascular Interventions, Peripheral Surgeries, Dialysis, Interventional Radiology End User: Cardiac Centers, Vascular Clinics, Neurointervention Units, Dialysis Facilities, Surgery Centers, Radiology Departments Deployment: Single Lumen, Double Lumen, Multi Lumen, Sheath Compatible, Catheter Compatible |
| Companies Covered | Boston Scientific Corporation, Teleflex Incorporated, Merit Medical Systems, Terumo Corporation, B. Braun Melsungen AG, Abbott, Argon Medical Devices, Freudenberg Medical, Nipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemostasis Valves Market Shifts & Advancements
Device miniaturization and procedural complexity are converging to reshape valve architecture, with manufacturers racing to integrate multi-lumen functionality without compromising seal integrity under arterial pressure.
Modular valve platforms with interchangeable seal cartridges are modularizing cath lab equipment strategies, allowing United States hospital systems to standardize housing interfaces while swapping diaphragm or rotating elements based on procedure type. Cardiac catheterization departments at academic medical centers are piloting these configurations to reduce SKU proliferation. This modularization is compressing supplier consolidation timelines as facilities demand interoperable subcomponents from fewer vendor relationships.
EU MDR recertification deadlines are forcing systematic clinical evidence regeneration for legacy valve products, with notified bodies in Germany and Ireland imposing extended audit durations for technical documentation review. Manufacturers with pre-2021 CE markings face portfolio triage decisions. High-pressure interventional segments requiring superior seal integrity are absorbing disproportionate compliance investment, reshaping R&D allocation toward premium diaphragm configurations.
Hospital procurement departments are consolidating interventional cardiology purchasing through centralized value analysis committees, displacing individual physician preference item selection with standardized enterprise contracts. United States integrated delivery networks are leading this transition, leveraging volume commitments to extract service bundling concessions. This concentration is most visible in multi-hospital systems across Texas and Florida, where catheterization procedure scale supports dedicated supply chain negotiation teams.
Global Hemostasis Valves Market Segmentation
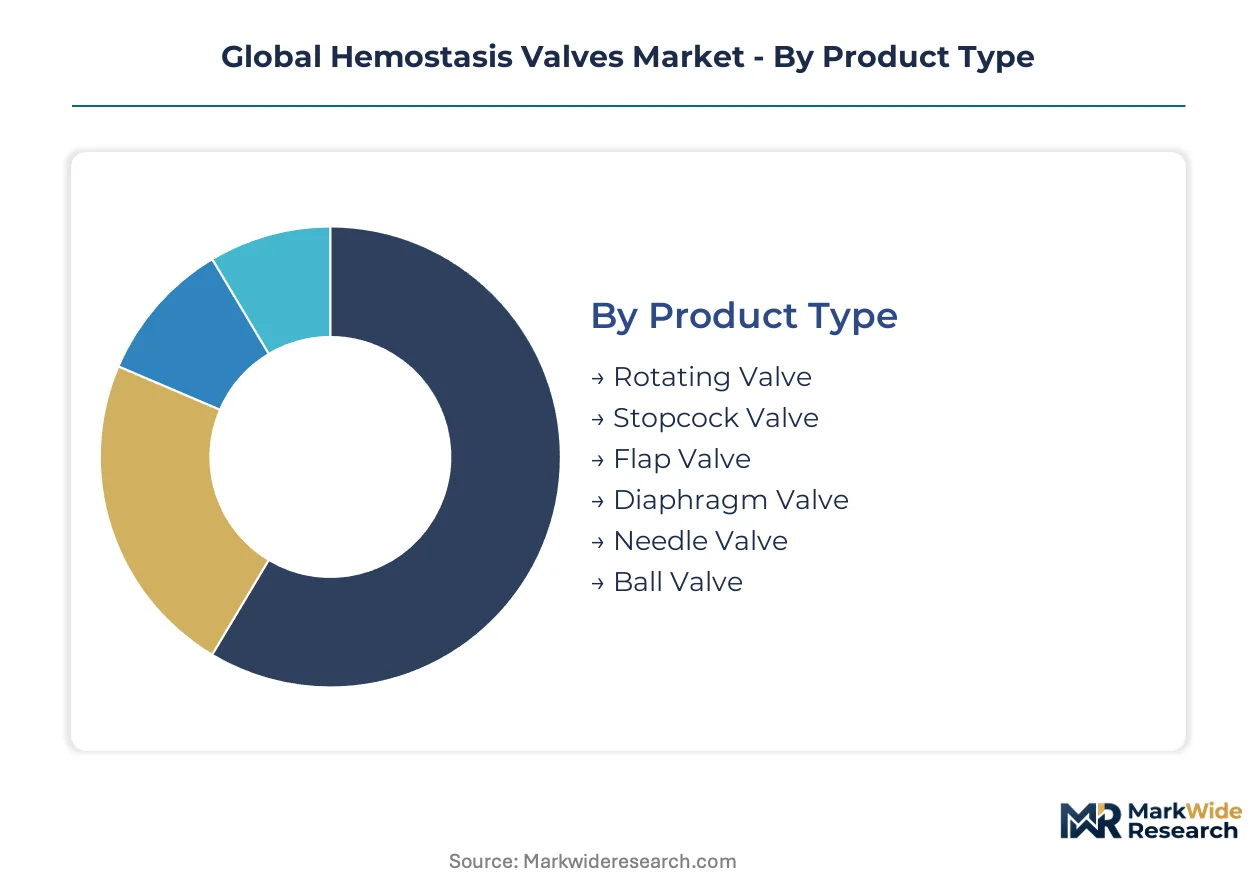
Hemostasis valve procurement varies sharply across clinical settings, with product architecture and deployment format decisions driven by procedural complexity, arterial pressure requirements, and catheter exchange frequency. Manufacturers must align R&D investment and inventory positioning with these divergent technical specifications.
Product Type:
Capital intensity concentrates in rotating and diaphragm valve configurations, where precision-molded polycarbonate housings and medical-grade elastomer seals demand dedicated injection molding infrastructure and cleanroom assembly capacity.
- Rotating Valve:These configurations employ a rotating seal mechanism that permits 360-degree catheter manipulation while maintaining hemostasis, constructed from polycarbonate bodies with silicone compression seals rated to 12 French compatibility. Demand clusters in United States cardiac catheterization labs where ergonomic handling preferences prioritize single-handed operation during rapid catheter exchanges.
- Diaphragm Valve:Thin elastomeric membranes provide superior seal integrity under high arterial pressures, utilizing fluoropolymer-coated silicone diaphragms that deform around catheter shafts without friction-induced trauma. German and Japanese tertiary centers specify these for neurovascular interventions where air embolism prevention is critical.
- Stopcock Valve:Simple lever-actuated flow control for low-pressure diagnostic applications.
- Flap Valve:One-way elastomeric flaps for basic hemostasis in peripheral access procedures.
- Needle Valve:Precision-threaded compression for micro-catheter compatibility in interventional radiology.
- Ball Valve:Spherical occluders for high-flow dialysis circuit applications.
Rotating valves absorb the bulk of installed capacity; double-lumen configurations are expanding most quickly as complex procedures demand simultaneous device delivery.
Application:
Procedure volume distribution determines manufacturing scale economics, with cardiac and neurovascular applications commanding dedicated production lines due to stringent biocompatibility and pressure-rating requirements.
- Cardiac Procedures:Percutaneous coronary intervention and electrophysiology studies require valves rated for repeated catheter exchanges under systemic arterial pressure, typically 8-12 French compatibility with rotating seal architectures. United States integrated delivery networks concentrate procurement through multi-year enterprise contracts covering high-volume cath lab operations.
- Neurovascular Interventions:Mechanical thrombectomy and aneurysm coiling demand double-lumen valves that accommodate simultaneous microcatheter and guidewire passage without sheath exchange. Tertiary stroke centers in Germany and the United States are scaling dedicated neurointerventional suites, driving specification for diaphragm-type seals with sub-atmospheric air entrainment prevention.
- Vascular Access:Central line placement and peripheral arterial access utilize standard rotating configurations.
- Peripheral Surgeries:Endovascular aortic repair and peripheral angioplasty employ sheath-compatible valves.
- Dialysis:High-flow venous access maintenance requires large-bore stopcock and ball valve formats.
- Interventional Radiology:Transarterial chemoembolization and biopsy procedures use needle valve micro-catheter interfaces.
Cardiac applications dominate current manufacturing throughput; neurovascular interventions are climbing the fastest as stroke care network expansion accelerates catheter lab deployment.
End User:
Customer concentration patterns shape sales force deployment and service bundling strategies, with cardiac centers and neurointervention units representing distinct purchasing behaviors and technical support requirements.
- Cardiac Centers:High-volume catheterization labs in United States academic medical centers and German university hospitals standardize on rotating valve platforms with enterprise pricing agreements. These facilities demand 24-hour technical support and consignment inventory arrangements due to emergency procedure scheduling.
- Neurointervention Units:Tertiary stroke centers in Japan's regional care networks and United States comprehensive stroke centers specify premium diaphragm configurations with double-lumen capability. Procurement decisions integrate with mechanical thrombectomy device vendor relationships, favoring bundled catheter-platform offerings.
- Vascular Clinics:Office-based peripheral intervention practices prioritize cost-optimized rotating valve formats.
- Dialysis Facilities:Freestanding centers require high-durability stopcock valves for arteriovenous access maintenance.
- Surgery Centers:United States ambulatory surgical centers seek compact single-use valve kits for low-complexity diagnostic procedures.
- Radiology Departments:Hospital-based interventional radiology services utilize needle valve configurations for biopsy and drainage applications.
Cardiac centers command the largest share of valve procurement volume; neurointervention units are gaining share fastest as regional stroke infrastructure expands beyond major metropolitan areas.
Deployment:
Physical interface specifications determine compatibility requirements and inventory complexity, with lumen configuration representing the primary technical differentiation in contemporary product development.
- Double Lumen:Parallel catheter channels enable simultaneous guidewire and device delivery without sheath exchange, constructed with bifurcated seal architectures that maintain independent hemostasis for each lumen. United States and German neurovascular centers are standardizing these for mechanical thrombectomy procedures where time-to-recanalization drives clinical outcomes.
- Single Lumen:Standard rotating or diaphragm seals for sequential catheter passage dominate procurement volume due to lower unit cost and broader sheath compatibility. These configurations serve the bulk of diagnostic cardiac catheterization and peripheral vascular procedures across established cath lab infrastructure in Japan and the United States.
- Multi Lumen:Three or more channels for complex endovascular reconstruction procedures.
- Sheath Compatible:Universal taper interfaces accommodating multiple introducer manufacturers.
- Catheter Compatible:Integrated designs for specific catheter platform ecosystems.
Single lumen deployments retain the greatest installed base; double lumen configurations are expanding most quickly as procedure complexity increases and simultaneous device delivery becomes standard of care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Ireland and Singapore concentrate medical device manufacturing, drawing polymer compounders and cleanroom assemblers into tax-advantaged production clusters. These zones accelerate hemostasis valve supply chain integration across three continents.
United States
Integrated delivery networks in Texas and Florida consolidate catheterization purchasing through dedicated supply chain negotiation teams. FDA 510(k) clearance pathways shape product development timelines for Class IIa devices. Boston and Minneapolis anchor neurovascular R&D clusters where mechanical thrombectomy device vendors bundle valve offerings.
Germany
Tertiary stroke centers in Bavaria and North Rhine-Westphalia scale dedicated neurointerventional suites with double-lumen valve specifications. EU MDR conformity assessments through notified bodies in Berlin and TÜV SÜD impose extended audit durations for technical documentation. Freudenberg Medical exemplifies the industrial concentration around Stuttgart's precision polymer cluster.
Japan
Regional stroke care networks expand cath lab availability beyond Tokyo and Osaka into secondary cities. PMDA marketing authorization requirements align with ISO 13485 quality management standards for silicone seal biocompatibility. Terumo Corporation anchors domestic manufacturing in Kanagawa Prefecture with integrated catheter platform production.
Ireland
Merit Medical Systems operates vertically integrated facilities in Galway to control cost and delivery timelines for European distribution. IDA Ireland tax incentives attract medical-grade elastomer compounders to Shannon Free Zone. Dublin's notified body presence accelerates CE marking for Class IIa devices serving EU markets.
India
Cost-sensitive hospital systems in Maharashtra and Karnataka extend sterilization cycles for rotating valve configurations. CDSCO medical device rules impose import licensing requirements on polycarbonate housing components. Chennai and Hyderabad emerge as cath lab equipment refurbishment hubs serving Southeast Asian secondary markets.
Global Hemostasis Valves Market Competitive Landscape
Top-tier vendors anchor integrated catheter platforms, while mid-scale specialists compete on manufacturing scale and regional distribution density. The vendor base stratifies across three tiers: multinational device conglomerates with bundled offerings, dedicated vascular access divisions with direct hospital contracting, and regional fabricators serving price-sensitive procurement committees. Strategic archetypes include platform bundlers, vertical integrators, and compliance-focused premium specialists. M&A activity concentrates catheter-platform convergence, while capacity expansion targets Ireland and Singapore free trade zones.
Among US-based multinationals, Boston Scientific Corporation and Abbott exemplify platform bundlers that lock in multi-product purchasing commitments through integrated guidewire and embolic protection offerings. Teleflex Incorporated occupies a position within the dedicated vascular access tier, anchoring hospital contracting relationships through specialized sales divisions. Merit Medical Systems represents the vertical integration archetype, with Irish and Utah facilities enabling cost control across polycarbonate molding and elastomer seal assembly.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Merit Medical Systems |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Abbott |
| Argon Medical Devices |
| Freudenberg Medical |
| Nipro |
| Others |
Supply & Pricing Matrix
Hospital procurement consolidation through United States integrated delivery networks is forcing valve manufacturers to absorb service bundling costs and extend payment terms, compressing margins and accelerating supplier exit from mid-tier contract tiers. This demand-side restructuring compels polycarbonate molding specialists to consolidate capacity in Ireland and Singapore free trade zones where tax advantages offset pricing concessions.
Pricing Analysis
Short lead-time premiums command substantial markups as United States cardiac centers demand 24-hour emergency inventory availability for mechanical thrombectomy procedures. Three-tier pricing structure across premium diaphragm, standard rotating, and economy stopcock configurations reflects ISO 13485 certification grade and after-sales technical support bundling. Cost compression in economy tiers is intensifying because Indian hospital systems extend sterilization cycles for reusable rotating configurations. Ambulatory surgical centers exhibit highest price sensitivity due to site-of-service payment differentials, while German tertiary stroke centers show lowest sensitivity given bundled catheter-platform procurement.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty chemical producers for medical-grade silicone elastomer formulations used in diaphragm seal assemblies. Manufacturing capacity concentrates in Ireland, Singapore, and Utah where cleanroom assembly infrastructure supports polycarbonate housing production. Raw material dependencies include polycarbonate resin, fluoropolymer coatings, and platinum-cured silicone compounds. Tariff exposure on Chinese-molded housing components threatens cost structures for European distribution. Distribution runs through direct hospital contracting with consignment inventory arrangements dominating high-volume cardiac center relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a consolidation play where EU MDR recertification burdens and biocompatibility testing bottlenecks are systematically eliminating marginal suppliers lacking robust quality management infrastructure.
For Market Incumbents: Hedge against silicone raw material volatility through captive supply arrangements or long-term offtake agreements with Freudenberg Medical and Japanese specialty compounders. Consolidate manufacturing footprint in Ireland's Shannon Free Zone to exploit IDA Ireland tax incentives while defending against reusable valve substitution in emerging markets through premium single-use bundling with mechanical thrombectomy platforms. For New Entrants and Emerging Players: The price-point gap between premium diaphragm valves specified for neurovascular interventions and economy rotating configurations in Indian cost-sensitive hospital systems offers white-space entry. Target secondary Japanese cities where regional stroke care network expansion outpaces incumbent service coverage. Pursue modular valve platform strategies with interchangeable seal cartridges to reduce SKU proliferation for academic medical center procurement committees. For Investors and Strategic Acquirers: The window for entry favors mid-scale manufacturers with established ISO 13485 certification and CE marking pathways already navigated. Long-term viability hinges on catheter-platform convergence enabling multi-product purchasing commitments. Watch FDA 510(k) clearance velocity for double-lumen configurations as the inflection indicator for neurovascular market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification deadlines force portfolio triage toward high-pressure diaphragm configurations with superior seal integrity. |
| Hospital System Partnership | Texas and Florida integrated delivery networks leverage volume commitments to extract service bundling concessions from valve manufacturers. |
| Backward Integration | Merit Medical Systems controls polycarbonate molding and elastomer seal assembly through Irish and Utah captive facilities. |
| Software Companion Development | Modular valve platforms with interchangeable seal cartridges reduce SKU proliferation for United States academic medical centers. |
| Reimbursement Strategy | Site-of-service payment differentials between hospital-based and ambulatory settings determine catheterization volume distribution. |
Research Methodology
FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases formed the secondary backbone, validated through primary interviews with cath lab directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads. Bottom-up and top-down triangulation cross-referenced polycarbonate resin trade flows with installed cath lab capacity across United States, German, and Japanese tertiary centers.
Bottom-up modeling segmented volume by product architecture, deployment format, and end-user concentration, while top-down approaches anchored aggregate demand to stroke thrombectomy procedure expansion and cardiac catheterization lab deployment across the analysis window. CAGRs derived from procedure volume elasticity to aging demographic penetration and reimbursement threshold adjustments. Industry-specific inputs incorporated REACH material compliance timelines and ISO 13485 auditor availability constraints.
Inputs from notified body audit schedules and silicone elastomer producer capacity announcements were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around enterprise contract pricing assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Transport Chairs Market
Medical Devices
Asia-Pacific Radiotherapy Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Global Heart Valve Devices Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
C-Arms Devices Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Lactate Meter Market
Medical Devices
Global Antimicrobial Coatings for Medical Devices Market