
 Indonesia Devices Market | 2026-2036
Indonesia Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Devices Market Insights
Project finance and leasing arrangements for enterprise device fleets is rewriting competitive access in Indonesia. Samsung Electronics leverages its in-house semiconductor supply chain to sustain pricing flexibility on bulk government orders. Xiaomi Inc anchors its position through localized assembly partnerships that satisfy domestic content thresholds. Lenovo Group Limited competes on commercial laptop configurations tailored to Indonesian banking compliance requirements.
Indonesia Devices encompass electronic hardware systems incorporating microprocessors, memory modules, wireless chipsets, and lithium-based power cells, manufactured through surface-mount technology and final assembly processes, serving communication, computation, and data-transmission functions for consumer and institutional users. Smartphones dominate volume flows while laptops capture the largest margin pool among enterprise buyers. Wearables represent the fastest-growing product type as health-tracking applications expand beyond consumer segments into corporate wellness programs. 5G-enabled devices are displacing 4G inventory across distribution channels even where network coverage remains partial.
BIS-equivalent standards enforced by Indonesia's national standardization agency, Ministry of Industry local content regulations, and Ministry of Communication and Informatics equipment certification protocols collectively determine market access and procurement eligibility for both domestic and imported devices. Compliance costs favor manufacturers with established Indonesian assembly operations over pure importers. Stakeholders must monitor spectrum allocation decisions and local content threshold adjustments as these will determine which technology tiers and supplier configurations remain viable in public-sector tenders.
Market Dynamics
Enterprise fleet digitization across Indonesian banking and logistics is compressing refresh cycles while Ministry of Industry local content rules reconfigure supplier qualification thresholds for government tenders.
Growth Catalysts
- TKDN Certification Mandates:Ministry of Industry local content requirements are steering public procurement toward domestically assembled devices, expanding qualified supplier pools for Indonesian manufacturers with in-country assembly operations.
- Smart-City Infrastructure Rollouts:Greater Jakarta and Surabaya municipal deployments of connected surveillance, traffic management, and public WiFi systems are absorbing premium device volumes across edge computing and IoT endpoints.
- 5G Spectrum Allocation:Ministry of Communication and Informatics spectrum releases are accelerating enterprise migration to 5G-enabled mobile computing equipment ahead of network coverage completion.
Market Restraints
- Lithium Supply Concentration:Battery cell sourcing dependence on East Asian suppliers exposes Indonesian device assemblers to input cost volatility and shipping disruption risks.
- BIS-Equivalent Testing Bottlenecks:Indonesia's national standardization agency certification timelines create procurement delays for imported enterprise equipment, favoring pre-certified domestic inventory.
- 4G Inventory Stranding:Channel oversupply of prior-generation smartphones and modems is compressing margins for distributors awaiting 5G network density improvements.
Strategic Opportunities
- Eastern Indonesia Penetration:Sulawesi, Maluku, and Papua provinces remain underpenetrated for enterprise mobile computing, offering first-mover positioning for logistics and resource extraction verticals.
- Health-Tracking Wearables:Corporate wellness program adoption of fitness bands and smartwatches is expanding beyond consumer segments into employee benefit platforms.
- Project Finance Structuring:Leasing arrangements for enterprise device fleets are rewriting competitive access, enabling smaller IT resellers to compete against cash-rich distributors.
Industry Challenges
- Surface-Mount Technician Scarcity:Final assembly operations in Batam and Jakarta face skilled labor shortages for precision PCB mounting and quality verification workflows.
- Multi-Agency Compliance Coordination:Parallel certification requirements across Ministry of Industry, Ministry of Communication and Informatics, and national standardization agency create documentation redundancy and timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Devices Market |
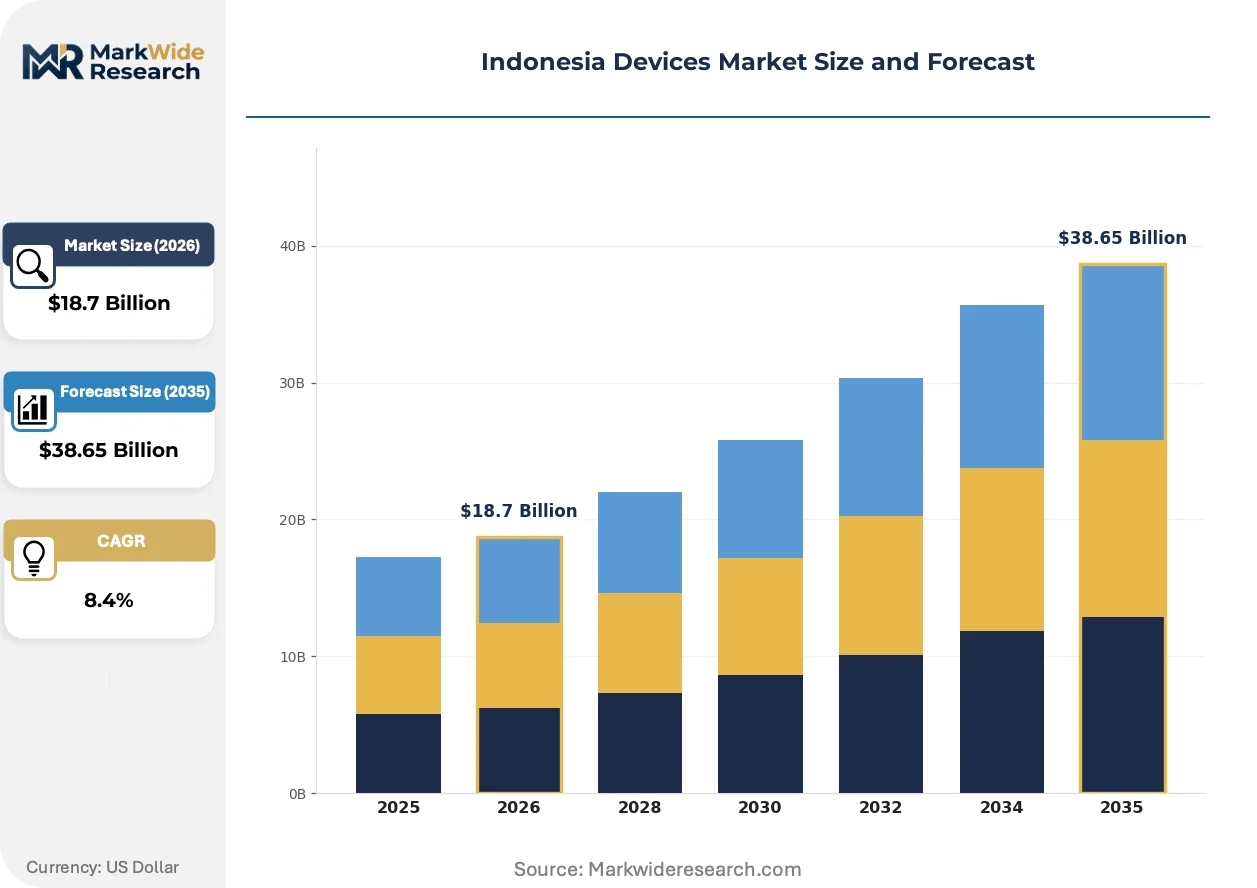
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearables End User: Consumers, Enterprises, Educational Institutions, Government Technology: 5G, GPS, NFC, Bluetooth Distribution Channel: Online Retail, Authorized Resellers, Direct Sales, Wholesalers |
| Companies Covered | Samsung Electronics, Lenovo Group Limited, Xiaomi Inc, Oppo Mobile Telecommunications Corp Ltd, Apple Inc, Vivo Inc, Dell Inc, The Hewlett-Packard Company, Realme, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Devices Market Trends and Innovations
Device architecture convergence with AI inference capabilities and modular repair standards is redefining hardware lifecycle economics across Indonesian enterprise procurement.
eSIM technology is eliminating physical SIM tray requirements and enabling remote carrier provisioning for fleet-managed devices. Indonesian banks deploying field tablets are adopting eSIM configurations to simplify logistics and reduce hardware failure points. Physical SIM distribution infrastructure is rendering obsolete for enterprise mobile computing deployments.
Ministry of Industry local content threshold adjustments are tightening TKDN calculation methodologies for imported component assemblies. Manufacturers with captive Indonesian surface-mount operations gain procurement eligibility advantages over pure final-assembly configurations. Government tender participation now requires documented domestic value-add percentages exceeding prior certification baselines.
Enterprise buyers are consolidating vendor relationships around full-lifecycle service contracts bundling hardware, MDM software, and end-of-life data destruction. Traditional transactional distribution through IT resellers is losing share to direct manufacturer partnerships with integrated financing. Banking and logistics verticals in Greater Jakarta are leading this procurement consolidation pattern.
Indonesia Devices Market Segmentation
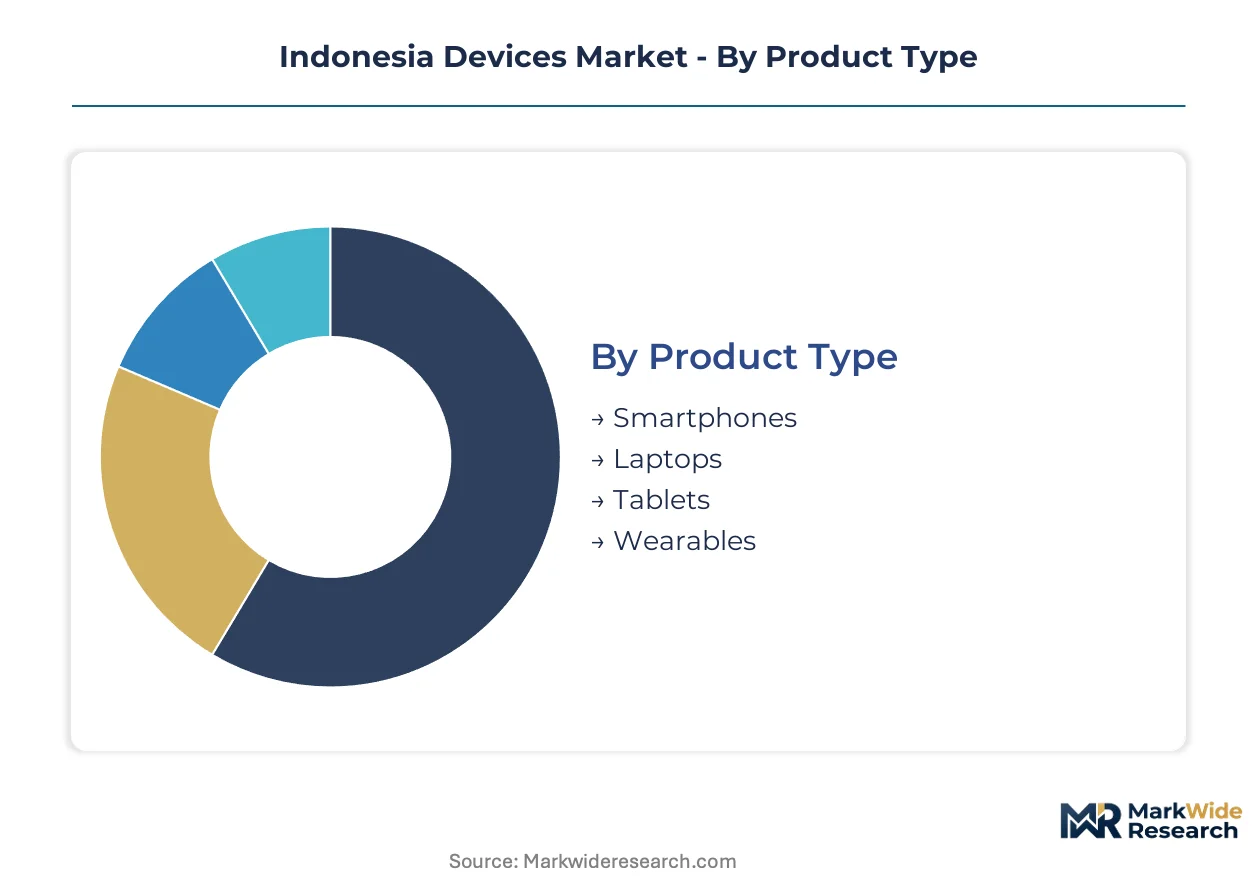
Device segmentation in Indonesia reflects divergent procurement rhythms across consumer and institutional buyers. Refresh cycles compress where digitization pressures intensify, while regulatory compliance layers reshape supplier qualification across each category.
Product Type:
Smartphones turn over fastest at 18-24 month consumer cycles, while enterprise laptops extend to 36-48 months under depreciation schedules.
- Smartphones:Handheld devices integrating cellular modems, application processors, and touch displays dominate unit shipments. Greater Jakarta and Surabaya absorb premium volumes as banking and logistics firms deploy fleet-managed devices for field operations.
- Laptops:Portable computing systems with x86 or ARM architectures capture the largest enterprise margin pool. Indonesian banks specify hardware-based encryption modules to satisfy Ministry of Communication and Informatics data security protocols for branch digitization.
- Tablets:Touchscreen devices bridging smartphone portability with laptop screen real estate serve kiosk and inventory applications.
- Wearables:Wrist-worn health and notification devices represent the fastest-growing category as corporate wellness programs expand beyond consumer segments.
Smartphones anchor the volume base while wearables gain share at the steepest rate.
End User:
Cost tiers separate high-specification enterprise procurement from price-sensitive mass-market consumption.
- Consumers:Individual purchasers drive replacement demand through retail channels, with 5G migration accelerating despite partial network coverage. Greater Jakarta households absorb premium device tiers while secondary cities prioritize value positioning.
- Enterprises:Banking and logistics verticals in Surabaya and Jakarta compress refresh cycles through project finance arrangements. TKDN certification requirements steer procurement toward domestically assembled equipment.
- Educational Institutions:School districts and universities procure bulk computing for student deployment, with Ministry of Industry local content rules influencing vendor selection.
- Government:Public-sector tenders require documented domestic value-add percentages exceeding prior certification baselines, favoring manufacturers with captive Indonesian assembly operations.
Consumers provide the demand foundation while enterprises deliver the steepest expansion trajectory.
Technology:
Application concentration varies sharply across connectivity protocols, with some technologies mandatory for specific use cases.
- 5G:Fifth-generation cellular modems enabling enhanced mobile broadband and ultra-reliable low-latency communication. Ministry of Communication and Informatics spectrum releases accelerate enterprise migration ahead of network density completion.
- GPS:Satellite positioning systems embedded in logistics fleet devices for real-time tracking across Indonesian archipelago geography.
- NFC:Near-field communication enabling contactless payment authentication, now standard in banking field tablets deployed across Greater Jakarta.
- Bluetooth:Short-range wireless protocol connecting peripherals to host devices, prevalent in wearable accessories and enterprise headset deployments.
Bluetooth saturates the installed base while 5G climbs the fastest among new device configurations.
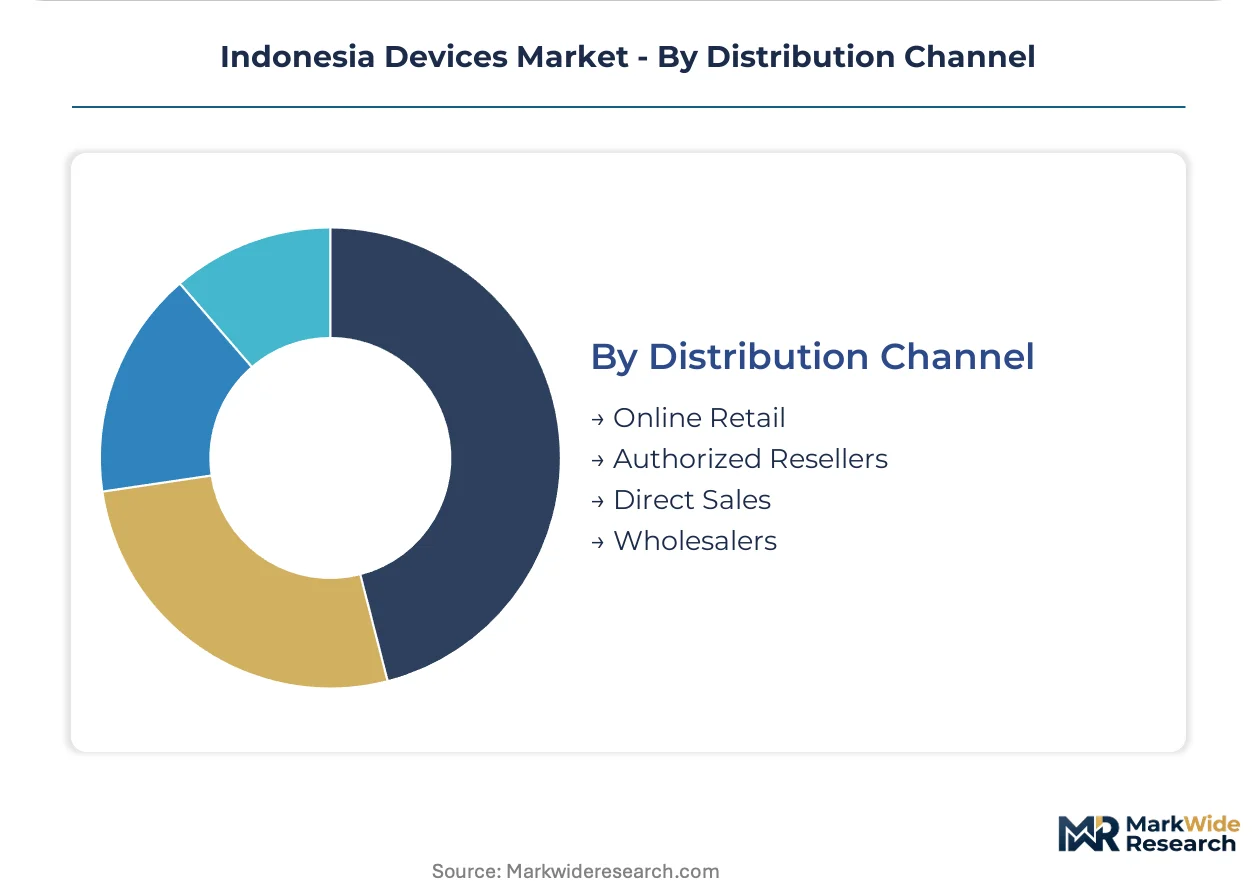
Distribution Channel:
Margin structures diverge between direct manufacturer relationships and layered intermediary networks.
- Online Retail:E-commerce platforms serving consumer replacement cycles with price transparency and delivery logistics. Marketplace operators compete on fulfillment speed across Indonesian island geography.
- Authorized Resellers:Certified distribution partners providing warranty support and local inventory for enterprise procurement. TKDN certification documentation flows through these channels for government tender participation.
- Direct Sales:Manufacturer-to-buyer relationships bundling hardware, MDM software, and end-of-life data destruction. Banking and logistics verticals in Greater Jakarta consolidate procurement through this channel.
- Wholesalers:Volume aggregators serving secondary cities and rural distribution, with 4G inventory stranding compressing margins awaiting 5G network improvements.
Authorized resellers anchor the volume base while direct sales gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ministry of Industry TKDN certification mandates are concentrating device assembly investment in Greater Jakarta and Surabaya industrial corridors. Municipal smart-city budgets in these metros are absorbing premium volumes of edge computing hardware.
Greater Jakarta
Banking sector digitization and logistics fleet modernization are compressing enterprise refresh cycles. Ministry of Communication and Informatics equipment certification protocols govern procurement eligibility for field-deployed tablets. Jakarta's Cikarang-Bekasi manufacturing belt hosts surface-mount operations serving government tender requirements.
Surabaya
East Java's logistics hub status is driving GPS-enabled mobile computing demand across shipping and warehousing verticals. Ministry of Industry local content thresholds steer procurement toward domestically assembled smartphones and laptops. The Rungkut industrial estate concentrates final assembly partnerships qualifying for TKDN documentation.
Bandung
Educational technology procurement from universities and vocational institutes sustains mid-volume computing demand. West Java provincial government bulk purchasing follows national standardization agency BIS-equivalent testing requirements. The Cimahi manufacturing zone supports component assembly operations for domestic content compliance.
Medan
North Sumatra's plantation and resource extraction sectors are adopting ruggedized mobile devices for field data collection. Regional government infrastructure budgets require documented domestic value-add percentages for connected surveillance deployments. The Belawan port corridor facilitates component import for Batam-sourced assembly integration.
Makassar
Sulawesi's underpenetrated enterprise mobile computing market offers positioning opportunities for logistics and mining verticals. Eastern Indonesia development programs include subsidized connectivity infrastructure requiring certified device endpoints. The Tanjung Bunga industrial zone is emerging as a distribution hub for archipelago-spanning fleet deployments.
Indonesia Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented distribution tiers. Samsung Electronics and Xiaomi Inc anchor volume positions through differentiated supply chain configurations. Three archetypes dominate: semiconductor-integrated manufacturers, localized assemblers, and commercial configuration specialists. Capacity expansion in Batam surface-mount facilities and strategic partnerships with Indonesian component suppliers represent the primary competitive moves.
Within the semiconductor-integrated tier, Samsung Electronics exemplifies pricing flexibility derived from captive chip supply. Xiaomi Inc occupies a position among localized assemblers satisfying TKDN thresholds through domestic partnerships. Lenovo Group Limited sits within the commercial configuration specialist archetype, tailoring laptop specifications for banking compliance requirements.
| Leading Market Players |
|---|
| Samsung Electronics |
| Lenovo Group Limited |
| Xiaomi Inc |
| Oppo Mobile Telecommunications Corp Ltd |
| Apple Inc |
| Vivo Inc |
| Dell Inc |
| The Hewlett-Packard Company |
| Realme |
| Others |
Pricing and Supply Chain Analysis
East Asian battery cell concentration feeds margin compression risks for Indonesian assemblers while TKDN certification tiers create pricing spreads that reward domestic surface-mount investment. Premium enterprise laptops with hardware encryption modules command spreads over standard consumer configurations as banking compliance requirements harden procurement specifications.
Pricing Analysis
Certification level creates the primary spread between TKDN-qualified domestic assembly and imported alternatives. Three-tier pricing structure separates government-tender premium from commercial mid-tier and retail economy segments. Cost compression in 4G inventory channels intensifies as 5G migration accelerates ahead of network density completion. Educational institutions exhibit highest price sensitivity while banking verticals prioritize compliance-grade specifications over unit cost.
Supply Chain Analysis
Export control regimes on advanced semiconductor lithography equipment constrain access to leading-edge fabrication nodes for Indonesian device assemblers. Component sourcing draws from South Korea, Taiwan, and China for memory modules and application processors. Lithium carbonate and cobalt hydroxide dependencies expose assemblers to commodity price volatility and shipping disruption through the Singapore-Jakarta corridor. Distribution runs through Batam-Jakarta industrial corridors for TKDN-compliant inventory qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia Devices Market expansion sits in early-cycle territory as 5G spectrum releases and smart-city infrastructure deployment create sustained demand tailwinds for certified enterprise equipment. TKDN threshold tightening and banking digitization programs compound procurement momentum for qualified domestic assembly operations.
For Market Incumbents: Harden TKDN certification documentation through captive surface-mount capacity expansion in Cikarang-Bekasi manufacturing belt. Deepen direct sales relationships with banking and logistics verticals to offset authorized reseller margin erosion. Threat substitution from Chinese assemblers with comparable domestic content qualifications demands pre-emptive channel control investment. For New Entrants and Emerging Players: Build out Eastern Indonesia distribution infrastructure targeting Sulawesi and Papua logistics verticals with ruggedized mobile computing configurations. Sulawesi mining and plantation sectors remain underpenetrated for fleet-managed device deployments. Go-to-market leverage rests on project finance partnerships with regional IT resellers lacking balance sheet depth for direct enterprise contracting. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier assemblers holding TKDN certifications but lacking enterprise direct sales capabilities. Long-term viability centers on 5G device refresh cycles and local content threshold durability. Watch Ministry of Industry announcements on TKDN calculation methodology revisions as inflection signal for qualification cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| TKDN Certification Investment | Captive surface-mount operations in Cikarang-Bekasi secure government tender eligibility under Ministry of Industry rules. |
| Direct Sales Channel Buildout | Manufacturer-to-banking relationships bundle hardware, MDM software, and data destruction, displacing transactional resellers. |
| Eastern Indonesia Distribution Expansion | Sulawesi and Papua logistics verticals offer first-mover positioning for fleet-managed ruggedized device deployments. |
| Project Finance Partnership Structuring | Leasing arrangements enable smaller IT resellers to compete against cash-rich distributors for enterprise refresh cycles. |
| eSIM Technology Integration | Remote carrier provisioning eliminates physical SIM logistics and reduces hardware failure points for banking field tablets. |
Research Methodology
A standing panel of device procurement managers at Indonesian banks, logistics fleet operators, Ministry of Industry certification officers, and Batam surface-mount facility engineers provided ongoing calibration. Primary interviews combined with secondary validation from Ministry of Communication and Informatics equipment certification databases, TKDN registry filings, and customs import records. Bottom-up assembly capacity assessment and top-down enterprise procurement survey data were triangulated.
Scenario-bracketing framed projections across the analysis window with sensitivity testing for TKDN threshold adjustments and 5G spectrum allocation timing. Segmentation dimensions modeled include product type, end user category, connectivity technology, and distribution channel. CAGRs derived from installed base replacement cycles and enterprise fleet digitization penetration curves. Forecast inputs incorporated smart-city infrastructure budget allocations and banking branch modernization schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese assemblers with TKDN-equivalent qualifications would shift outcomes. Material shifts in Ministry of Industry local content calculation methodologies or lithium supply chain disruption severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Brazil Aesthetic Equipment Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Venturi Mask Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Oral Appliance Market
Medical Devices
C-Arms Devices Market
Medical Devices
Intrasaccular Embolization Systems Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Global Patient-Controlled Analgesic Pumps Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Implant-Borne Prosthetics Market