
 Germany Drug Delivery Devices Market | 2026-2036
Germany Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Drug Delivery Devices Market Foresight
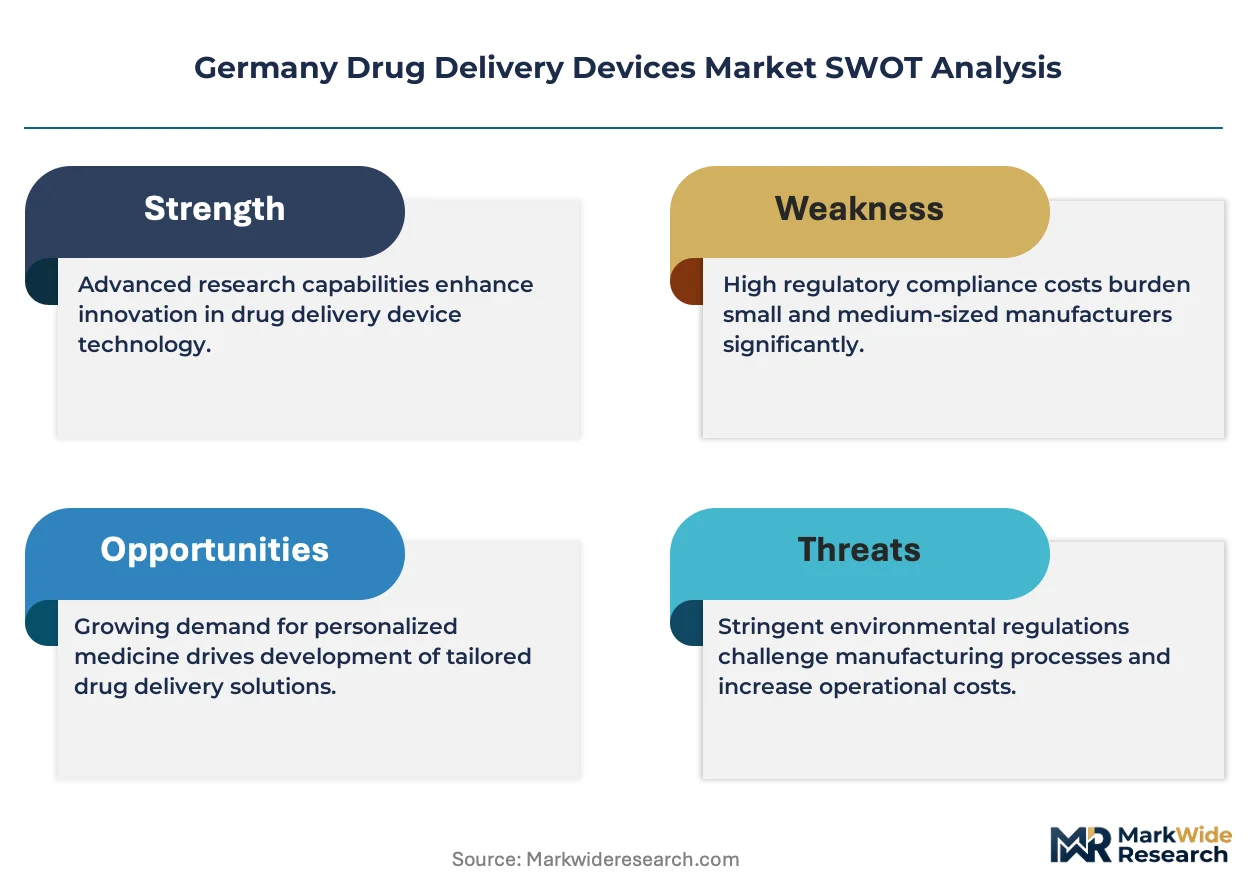
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for manufacturers seeking CE marking in Germany. Boehringer Ingelheim leverages its vertically integrated respiratory portfolio to sustain manufacturing scale across inhaler platforms. Bayer AG anchors its position through polymer science expertise that differentiates prefillable syringe systems. Novo Nordisk competes on wearable injection technology leadership, positioning its connected insulin delivery devices for reimbursement eligibility under German statutory health insurance frameworks.
Germany drug delivery devices encompass engineered systems for controlled administration of therapeutic agents, incorporating precision-machined components, biocompatible polymers, and electronic dosing controls with accuracy tolerances typically within five percent. These systems serve pharmaceutical manufacturers, healthcare institutions, and patients requiring reliable, repeatable dosing across chronic disease management. Prefilled syringes and auto-injectors dominate value capture due to biologics compatibility and reduced contamination risk, while wearable devices represent the fastest-expanding margin pool as connected dosing platforms gain reimbursement traction. Metered dose inhalers remain structurally mature, with consolidation pressure on suppliers serving respiratory applications where generic competition intensifies.
Germany's Federal Institute for Drugs and Medical Devices enforces MDR transitional provisions that extend compliance deadlines while tightening clinical evidence requirements for Class III devices. The country's national reimbursement authority, the Federal Joint Committee, determines coverage eligibility that directly shapes hospital procurement volumes and home healthcare device adoption. Stakeholders must monitor how the EU AI Act intersects with software-as-medical-device classifications for connected delivery platforms, as algorithm-enabled dosing algorithms face evolving conformity assessment pathways that will determine market access speed for next-generation systems.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing compliance timelines while elevating clinical evidence thresholds for Class III drug delivery systems, forcing manufacturers to restructure quality management systems and accelerate notified body engagements ahead of certificate expiry waves.
Growth Catalysts
- MDR Transition Provisions:Extended but tightening deadlines for CE marking renewal are concentrating demand among notified bodies, creating backlog premiums for early certifiers and accelerating consolidation among smaller device manufacturers unable to absorb audit costs.
- Prefilled Syringe Biocompatibility:Cyclic olefin polymer formulations are displacing glass for biologics storage, reducing breakage rates in cold-chain logistics and enabling larger-volume subcutaneous administration for monoclonal antibody therapies.
- Baden-Württemberg Manufacturing Clusters:Specialized contract manufacturers in Stuttgart and Mannheim anchor precision machining capabilities for auto-injector springs and needle safety mechanisms, reducing lead times for pharmaceutical OEMs.
Market Restraints
- Notified Body Capacity Bottlenecks:TÜV SÜD and DEKRA certification queues now exceed 18 months for Class III devices, freezing pipeline advancement for mid-cap manufacturers without legacy MDD certificates.
- Polymer Feedstock Concentration:Cyclic olefin copolymer resin supply concentrates among three Japanese and German chemical producers, exposing device margins to benzene derivative price volatility and force majeure allocations.
- Glass-to-Polymer Transition Friction:Extractables and leachables testing protocols for novel polymer primary containers lack harmonized standards, delaying regulatory submissions for combination products.
Strategic Opportunities
- Connected Wearable Platforms:Bluetooth-enabled patch pumps with dose capture algorithms qualify for German statutory health insurance reimbursement codes when integrated with disease management apps, opening chronic therapy segments.
- Bavaria Precision Electronics:Munich and Nuremberg sensor manufacturers are converging with Freiburg microfluidics specialists to develop closed-loop insulin delivery systems with real-time glucose feedback.
- Home Healthcare Channel Expansion:Pharmacy networks in North Rhine-Westphalia are building device training infrastructure for self-administration, capturing margin from hospital-to-home therapy transitions.
Industry Challenges
- Software-as-Medical-Device Classification:Dose calculation algorithms embedded in connected injectors trigger EU AI Act intersection assessments, requiring dual conformity pathways that extend time-to-market by 8-14 months.
- Legacy System Integration:Hospital IT departments in Saxony and Hesse report API incompatibility between next-generation connected devices and established electronic health record architectures, complicating procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Drug Delivery Devices Market |
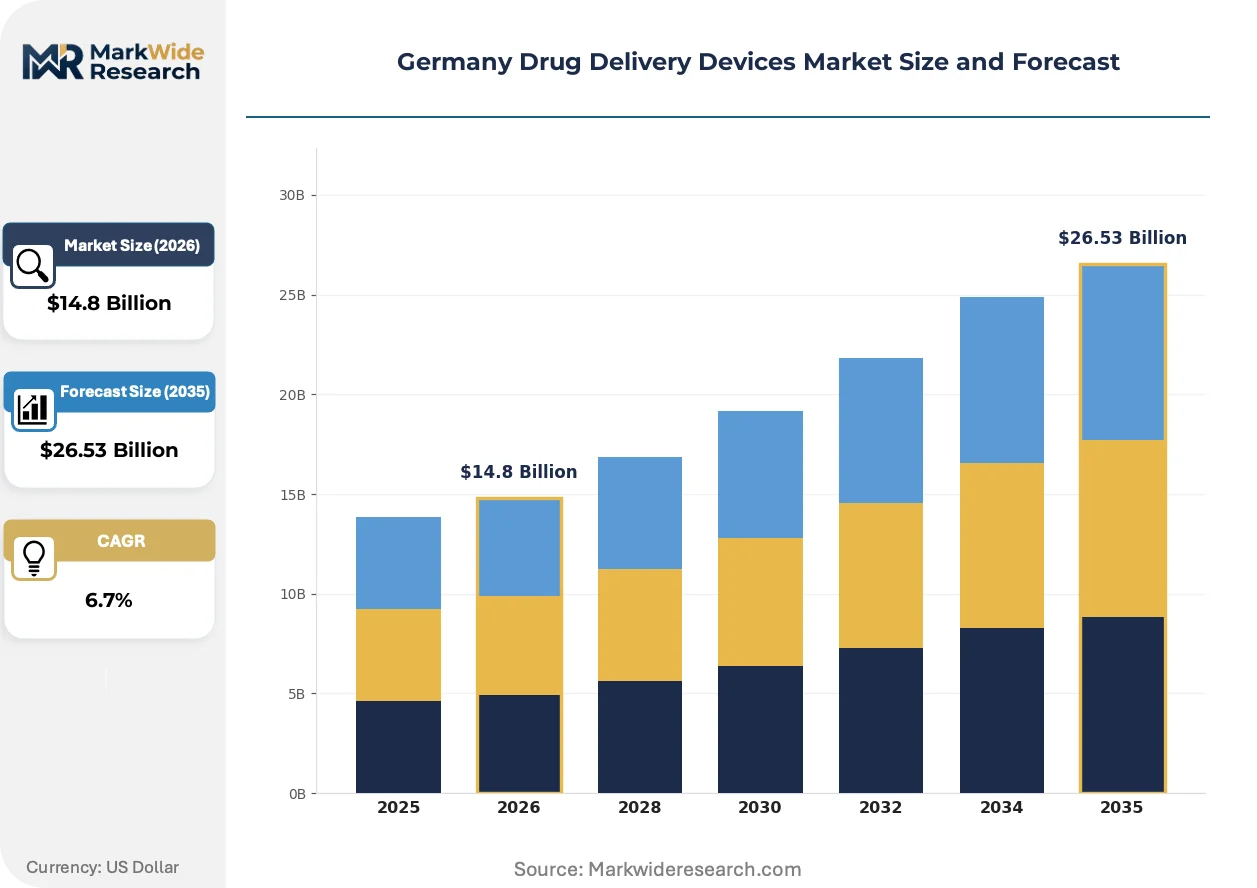
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
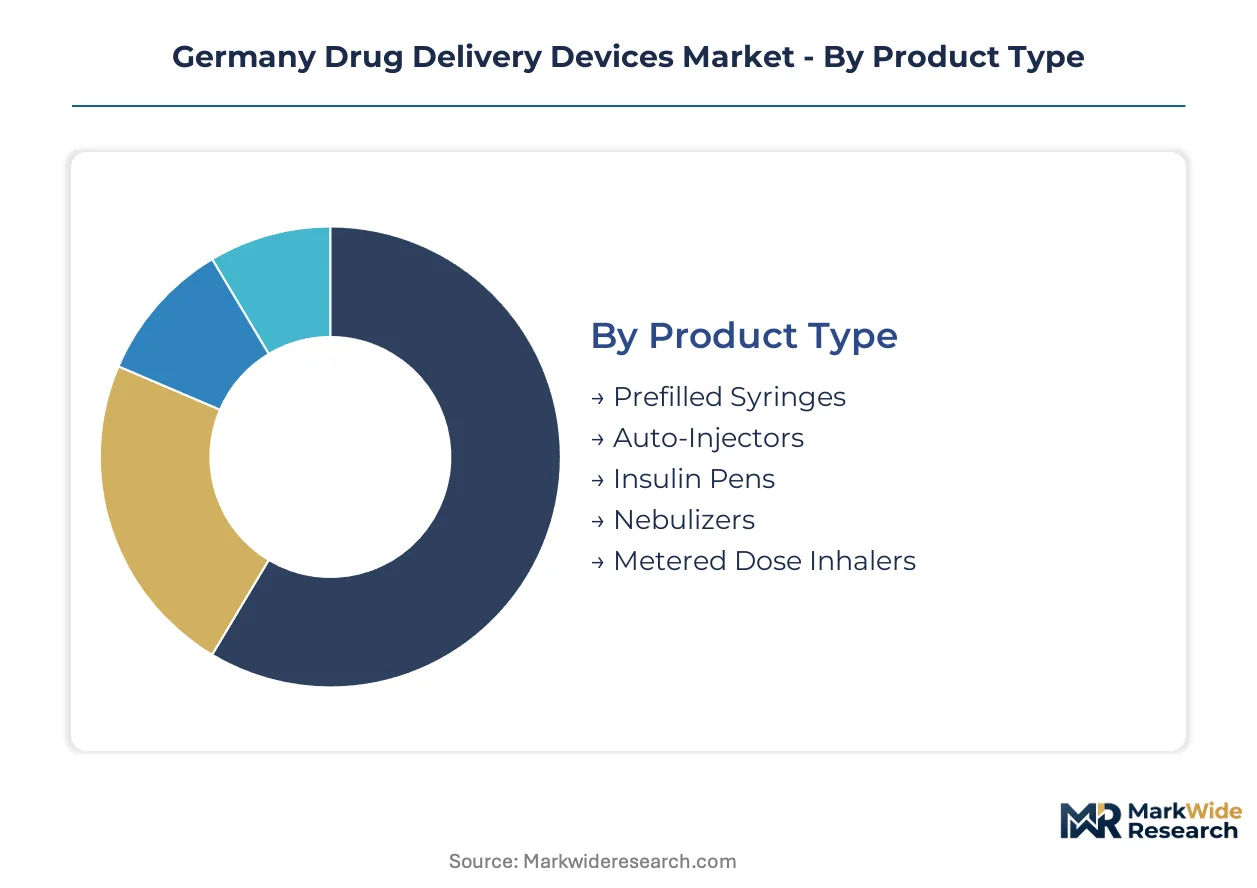
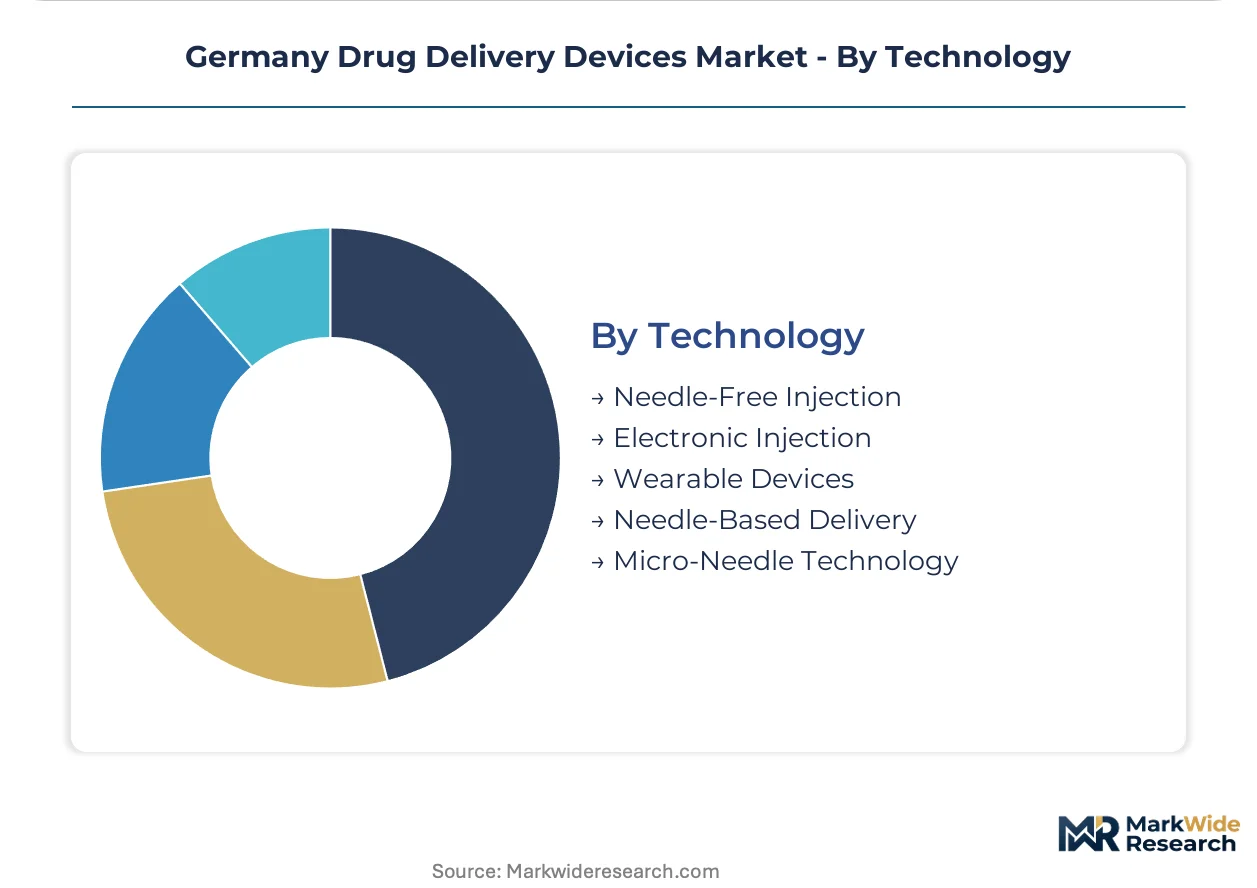
| Segmentation | Product Type: Prefilled Syringes, Auto-Injectors, Insulin Pens, Nebulizers, Metered Dose Inhalers Application: Diabetes Management, Respiratory Disorders, Oncology Treatments, Vaccine Administration, Pain Management End User: Hospitals, Specialty Clinics, Home Healthcare Providers, Ambulatory Centers, Diagnostic Laboratories Technology: Needle-Free Injection, Electronic Injection, Wearable Devices, Needle-Based Delivery, Micro-Needle Technology |
| Companies Covered | Boehringer Ingelheim, Bayer AG, Roche Holding AG, Novartis AG, Sanofi, Novo Nordisk, Becton Dickinson, Medtronic, Ypsomed, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Drug Delivery Devices Market Shifts & Advancements
Electromechanical dosing platforms are displacing purely mechanical systems across chronic disease management, while regulatory convergence between medical device and AI frameworks is rewriting conformity assessment protocols for algorithm-enabled delivery systems.
Connected auto-injectors with integrated dose verification sensors are overtaking conventional mechanical alternatives in German diabetes and multiple sclerosis therapy segments. Rheumatology clinics in Hamburg and Cologne are standardizing on Bluetooth-enabled platforms that transmit injection timestamps to physician dashboards. This connectivity layer is compressing reimbursement differentiation between device tiers, as payers increasingly condition coverage on adherence documentation capabilities.
The EU AI Act's risk classification matrix is intersecting with MDR software-as-medical-device definitions, forcing manufacturers to submit algorithm training datasets for notified body review. Dose optimization algorithms in closed-loop insulin systems now face dual conformity assessments under both frameworks. Bavarian device developers are restructuring quality management systems to accommodate this regulatory overlap, with some prioritizing simpler open-loop architectures to accelerate market access.
Hospital procurement consortia in Berlin and Munich are consolidating device purchasing through centralized tenders that bundle training and maintenance services. This aggregation is marginalizing distributors unable to deliver clinical education programs, while favoring manufacturers with dedicated field support teams. The shift is most pronounced in oncology supportive care, where complex biologics administration requires device-specific nursing certification.
Germany Drug Delivery Devices Market Segmentation
Device segmentation in Germany tracks divergent compliance burdens across MDR classification tiers and reimbursement eligibility corridors. Manufacturers optimize portfolio mix against notified body capacity constraints and Federal Joint Committee coverage decisions.
Product Type:
Supply concentration clusters around polymer primary container capabilities in Baden-Württemberg and precision spring manufacturing in Bavaria.
- Prefilled Syringes:Cyclic olefin polymer formulations reduce cold-chain breakage versus borosilicate glass. Demand concentrates in Bavaria's monoclonal antibody fill-finish facilities where extractables testing protocols remain unresolved.
- Auto-Injectors:Electromechanical platforms with dose verification sensors integrate Bluetooth connectivity for adherence documentation. Rheumatology clinics in Hamburg and Cologne standardize on these systems for biologics self-administration.
- Insulin Pens:Reusable and disposable variants serve Type 1 and Type 2 diabetes populations under statutory health insurance reimbursement.
- Nebulizers:Compressor and mesh technologies support respiratory therapy in home healthcare settings across North Rhine-Westphalia.
- Metered Dose Inhalers:Pressurized systems face generic competition pressure with consolidation among propellant suppliers.
Today's leader: Prefilled Syringes. Tomorrow's challenger: Auto-Injectors.
Application:
Cost tier differentiation separates high-complexity biologics administration from commodity vaccine delivery.
- Diabetes Management:Wearable insulin delivery systems with closed-loop glucose feedback command premium reimbursement. Munich sensor manufacturers partner with Freiburg microfluidics specialists on next-generation platforms.
- Respiratory Disorders:Inhaler and nebulizer demand tracks COPD prevalence in industrial regions of the Ruhr Valley. Boehringer Ingelheim's vertically integrated respiratory portfolio sustains manufacturing scale.
- Oncology Treatments:Prefilled syringes for supportive care biologics require device-specific nursing certification through hospital procurement consortia.
- Vaccine Administration:Standard syringe and auto-injector volumes fluctuate with immunization campaign scheduling.
- Pain Management:Patient-controlled analgesia pumps and patch systems serve post-surgical recovery in Saxony hospital networks.
Diabetes Management commands margin concentration. Oncology Treatments are climbing the fastest on biologics pipeline expansion.
End User:
Volume concentration shifts from inpatient facilities toward home healthcare channels as reimbursement favors hospital-to-home transitions.
- Hospitals:Centralized tenders in Berlin and Munich bundle device purchasing with training and maintenance services, marginalizing distributor intermediaries.
- Specialty Clinics:Rheumatology and endocrinology practices in Hamburg drive adoption of connected injection platforms for adherence monitoring.
- Home Healthcare Providers:Pharmacy networks in North Rhine-Westphalia build device training infrastructure for self-administration, capturing margin from therapy transitions.
- Ambulatory Centers:Same-day surgical facilities require rapid-turnaround injection systems for post-procedure pain protocols.
- Diagnostic Laboratories:Limited direct device demand concentrates on sample collection and pre-analytical processing tools.
Home Healthcare Providers are expanding most quickly. Hospitals retain procurement leverage through consolidated purchasing.
Technology:
Maturity gradients separate established needle-based systems from emerging electronic and micro-needle platforms facing dual MDR-AI Act conformity assessments.
- Needle-Free Injection:Jet injector systems serve vaccine campaigns and needle-phobic populations with powder and liquid formulations.
- Electronic Injection:Dose-capture algorithms trigger software-as-medical-device classification under EU AI Act intersection rules, extending time-to-market.
- Wearable Devices:Bluetooth-enabled patch pumps with disease management app integration qualify for German statutory health insurance reimbursement codes.
- Needle-Based Delivery:Conventional syringe and pen systems dominate volume through established supply chains and lowest unit economics.
- Micro-Needle Technology:Dissolving and hollow arrays enable intradermal vaccine and biologics delivery with reduced cold-chain dependence.
Needle-Based Delivery anchors current volume. Wearable Devices show steepest expansion trajectory on reimbursement tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering talent clusters in Stuttgart, Munich, and Mannheim anchor the country's drug delivery device manufacturing base. These workforce concentrations support specialized machining, polymer science, and sensor integration capabilities that pharmaceutical OEMs depend upon for component supply.
Baden-Württemberg
Auto-injector spring manufacturers and needle safety mechanism specialists concentrate in Stuttgart and Mannheim. The Federal Institute for Drugs and Medical Devices enforces MDR transitional provisions that extend compliance deadlines for Class III devices produced here. Precision machining clusters reduce lead times for pharmaceutical OEMs sourcing mechanical components.
Bavaria
Monoclonal antibody fill-finish facilities in Bavaria drive demand for cyclic olefin polymer prefilled syringes with reduced cold-chain breakage. Munich sensor manufacturers partner with Freiburg microfluidics specialists on closed-loop insulin delivery systems. The Federal Joint Committee determines reimbursement eligibility that shapes procurement volumes for connected dosing platforms developed in this region.
North Rhine-Westphalia
Pharmacy networks in North Rhine-Westphalia build device training infrastructure for self-administration of diabetes and respiratory therapies. The EU AI Act intersects with MDR software-as-medical-device classifications for connected delivery platforms deployed through this channel. Hospital-to-home therapy transitions concentrate margin capture among healthcare providers with dedicated field support teams.
Hamburg
Rheumatology clinics in Hamburg and Cologne standardize on Bluetooth-enabled auto-injectors for biologics self-administration. The EU Medical Device Regulation elevates clinical evidence thresholds for Class III systems used in these specialty practices. Adherence documentation capabilities condition payer coverage decisions, compressing reimbursement differentiation between device tiers.
Berlin-Brandenburg
Hospital procurement consortia in Berlin consolidate device purchasing through centralized tenders bundling training and maintenance services. The Federal Joint Committee coverage eligibility directly shapes procurement volumes for oncology supportive care devices requiring nursing certification. This aggregation marginalizes distributors unable to deliver clinical education programs.
Germany Drug Delivery Devices Market Competitive Landscape
The competitive structure tilts toward vertically integrated pharmaceutical conglomerates with captive device manufacturing capabilities. Boehringer Ingelheim and Bayer AG exemplify this archetype, leveraging polymer science and respiratory portfolio integration to sustain manufacturing scale. Mid-cap specialists concentrate in Baden-Württemberg precision machining and Bavaria sensor integration. Consolidation pressure intensifies as notified body capacity bottlenecks exceed eighteen months for Class III certifications. Strategic moves center on backward integration into polymer primary container production and partnerships with Freiburg microfluidics clusters.
Among Swiss and Danish device developers, Ypsomed and Novo Nordisk occupy positions within the wearable injection technology tier. Boehringer Ingelheim anchors the respiratory-integrated manufacturing archetype through its vertically structured inhaler platforms. Bayer AG exemplifies polymer science differentiation in prefillable syringe systems. These three companies represent distinct strategic postures: connectivity-focused wearable platforms, vertically integrated respiratory manufacturing, and materials science-led container innovation.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Bayer AG |
| Roche Holding AG |
| Novartis AG |
| Sanofi |
| Novo Nordisk |
| Becton Dickinson |
| Medtronic |
| Ypsomed |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap precision machinists in Baden-Württemberg anchor component supply for auto-injector springs and needle safety mechanisms, creating pricing discipline through long-term pharmaceutical OEM contracts that resist spot-market volatility. Their captive relationships with Boehringer Ingelheim and Bayer AG limit price transparency while concentrating margin capture among established tier-one suppliers.
Pricing Analysis
Bundled service contracts that wrap device supply with clinical training and maintenance support command 15-25% premiums over unbundled hardware transactions in German hospital procurement. Three-tier pricing structure across premium connected platforms, standard electromechanical devices, and economy mechanical systems tracks MDR certification burden and reimbursement eligibility under Federal Joint Committee decisions. Cost compression in the economy tier intensifies as generic inhaler competition forces propellant suppliers to absorb benzene derivative volatility. Home healthcare providers exhibit highest price sensitivity due to thin pharmacy margins, while oncology clinics demonstrate lowest sensitivity where nursing certification requirements lock in device-specific purchasing.
Supply Chain Analysis
Single-source vulnerability sits with cyclic olefin copolymer resin production concentrated among three Japanese and German chemical suppliers, exposing device margins to force majeure allocations. Precision machining draws from Baden-Württemberg and Bavaria clusters, while sensor integration rests on Munich and Freiburg electronics ecosystems. Tariff exposure on Asian-sourced microelectronics amplifies lead time uncertainty for Bluetooth-enabled wearable platforms. Distribution runs through pharmaceutical OEM direct sales forces for hospital consortia, with specialized distributors serving home healthcare channels in North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Germany drug delivery devices rests on MDR compliance cost recovery through premium-tier connected platforms and polymer-to-glass substitution reducing cold-chain logistics spend.
For Market Incumbents: Deploy backward integration into cyclic olefin polymer primary container production to secure resin allocation priority and capture margin from biologics storage innovation. Consolidate field service capabilities in Bavaria and Baden-Württemberg to defend against mid-cap specialists offering training-light alternatives. The eighteen-month notified body queue threatens pipeline advancement for competitors lacking legacy MDD certificates. For New Entrants and Emerging Players: Enter via pharmacy network partnerships in North Rhine-Westphalia, where hospital-to-home therapy transitions concentrate device training demand among regional healthcare providers. Target rheumatology clinics in Hamburg and Cologne standardizing on Bluetooth-enabled adherence platforms, as these practices seek second-source alternatives to incumbent electromechanical systems. Pursue Freiburg microfluidics collaborations to accelerate closed-loop insulin delivery development without full vertical manufacturing investment. For Investors and Strategic Acquirers: Valuations sit cheapest among precision machining specialists in Stuttgart and Mannheim lacking MDR transition capital, presenting consolidation targets for notified body certificate portfolios. Long-term viability centers on software-as-medical-device revenue streams from algorithm-enabled dosing platforms qualifying for German statutory health insurance reimbursement. Monitor EU AI Act implementation timelines as inflection indicator for connected device market access speed.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | Early notified body engagement secures certificate renewal ahead of MDR deadline waves. |
| Polymer Primary Container Backward Integration | Captive cyclic olefin copolymer supply reduces breakage risk and extractables testing delays. |
| Hospital System Partnership | Berlin and Munich consortia bundle training services that marginalize distributor intermediaries. |
| Software Companion Development | Bluetooth-enabled disease management apps trigger Federal Joint Committee reimbursement eligibility. |
| Reimbursement Strategy | Federal Joint Committee coverage decisions directly shape procurement volumes for connected dosing platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at notified bodies, biomedical engineers at Baden-Württemberg precision manufacturers, hospital purchasing committee members in Berlin and Munich, and pharmacy network operators in North Rhine-Westphalia. Secondary validation drew from BfArM MDR guidance documents, Federal Joint Committee reimbursement determinations, EU AI Act implementation texts, and customs records for cyclic olefin polymer imports. Bottom-up device shipment modeling triangulated against top-down pharmaceutical OEM procurement disclosures.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation dimensions spanning device type, application therapy area, end-user channel, and technology maturity tier. CAGRs derived from fitted growth curves incorporating MDR transition timeline assumptions, reimbursement code expansion patterns for connected platforms, and polymer feedstock price elasticity estimates. Forecast inputs included notified body capacity utilization rates and hospital consortia tender aggregation trends.
Inputs from BfArM regulatory filings and Federal Joint Committee coverage decisions were available through the study window; gaps in real-time notified body queue data introduce uncertainty bands around certification timeline assumptions. Forecasts reflect documented assumptions regarding MDR implementation pace and EU AI Act software classification interpretations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Blood Thawing System Market
Medical Devices
Spinal Fusion Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Heel and Elbow Suspension Market
Medical Devices
Stethoscope Hygiene Devices Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
Intrathecal Pumps Market