
 Medical Face Shield Market | 2026-2036
Medical Face Shield Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Face Shield Market Outlook
Aftermarket service revenue for sterilization validation and replacement visor programs is narrowing as manufacturers bundle extended-use warranties into direct sales contracts. 3M leverages its respiratory protection platform to cross-sell face shields through integrated hospital procurement contracts. Cardinal Health sustains distribution dominance through its direct-to-facility logistics network spanning acute care systems. Medline Industries anchors private-label manufacturing capacity that supplies group purchasing organizations with cost-engineered disposable options.
A medical face shield is a transparent personal protective device constructed from polycarbonate, polyethylene terephthalate, or acrylic sheet, typically mounted on an adjustable headband or frame, designed to block splashes, sprays, and respiratory droplets from contacting the facial mucous membranes of healthcare workers. The device achieves optical clarity ratings exceeding 90% light transmission while maintaining impact resistance tested to ANSI Z87.1 velocity specifications. Disposable polycarbonate shields command the largest volume share in emergency services and laboratory settings where contamination protocols mandate single-use disposal. Reusable anti-fog variants represent the fastest-expanding material-product intersection as hospitals in Germany and the United States amortize capital costs across multi-year sterilization cycles. PET-based economy shields occupy the most price-sensitive tier of clinic procurement, particularly in direct-sales channels where wholesalers compete on per-unit packaging efficiency.
FDA 510(k) clearance requirements and OSHA bloodborne pathogen standards govern product entry and workplace deployment in the United States, while the EU Medical Device Regulation (MDR) and CE marking obligations shape conformity assessment pathways for European manufacturers. The FDA's evolving guidance on fluid resistance testing pressures suppliers to validate splash protection at higher velocity thresholds, effectively raising technical barriers for new entrants. Stakeholders must monitor whether MDR notified body capacity constraints delay certification timelines for polycarbonate shield assemblies destined for EU hospital systems.
Market Dynamics
Hospital procurement departments in the United States are consolidating purchasing power through multi-year stockpile contracts for reusable anti-fog variants, compressing supplier margins while elevating technical performance requirements.
Growth Catalysts
- OSHA Bloodborne Pathogen Standards:Workplace safety mandates in the United States require splash protection for healthcare workers, creating baseline demand across acute care facilities.
- Polycarbonate Anti-Fog Coatings:Advances in hydrophilic surface treatments extend product lifecycles, enabling German university hospital networks to justify capital investment in reusable programs.
- Bundeswehr Medical Corps Coordination:Military-civilian pandemic preparedness frameworks in Germany synchronize bulk purchasing across federal and state health systems.
Market Restraints
- Petroleum-Derived Feedstock Volatility:Polycarbonate resin prices fluctuate with benzene and propylene markets, squeezing margin predictability for shield manufacturers.
- Notified Body Bottlenecks:EU MDR certification delays for polycarbonate assemblies extend time-to-revenue for European suppliers seeking CE marking.
- N95 Respirator Substitution:Tight-fitting elastomeric respirators with integrated eye protection displace standalone shields in high-aerosol procedures.
Strategic Opportunities
- India Clinic Tier Penetration:Primary health centers in rural Maharashtra and Uttar Pradesh lack standardized PPE protocols, creating first-mover advantage for PET-based economy shield suppliers.
- FDA 510(k) Pathway Streamlining:Predicate device accumulation for anti-fog variants reduces regulatory burden for follow-on submissions.
- Sterilization-As-A-Service:Third-party validation partnerships allow manufacturers to capture recurring revenue without capital-intensive in-house autoclave networks.
Industry Challenges
- ANSI Z87.1 Velocity Testing Expertise:Limited laboratory capacity for high-impact certification creates bottlenecks for new product introductions.
- Legacy Inventory Obsolescence:Pre-MDR stockpiles held by EU distributors face write-down pressure as CE-marked devices replace non-conforming units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Face Shield Market |
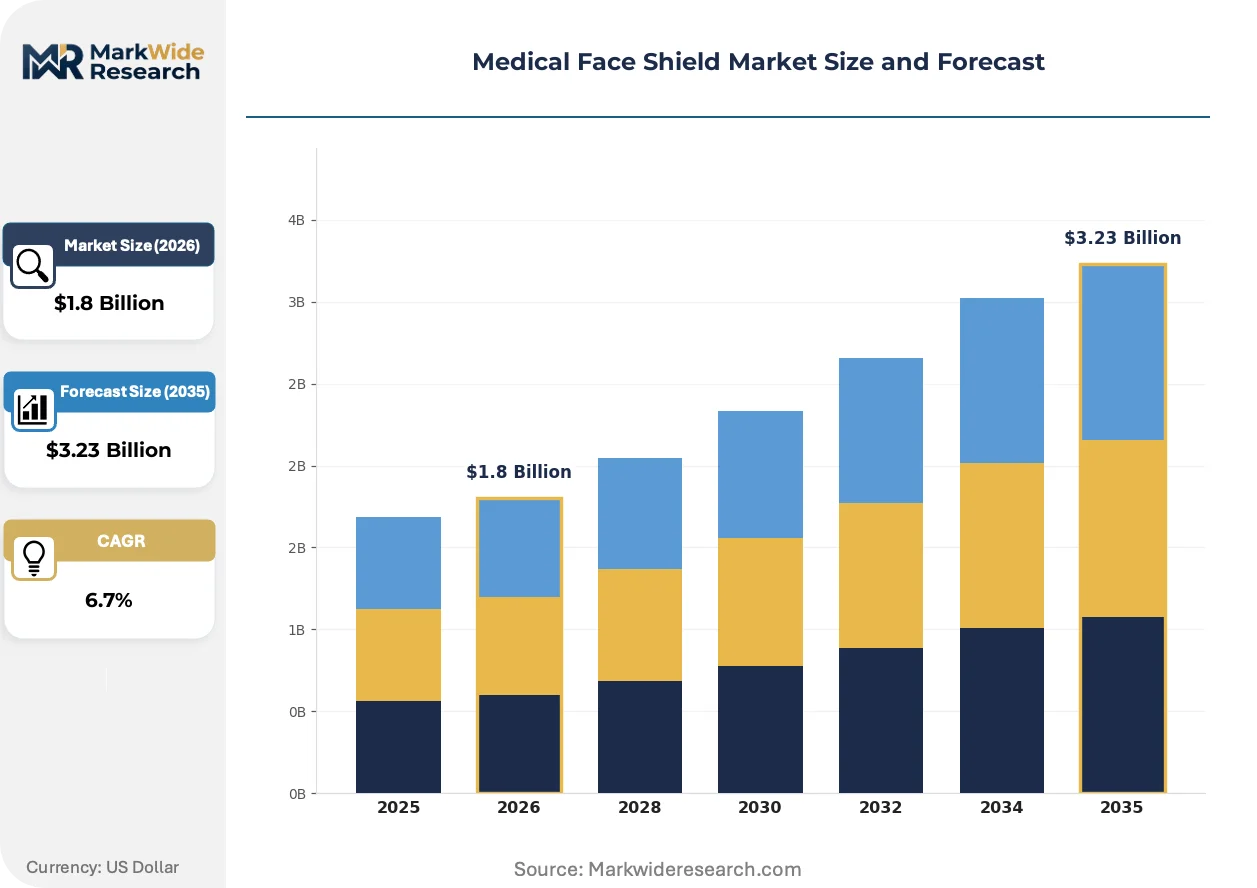
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Anti-Fog, Optical End User: Hospitals, Clinics, Emergency Services, Laboratories Material: Polycarbonate, PET, PVC, Acrylic Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | 3M, Cardinal Health, Medline Industries, MSA Safety, Honeywell International Inc., Alpha Pro Tech, Prestige Ameritech, Sanax Protective Products, Paulson Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Face Shield Market Strategic Shifts
Digital design tools and additive manufacturing are compressing product development cycles while regulatory convergence across FDA and EU MDR frameworks is elevating performance verification standards.
Anti-fog coating deposition via plasma-enhanced chemical vapor deposition is virtualizing traditional spray-application methods. German university hospital procurement teams specify vapor-deposited coatings for multi-year sterilization programs. This technology is virtualizing the aftermarket service model by embedding durability guarantees into original equipment contracts.
EU MDR Article 10 technical documentation requirements now mandate clinical evaluation reports for Class I reusable devices. German notified bodies demand biocompatibility testing per ISO 10993 for headband materials in contact with skin. Polycarbonate shield manufacturers serving EU hospital systems are restructuring quality management systems to accommodate unannounced audits.
Group purchasing organizations in the United States are unbundling after-sales sterilization validation from equipment procurement. Cardinal Health and Medline Industries now compete on per-use cost models rather than unit price. This shift concentrates contract value in logistics networks capable of reverse-flow collection and redeployment.
Medical Face Shield Market Segmentation
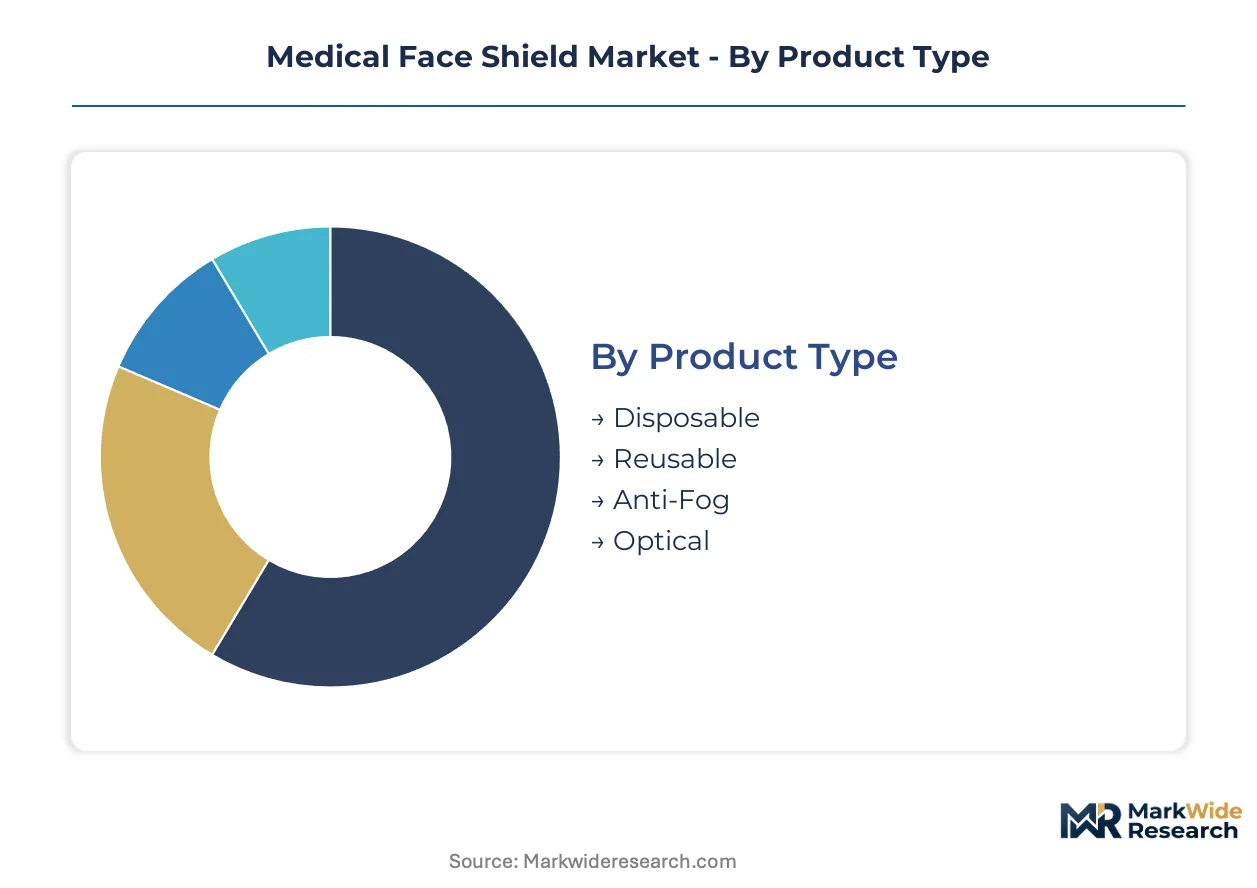
Medical face shield procurement splits across durability expectations, sterilization protocols, and optical performance requirements. Hospital systems balance infection control mandates against capital amortization cycles when selecting product configurations. Material science advances and distribution channel evolution further subdivide purchasing patterns across acute care networks.
Product Type:
Demand spans single-use emergency deployment through multi-year reusable programs with diverging total-cost-of-ownership profiles.
- Disposable:Single-use polycarbonate or PET assemblies dominate emergency services and high-turnover laboratory environments where contamination protocols prohibit reprocessing. United States hospital stockpile programs prioritize these for pandemic surge capacity.
- Reusable:Rigid frame systems with replaceable visors amortize capital investment across sterilization cycles. German university hospital networks specify these for operating theater integration.
- Anti-Fog:Hydrophilic surface treatments maintain optical clarity through temperature differentials in surgical suites. Plasma-enhanced chemical vapor deposition is virtualizing aftermarket service models by embedding durability guarantees.
- Optical:Precision-grade acrylic with distortion-corrected curvature serves microsurgery and diagnostic imaging suites where visual acuity is non-negotiable.
The dominant share belongs to Disposable, while Reusable is closing the gap fastest.
End User:
Procurement sophistication varies from centralized hospital supply chains to fragmented clinic purchasing.
- Hospitals:Integrated delivery networks negotiate multi-year contracts bundling face shields with respiratory protection platforms. OSHA bloodborne pathogen compliance creates baseline demand across acute care floors.
- Clinics:Primary health centers in price-sensitive tiers prioritize PET-based economy shields. Volume procurement through group purchasing organizations compresses per-unit margins.
- Emergency Services:Rapid-deployment protocols favor pre-packaged disposable kits with standardized sizing for field trauma response.
- Laboratories:Biosafety level containment facilities specify chemical-resistant polycarbonate with ANSI Z87.1 impact certification for splash protection.
Hospitals command the largest procurement volume, though Clinics are expanding fastest as ambulatory care networks proliferate.
Material:
Performance requirements and petroleum feedstock exposure shape material selection across end-use tiers.
- Polycarbonate:High-impact resistance and optical clarity position this resin for reusable programs and surgical applications. Benzene and propylene price volatility squeezes manufacturer margin predictability.
- PET:Lightweight economy-grade sheeting serves cost-engineered disposable programs. Recycling infrastructure limitations constrain circular economy claims.
- PVC:Flexible formulation options suit budget-constrained clinic procurement in emerging markets with less stringent optical standards.
- Acrylic:Superior light transmission properties serve optical-grade segments where distortion tolerance approaches zero.
Polycarbonate holds the installed base leadership, yet PET is gaining share fastest in volume-driven disposable channels.
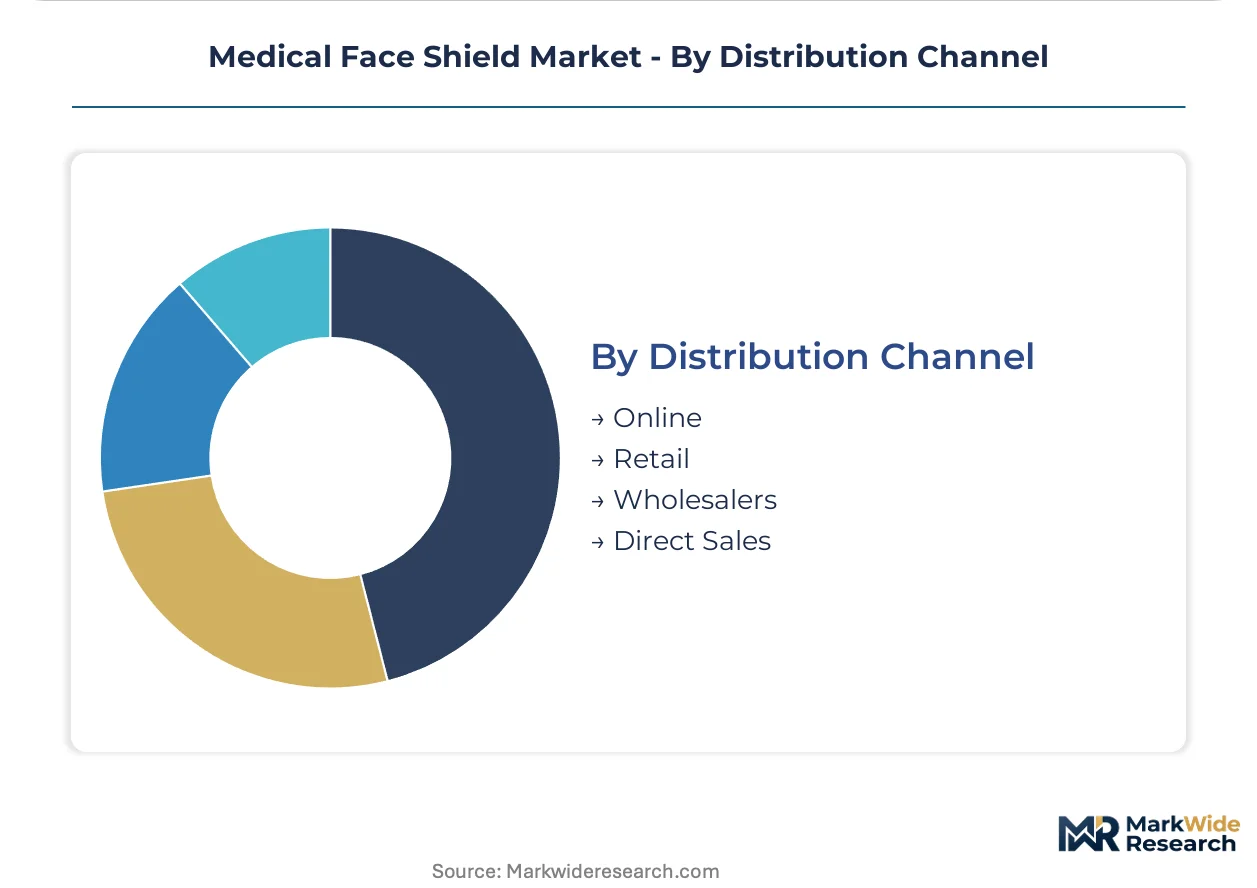
Distribution Channel:
Channel selection reflects order scale, customization requirements, and reverse-logistics needs.
- Online:E-procurement platforms serve small clinics and independent practitioners with standardized SKUs and rapid fulfillment. Limited technical specification support constrains complex orders.
- Retail:Pharmacy and medical supply storefronts capture walk-up demand from outpatient facilities and individual healthcare workers. Inventory depth challenges persist for specialty anti-fog variants.
- Wholesalers:Cardinal Health and Medline Industries leverage direct-to-facility logistics networks spanning acute care systems. Per-use cost models now dominate contract negotiations.
- Direct Sales:Manufacturers engage hospital procurement departments for customized reusable programs with embedded sterilization validation services.
Wholesalers anchor the largest contract value, while Direct Sales is climbing fastest as bundled service agreements displace transactional purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across geographies. German hospital networks absorb premium pricing for multi-year reusable programs, while Indian primary health centers drive volume through PET-based economy tiers.
United States
Hospital procurement departments consolidate purchasing through integrated delivery networks bundling face shields with respiratory protection platforms. OSHA bloodborne pathogen standards mandate splash protection across acute care floors, creating baseline demand. The Boston-Cambridge medical device cluster anchors sterilization validation service partnerships for reusable anti-fog programs.
Germany
Bundeswehr medical corps coordination synchronizes bulk purchasing across federal and state health systems for pandemic preparedness. EU MDR notified body capacity constraints extend certification timelines for polycarbonate shield assemblies destined for university hospital networks. The Rhine-Ruhr industrial corridor concentrates plasma-enhanced coating deposition facilities serving multi-year sterilization contracts.
India
Primary health centers in rural Maharashtra and Uttar Pradesh lack standardized PPE protocols, creating first-mover advantage for PET-based economy shield suppliers. CDSCO medical device regulations tighten quality benchmarks for imported polycarbonate assemblies. The Ahmedabad-Surat chemical belt feeds lightweight sheeting to cost-engineered disposable channels.
China
NMPA medical device registration requirements elevate technical documentation burdens for polycarbonate shield manufacturers targeting hospital procurement. Dual carbon goals pressure feedstock-intensive resin production, squeezing margin structures for export-oriented fabricators. The Yangtze River Delta concentration of optical-grade acrylic processors serves microsurgery equipment integration.
Japan
METI industrial standards harmonization with ISO 10993 biocompatibility protocols shapes headband material selection for reusable programs. PMDA quality management system inspections extend lead times for new market entrants. The Osaka-Kobe manufacturing hub specializes in precision-grade acrylic distortion correction for diagnostic imaging suites.
Medical Face Shield Market Competitive Environment
Diversified industrial conglomerates and specialized PPE fabricators split the market across integrated procurement platforms and focused product lines. The vendor base concentrates around three strategic archetypes: respiratory protection platforms leveraging cross-selling infrastructure, distribution-heavy logistics networks optimizing per-use cost models, and private-label manufacturers capturing group purchasing organization volume. Dominant competitive moves include backward integration into polycarbonate resin sourcing and strategic partnerships embedding sterilization validation into original equipment contracts.
Within the diversified industrial tier, 3M exemplifies platform-based cross-selling through respiratory protection integration. Cardinal Health anchors distribution dominance via direct-to-facility logistics networks spanning acute care systems. Medline Industries occupies a position as the private-label manufacturing specialist supplying cost-engineered disposable options to group purchasing organizations.
| Leading Market Players |
|---|
| 3M |
| Cardinal Health |
| Medline Industries |
| MSA Safety |
| Honeywell International Inc. |
| Alpha Pro Tech |
| Prestige Ameritech |
| Sanax Protective Products |
| Paulson Manufacturing |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Ruhr industrial corridor anchors polycarbonate resin capacity that feeds shield manufacturing across European hospital systems, concentrating upstream pricing leverage among petrochemical processors who index contracts to benzene and propylene futures. This geographic concentration amplifies margin volatility for downstream fabricators while compressing negotiation room for procurement departments in German university hospital networks.
Pricing Analysis
Extended-use warranty programs and sterilization validation services drive lifetime value capture as manufacturers bundle after-sales revenue into direct sales contracts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared anti-fog variants from ANSI Z87.1 certified standard grades and PET-based disposable tiers. Cost compression in economy channels intensifies because group purchasing organizations consolidate volume and squeeze per-unit margins. Clinics in price-sensitive tiers exhibit highest price sensitivity; German Bundeswehr medical corps procurement demonstrates lowest sensitivity due to pandemic preparedness mandates.
Supply Chain Analysis
Petroleum feedstock volatility between Middle Eastern suppliers and Asian resin processors dominates margin risk for polycarbonate shield manufacturers. Production gravity centers on Germany, China, and the United States for finished assemblies, while benzene and propylene feedstocks draw from integrated petrochemical complexes in the Middle East and Asia. Single-source vulnerability in plasma-enhanced coating equipment constrains anti-fog variant scaling. Distribution runs through direct-to-facility logistics networks for hospital systems and wholesale channels for clinic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
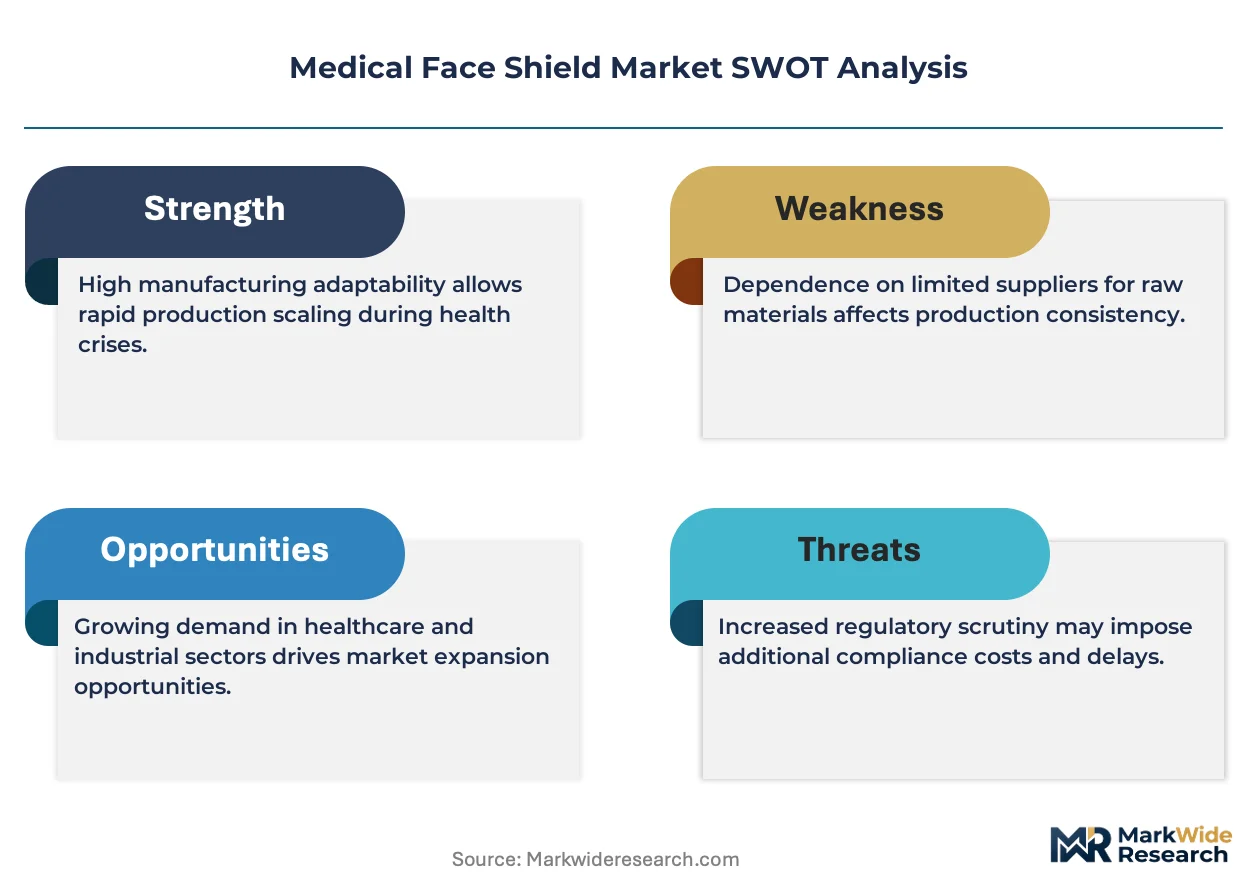
The medical face shield market functions as a defensive-moat sector where regulatory entrenchment through FDA 510(k) clearance and EU MDR certification creates switching costs that protect incumbent positions against commodity competition.
For Market Incumbents: Harden certification portfolios by accumulating predicate devices for anti-fog variants that streamline FDA submission pathways. Deepen captive supply of polycarbonate resin through backward integration into benzene-processor relationships. Elastomeric respirator substitution threatens standalone shield demand; anchor hospital contracts through respiratory protection platform bundling that 3M exemplifies.
For New Entrants and Emerging Players: Pursue rural India clinic tier penetration where CDSCO regulations tighten but standardized PPE protocols remain underdeveloped. Maharashtra and Uttar Pradesh primary health centers offer first-mover positioning for PET-based economy shield suppliers. Direct sales channel engagement with state-level procurement offices bypasses entrenched wholesale networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sterilization-as-a-service platform operators over commodity disposable manufacturers. Long-term viability hinges on recurring revenue capture through validation partnerships rather than transactional unit sales. Acquisition target archetype: regional fabricators with notified body relationships and autoclave network access. Monitor FDA guidance velocity on fluid resistance testing thresholds as inflection signal for technical barrier elevation.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Accumulation | Anti-fog variant submissions leverage cleared devices to compress regulatory timelines for hospital procurement contracts. |
| Plasma-Enhanced Coating Deposition | German university hospitals specify vapor-deposited hydrophilic treatments that embed durability guarantees into multi-year agreements. |
| Sterilization-As-A-Service Partnership | Third-party validation partnerships allow manufacturers to capture recurring revenue without capital-intensive autoclave infrastructure. |
| Backward Integration into Resin Sourcing | Captive benzene-processor relationships insulate margin predictability against petroleum feedstock volatility. |
| Group Purchasing Organization Unbundling | Per-use cost models displace unit pricing as Cardinal Health and Medline Industries compete on logistics network efficiency. |
Study Parameters
Operator-level perspectives from hospital procurement directors, GPO contracts managers, biomedical engineers, and sterilization validation specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and customs trade records. Bottom-up demand modeling across product type, end user, material, and distribution channel segments triangulated with top-down macroeconomic anchoring.
Scenario-bracketing framed projections across conservative, baseline, and expansion cases throughout the forecast period. Segmentation dimensions modeled include durability tier, sterilization protocol, optical performance grade, and regional regulatory cluster. CAGRs derived from installed base amortization cycles and replacement rate analysis. Industry-specific inputs incorporated OSHA bloodborne pathogen compliance mandates and EU MDR notified body capacity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by elastomeric respirator manufacturers or rapid MDR certification acceleration would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Portable OT Light Market
Medical Devices
Ambulatory X-Ray Devices Market
Medical Devices
Infusion Fluid Holder Market
Medical Devices
China Intrauterine Devices Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Syringeless Injector Market
Medical Devices
Electric Handpiece Market
Medical Devices
Diabetes Devices Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market
Medical Devices
Auto Keratometer Market
Medical Devices
UHD Surgical Display Market
Medical Devices
IV Fluid Monitoring Device Market
Medical Devices
Deaver Retractor Market
Medical Devices
Europe Biopsy Devices Market