
 Orthokeratology Market | 2026-2036
Orthokeratology Market Size, Share, and Industry Trends Forecast 2026-2036
Orthokeratology Market Outlook
Aftermarket lens replacement and fitting adjustment revenue is reconfiguring profit pools away from initial device sales across the orthokeratology value chain. Euclid Systems Corporation specializes in custom-designed orthokeratology lenses with advanced topography-guided manufacturing. Menicon Co., Ltd. leverages its integrated Japanese production base to sustain quality consistency across international markets. CooperVision Inc competes through broad distribution reach into partnered clinic networks across multiple continents.
Orthokeratology employs rigid gas-permeable contact lenses worn overnight to temporarily reshape corneal curvature, typically manufactured from fluorosilicone acrylate materials with oxygen permeability values exceeding 100 Dk/t to ensure physiological safety during extended wear. The primary commercial purpose centers on reversible myopia correction and progressive myopia control in children without daytime visual correction. Custom designed lenses command premium positioning due to corneal topography matching requirements, while digital imaging technology underpins precision fitting workflows that reduce remake rates. GP lenses retain volume leadership in mature markets though pre-carved alternatives gain traction in price-sensitive segments.
FDA 510(k) clearance requirements for overnight wear indications shape US product entry timelines and clinical evidence standards. The EU Medical Device Regulation and CE marking obligations govern European market access with enhanced post-market surveillance mandates. China's NMPA oversees domestic lens registration while the country's national myopia control guidelines directly channel pediatric demand toward orthokeratology interventions. Stakeholders must monitor regulatory divergence between jurisdictions as classification rules and clinical data requirements evolve.
Market Dynamics
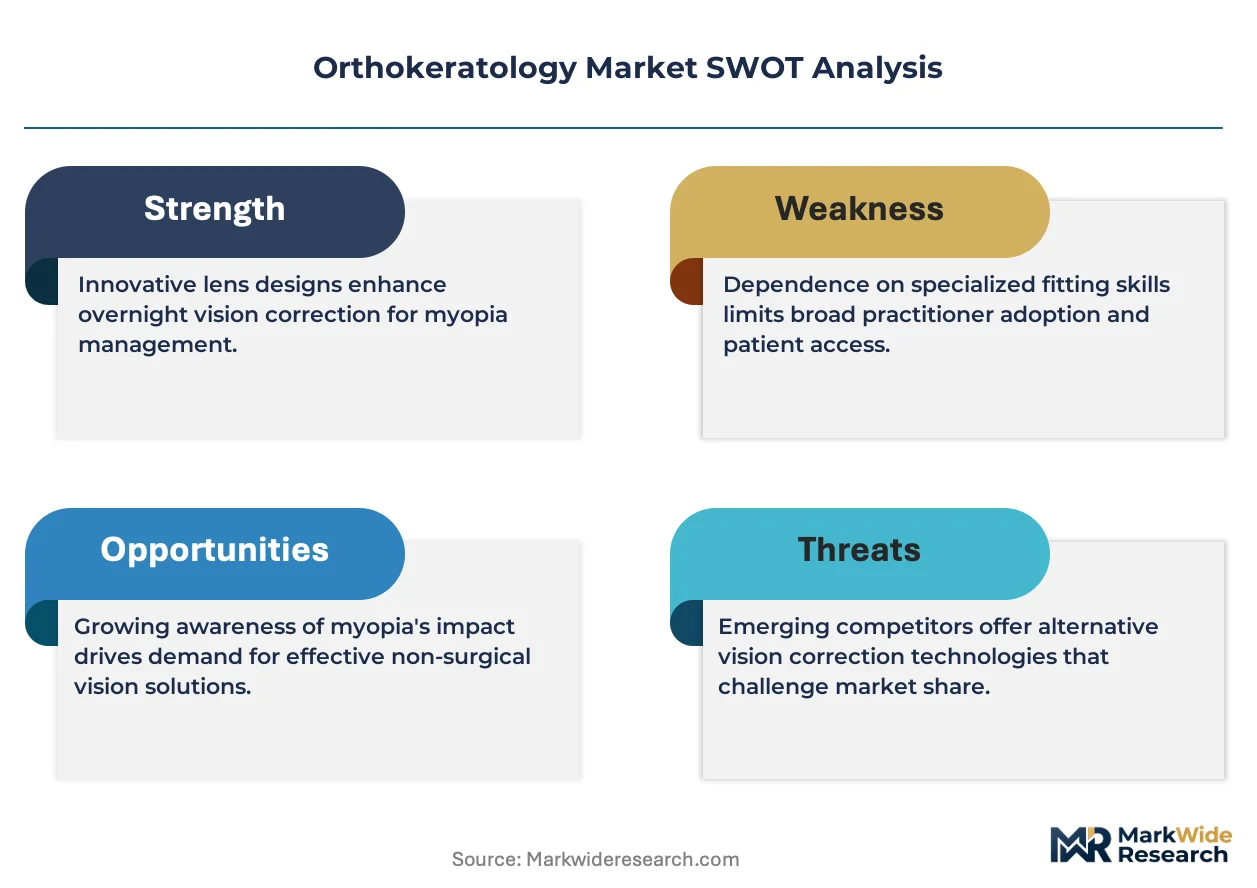
China's national myopia control guidelines are redirecting pediatric vision care spending toward overnight orthokeratology lenses, compressing fitting cycles and reshaping clinic economics across East Asian markets.
Growth Catalysts
- East Asian school screening mandates:China's Ministry of Education mandates annual vision screening for students, channeling detected myopia cases toward orthokeratology interventions in urban clinic networks.
- Fluorosilicone acrylate material advances:Oxygen permeability values exceeding 100 Dk/t enable safe overnight wear, expanding the addressable patient pool to younger children.
- FDA 510(k) pathway maturation:Established clearance frameworks for overnight wear indications reduce regulatory uncertainty for US market entrants.
Market Restraints
- High-fitting skill dependency:Corneal topography interpretation and lens customization require specialized optometrist training, limiting clinic expansion velocity.
- Raw material supplier concentration:Fluorosilicone acrylate monomer production concentrates among Japanese and German chemical specialists, creating input cost volatility.
- LASIK substitution threat:Laser vision correction offers permanent refractive outcomes for adult patients, capping orthokeratology's adult market penetration.
Strategic Opportunities
- Underpenetrated Southeast Asia:Vietnam, Thailand, and Indonesia lack established orthokeratology clinic networks despite rising pediatric myopia prevalence.
- Telemedicine-integrated fitting workflows:Remote corneal topography review and lens ordering platforms reduce geographic barriers to specialist access.
- EU Medical Device Regulation harmonization:CE marking under MDR enables streamlined multi-country European market access for compliant manufacturers.
Industry Challenges
- Corneal topography technician shortage:Precision fitting requires skilled operators capable of interpreting elevation maps and designing reverse geometry lenses.
- Extended FDA clinical trial timelines:Pediatric myopia control claims require multi-year efficacy studies, delaying product differentiation for US manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthokeratology Market |
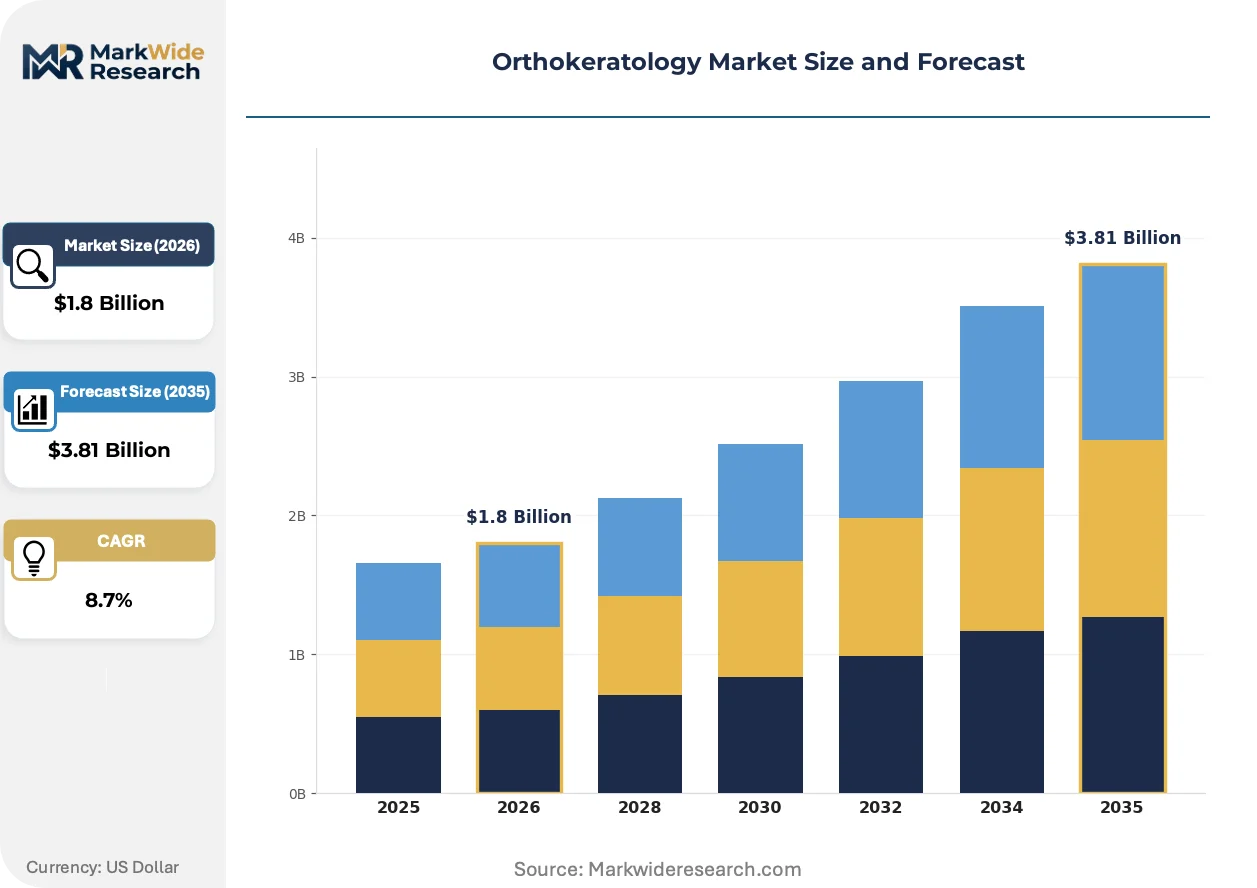
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GP Lenses, Pre-carved Lenses, Custom Designed Lenses, Speciality Lenses End User: Optometrists, Ophthalmologists, Clinics, Retail Eye Care Centers Distribution Channel: Online, Offline, Direct Sales, Partnered Clinics Technology: Digital Imaging, Scanning Technology, Myopia Management, Lens Manufacturing |
| Companies Covered | Bausch & Lomb Incorporated, Euclid Systems Corporation, CooperVision Inc, Johnson & Johnson Vision Care, Inc., Menicon Co., Ltd., Alpha Corporation, Brighten Optix Co., GP Specialists, TruForm Optics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthokeratology Market Strategic Shifts
Digital corneal mapping and artificial intelligence are compressing fitting workflows while regulatory harmonization efforts reshape competitive entry barriers across major markets.
Topography-guided lens design software is digitizing the traditionally manual fitting process. Pediatric clinics in China and South Korea are adopting these platforms at accelerating rates. The technology is digitizing corneal shape analysis, reducing remake rates from empirical fitting methods.
China's NMPA has tightened post-market surveillance requirements for overnight wear contact lenses. Domestic manufacturers must now submit annual safety reports and adverse event data. Imported products face extended review timelines, favoring local registrants with established compliance infrastructure.
Aftermarket service unbundling is fragmenting revenue streams across the value chain. Clinic networks are separating initial fitting fees from replacement lens subscriptions and adjustment visits. This shift is most pronounced in China's tier-one cities, where chain optometry brands compete on service packaging rather than device margins alone.
Orthokeratology Market Segmentation
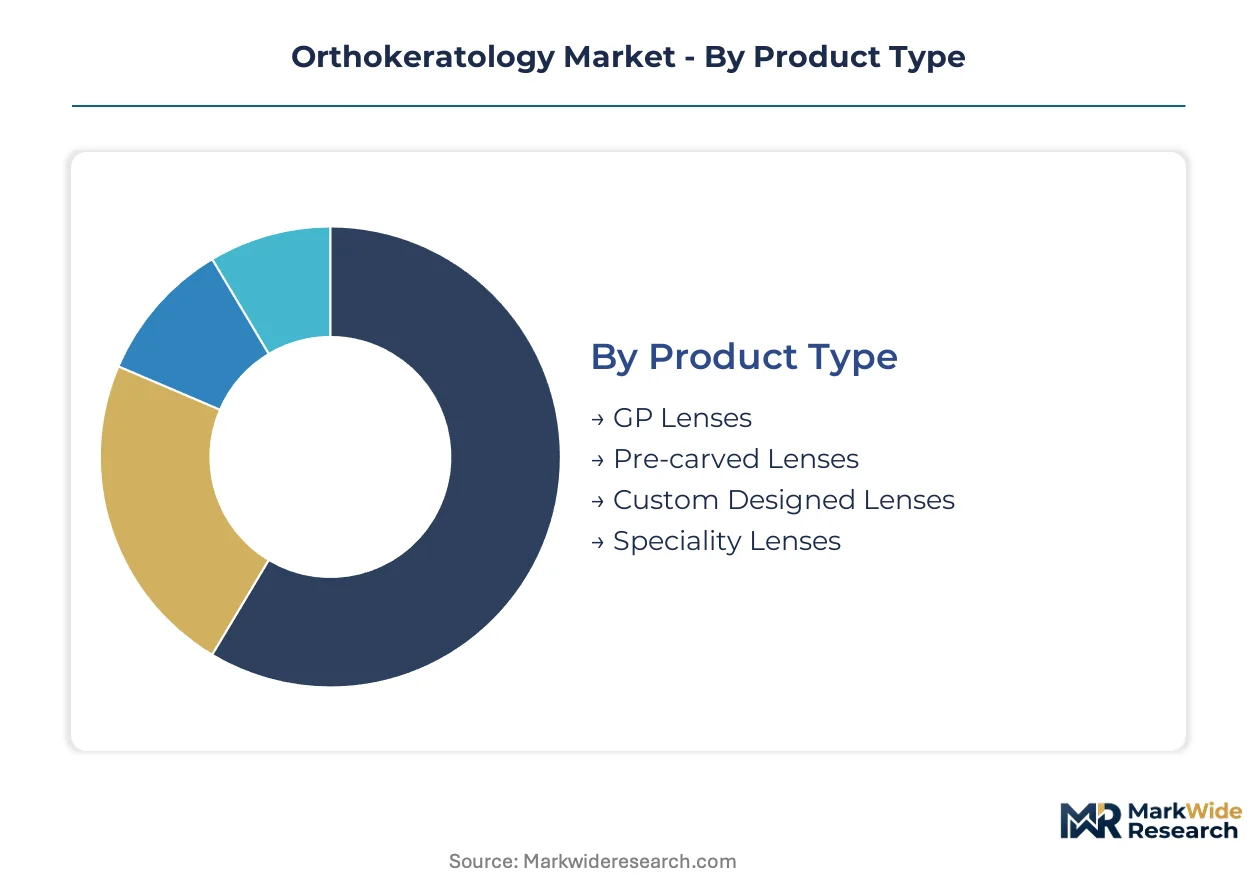
Orthokeratology revenue streams fragment across fitting workflows, with aftermarket lens replacement and adjustment visits now exceeding initial device margins. Segmentation reveals where service intensity concentrates profit pools away from hardware sales.
Product Type:
After-sales service intensity varies sharply by lens category, with custom designs demanding recurring topography reviews and replacement schedules that lock in multi-year patient relationships.
- GP Lenses:Manufactured from fluorosilicone acrylate with oxygen permeability exceeding 100 Dk/t, these rigid gas-permeable lenses dominate mature markets through established fitting protocols and broad practitioner familiarity. Demand concentrates in US and Japanese optometry networks where FDA and PMDA clearance histories have built prescriber confidence over decades, though remake rates from empirical fitting methods compress margins compared to digitally guided alternatives.
- Custom Designed Lenses:Corneal topography-matched reverse geometry designs command premium positioning through individualized curvature mapping and precision manufacturing workflows. Chinese urban clinic networks drive volume here, as national myopia control guidelines channel pediatric cases toward personalized interventions with documented efficacy tracking requirements.
- Pre-carved Lenses:Standardized curvature inventories reduce fitting complexity and per-unit cost for price-sensitive markets.
- Speciality Lenses:Hybrid designs address irregular corneas or combined refractive errors beyond standard myopia correction.
GP lenses hold the largest share; momentum sits with custom designed lenses.
End User:
Margin capture concentrates with practitioners who control both diagnosis and fitting workflow, creating divergent economics across credential types.
- Optometrists:Primary gatekeepers for orthokeratology fitting in most markets, these practitioners combine refractive assessment with corneal topography interpretation and lens customization. Chinese chain optometry brands in Shanghai, Beijing, and Guangzhou are consolidating this channel through standardized training programs and centralized lens ordering platforms.
- Clinics:Dedicated myopia control centers capture the highest per-patient lifetime value through subscription-based replacement lens programs and scheduled follow-up protocols. South Korean clinic networks in Seoul and Busan pioneered this model, with tier-one Chinese cities now replicating the structure.
- Ophthalmologists:Surgical specialists typically refer orthokeratology cases to optometric colleagues, limiting direct fitting volume.
- Retail Eye Care Centers:General optical retailers lack specialized topography equipment and trained staff for orthokeratology services.
Optometrists anchor volume; clinics are expanding most quickly.
Distribution Channel:
Channel selection determines regulatory exposure and patient relationship depth, with hybrid models emerging to balance compliance and convenience.
- Partnered Clinics:Manufacturer-affiliated networks enforce standardized fitting protocols and quality audits while capturing recurring revenue through exclusive lens supply agreements. Menicon and Euclid Systems Corporation have built dense partnered footprints across Japan, South Korea, and coastal China.
- Direct Sales:Lens manufacturers selling directly to established practitioners bypass distributor markups but require internal compliance infrastructure for multi-jurisdiction regulations.
- Online:Remote ordering platforms face strict limitations where overnight wear contact lenses require prescription verification and fitting supervision.
- Offline:Traditional distributor networks persist in markets with fragmented optometry practice structures.
Partnered clinics dominate value capture; direct sales channels are gaining share fastest.
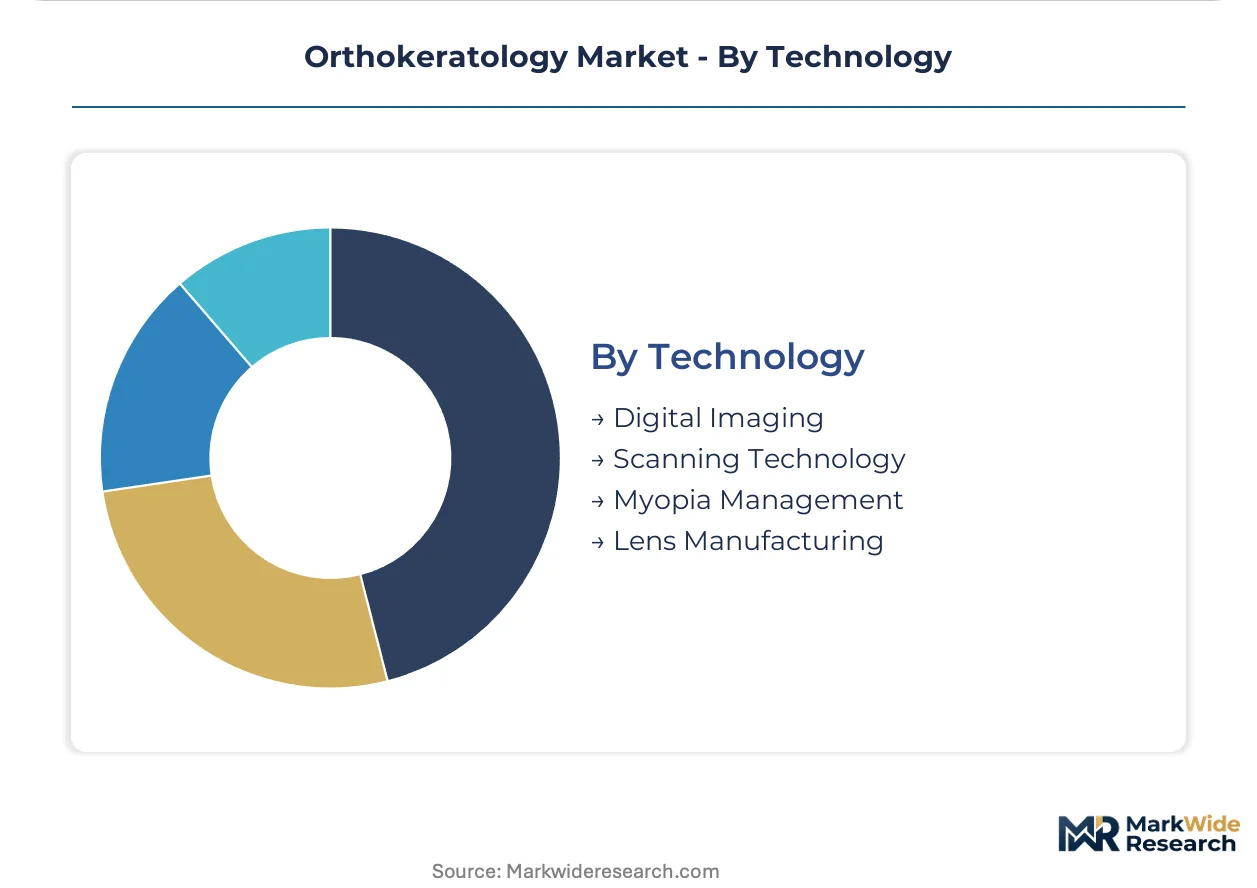
Technology:
Technology stack investments separate precision-fit leaders from commodity competitors, with digital workflows now table stakes for premium positioning.
- Digital Imaging:Corneal topography and tomography systems enable sub-micron elevation mapping that feeds directly into lens design software. Chinese pediatric clinics are adopting these platforms at accelerating rates to meet NMPA documentation requirements for overnight wear safety monitoring.
- Myopia Management:Integrated software platforms track axial length progression and treatment efficacy over multi-year pediatric protocols. South Korean and Taiwanese clinic networks have developed proprietary databases that demonstrate outcomes to parents and regulators.
- Scanning Technology:Optical coherence tomography and Scheimpflug imaging provide anterior segment detail for complex cases.
- Lens Manufacturing:Computer numerical control lathes and plasma surface treatments enable the reverse geometry profiles essential for corneal reshaping.
Digital imaging commands current investment; myopia management platforms show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with Chinese buyers accepting premium pricing for pediatric myopia control while Southeast Asian markets remain acutely price-sensitive despite rising prevalence rates.
China
Urban parents in tier-one cities prioritize documented myopia progression control over absolute cost, driving fitting volume through Shanghai and Beijing clinic networks. The NMPA tightened post-market surveillance for overnight wear lenses, requiring annual safety submissions from domestic and foreign registrants. The Yangtze River Delta cluster around Shanghai concentrates manufacturing capacity for fluorosilicone acrylate materials and precision lathe operations.
United States
Adult patients seeking reversible refractive correction without daytime lens wear sustain steady demand, though pediatric penetration lags East Asian levels. The FDA 510(k) pathway for overnight wear indications demands multi-year clinical evidence, compressing new entrant timelines. Southern California and Texas metropolitan areas host the densest concentrations of orthokeratology-certified optometrists and affiliated fitting centers.
Japan
Established PMDA clearance histories dating to the 1990s built enduring practitioner confidence in rigid gas-permeable modalities. METI-supported quality certification programs reinforce domestic manufacturer positioning against imported alternatives. The Kansai region around Osaka maintains specialized production facilities for high-Dk/t fluorosilicone acrylate monomers supplying regional lens fabricators.
South Korea
Subscription-based replacement lens programs pioneered in Seoul clinic networks now serve as the template for Chinese tier-one city replication. The MFDS regulates overnight wear contact lenses under medical device classification with post-market adverse event reporting mandates. The Seoul Capital Area concentrates both fitting volume and domestic lens design software development.
Germany
Price-sensitive consumers in Europe's largest economy gravitate toward pre-carved lens alternatives where standardized designs reduce per-unit cost. The EU Medical Device Regulation and CE marking requirements govern market access with enhanced post-market surveillance obligations. Bavaria's precision optics manufacturing base supplies corneal topography equipment deployed across European fitting practices.
Orthokeratology Market Competitive Environment
Capability concentration sits with specialized manufacturers possessing topography-guided design workflows; scale advantage sits with diversified optical conglomerates leveraging broad distribution infrastructure. The vendor base separates into three tiers: integrated Japanese producers with captive material supply, US-based precision specialists, and emerging Chinese fabricators serving domestic price points. Strategic moves center on clinic network exclusivity agreements and telemedicine-integrated fitting platform development.
Among Japanese specialists, Menicon Co., Ltd. exemplifies the integrated production archetype with in-house fluorosilicone acrylate capabilities, while Euclid Systems Corporation represents the precision-design tier through its topography-matched customization focus. CooperVision Inc occupies the scale-driven position, leveraging continental distribution reach into partnered clinic networks across multiple jurisdictions.
| Leading Market Players |
|---|
| Bausch & Lomb Incorporated |
| Euclid Systems Corporation |
| CooperVision Inc |
| Johnson & Johnson Vision Care, Inc. |
| Menicon Co., Ltd. |
| Alpha Corporation |
| Brighten Optix Co. |
| GP Specialists |
| TruForm Optics Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in fluorosilicone acrylate monomer production across Japan and Germany is tightening supplier pricing power and compressing lens manufacturer margins, while Chinese fabricators exploit domestic material availability to undercut premium positioning.
Pricing Analysis
Aftermarket service revenue including replacement lens subscriptions and topography-guided adjustment visits now drives lifetime patient value beyond initial fitting fees. Three-tier pricing structure across premium custom designs, standard GP lenses, and economy pre-carved alternatives separates Menicon and Euclid positioning from emerging Chinese competitors. Cost compression in the pre-carved tier is intensifying because Vietnamese and Indonesian buyers resist premium custom workflows. Clinic networks in China's tier-one cities show least price sensitivity, while Southeast Asian retail eye care centers remain acutely cost-conscious.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk planning for fluorosilicone acrylate lens manufacturers. Raw material production concentrates in Japan's Kansai region and Germany's chemical corridor, with precision lathe fabrication clustering in China's Yangtze River Delta. Lens manufacturing draws from fluorosilicone acrylate monomers, CNC lathe equipment, and plasma surface treatment systems. Single-source vulnerability persists for high-Dk/t material formulations. Distribution runs through manufacturer-partnered clinic networks with exclusive supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orthokeratology sits in early-cycle expansion as China's national myopia control guidelines institutionalize overnight lens protocols across East Asian pediatric care systems.
For Market Incumbents: Insulate margin structure by deepening backward integration into fluorosilicone acrylate material production and securing exclusive topography-guided design software licenses. Lock in clinic network loyalty through multi-year replacement lens subscription contracts before emerging Chinese fabricators achieve NMPA registration parity. For New Entrants and Emerging Players: Build out telemedicine-integrated fitting platforms targeting Vietnam, Thailand, and Indonesia where established clinic networks remain sparse. Penetrate through optometrist training partnerships that address the corneal topography technician shortage blocking competitor expansion. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among clinic networks with subscription-based replacement programs and proprietary myopia management databases. Five-to-ten year viability favors targets with NMPA or FDA overnight wear clearance already secured. Watch for MFDS adverse event reporting spikes as an inflection signal on safety perception.| Strategic Initiative | Industry Significance |
|---|---|
| Topography-Guided Design Software Development | Digital fitting workflows reduce remake rates and lock in practitioner loyalty through proprietary platforms. |
| NMPA Overnight Wear Registration | Domestic Chinese clearance accelerates market access ahead of extended review timelines facing imported products. |
| Fluorosilicone Acrylate Backward Integration | In-house monomer production shields margins from Japanese and German supplier concentration. |
| Subscription-Based Replacement Programs | Recurring lens revenue transforms one-time fitting economics into multi-year patient relationships. |
| Telemedicine-Integrated Fitting Platforms | Remote topography review expands geographic reach beyond specialist-constrained urban centers. |
Study Parameters
Initial hypotheses were tested against primary input from orthokeratology-certified optometrists, clinic network operators, fluorosilicone acrylate material suppliers, and NMPA regulatory consultants and refined through secondary validation against FDA 510(k) filings, MFDS medical device registrations, Chinese customs trade data, and hospital procurement databases. Bottom-up fitting volume estimates from clinic networks were triangulated against top-down material consumption figures from fluorosilicone acrylate producers.
Demand-supply balance modeling across the projection horizon incorporated pediatric myopia prevalence trajectories, regulatory clearance pipeline status, and practitioner training capacity constraints. Segmentation dimensions included lens type, end-user credential, distribution channel structure, and technology stack investment level. CAGRs were derived from fitted adoption curves calibrated to historical fitting volume data and policy implementation timelines. Industry-specific inputs encompassed NMPA post-market surveillance reporting frequency and MFDS adverse event database trends.
Stress conditions across fluorosilicone acrylate price volatility, NMPA registration timeline extension, and LASIK technology advancement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on policy continuity and material supply stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
USA Ophthalmic Devices Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Lazy Eye Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Nystagmus Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
Macular Edema and Macular Degeneration Market
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Choroideremia Treatment Market
Ophthalmology
Conjunctivitis Treatment Market