
 Steerable Needles Market | 2026-2036
Steerable Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Steerable Needles Market Analytics
The capability gap between capital-heavy integrated manufacturers and lean device specialists is collapsing. Boston Scientific Corporation leverages in-house catheter production to control steerable tip geometries. Merit Medical Systems anchors its position through concentrated R&D spending on electromagnetic tracking integration. Medtronic dominates hospital contracting channels across North American academic medical centers.
Steerable needles are deflectable interventional instruments, typically constructed from nitinol or stainless steel hypotubes with pre-curved stylets or tendon-actuated tips, designed to navigate around anatomical obstacles during percutaneous procedures. Electro-surgical needle variants incorporate active electrodes for tissue ablation, while biopsy needle configurations prioritize sample core integrity through adjustable trajectory correction. Robotic systems represent the fastest-expanding technology segment as surgical platforms demand sub-millimeter positional repeatability. Hospitals remain the dominant end-user channel, though outpatient centers are gaining share where same-day interventional procedures expand capacity.
FDA 510(k) clearance requirements and EU MDR technical documentation standards govern steerable needle commercialization, with both frameworks intensifying biocompatibility and sterilization validation demands. Japan's PMDA imposes additional clinical data requirements for novel tip-deflection mechanisms, extending market entry timelines for non-domestic manufacturers. Stakeholders must monitor how electromagnetic tracking interoperability standards evolve across regulatory jurisdictions.
Market Dynamics
Electromagnetic tracking interoperability standards are compressing development cycles for steerable needle platforms as manufacturers race to integrate real-time navigation with existing surgical robotics infrastructure.
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating biocompatibility validation investments to capture European hospital procurement contracts before technical documentation requirements intensify.
- Same-day interventional capacity:Outpatient centers in the United States expanding biopsy and ablation volumes, creating pull-through demand for deflectable tip configurations.
- Nitinol hypotube supply:Concentrated Taiwanese and German metallurgy suppliers enabling precision pre-curving capabilities for tendon-actuated designs.
Market Restraints
- Input cost volatility:Nitinol alloy prices fluctuate with nickel spot markets, squeezing gross margins for hypotube-dependent manufacturers.
- Regulatory friction:Japan's PMDA imposes extended clinical data requirements on novel tip-deflection mechanisms, delaying market entry for non-domestic firms.
- Technical limitation:Electromagnetic interference from standard surgical equipment degrades tracking accuracy in unshielded operating environments.
Strategic Opportunities
- Underpenetrated outpatient channels:Ambulatory surgical centers in Germany lack dedicated interventional radiology suites equipped with steerable needle systems.
- Technology convergence:Integration of optical coherence tomography with deflectable biopsy needles enables real-time tissue characterization during trajectory adjustment.
- IRA hospital infrastructure incentives:United States facilities qualifying for equipment modernization credits can offset capital deployment for robotic navigation platforms.
Industry Challenges
- Electromechanical engineering talent scarcity:Firms competing for specialists capable of bridging tendon-actuated mechanics with sensor fusion algorithms.
- ISO 13485 certification timelines:Quality management system audits for steerable needle production lines extend 14-18 months, constraining capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steerable Needles Market |
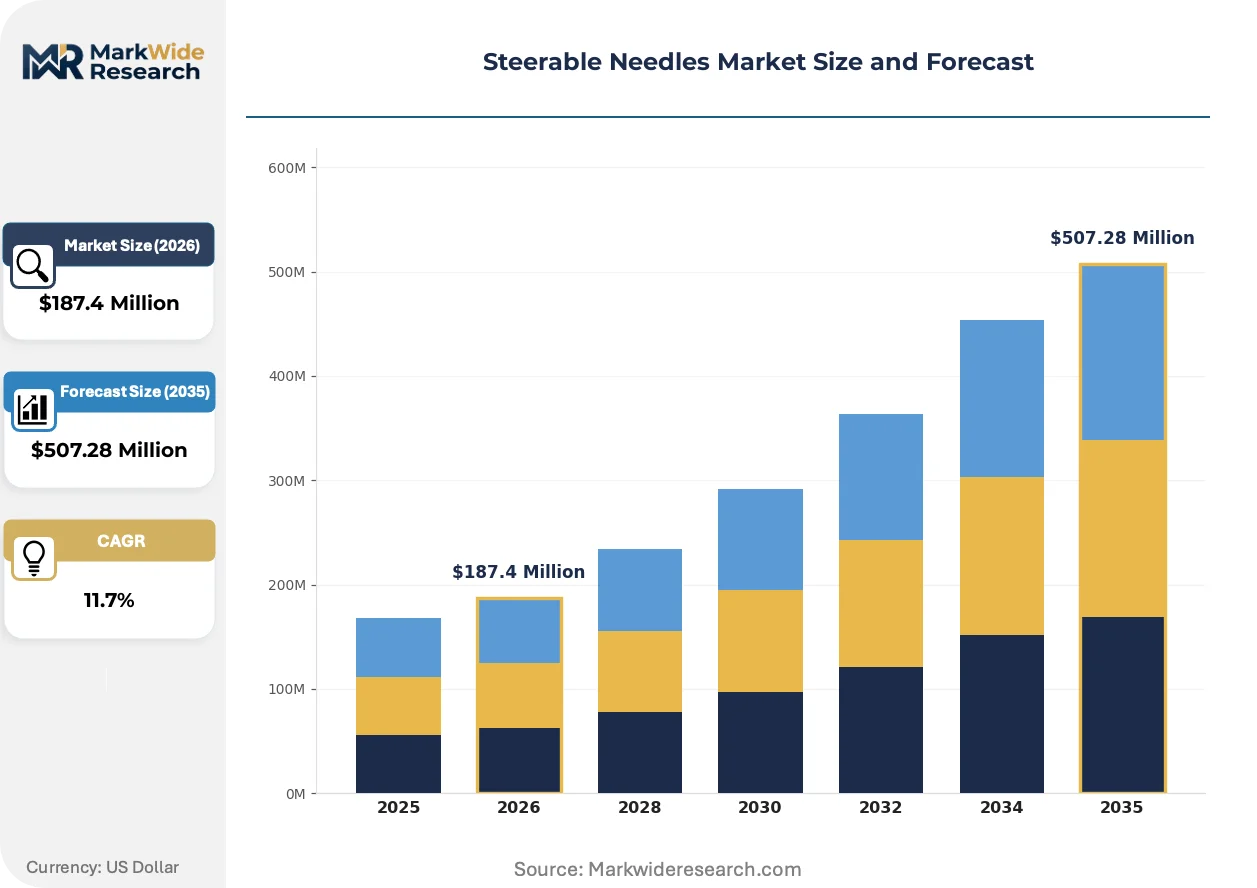
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electro-Surgical Needles, Biopsy Needles, Flexible Needles, Micro-Needles Application: Oncology, Cardiovascular, Neurology, Pain Management End User: Hospitals, Clinics, Research Labs, Outpatient Centers Technology: Ultrasound-Guided, Fluoroscopy-Guided, Electromagnetic Tracking, Robotic Systems |
| Companies Covered | AprioMed, Merit Medical Systems, Boston Scientific Corporation, Medtronic, Olympus Corporation, Johnson & Johnson, Stryker Corporation, Cook Medical, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steerable Needles Market Evolving Landscape
Real-time imaging fusion and disposable instrument economics are rewriting the value equation for percutaneous navigation tools. Device architectures are compressing toward single-use formats while preserving sub-millimeter accuracy.
Shape-memory alloy actuation is miniaturizing. Pre-curved nitinol stylets embedded within 18-gauge hypotubes now enable 90-degree deflection at 3-millimeter bend radii. Academic medical centers in Japan and the United States are piloting these configurations for transbronchial lung biopsy. The technology is miniaturizing access corridors, allowing interventionalists to navigate previously unreachable peripheral nodules without pleural puncture.
EU MDR Article 10 technical documentation requirements are intensifying sterilization validation burdens. Manufacturers must now submit complete biological evaluation plans for reusable steerable needle components. German notified bodies are processing submissions 40% slower than under the prior Medical Devices Directive, compressing European launch windows for 2025 product cycles.
Hospital procurement committees are consolidating vendor relationships around integrated navigation ecosystems. Single-source contracts bundling electromagnetic tracking hardware with disposable steerable needles are displacing standalone instrument purchasing. This concentration is most visible in United States academic medical centers, where capital committees prioritize interoperability with existing robotic bronchoscopy platforms over best-of-breed instrument selection.
Steerable Needles Market Segmentation
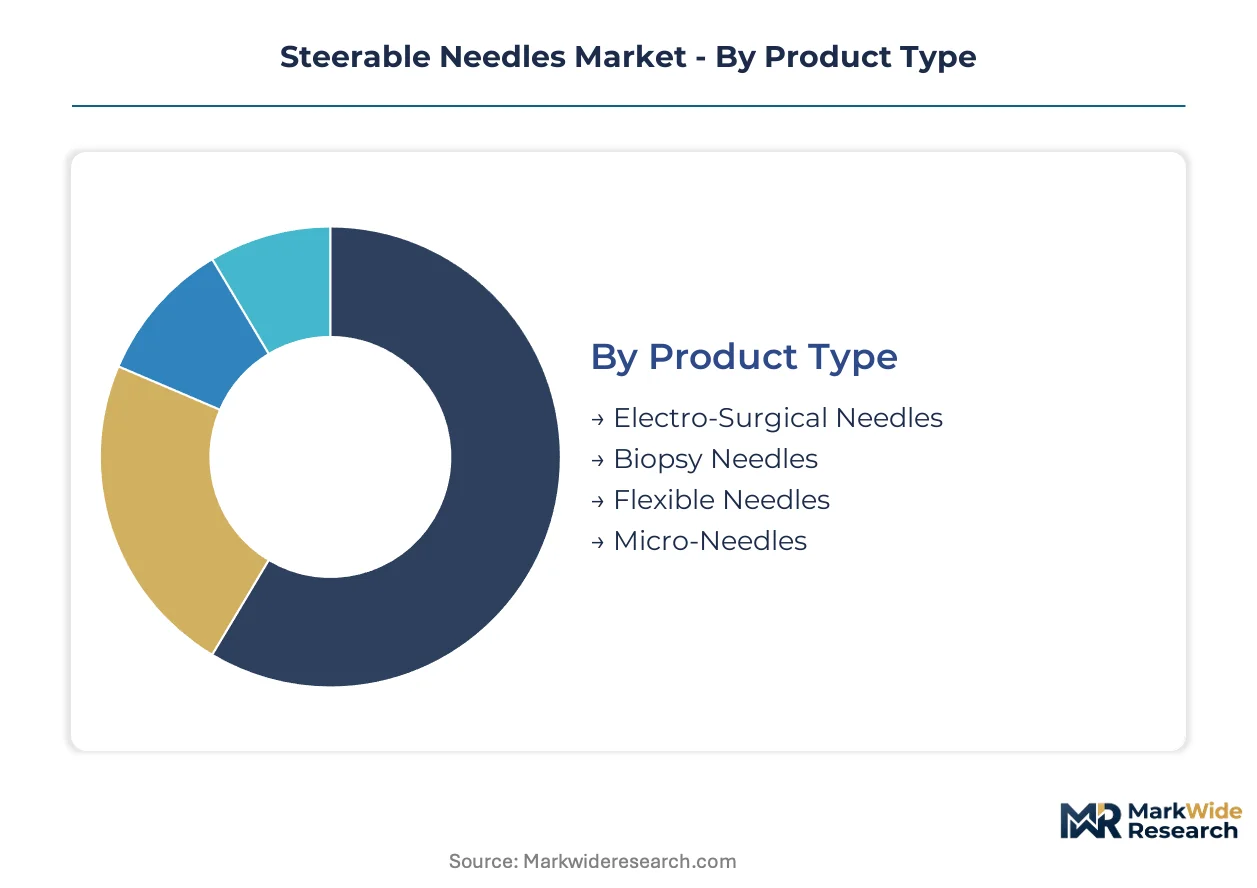
Steerable needle procurement patterns diverge sharply across clinical settings and navigation modalities. Manufacturers configure product portfolios around reimbursement pathways and capital equipment compatibility rather than standalone instrument performance.
Product Type:
Margin pools concentrate in biopsy and electro-surgical configurations where disposable economics and procedure volume create recurring revenue streams.
- Biopsy Needles:Tendon-actuated hypotube designs with adjustable trajectory correction preserve tissue core integrity during peripheral lung and renal sampling. Demand clusters in United States academic medical centers expanding robotic bronchoscopy programs for early-stage nodule diagnosis.
- Electro-Surgical Needles:Active electrode integration enables simultaneous navigation and ablation, eliminating instrument exchanges during thermal tumor destruction. German interventional radiology departments favor these configurations for liver and kidney lesion treatment under CT-fluoroscopy guidance.
- Flexible Needles:Nitinol pre-curved stylets within 18-gauge hypotubes achieve 90-degree deflection at 3-millimeter bend radii for transbronchial access.
- Micro-Needles:Sub-22-gauge formats target ophthalmic and dermatologic applications where tissue displacement tolerance is minimal.
Biopsy Needles hold installed capacity. Flexible Needles are rotating up the share rankings.
Application:
Procedure reimbursement differentials across therapeutic areas determine which applications absorb premium navigation technology.
- Oncology:Percutaneous tumor biopsy and ablation procedures drive the steepest expansion trajectory as lung cancer screening protocols expand eligible patient pools. Japan's PMDA clinical data requirements for novel tip-deflection mechanisms slow entry for transbronchial platforms targeting peripheral nodules.
- Cardiovascular:Electrophysiology mapping and transseptal puncture demand sub-millimeter positional repeatability that electromagnetic tracking integration now enables. United States hospital capital committees prioritize compatibility with existing robotic catheter navigation systems.
- Neurology:Deep brain stimulation lead placement and intracranial biopsy require rigid-framed stereotaxy rather than deflectable needles, limiting addressable volume.
- Pain Management:Radiofrequency ablation of spinal nerves uses simpler curved-tip designs without real-time tracking, compressing price points.
Oncology commands the premium tier. Cardiovascular is gaining procedural share fastest.
End User:
Capital intensity and regulatory compliance burdens sort end users into distinct purchasing behaviors.
- Hospitals:Integrated navigation ecosystems with bundled electromagnetic tracking hardware and disposable steerable needles dominate procurement at United States academic medical centers. FDA 510(k) clearance pathways and IRA infrastructure incentives accelerate capital deployment for robotic platforms.
- Outpatient Centers:Same-day biopsy and ablation volumes are expanding in United States ambulatory settings, creating pull-through demand for deflectable tip configurations without full surgical suite infrastructure.
- Clinics:Pain management and minor dermatologic procedures operate on instrument-only economics without navigation system investment.
- Research Labs:Preclinical validation of novel tip-deflection mechanisms and shape-memory alloy actuation occurs at academic institutions in Japan and Germany.
Hospitals anchor capital deployment. Outpatient Centers are climbing the fastest.
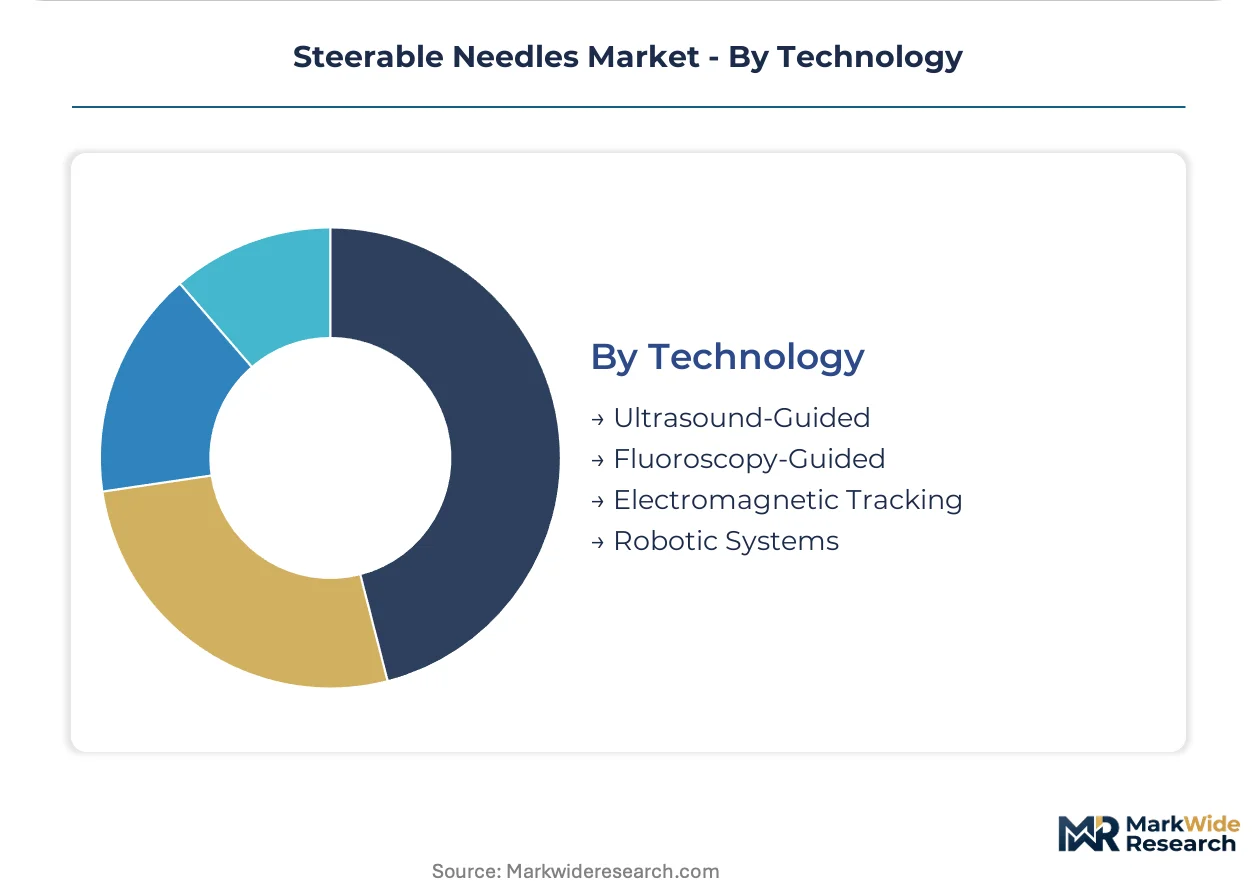
Technology:
Interoperability standards and equipment replacement cycles determine which navigation modalities gain procedural share.
- Robotic Systems:Surgical platforms demand sub-millimeter positional repeatability, driving integration of steerable needles with articulated instrument arms. United States academic medical centers consolidate vendor relationships around single-source contracts bundling hardware and disposables.
- Electromagnetic Tracking:Real-time navigation with existing surgical robotics infrastructure is compressing development cycles, though electromagnetic interference from standard surgical equipment degrades accuracy in unshielded environments.
- Ultrasound-Guided:Cost-effective visualization for superficial and abdominal procedures without capital equipment dependencies.
- Fluoroscopy-Guided:CT-fluoroscopy integration dominates interventional radiology workflows in German hospitals for hepatic and renal interventions.
Robotic Systems concentrate R&D investment. Electromagnetic Tracking is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for steerable needle systems concentrates in the United States and Germany, where bundled navigation contracts command premiums, while Japanese procurement operates under stricter cost-efficiency mandates that compress margins for non-domestic suppliers.
United States
Academic medical centers in Boston and Houston drive capital deployment for robotic bronchoscopy platforms with integrated steerable needles. FDA 510(k) clearance pathways accelerate commercialization timelines for novel tip-deflection mechanisms. The IRA's hospital infrastructure incentives enable equipment modernization credits that offset capital deployment for navigation systems in Southeast and Midwest facilities.
Germany
Interventional radiology departments in Munich and Berlin favor electro-surgical needle configurations for hepatic and renal ablation under CT-fluoroscopy guidance. EU MDR Article 10 technical documentation requirements intensify sterilization validation burdens, with German notified bodies processing submissions slower than under prior directives. The Baden-Württemberg medical technology cluster concentrates precision hypotube manufacturing for tendon-actuated designs.
Japan
PMDA clinical data requirements for novel tip-deflection mechanisms extend market entry timelines for transbronchial platforms targeting peripheral lung nodules. Tokyo and Osaka academic medical centers pilot shape-memory alloy actuation for 90-degree deflection at 3-millimeter bend radii. METI funding programs support domestic manufacturers developing electromagnetic tracking interoperability standards.
United Kingdom
NHS procurement frameworks prioritize cost containment in interventional radiology suites, limiting uptake of premium navigation ecosystems outside London teaching hospitals. MHRA alignment with EU MDR standards maintains technical documentation requirements post-Brexit. The Cambridge-Oxford medical technology corridor hosts preclinical validation of optical coherence tomography integration with deflectable biopsy needles.
South Korea
MFDS fast-track approval pathways for breakthrough medical devices attract steerable needle manufacturers seeking accelerated Asian market entry beyond Japan. Seoul National University Hospital and Samsung Medical Center drive demand for sub-millimeter positional repeatability in cardiovascular electrophysiology procedures. The Pangyo Techno Valley cluster concentrates surgical robotics development with integrated navigation capabilities.
Steerable Needles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated surgical robotics manufacturers controlling navigation ecosystem bundling while specialized hypotube fabricators compete on disposable instrument economics. The market structures around three tiers: capital-heavy platform vendors, mid-scale navigation integrators, and component-focused specialists. Dominant competitive moves include strategic partnerships for electromagnetic tracking interoperability and portfolio diversification into single-use instrument formats.
Among diversified medical technology conglomerates, Boston Scientific Corporation, Medtronic, and Johnson & Johnson occupy positions that exemplify the capital-intensive platform tier, leveraging hospital contracting channels and in-house catheter production capabilities to anchor bundled navigation ecosystem offerings. Merit Medical Systems represents the mid-scale navigation integrator archetype, concentrating R&D positioning around electromagnetic tracking compatibility. Olympus Corporation and Stryker Corporation sit within the surgical visualization and robotics integration segment, where equipment replacement cycles determine procurement influence.
| Leading Market Players |
|---|
| AprioMed |
| Merit Medical Systems |
| Boston Scientific Corporation |
| Medtronic |
| Olympus Corporation |
| Johnson & Johnson |
| Stryker Corporation |
| Cook Medical |
| Teleflex Incorporated |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Taiwanese nitinol hypotube foundries shapes both supply concentration and price floors for steerable needle manufacturers. German metallurgy specialists command premium positioning through precision pre-curving capabilities, while volume buyers in United States academic medical centers extract discounts through multi-year disposable instrument commitments.
Pricing Analysis
The customization-premium spread separates standard 18-gauge biopsy configurations from configured-to-order electro-surgical needles with integrated ablation electrodes. Three-tier pricing structure across premium, standard, and economy levels stratifies by electromagnetic tracking compatibility and FDA 510(k) clearance tier. Cost compression in standard hypotube segments is intensifying because Taiwanese suppliers are expanding nitinol melting capacity. Outpatient centers exhibit highest price sensitivity due to instrument-only economics without navigation system bundling, while United States hospital capital committees prioritize interoperability premiums over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending inbound logistics timelines for nitinol alloy shipments from Taiwanese ports. Manufacturing gravity centers on Taiwan for hypotube drawing, Germany for precision pre-curving, and United States for final instrument assembly and sterilization. Raw material dependencies rest on nickel spot markets, specialized polymer sheathing, and electromagnetic sensor coils. Single-source vulnerability concentrates in Taiwanese nitinol suppliers serving multiple competing device manufacturers. Distribution runs through hospital GPO contracts in North America, direct interventional radiology department sales in Germany, and layered distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Disposable instrument economics and navigation software subscriptions are expanding faster than capital hardware sales, creating a service-attach opportunity that rewards recurring-revenue business models over one-time platform deployments.
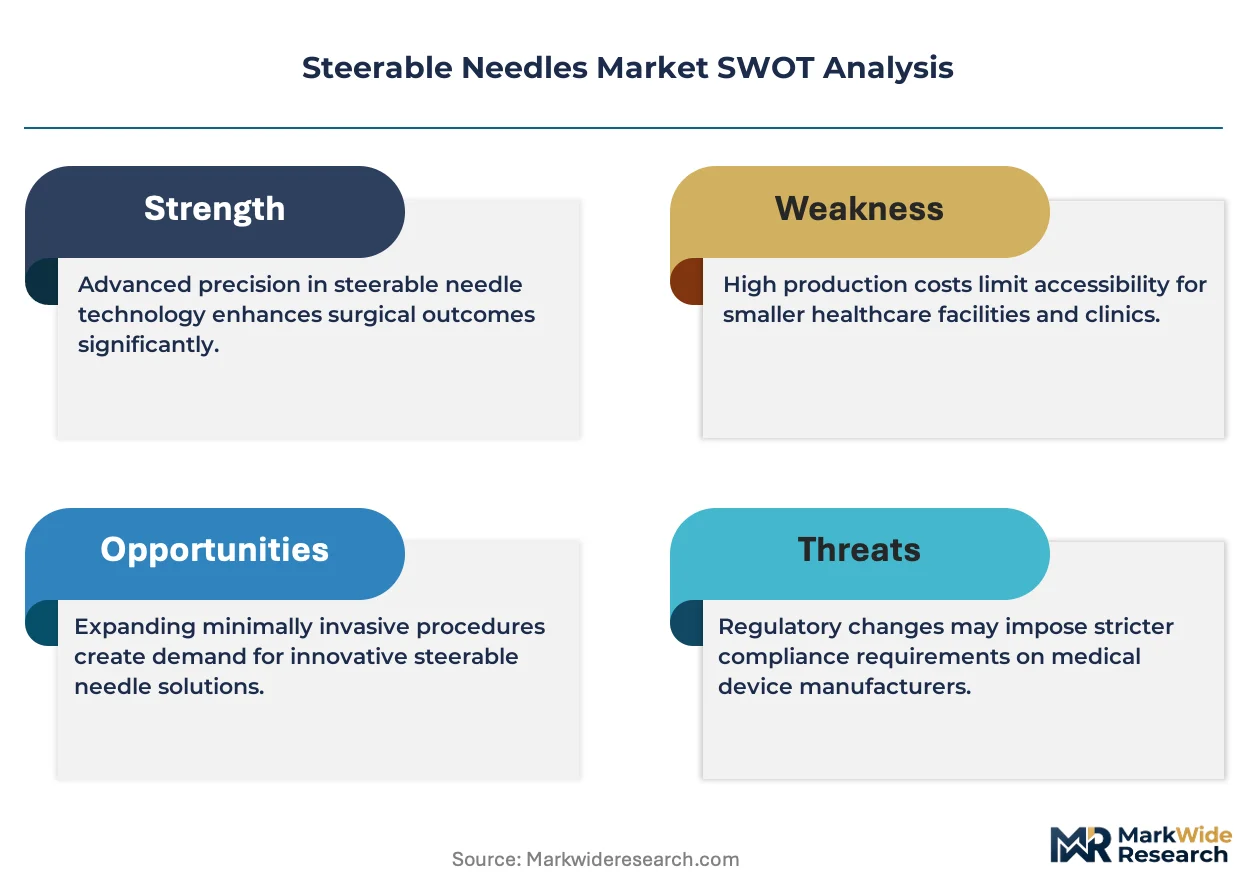
For Market Incumbents: Secure electromagnetic tracking interoperability certification ahead of evolving FDA and EU MDR standards to lock in hospital system switching costs. Consolidate hypotube supply relationships through backward integration into nitinol pre-curving capabilities or exclusive offtake agreements with Taiwanese metallurgy specialists. Electromagnetic interference vulnerabilities in unshielded operating rooms threaten installed base retention if competitors deliver superior shielding solutions. For New Entrants and Emerging Players: Lead with disposable-only instrument configurations targeting German ambulatory surgical centers lacking dedicated interventional radiology suites. Optical coherence tomography integration with deflectable biopsy needles represents the most penetrable white-space application. Pursue MFDS fast-track approval in South Korea to establish Asian market presence before attempting Japan's PMDA-intensive pathway. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mid-scale navigation integrators with electromagnetic tracking compatibility and established hospital contracting channels over capital-heavy platform vendors facing robotics replacement cycle risk. Long-term viability hinges on software companion development capabilities and recurring disposable revenue streams. The signal to watch is consolidation velocity among Taiwanese nitinol suppliers, which would reshape upstream pricing power across device manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Tracking Interoperability Certification | FDA 510(k) clearance for navigation compatibility locks in United States academic medical center procurement. |
| Nitinol Hypotube Backward Integration | In-house pre-curving capabilities insulate gross margins from nickel spot market volatility. |
| Disposable Instrument Format Expansion | Single-use configurations capture outpatient center volume without capital equipment sales cycles. |
| Optical Coherence Tomography Integration | Real-time tissue characterization during trajectory adjustment differentiates premium biopsy platforms. |
| MFDS Fast-Track Approval Pursuit | South Korean regulatory pathway accelerates Asian market entry ahead of Japan's PMDA requirements. |
Research Methodology
The analysis maps biopsy needle configurations, electro-surgical variants, and robotic navigation platforms, each validated through interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interview insights combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up instrument shipment estimates and top-down procedure volume analysis triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application area, end-user channel, and navigation technology modality. CAGRs derive from procedure volume elasticity, equipment replacement cycles, and reimbursement pathway expansion. Industry-specific forecast inputs incorporate electromagnetic tracking adoption curves and EU MDR compliance timeline compression.
Underlying assumptions cover stable nickel alloy pricing, continued FDA 510(k) pathway availability, and EU MDR notified body processing capacity, with deviation risk concentrated in PMDA regulatory delays and electromagnetic interference mitigation breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Gel Stent Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Smart Syringe Market
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
Active Wheelchair Market
Medical Devices
Global Disability Devices Market
Medical Devices
Intravenous Line Connectors Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Global Defibrillators Market
Medical Devices
Foot Suction Unit Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Global Artificial Pancreas Device System Market