
 Global Digital Dentistry Devices Market | 2026-2036
Global Digital Dentistry Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Dentistry Devices Market Foresight
A shift from outsourced dental lab production toward in-house chairside manufacturing is hardening across developed markets. Dentsply Sirona leverages its integrated CAD/CAM portfolio to anchor clinic-level digital workflows. 3Shape competes through open-architecture scanning software that sustains interoperability with third-party mills. Planmeca dominates Nordic markets through its vertical control over imaging, software, and fabrication hardware.
Digital dentistry devices comprise electromechanical and photonic systems that capture intraoral geometry with sub-50-micron accuracy, process three-dimensional data through proprietary software, and fabricate restorations via subtractive milling or additive photopolymerization. Intraoral scanners lead product type revenue due to their position as the entry point for digital workflow adoption. CAD/CAM systems capture the deepest margin pools through recurring software licensing and consumable attachment sales. Artificial Intelligence within the technology dimension is expanding fastest as FDA-cleared algorithms automate margin detection and treatment planning.
The FDA's 510(k) framework governs device safety and software validation for US market access, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking of active implantable accessories. ISO 13485 certification shapes supplier qualification for dental laboratories and clinic chains. Stakeholders must monitor how FDA guidance on AI-enabled diagnostic features reshapes product development roadmaps and competitive differentiation.
Market Dynamics
The shift from centralized dental laboratory production to distributed chairside manufacturing is restructuring procurement patterns across developed markets. This transition compresses turnaround times from weeks to hours while elevating capital intensity at the point of care.
Growth Catalysts
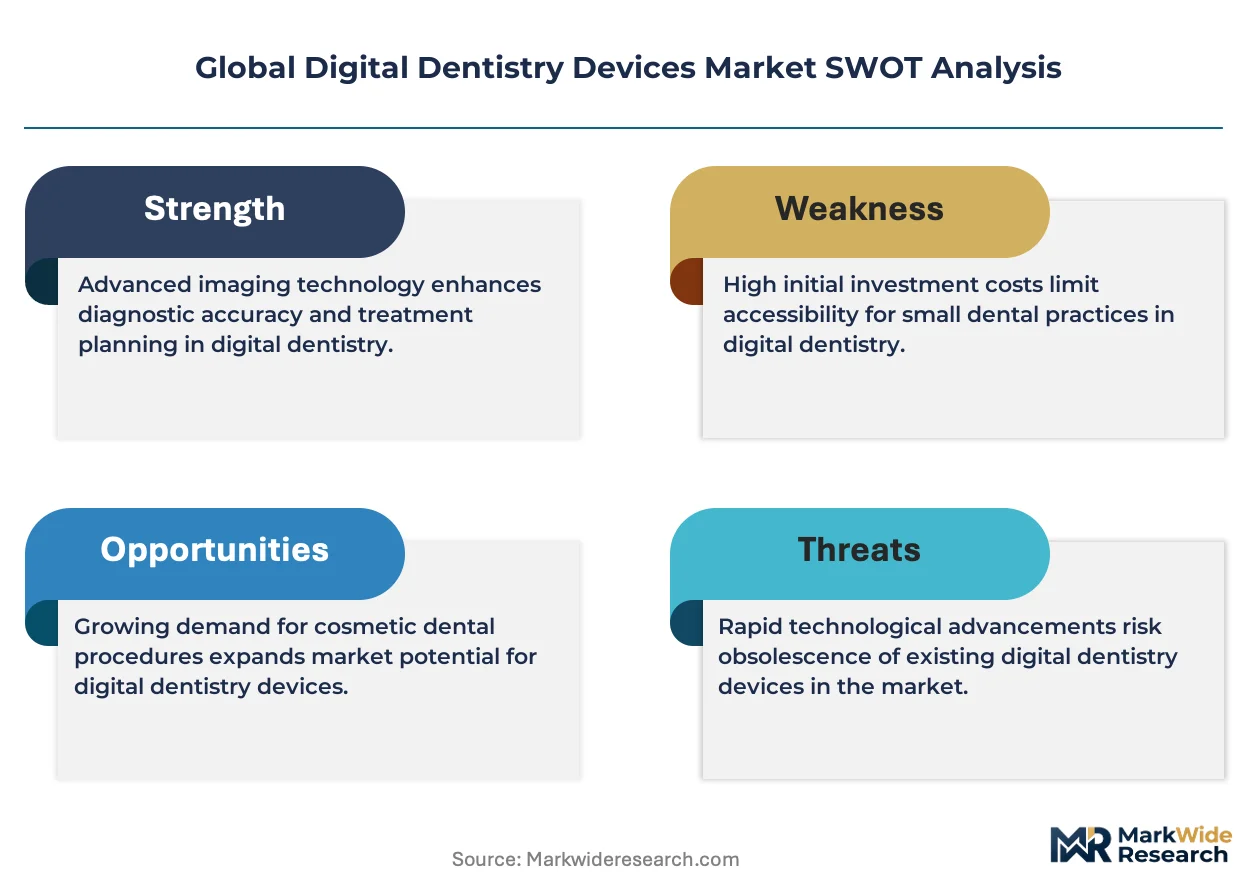
- FDA 510(k) Streamlining:The FDA's expedited clearance pathway for software-enabled diagnostic features accelerates product commercialization timelines for intraoral scanning platforms.
- Chairside CAD/CAM Workflows:Dental clinics in Germany's precision manufacturing corridor around Biberach are deploying integrated milling systems to capture margin pools previously flowing to external laboratories.
- AI-Enabled Margin Detection:Machine vision algorithms cleared under FDA's De Novo pathway automate crown preparation analysis, reducing technician labor hours per restoration.
Market Restraints
- Photopolymer Resin Cost Volatility:Specialty acrylate monomers for additive fabrication face supply tightness from concentrated European chemical producers.
- EU MDR Clinical Evidence Burden:The European Medical Device Regulation's expanded documentation requirements for active implantable accessories lengthen CE marking timelines.
- Sub-50-Micron Accuracy Threshold:Technical limitations in ambient-light rejection constrain scanner performance in uncontrolled clinical environments.
Strategic Opportunities
- Underpenetrated Indian Dental Chains:Corporate dentistry platforms in Mumbai and Bangalore lack digital workflow infrastructure despite accelerating patient volume growth.
- Convergence of Intraoral Scanning and CBCT:Registration of optical surface data with volumetric radiographic datasets enables fully guided implantology without physical impressions.
- Japan's METI Subsidy Programs:Ministry funding for SME technology adoption lowers effective equipment costs for independent practitioners transitioning to digital systems.
Industry Challenges
- CAD/CAM Technician Shortage:Dental schools in the United States graduate insufficient operators proficient in three-dimensional design software for immediate chairside deployment.
- ISO 13485 Certification Bottlenecks:Auditing backlogs at notified bodies delay supplier qualification for laboratory chains seeking vendor diversification.
- Legacy Practice Management Integration:Proprietary scanner data formats resist seamless interoperability with established patient record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Dentistry Devices Market |
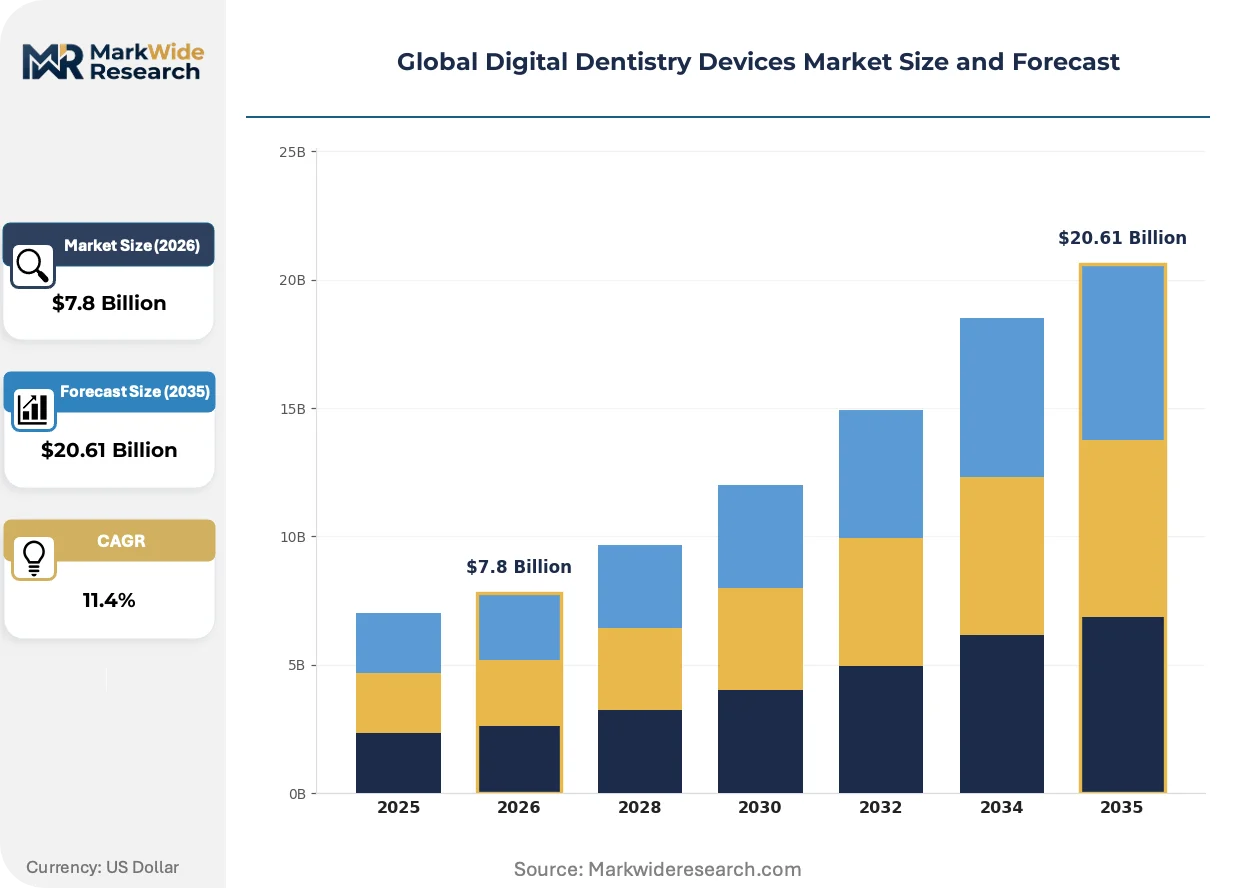
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Scanners, CAD/CAM Systems, 3D Printers, Milling Machines, Dental Lasers, Imaging Systems Technology: Optical, Ultrasonic, Laser, Digital Radiography, Artificial Intelligence, Augmented Reality Application: Orthodontics, Endodontics, Prosthodontics, Oral Surgery, Periodontics, Cosmetic Procedures End User: Dental Laboratories, Dental Clinics, Research Institutes, Dental Schools, Mobile Dental Units |
| Companies Covered | Planmeca, Straumann Group, Dentsply Sirona, Ivoclar Vivadent, Zimmer Biomet, Align Technology, 3Shape, Carestream Dental, Envista Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Dentistry Devices Market Shifts & Advancements
Photopolymerization technology is overtaking subtractive milling as the dominant fabrication modality for provisional and definitive restorations. This transition reflects material science advances and workflow efficiency demands from high-volume dental chains.
Additive manufacturing via vat photopolymerization is overtaking CNC milling for single-unit crowns and surgical guides. Large dental service organizations in the United States are deploying chairside printers at satellite locations to eliminate shipping logistics. This compression of the production-delivery cycle is overtaking the traditional laboratory outsourcing model that dominated the previous decade.
The EU Medical Device Regulation's classification of certain CAD/CAM components as active implantable accessories imposes clinical evidence requirements that exceed prior CE marking standards. German manufacturers in Leinfelden-Echterdingen are expanding regulatory affairs headcount to manage technical documentation. This compliance burden is accelerating consolidation among smaller software developers lacking dedicated quality management systems.
Corporate dental platforms are consolidating purchasing authority previously dispersed across independent practitioners. Large clinic chains in North America now negotiate enterprise software licenses and consumable supply agreements directly with equipment vendors. This concentration of procurement decision-making is visible most acutely in the southeastern United States, where private equity-backed dental groups control expanding geographic footprints.
Global Digital Dentistry Devices Market Segmentation
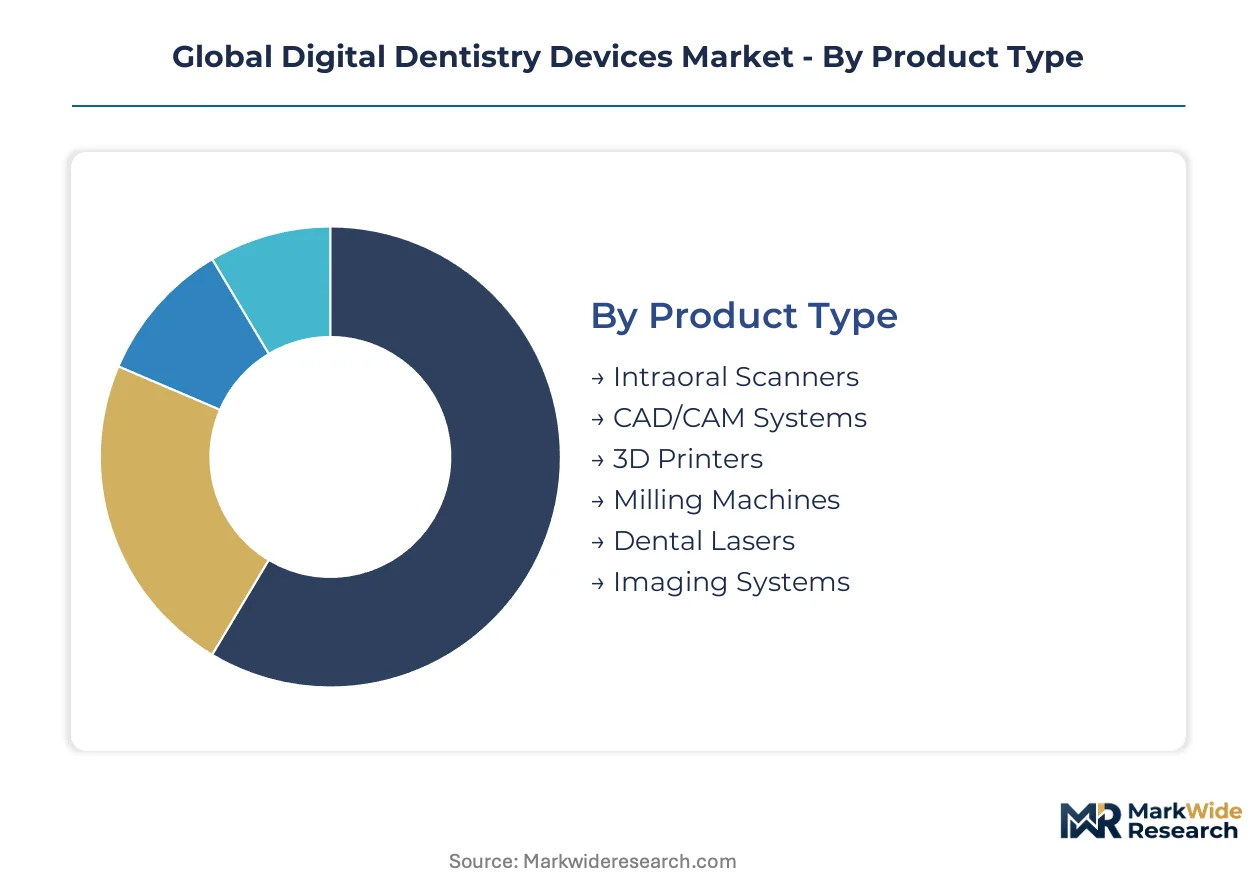
Segmentation reveals how procurement authority concentrates across different customer configurations and how technology adoption patterns vary by clinical application. Understanding these divisions exposes where margin pools accumulate and where competitive positioning shifts most rapidly.
Product Type:
Supply concentration favors integrated platform vendors who bundle hardware with recurring software revenue streams.
- Intraoral Scanners:Handheld photonic devices capture sub-50-micron accurate surface geometry using structured light or confocal microscopy. Demand clusters in Germany's precision manufacturing corridor around Biberach and Leinfelden-Echterdingen, where clinics accelerate chairside workflow adoption to compress turnaround times from weeks to hours.
- CAD/CAM Systems:Integrated design and fabrication platforms combine three-dimensional modeling software with subtractive mills or additive photopolymerization units. Dental laboratories in the United States negotiate enterprise licenses directly with vendors as private equity-backed clinic chains consolidate purchasing authority previously dispersed across independent practitioners.
- 3D Printers:Vat photopolymerization systems fabricate surgical guides and provisional restorations layer-by-layer from specialty acrylate resins.
- Milling Machines:CNC subtractive units carve definitive restorations from ceramic or hybrid blocks.
- Dental Lasers:Soft and hard tissue ablation systems enable minimally invasive procedures.
- Imaging Systems:Cone beam computed tomography and panoramic radiography equipment provide volumetric diagnostic data.
Intraoral scanners absorb the bulk of installed capacity; 3D printers are expanding most quickly as photopolymerization overtakes milling for single-unit crowns.
Technology:
Cost tier differentiation separates premium integrated platforms from modular point solutions.
- Optical:Structured light and confocal scanning technologies dominate intraoral geometry capture. Nordic markets show particular concentration here as Planmeca leverages vertical control over imaging, software, and fabrication hardware to anchor clinic-level digital workflows.
- Artificial Intelligence:Machine vision algorithms automate margin detection and treatment planning with FDA-cleared diagnostic features. The FDA's De Novo pathway accelerates commercialization timelines for these software-enabled platforms, reducing technician labor hours per restoration.
- Ultrasonic:Piezoelectric systems enable precise hard tissue preparation.
- Laser:Erbium and diode wavelengths address soft tissue management and caries removal.
- Digital Radiography:Solid-state sensors replace film-based imaging with immediate image availability.
- Augmented Reality:Overlay visualization guides implant placement and orthodontic treatment planning.
Optical technology commands the deepest installed base; artificial intelligence is climbing the fastest as regulatory pathways streamline algorithm deployment.
Application:
Volume concentration tracks toward high-frequency, repeatable procedures that justify capital equipment amortization.
- Prosthodontics:Crown, bridge, and implant restoration workflows generate the highest equipment utilization rates. Large dental service organizations in the United States deploy chairside production systems at satellite locations to eliminate shipping logistics and capture margin pools previously flowing to external laboratories.
- Orthodontics:Clear aligner therapy and indirect bonding drive scanner adoption for digital model generation. Corporate dentistry platforms in Mumbai and Bangalore lack this infrastructure despite accelerating patient volume growth, creating expansion opportunity.
- Endodontics:Three-dimensional imaging guides complex canal morphology assessment.
- Oral Surgery:Surgical guide fabrication and implant placement planning integrate optical and radiographic datasets.
- Periodontics:Soft tissue laser applications and regenerative procedure planning.
- Cosmetic Procedures:Veneer design and smile simulation software.
Prosthodontics claims the largest share of equipment deployment; orthodontics is gaining share fastest as aligner therapy expands beyond specialty practices.
End User:
Customer type determines purchasing process complexity and service contract structure.
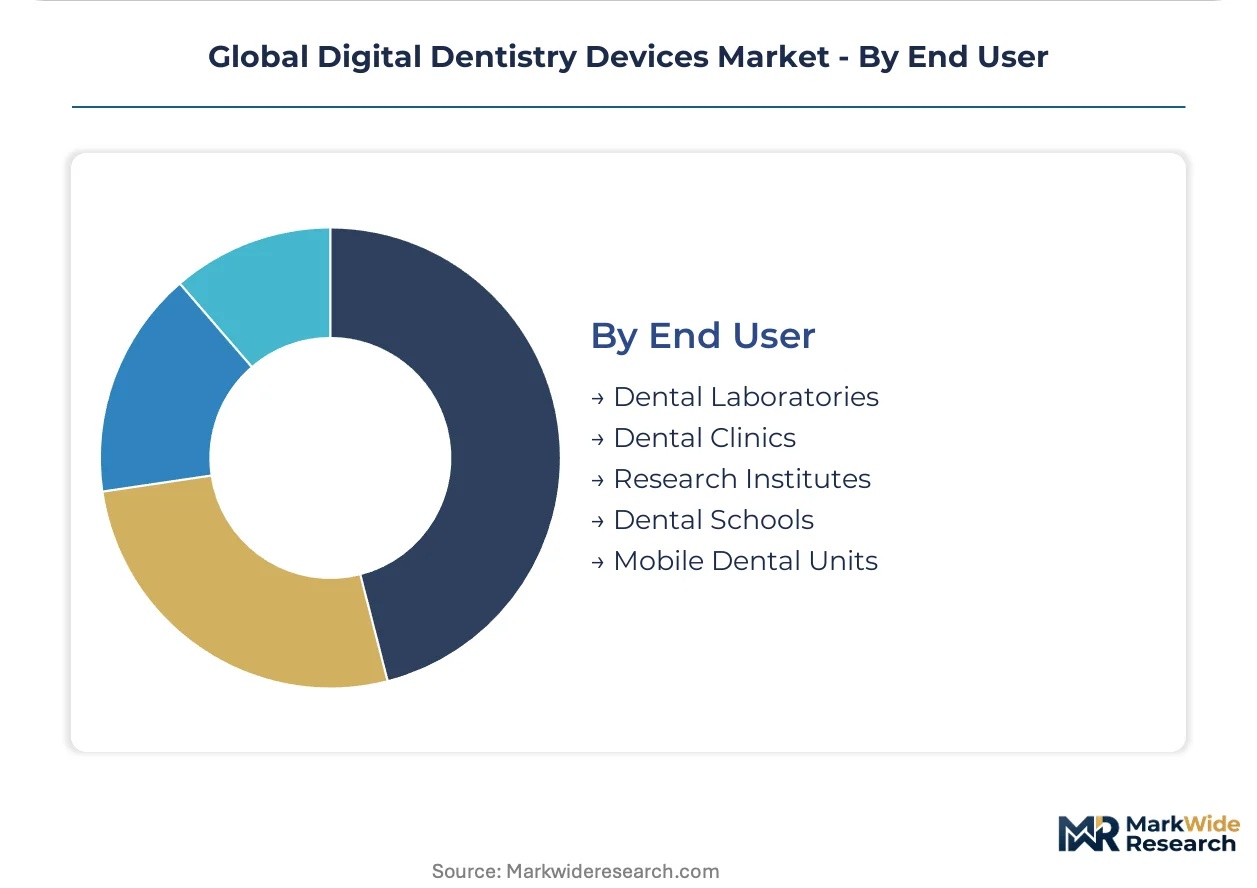
- Dental Clinics:Chairside manufacturing adoption compresses production-delivery cycles and elevates capital intensity at the point of care. Japan's METI subsidy programs lower effective equipment costs for independent practitioners transitioning to these digital systems.
- Dental Laboratories:Centralized production facilities face margin pressure from distributed clinic-level fabrication. ISO 13485 certification requirements shape supplier qualification as auditing backlogs at notified bodies delay vendor diversification efforts.
- Research Institutes:Academic and clinical research settings drive technology validation.
- Dental Schools:Training institutions face insufficient graduating operators proficient in three-dimensional design software for immediate chairside deployment.
- Mobile Dental Units:Portable care delivery platforms require ruggedized, compact equipment configurations.
Dental clinics account for the majority of new equipment orders; dental laboratories are restructuring fastest as outsourcing volumes decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters around Biberach and Leinfelden-Echterdingen supply ceramic blanks and optical components that anchor digital dentistry hardware production. Specialty acrylate monomers from concentrated European chemical producers feed additive fabrication systems worldwide.
United States
Private equity-backed dental groups in the southeastern United States consolidate purchasing authority across expanding geographic footprints. The FDA's 510(k) clearance pathway streamlines software-enabled device commercialization. Large dental service organizations deploy chairside production systems at satellite locations to eliminate shipping logistics.
Germany
Dental clinics in Baden-Württemberg accelerate chairside CAD/CAM adoption to capture margin pools previously flowing to external laboratories. The EU Medical Device Regulation imposes stricter clinical evidence requirements for CE marking of active implantable accessories. Manufacturers in Leinfelden-Echterdingen expand regulatory affairs headcount to manage technical documentation burdens.
Japan
Independent practitioners in Tokyo and Osaka transition to digital systems as patient volume growth justifies capital equipment amortization. METI subsidy programs lower effective equipment costs for SME technology adoption. Kanto region clinics integrate optical scanning with cone beam computed tomography for fully guided implantology.
India
Corporate dentistry platforms in Mumbai and Bangalore lack digital workflow infrastructure despite accelerating patient volume growth. The Central Drugs Standard Control Organization governs medical device registration with evolving classification frameworks. ISO 13485 certification shapes supplier qualification as laboratory chains seek vendor diversification.
Switzerland
Precision manufacturing traditions in the Basel-Zurich corridor support high-accuracy electromechanical system production. Swissmedic maintains rigorous quality standards for active implantable accessories that exceed baseline CE marking requirements. Dental technology clusters leverage vertical control over imaging, software, and fabrication hardware.
Global Digital Dentistry Devices Market Competitive Landscape
Global majors compete with regional champions across integrated platform versus modular point-solution positioning. The vendor base organizes around three tiers: full-stack hardware-software integrators, open-architecture software specialists, and component-focused equipment fabricators. Consolidation accelerates as regulatory compliance burdens favor scaled quality management systems. Dominant competitive moves include strategic partnerships between scanner manufacturers and third-party mill vendors, plus backward integration into consumable resin and ceramic blank production.
Within the integrated platform tier, Dentsply Sirona and Planmeca occupy positions as archetypal full-stack vendors combining imaging, software, and fabrication hardware. 3Shape exemplifies the open-architecture specialist model, while Straumann Group sits within the implant-focused ecosystem anchor category. These three companies represent contrasting strategic postures: captive vertical integration versus interoperability maximization versus therapeutic-area concentration.
| Leading Market Players |
|---|
| Planmeca |
| Straumann Group |
| Dentsply Sirona |
| Ivoclar Vivadent |
| Zimmer Biomet |
| Align Technology |
| 3Shape |
| Carestream Dental |
| Envista Holdings |
| Others |
Supply & Pricing Matrix
Corporate dental chains consolidating purchasing authority across the southeastern United States are demanding unbundled hardware pricing with transparent software licensing terms, forcing vendors to restructure service contracts and compress margins on entry-level scanner configurations.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier vendors from economy competitors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification grade and after-sales service intensity. Cost compression in the economy tier is intensifying because private equity-backed clinic chains negotiate enterprise licenses that commoditize base hardware. Dental laboratories exhibit highest price sensitivity due to margin pressure from distributed chairside manufacturing.
Supply Chain Analysis
ISO 13485 certification gates supplier qualification for ceramic blank and optical component vendors. Manufacturing concentrates in Germany, Switzerland, and Japan for precision electromechanical systems. Specialty acrylate monomers for photopolymerization draw from concentrated European chemical producers. Single-source vulnerability in photopolymer resin supply creates exposure to feedstock volatility. Distribution runs through authorized dealer networks serving clinic chains and independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photopolymerization additive manufacturing is displacing subtractive milling as the dominant fabrication modality, compressing production-delivery cycles and restructuring equipment procurement priorities across dental service organizations.
For Market Incumbents: Hedge against open-architecture software competitors by deepening backward integration into consumable resin and ceramic blank production. Capture margin pools through captive supply of proprietary materials. Accelerate regulatory affairs investment to manage EU MDR documentation burdens that favor scaled quality management systems. For New Entrants and Emerging Players: The price-point gap between premium integrated platforms and economy intraoral scanners opens opportunity in India's underpenetrated corporate dentistry chains. Target Mumbai and Bangalore clinic platforms lacking digital workflow infrastructure. Pursue METI subsidy-aligned distribution partnerships for Japanese independent practitioner segments. For Investors and Strategic Acquirers: The window for entry favors software developers with FDA-cleared AI diagnostic algorithms and lean quality management systems. Five-to-ten year viability hinges on regulatory compliance scalability rather than hardware manufacturing depth. Monitor FDA De Novo pathway clearance velocity as inflection indicator for algorithm commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Software-enabled diagnostic features accelerate market entry under streamlined clearance pathways. |
| CE Marking Pathway | EU MDR clinical evidence requirements favor manufacturers with dedicated regulatory affairs capacity. |
| Hospital System Partnership | Large dental service organizations consolidate procurement authority across expanding geographic footprints. |
| Software Companion Development | AI-enabled margin detection algorithms reduce technician labor hours per restoration. |
| Reimbursement Strategy | Integration with practice management systems determines enterprise software license penetration. |
Research Methodology
Multi-period observation of intraoral scanner shipment volumes, software license renewals, and photopolymer resin consumption anchored the trend analysis, supplemented by interviews with dental clinic procurement directors, biomedical engineers at hospital systems, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, ISO 13485 certification registries, and customs records for ceramic blank and optical component trade flows. Bottom-up equipment deployment counts triangulated against top-down vendor revenue estimates.
Input-output matrices mapped scanner adoption rates to milling machine and 3D printer installed base expansion across the projection horizon. Segmentation dimensions modeled include product type, technology tier, clinical application, and end-user configuration. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns. Forecast inputs incorporated METI subsidy program uptake rates and private equity dental group formation velocity.
Underlying measurement precision varies by segment; intraoral scanner volumes carry tighter precision than AI software licensing due to disclosed shipment data availability. Forecasts reflect assumptions regarding regulatory pathway efficiency and resin supply stability. A model refresh is warranted upon material change in FDA guidance on AI-enabled diagnostic features.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Intrauterine Devices Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Skull Clamp Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
IV Equipment Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Spectacle Lens Market
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Global Advanced Bipolar Direct Energy Device Market
Medical Devices
UK Artificial Organs and Bionic Implants Market