
 Global Artificial Pancreas Device System Market | 2026-2036
Global Artificial Pancreas Device System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Pancreas Device System Market Foresight
Swiss manufacturing capacity for precision insulin pump components is fragmenting as multiple vendors establish dedicated production lines for closed-loop systems. Medtronic plc anchors North American supply through vertically integrated sensor-pump manufacturing in California and Puerto Rico. Tandem Diabetes Care, Inc. competes on algorithm agility, releasing control software updates that differentiate its hybrid closed-loop platform. Dexcom, Inc. dominates continuous glucose sensing substrate production, supplying OEM partners and direct-to-consumer channels simultaneously.
An artificial pancreas device system constitutes an integrated therapeutic platform combining continuous glucose monitoring sensors, algorithm-driven insulin pumps, and wireless communication modules to automate glycemic management without sustained patient intervention. The system maintains target blood glucose ranges through predictive control algorithms processing sensor data at intervals under five minutes, primarily serving insulin-dependent diabetes populations requiring reduced hypoglycemic exposure and overnight glucose stability. Hybrid closed-loop configurations currently occupy the largest installed base among device types, while fully closed-loop systems represent the fastest-growing category as algorithm reliability improves and regulatory pathways mature. Sensor-augmented pump segments sustain significant volume in price-sensitive markets, though margin pools concentrate in platforms integrating proprietary continuous glucose monitoring with predictive low glucose suspend functionality.
FDA premarket approval requirements under the breakthrough devices program shape United States market access timelines, while EMA medical device regulation and CE marking obligations govern European commercialization pathways. Japan's PMDA reviews software-as-medical-device components under distinct consultation procedures, creating multi-track regulatory complexity for algorithm-heavy platforms. Stakeholders must monitor evolving reimbursement parity between integrated artificial pancreas systems and standalone continuous glucose monitoring across national health technology assessment frameworks.
Market Dynamics
Algorithmic control software is compressing product refresh cycles across artificial pancreas platforms, forcing hardware manufacturers to decouple sensor-pump lifecycles from software update cadences. This structural shift rewards vendors with modular architectures over vertically integrated legacy stacks.
Growth Catalysts
- FDA Breakthrough Devices Program:Accelerated premarket review timelines for hybrid closed-loop submissions compress commercialization pathways by 12-18 months versus standard PMA routes.
- Continuous Glucose Monitoring integration mandates:Germany's G-BA reimbursement parity rulings between standalone CGM and integrated artificial pancreas systems eliminate cost barriers for insulin-dependent populations.
- Predictive low glucose suspend algorithms:Machine learning models processing sub-five-minute sensor intervals reduce nocturnal hypoglycemic events, expanding addressable populations to pediatric and elderly diabetes cohorts previously excluded from pump therapy.
Market Restraints
- Precision component supply concentration:Swiss MEMS foundries and California-based sensor substrate manufacturers control critical insulin pump valve and glucose oxidase electrode supply, creating single-source vulnerability.
- Software validation burden:FDA premarket submission requirements for algorithm-as-medical-device components impose documentation costs exceeding hardware development expenditures for mid-cap entrants.
- Reimbursement fragmentation:Japan's PMDA software consultation procedures and MHLW pricing negotiations operate on asynchronous timelines, delaying commercial launches by 24-36 months post-CE marking.
Strategic Opportunities
- Underpenetrated Type 2 insulin-dependent segments:Brazil's ANVISA fast-track pathway for closed-loop systems in non-intensive care settings opens addressable populations fivefold larger than Type 1 diabetes prevalence.
- Dual-hormone platform convergence:Glucagon micro-pump integration with existing insulin delivery hardware creates fully automated glycemic control without patient carbohydrate counting.
- Remote patient monitoring reimbursement codes:United States CMS transitional care management billing incentives for algorithm-adjusted insulin dosing shift provider economics toward proactive glucose management models.
Industry Challenges
- Control systems engineering talent scarcity:Predictive algorithm development requires specialized expertise in biomedical signal processing and stochastic model predictive control, functions concentrated at MIT, Stanford, and ETH Zurich research clusters.
- Legacy electronic health record integration friction:Hospital IT departments face API incompatibility between proprietary closed-loop data formats and Epic, Cerner, and Meditech glucose management modules.
- Biocompatibility certification timelines:ISO 10993 extended implant duration studies for 14-day wear sensors delay product launches by 18-24 months regardless of algorithm readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Pancreas Device System Market |
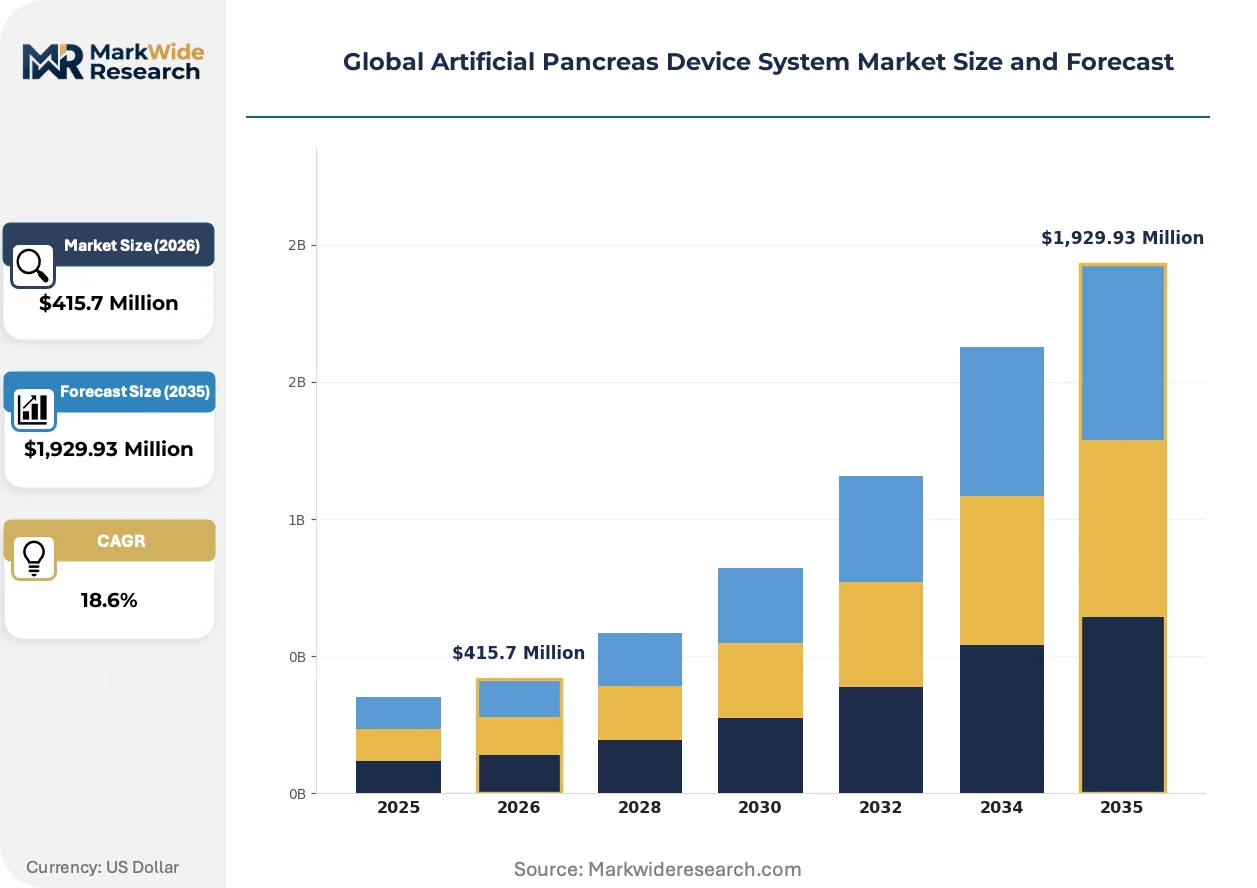
| Market Size in 2026 | $415.7 Million |
| Market Size in 2035 | $1,929.93 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Sensor-Augmented Pump, Hybrid Closed Loop, Predictive Low Glucose Suspend, Fully Closed Loop Technology: Continuous Glucose Monitoring, Insulin Pump, Control Algorithm, Wireless Communication, Bluetooth Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pediatric Diabetes End User: Diabetes Clinics, Endocrinologists, Ambulatory Care, Home Care, Diabetes Educators |
| Companies Covered | Medtronic plc, Tandem Diabetes Care, Inc., Insulet Corporation, Dexcom, Inc., Abbott Laboratories, Beta Bionics, Inc., Ypsomed, Roche Diabetes Care, Pancreum, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Pancreas Device System Market Shifts & Advancements
Cloud-native algorithm deployment is severing hardware-software coupling in artificial pancreas architectures, enabling real-time model updates without device replacement. This shift compresses competitive differentiation cycles from years to quarters.
Edge computing architectures embedded directly within insulin pump microcontrollers are digitizing glucose prediction workflows, eliminating latency from smartphone or cloud relay. Adolescent diabetes clinics in Denmark and the Netherlands are piloting these systems for hypoglycemic unawareness populations. The technology is digitizing regulatory submission strategies, with FDA now accepting over-the-air update protocols as premarket change control plans rather than supplemental PMA requirements.
EMA Medical Device Regulation Article 10.4 post-market surveillance obligations are mandating algorithm performance transparency through EUDAMED registration of predictive accuracy metrics by glucose range. Manufacturers must now disclose false positive hypoglycemic alert rates in public-facing technical documentation. Smaller vendors without established quality management systems are outsourcing post-market clinical follow-up to specialized CROs in Ireland and Switzerland, fragmenting value capture from device sales to service contracts.
Direct-to-consumer subscription models for sensor-pump consumables are displacing traditional durable medical equipment distribution through hospital-based diabetes educators. Endocrinology practices in Texas and Florida are unbundling device training from ongoing algorithm optimization, shifting margin pools to telehealth platforms. This channel reconfiguration is most visible in United States commercial insurance markets where employer-sponsored plans favor predictable per-member-per-month costs over capital equipment purchases.
Global Artificial Pancreas Device System Market Segmentation
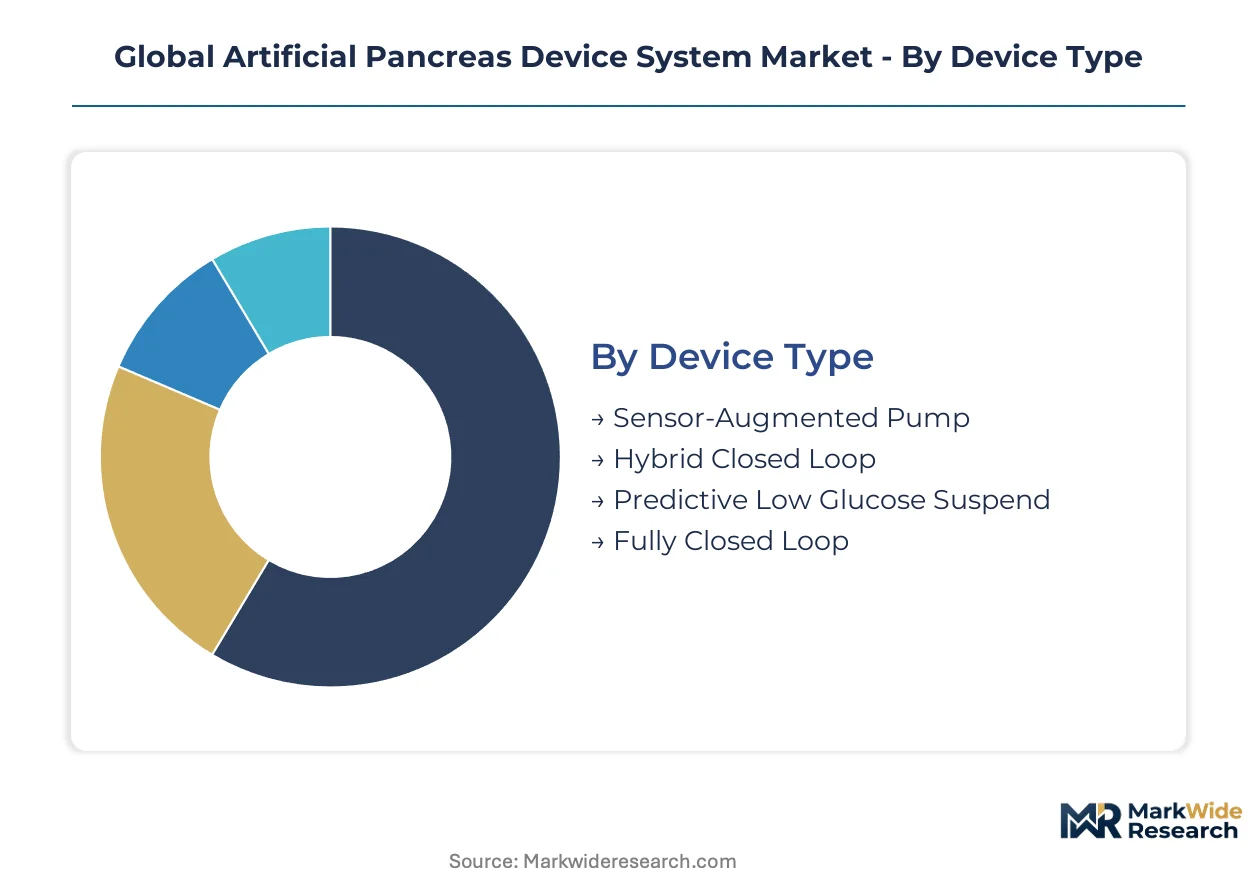
Artificial pancreas platforms fragment across multiple technical and clinical dimensions, each commanding distinct regulatory pathways and margin structures. Understanding these segment boundaries reveals where algorithm innovation outpaces hardware commoditization and which patient populations unlock premium pricing.
Device Type:
Mature configurations dominate installed base economics while emerging architectures reset competitive benchmarks for automation fidelity.
- Hybrid Closed Loop:Combines automated basal insulin modulation with patient-initiated bolus dosing, requiring manual carbohydrate input for meal events. Demand concentrates in Germany and the United States where reimbursement frameworks cover integrated CGM-pump platforms; algorithm reliability improvements are compressing patient intervention burdens toward fully automated alternatives.
- Fully Closed Loop:Eliminates meal announcement requirements through predictive glucose trajectory modeling and adaptive learning for unannounced carbohydrate intake. Pediatric diabetes centers in Denmark and the Netherlands are piloting these systems for hypoglycemic unawareness populations; regulatory maturation in FDA breakthrough and EMA adaptive pathways is accelerating commercial timelines.
- Sensor-Augmented Pump:Provides CGM data display without automated insulin adjustment, serving price-sensitive markets and transition populations.
- Predictive Low Glucose Suspend:Interrupts insulin delivery ahead of predicted hypoglycemic events, occupying a middle automation tier with lower documentation burden for mid-cap entrants.
Hybrid Closed Loop retains volume leadership; Fully Closed Loop holds the steepest expansion curve.
Technology:
Cost tier stratification separates proprietary integrated stacks from modular commodity components.
- Continuous Glucose Monitoring:Electrochemical sensors measuring interstitial glucose via glucose oxidase electrodes with factory-calibrated algorithms, representing the highest-value capture layer in system architecture. Dexcom and Abbott manufacturing concentration in California and Illinois creates supply vulnerability for OEM partners.
- Control Algorithm:Model predictive control and machine learning frameworks processing sub-five-minute sensor intervals to forecast glucose trajectories and calculate insulin dosing. FDA software-as-medical-device validation requirements impose documentation costs exceeding hardware development for algorithm-heavy submissions.
- Insulin Pump:Precision micro-mechanical delivery systems with MEMS-actuated valves, sourced from Swiss foundries and vertically integrated California facilities.
- Wireless Communication:Proprietary radio protocols and Bluetooth Low Energy stacks enabling sensor-pump-smartphone data triangulation.
- Bluetooth:Standardized connectivity layer for patient-facing mobile applications and cloud telemetry relay.
Continuous Glucose Monitoring commands the dominant margin pool; Control Algorithm is climbing the fastest as software decouples from hardware refresh cycles.
Application:
Customer type stratification separates intensive insulin users from expanding addressable populations previously excluded from pump therapy.
- Type 1 Diabetes:Autoimmune destruction of pancreatic beta cells requiring exogenous insulin for survival, representing the historical core market with established reimbursement pathways and clinical evidence bases for closed-loop outcomes.
- Type 2 Diabetes:Insulin-dependent subpopulations with progressive beta-cell failure, fivefold larger prevalence than Type 1; Brazil's ANVISA fast-track pathway for non-intensive care settings is opening trial populations.
- Pediatric Diabetes:Cohorts under 18 years requiring overnight glucose stability and reduced caregiver intervention; predictive algorithms are expanding inclusion criteria previously limited by hypoglycemic risk tolerance.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring tight glycemic targets with minimal pharmacologic exposure, served by temporary closed-loop rentals in Nordic hospital systems.
Type 1 Diabetes retains volume leadership; Type 2 Diabetes holds the steepest expansion curve.
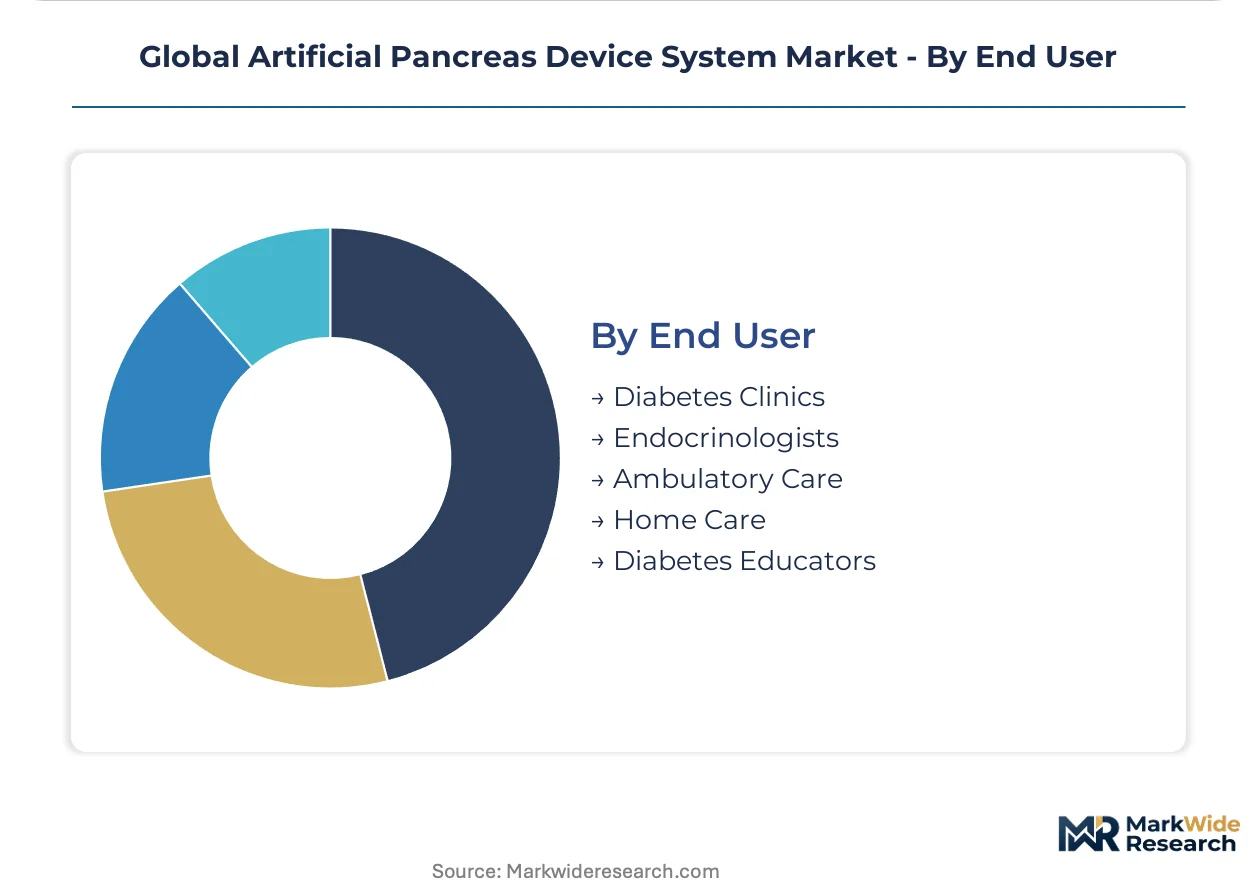
End User:
Geography concentration in reimbursement-advanced markets determines channel economics and training burden allocation.
- Home Care:Direct-to-consumer and telehealth-supported self-management, displacing hospital-based diabetes educator distribution in United States commercial insurance markets favoring per-member-per-month cost predictability.
- Diabetes Clinics:Specialized centers with certified diabetes care and education specialists providing device training and algorithm optimization, capturing ongoing service revenue as hardware margins compress.
- Endocrinologists:Physician practices prescribing and managing closed-loop therapy with EHR integration requirements creating friction with proprietary data formats.
- Ambulatory Care:Hospital outpatient departments transitioning patients from acute settings to closed-loop management under transitional care management billing incentives.
- Diabetes Educators:Independent training providers unbundling device onboarding from ongoing algorithm support, shifting margin pools to subscription telehealth platforms in Texas and Florida.
Home Care retains volume leadership; Diabetes Clinics holds the steepest expansion curve as service revenue displaces equipment sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiss MEMS foundries and California sensor substrate manufacturers control critical insulin pump valve and glucose oxidase electrode supply, creating geographic concentration that shapes regional market access. Demand clusters in jurisdictions with advanced reimbursement frameworks for continuous glucose monitoring integration.
United States
FDA breakthrough device designations compress pre-market review timelines by 12-18 months versus standard PMA routes. CMS transitional care management billing incentives reward algorithm-adjusted insulin dosing in Texas and Florida endocrinology practices. Medtronic anchors North American supply through vertically integrated sensor-pump manufacturing in California and Puerto Rico.
Germany
G-BA reimbursement parity rulings between standalone CGM and integrated artificial pancreas systems eliminate cost barriers for insulin-dependent populations. EMA medical device regulation and CE marking obligations govern European commercialization pathways for hybrid closed-loop submissions. Diabetes clinics in Bavaria and North Rhine-Westphalia expand adoption of closed-loop insulin delivery platforms.
Japan
PMDA reviews software-as-medical-device components under distinct consultation procedures, creating multi-track regulatory complexity for algorithm-heavy platforms. MHLW pricing negotiations operate on asynchronous timelines, delaying commercial launches. Tokyo-based research clusters concentrate control systems engineering talent for predictive algorithm development.
Denmark
Pediatric diabetes centers pilot fully closed-loop systems for hypoglycemic unawareness populations through predictive glucose trajectory modeling. Nordic hospital systems deploy temporary closed-loop rentals for gestational diabetes management. Edge computing architectures embedded within insulin pump microcontrollers undergo clinical validation in Copenhagen and Aarhus.
Brazil
ANVISA fast-track pathway for closed-loop systems in non-intensive care settings opens addressable populations fivefold larger than Type 1 diabetes prevalence. Type 2 insulin-dependent segments represent underpenetrated expansion opportunity. São Paulo and Rio de Janeiro diabetes clinics drive initial adoption of sensor-augmented pump platforms.
Global Artificial Pancreas Device System Market Competitive Landscape
Vertically integrated conglomerates and modular algorithm specialists split the market between captive supply chains and software-decoupled architectures. Consolidation concentrates in sensor substrate and precision pump component layers, while application software remains fragmented. Two strategic archetypes dominate: manufacturers with in-house CGM-pump integration and vendors licensing algorithm control to third-party hardware. Dominant competitive moves include backward integration into MEMS foundry capacity and cloud-native algorithm deployment severing hardware-refresh dependencies.
Among North American device manufacturers, Medtronic plc and Tandem Diabetes Care, Inc. exemplify contrasting architectural approaches to closed-loop platform development. Dexcom, Inc. occupies a position as the dominant continuous glucose sensing substrate supplier, simultaneously serving OEM partnerships and direct-to-consumer channels. These three entities anchor the competitive structure through their respective control over hardware integration, algorithm agility, and sensor manufacturing concentration.
| Leading Market Players |
|---|
| Medtronic plc |
| Tandem Diabetes Care, Inc. |
| Insulet Corporation |
| Dexcom, Inc. |
| Abbott Laboratories |
| Beta Bionics, Inc. |
| Ypsomed |
| Roche Diabetes Care |
| Pancreum, Inc. |
| Others |
Supply & Pricing Matrix
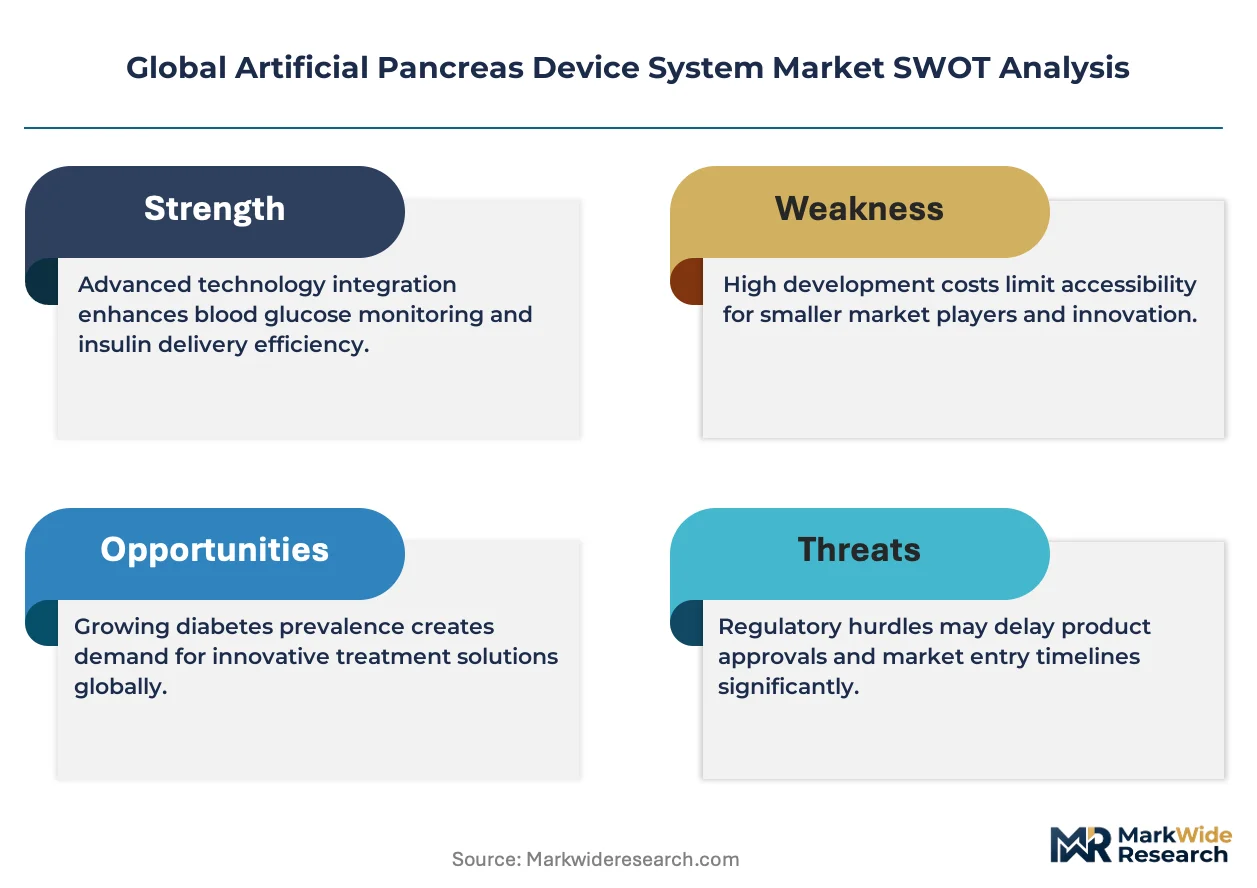
Single-source dependency on Swiss MEMS foundries for precision insulin pump valves determines both three-tier pricing stratification across premium, standard, and economy levels and the geographic clustering of component manufacturing. FDA premarket approval timelines and EMA CE marking obligations impose regulatory cost burdens that compress margins in mid-tier sensor-augmented pump segments while algorithm-integrated platforms command premium positioning.
Pricing Analysis
FDA breakthrough device designation dictates the pricing tier structure by accelerating market access for hybrid closed-loop systems that bundle proprietary continuous glucose monitoring with predictive algorithms. Pricing stratifies across premium, standard, and economy tiers based on automation fidelity and reimbursement certification grade, with integrated closed-loop platforms capturing premium positioning against sensor-augmented alternatives. Cost compression in standard-tier pump hardware is intensifying because modular software architectures decouple algorithm value from device replacement cycles. Home care direct-to-consumer channels exhibit highest price sensitivity, while pediatric diabetes clinics demonstrate lowest sensitivity due to reimbursement parity mandates in Germany and the United States.
Supply Chain Analysis
Glucose oxidase electrode substrates and MEMS-actuated pump valves feed from concentrated manufacturing bases in Switzerland, California, and Illinois. Raw material dependencies center on electrochemical sensor membranes, precision micro-mechanical components, and biocompatible polymers for 14-day wear applications. Single-source vulnerability at Swiss foundries creates supply chain risk should export controls or capacity constraints emerge. Distribution runs through hospital-based diabetes educator networks in reimbursement-advanced markets and direct-to-consumer subscription platforms in United States commercial insurance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in artificial pancreas systems are reaching an inflection as cloud-native algorithm deployment severs hardware-software coupling, enabling ecosystem interoperability that rewards modular architectures over vertically integrated legacy stacks.
For Market Incumbents: Pre-empt modular algorithm specialists by accelerating backward integration into Swiss MEMS foundry capacity and securing captive supply of glucose oxidase electrode substrates. Defensive consolidation through in-house production of precision pump components counters emerging entrants licensing control software to third-party hardware manufacturers. Channel control via direct-to-consumer subscription models for sensor-pump consumables protects margin pools as hospital-based distribution erodes.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's Type 2 insulin-dependent segments through ANVISA fast-track pathway submissions for non-intensive care closed-loop deployments. Target gestational diabetes temporary rental programs in Nordic hospital systems as a white-space application with lower regulatory documentation burden. A software-as-medical-device go-to-market angle bypasses hardware certification timelines while capturing algorithm service revenue.
For Investors and Strategic Acquirers: FDA software-as-medical-device premarket guidance reshapes the acquisition landscape by elevating algorithm validation capabilities above hardware manufacturing scale. Long-term viability across the projection horizon favors targets with stochastic model predictive control expertise and cloud-native deployment infrastructure. Acquisition target archetype: modular algorithm vendors with established quality management systems and EUDAMED registration capabilities. The signal to watch is CMS transitional care management billing code expansion for algorithm-adjusted insulin dosing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses commercialization timelines by 12-18 months versus standard PMA routes. |
| Cloud-Native Algorithm Deployment | Over-the-air update protocols accepted as premarket change control plans eliminate hardware refresh dependencies. |
| Swiss MEMS Foundry Backward Integration | Captive supply of precision insulin pump valves insulates against single-source vulnerability in critical components. |
| Dual-Hormone Platform Convergence | Glucagon micro-pump integration with existing insulin delivery hardware creates fully automated glycemic control. |
| CMS Reimbursement Strategy | Transitional care management billing incentives shift provider economics toward proactive glucose management models. |
Research Methodology
A spread of perspectives from endocrinology practice administrators, biomedical engineers at closed-loop platform developers, hospital GPO contracts managers, and regulatory affairs specialists at algorithm-heavy submissions converged on the working assumptions. Primary interview insights combined with secondary validation against FDA 510(k) and PMA filings, EMA EUDAMED registration databases, CMS Medicare reimbursement codes, and Japan PMDA consultation procedure records. Bottom-up demand modeling across patient population segments triangulated with top-down market sizing from device shipment estimates.
Demand-supply balance framing anchored the analytical framework across the modeling period, with installed base growth, replacement cycles, and new patient starts modeled separately. Segmentation dimensions included device automation tier, glucose sensing technology, diabetes type, patient age cohort, and regional reimbursement pathway. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in continuous glucose monitoring and insulin pump markets. Forecast inputs incorporated algorithm reliability improvement trajectories and regulatory pathway maturation timelines.
Stress conditions across Swiss MEMS foundry capacity constraints, FDA software validation documentation burden escalation, and Japan MHLW pricing negotiation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding reimbursement parity expansion and algorithm performance transparency mandates. Cross-checking against hospital procurement database trends and GPO contract award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Root Canal Irrigators Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Oxygen Conserving Devices Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Global Retinoscopes Market
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
Engine-Driven Endodontic File Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Self-Injections Market
Medical Devices
Carpal Tunnel Release Systems Market
Medical Devices
Global Breast Implants Market
Medical Devices
Cranial Clamps Market
Medical Devices
Europe Otoscope Market
Medical Devices
Medical Laser Cutting Device Market