
 Organic Electronics Market | 2026-2036
Organic Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Electronics Market Intelligence
The shift from rigid consumer electronics toward flexible applications in medical diagnostics and automotive systems is rebalancing the end-user portfolio. LG Display leverages its manufacturing scale in large-format OLED display panels. In contrast, Merck KGaA differentiates through its specialized portfolio of high-purity organic semiconductor materials. Covestro AG competes by supplying advanced polymer films crucial for flexible device substrates, positioning itself within the material supply chain.
Organic electronics utilize carbon-based polymers or small molecules as the active semiconductor layer in electronic devices. Their primary advantage is solution processability, enabling fabrication on flexible substrates like plastic. This technology facilitates the creation of lightweight and conformable electronic components. Organic Light Emitting Diodes (OLEDs) for display panels remain the largest product segment by value. However, applications in energy harvesting, using organic photovoltaics and sensors, are expanding due to their unique form factors.
Regulatory frameworks such as the EU’s RoHS and REACH directives, alongside EPA guidelines in the United States, influence material selection and end-of-life management. These standards compel manufacturers to reduce hazardous substances in electronic components, favoring certain organic materials. The central challenge for component designers and material suppliers is to advance device performance and operational lifetime without compromising on environmental compliance or cost targets.
Market Dynamics
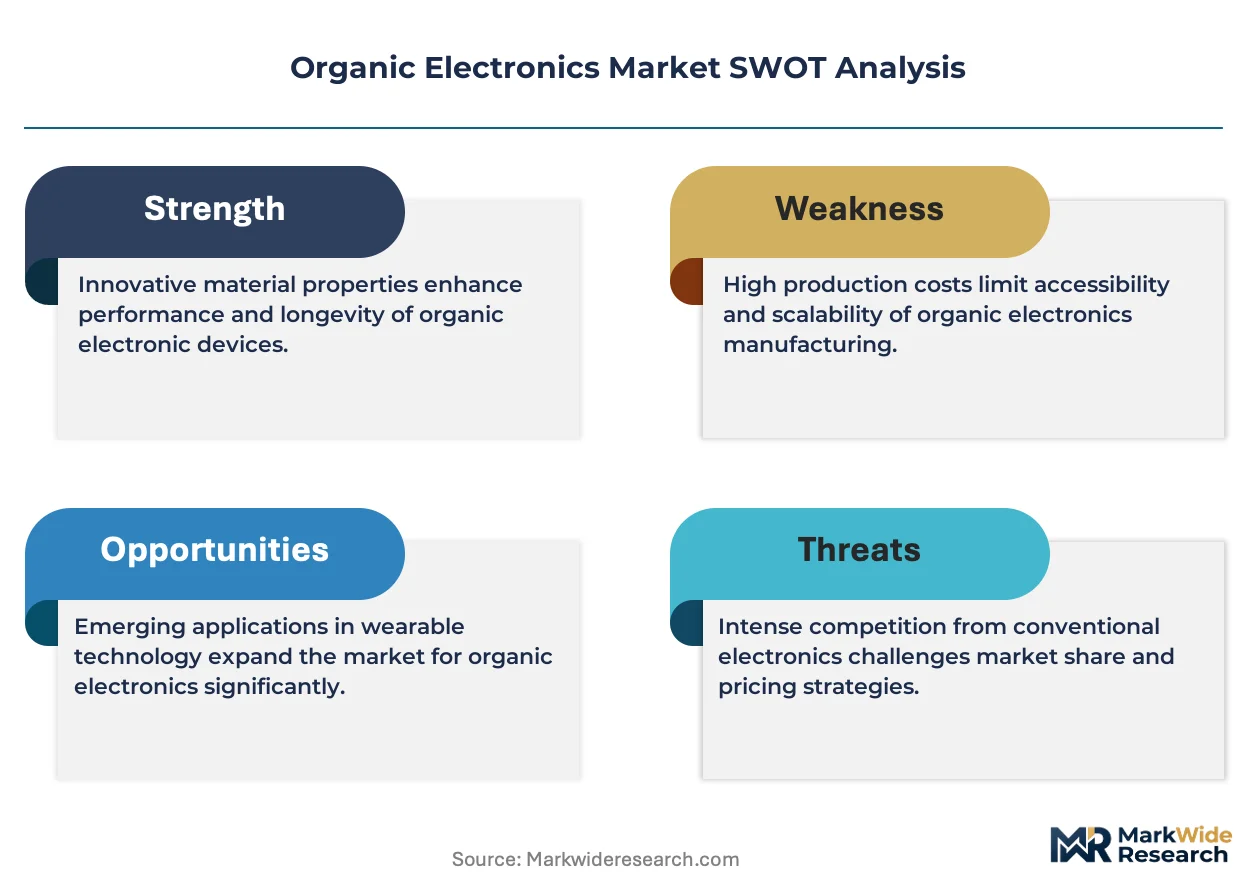
The central dynamic is the rebalancing of R&D investment between mature OLED display applications and emerging flexible electronics. This shift is driven by demand for new form factors in automotive and medical sectors, challenging established material performance-cost tradeoffs.
Growth Catalysts
- Material Innovation:Advancements in solution-processable, high-mobility organic semiconductor materials are enabling faster, more efficient transistors for next-generation flexible displays and sensor arrays.
- Wearable Device Demand:The proliferation of smartwatches, fitness trackers, and flexible medical sensors creates sustained demand for lightweight, conformable, and power-efficient organic electronic components.
- Industrial Concentration:South Korea's dominant position in display panel manufacturing, supported by government R&D incentives, creates a concentrated ecosystem that accelerates material development and adoption cycles.
Market Restraints
- Operational Lifetime:Many organic materials exhibit limited operational stability when exposed to oxygen and moisture, requiring complex and costly encapsulation techniques that hinder cost-competitiveness against silicon.
- Material Purification Costs:Achieving the high purity required for reliable semiconductor performance involves multi-step synthesis and purification processes, contributing significantly to the final device cost.
- Environmental Compliance:Navigating complex substance regulations like the EU’s REACH directive for certain solvents and precursors used in synthesis adds significant compliance overhead and material qualification time.
Strategic Opportunities
- Implantable Biosensors:The biocompatibility of certain organic polymers presents an opportunity to develop flexible, implantable sensors for continuous medical monitoring, a market less sensitive to cost than consumer electronics.
- Printed Electronics for IoT:Converging low-cost organic printing techniques with the massive sensor deployment needs of the Internet of Things (IoT) opens avenues for ubiquitous, disposable smart labels and environmental sensors.
- Circular Economy Mandates:European Union directives promoting device repairability and material recycling favor organic electronics, which offer potential for disassembly and material recovery compared to complex inorganic assemblies.
Industry Challenges
- Performance Metrology:A lack of standardized testing protocols for carrier mobility and device lifetime across different labs and manufacturers complicates material selection for component designers and slows down qualification.
- Process Scalability:Translating lab-scale synthesis and solution-based deposition processes to high-volume, high-yield roll-to-roll manufacturing presents significant chemical engineering and equipment challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Electronics Market |
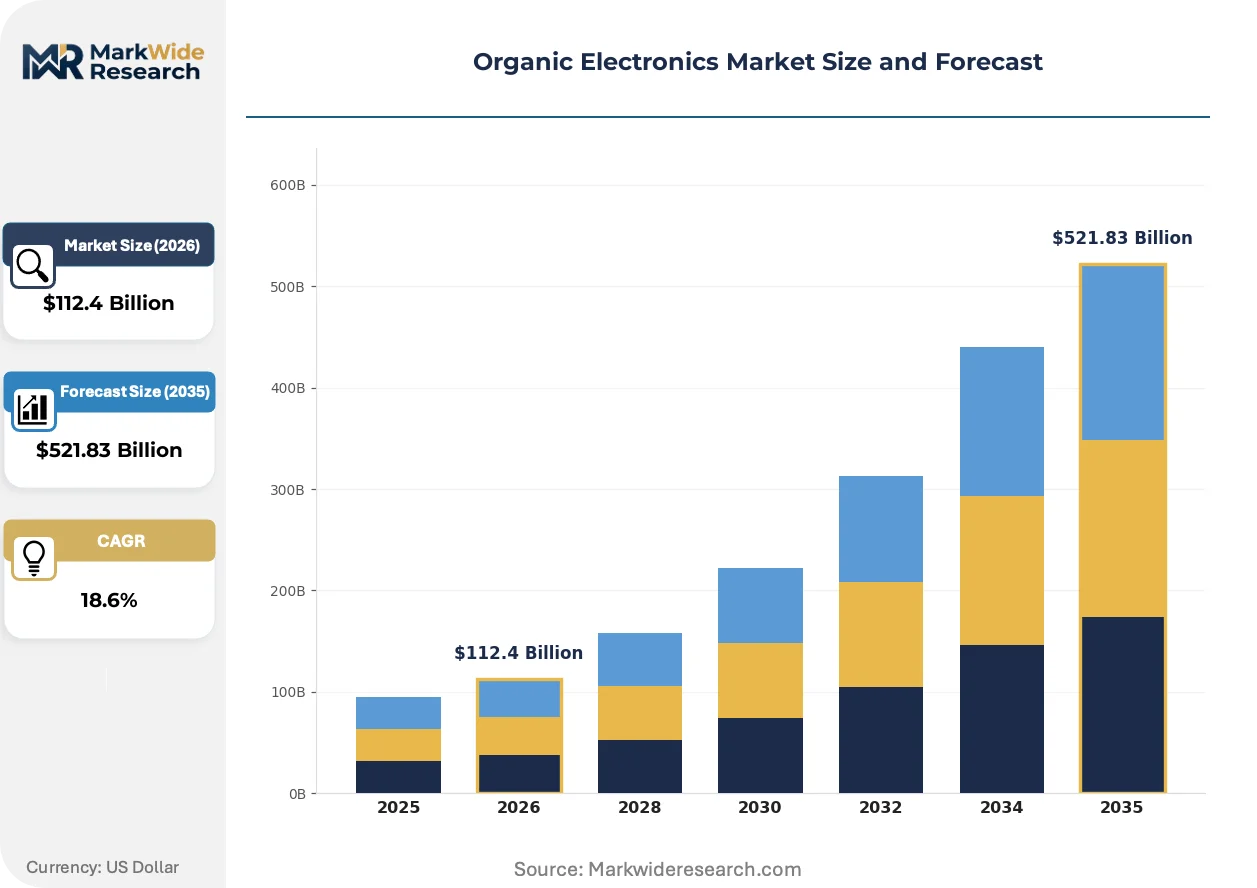
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $521.83 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Light Emitting Diodes, Organic Photovoltaics, Organic Thin-Film Transistors, Organic Sensors, Organic Solar Cells Technology: Polymer Electronics, Small Molecule Electronics, Printed Electronics, Flexible Electronics, Hybrid Organic Electronics Application: Display Panels, Wearable Devices, Lighting Solutions, Energy Harvesting, Medical Diagnostics End User: Consumer Electronics Manufacturers, Medical Equipment Developers, Defense Contractors, Textile Innovators, Automotive Tier-1 Suppliers |
| Companies Covered | LG Display, Evonik Industries AG, Merck KGaA, Covestro AG, Sumitomo Chemical, BASF SE, DuPont, Universal Display Corporation, Samsung Display, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Electronics Market Strategic Shifts & Innovations
A fundamental shift from component-level performance to system-level integration is underway. Material science breakthroughs now intersect with sustainability mandates and new user interface demands, creating novel product categories beyond traditional displays.
Thermally Activated Delayed Fluorescence (TADF) materials are organic emitters achieving high internal quantum efficiency without heavy metals like iridium. Display panel manufacturers are integrating TADF emitters, particularly for blue pixels, to improve energy efficiency. This innovation is rewriting the cost-performance equation for OLED panels, reducing reliance on supply-constrained noble metals.
China's "dual carbon" goals and policies supporting its domestic semiconductor supply chain are influencing material development. These initiatives incentivize local research and production of high-performance organic electronic materials to reduce import dependency. The domestic photovoltaic and display sectors are primary beneficiaries, with increased investment in organic solar cell and OLED material production.
End-product manufacturers in automotive and medical devices are shifting from procuring discrete components to co-developing integrated flexible electronic systems. This collaborative model disrupts the traditional tiered supplier relationship, requiring material companies to have deeper systems engineering expertise. The trend is most visible in Germany's automotive sector with integrated organic lighting and sensor films.
Organic Electronics Market Segmentation
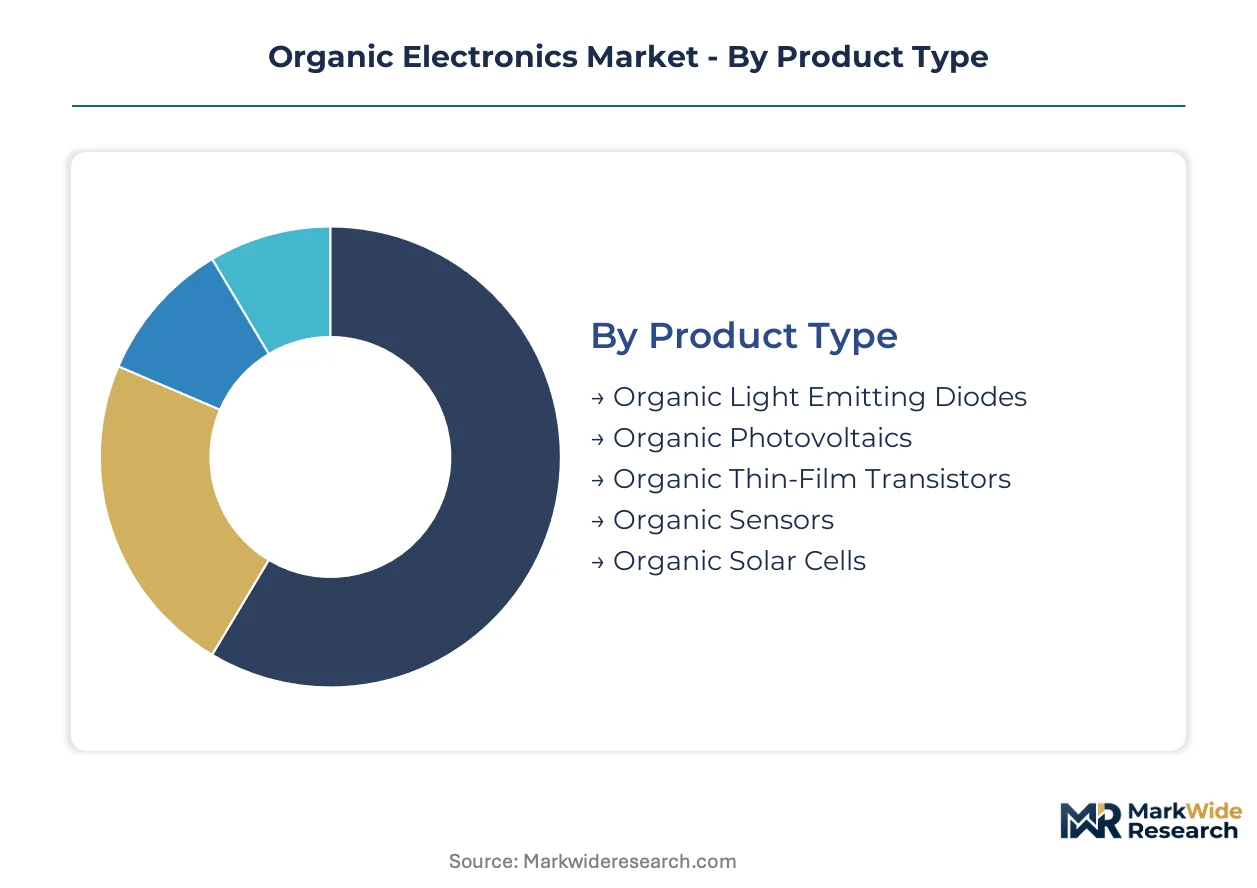
Understanding the Organic Electronics Market through segmentation clarifies where capital investments yield optimal returns and where technological advancements are driving new product categories. This breakdown reveals the distinct material science requirements and market dynamics across various applications and end-user groups.
Product Type:
Capital intensity varies significantly across product types, with display manufacturing requiring substantial upfront investment in fabrication facilities and specialized equipment.
- Organic Light Emitting Diodes:These utilize carbon-based materials to emit light when current passes through them, forming the active layers in displays. Demand concentrates in South Korea due to its dominant display panel industry, driving advancements in energy-efficient blue pixel emitters.
- Organic Photovoltaics:These devices convert light into electricity using organic semiconductor materials, offering flexibility and transparency. Demand is accelerating in Germany for building-integrated photovoltaics, driven by renewable energy mandates.
- Organic Thin-Film Transistors:These components serve as switches or amplifiers in flexible electronic circuits.
- Organic Sensors:These devices detect physical or chemical changes, often integrated into flexible substrates for medical and environmental monitoring.
- Organic Solar Cells:These are a specific type of organic photovoltaic, primarily focused on solar energy conversion.
Organic Light Emitting Diodes absorb the bulk of installed capacity; Organic Photovoltaics are expanding most quickly.
Technology:
The choice of underlying technology influences process scalability and material purity requirements, directly impacting manufacturing costs.
- Flexible Electronics:This technology enables devices to bend, fold, or stretch without compromising function, utilizing plastic or textile substrates. Demand for flexible electronics is accelerating in the US for medical sensors and wearable devices, driven by patient comfort and portability.
- Printed Electronics:This approach uses printing methods to deposit active organic materials onto substrates, enabling low-cost, high-volume manufacturing. Demand is concentrating in China for smart packaging and IoT tags, incentivized by domestic supply chain goals.
- Polymer Electronics:This segment utilizes long-chain organic molecules as semiconductor materials, offering solution processability.
- Small Molecule Electronics:This technology employs discrete organic molecules, often requiring vacuum deposition for high-performance devices.
- Hybrid Organic Electronics:These integrate organic and inorganic materials to combine their respective advantages, enhancing device performance.
Flexible Electronics represent the largest segment by adoption; Printed Electronics are gaining share fastest.
Application:
Diverse applications require tailored material properties, from display brightness to sensor sensitivity, influencing research and development priorities.
- Display Panels:Organic electronics form the active emissive layers in OLED displays for smartphones, televisions, and monitors. Demand in South Korea remains dominant for large-format OLED display panels, leveraging existing manufacturing infrastructure.
- Wearable Devices:This application integrates organic electronic components into smartwatches, fitness trackers, and flexible medical patches. Demand is high across Europe for continuous health monitoring, enabled by lightweight and conformable designs.
- Lighting Solutions:Organic Light Emitting Diodes offer diffuse, energy-efficient illumination for general lighting and automotive interiors.
- Energy Harvesting:Organic photovoltaics and thermoelectric generators capture ambient energy for low-power electronics.
- Medical Diagnostics:Flexible organic sensors and bioelectronics enable non-invasive and implantable diagnostic tools.
Display Panels command the highest market value; Wearable Devices show the steepest expansion trajectory.
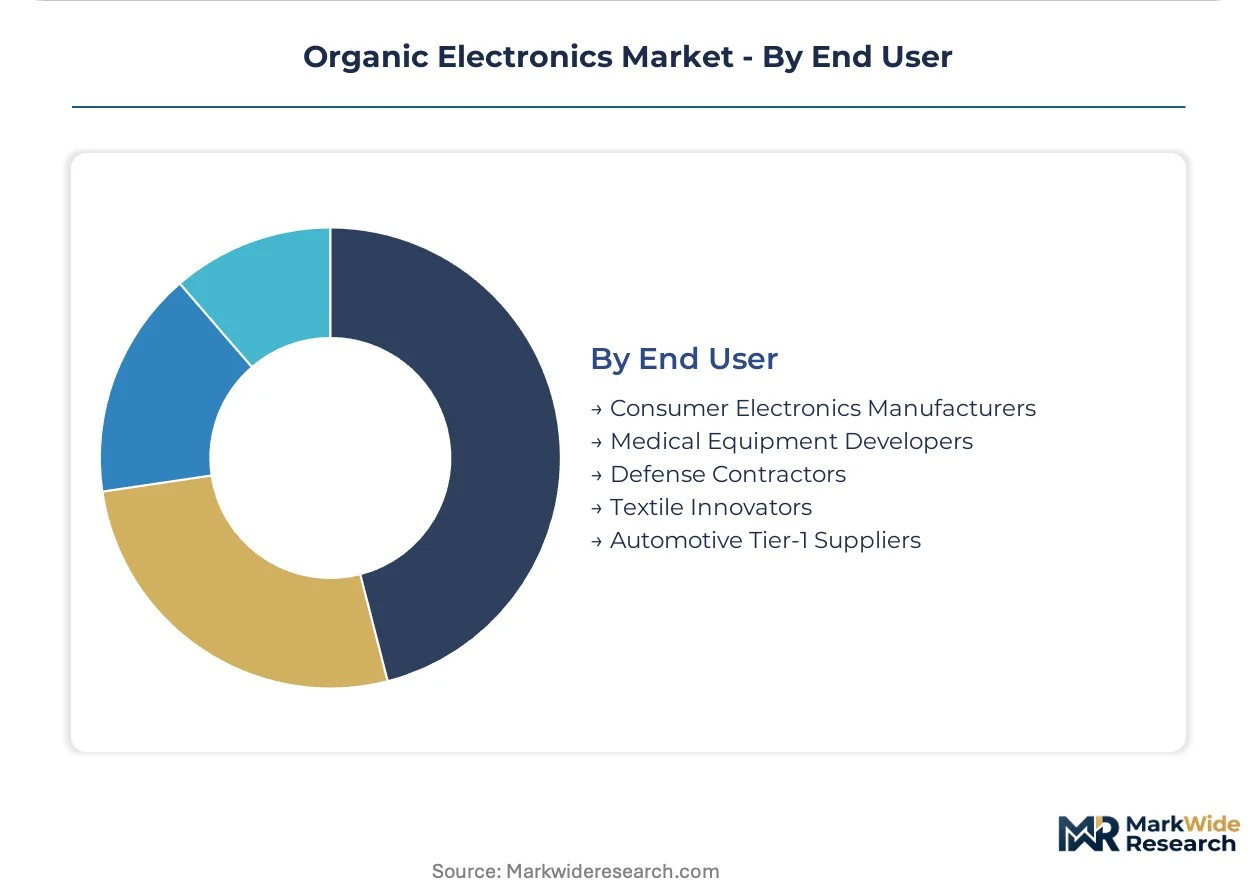
End User:
End-user segments dictate product specifications, regulatory compliance, and supply chain integration models for organic electronic components.
- Consumer Electronics Manufacturers:These companies integrate organic displays, sensors, and flexible components into smartphones, tablets, and smart home devices. Demand is concentrated in China, driven by a large domestic market and government incentives for local production.
- Automotive Tier-1 Suppliers:These firms incorporate flexible OLED lighting, transparent displays, and integrated sensor films into vehicle interiors and exteriors. Demand is strong in Germany, where co-development models with material companies are prevalent for advanced systems.
- Medical Equipment Developers:These entities utilize biocompatible organic sensors and flexible electronics for diagnostic and therapeutic devices.
- Defense Contractors:This sector integrates ruggedized flexible displays and sensors into military communication and surveillance systems.
- Textile Innovators:This segment embeds organic electronic elements into smart fabrics for performance monitoring and interactive apparel.
Consumer Electronics Manufacturers represent the largest purchasing segment; Automotive Tier-1 Suppliers are exhibiting rapid growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's concentrated display panel ecosystem, supported by significant R&D incentives, drives much of the organic electronics market. This strategic focus accelerates material development and adoption cycles across the region. Other nations also leverage specific policy frameworks to foster growth in this specialized sector.
South Korea
South Korea's display panel industry creates sustained demand for advanced organic light-emitting diodes and related materials. Government R&D incentives, alongside local manufacturing policies, foster a robust ecosystem for organic electronics innovation. The Seoul Capital Area concentrates much of the world's large-format OLED display panel manufacturing and material development.
Germany
Germany experiences strong demand for organic photovoltaics, driven by renewable energy mandates and a robust automotive sector. The EU Green Deal and national policies incentivize the development of sustainable energy solutions and advanced vehicle components. Bavaria and Baden-Württemberg are centers for integrated organic lighting and sensor film co-development with automotive Tier-1 suppliers.
United States
The United States sees significant demand for flexible electronics in medical sensors and wearable devices. EPA guidelines influence material selection, while HIPAA regulations shape the development of medical diagnostic tools. California's technology hubs, alongside Boston's biotech corridor, specialize in flexible, implantable biosensor research and production.
China
China's large domestic market and smart packaging initiatives generate substantial demand for printed electronics and IoT tags. The nation's "dual carbon" goals and policies supporting its domestic semiconductor supply chain incentivize local material development. The Yangtze River Delta region is a key hub for high-volume consumer electronics manufacturing and organic solar cell production.
Organic Electronics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments of the organic electronics market. The landscape features vertically integrated display manufacturers alongside specialized material science companies and advanced polymer film suppliers. Strategic archetypes include large-scale component producers, niche material innovators, and substrate technology providers. Companies engage in significant R&D investment and form strategic partnerships to advance device performance and operational lifetime.
Specialized material developers like Germany-based Merck KGaA and Covestro AG (a German AG) occupy positions focused on high-purity organic semiconductor materials and advanced polymer films, respectively. These firms exemplify the critical role of material science innovation in the organic electronics sector. In contrast, South Korea's LG Display, a large-scale manufacturer, anchors the display panel segment, leveraging its extensive production capabilities for large-format OLEDs. These players represent distinct approaches to market participation, from upstream material supply to integrated component manufacturing.
| Leading Market Players |
|---|
| LG Display |
| Evonik Industries AG |
| Merck KGaA |
| Covestro AG |
| Sumitomo Chemical |
| BASF SE |
| DuPont |
| Universal Display Corporation |
| Samsung Display |
| Others |
Cost & Logistics Intelligence
EU’s RoHS and REACH directives, alongside EPA guidelines, compel manufacturers to reduce hazardous substances in electronic components. This regulatory pressure drives material suppliers to invest in compliant organic semiconductor development, influencing component pricing.
Pricing Analysis
Assured supply of high-purity organic semiconductor materials often commands a premium for specialized applications through contract-based long-term offtake, contrasting with more transactional pricing for standard OLED precursors. Price differentiation stems from material purity, specific certification levels required for medical devices, and customization for unique form factors. Pricing pressure stems from the need to compete against established inorganic semiconductor technologies, particularly in cost-sensitive consumer electronics. Medical equipment developers show less price sensitivity compared to consumer electronics manufacturers, prioritizing performance and biocompatibility.
Supply Chain Analysis
China's "dual carbon" goals and policies supporting its domestic semiconductor supply chain are reshaping sourcing preferences for organic electronic materials. Supply concentration centers on South Korea for display panel components, Germany for advanced automotive films, and China for printed electronics and organic solar cell precursors. The industry draws from specialized high-purity organic semiconductor materials and advanced polymer films, often with complex synthesis requirements, creating single-source vulnerability. Distribution runs primarily through direct sales channels from material science companies to integrated device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Organic Electronics Market is consolidating, driven by high material purification costs that challenge smaller players and favor vertically integrated specialists. This market demands significant capital investment and specialized expertise, leading to a natural selection process.
For Market Incumbents: Anticipate continued pressure from silicon-based alternatives by investing heavily in next-generation material science. Deepen R&D into thermally activated delayed fluorescence (TADF) materials to improve display energy efficiency and reduce reliance on noble metals. Pursue strategic partnerships for process scalability, particularly in high-volume roll-to-roll manufacturing, to overcome current cost disadvantages. Strengthen intellectual property portfolios around stable, high-mobility organic semiconductors to maintain competitive differentiation.
For New Entrants and Emerging Players: Medical equipment developers represent an underserved buyer archetype, seeking flexible and biocompatible solutions for implantable biosensors. Target this segment by developing specialized organic polymers for continuous health monitoring, where cost sensitivity is lower. Leverage low-cost organic printing techniques to address the massive sensor deployment needs of the Internet of Things (IoT). Focus go-to-market strategies on demonstrating unique form factors and long-term stability for niche medical and industrial applications.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term value creation in specialized material science. Target niche material innovators with robust intellectual property in high-purity organic semiconductor synthesis or advanced polymer films. Focus on companies addressing operational lifetime challenges and environmental compliance, critical for sustained growth over the next decade. The signal to watch is the widespread adoption of standardized testing protocols for carrier mobility and device lifetime, indicating market maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for OLEDs | LG Display expands production capabilities to meet growing demand for large-format display panels. |
| Backward Integration into Material Synthesis | Merck KGaA secures its supply chain for high-purity organic semiconductor precursors. |
| Joint Venture for Flexible Sensor Development | Medical equipment developers partner to integrate organic sensors into new diagnostic devices. |
| Technology Licensing for TADF Emitters | Display panel manufacturers gain access to energy-efficient organic light-emitting diode technology. |
| Green Manufacturing Transition | Covestro AG adopts sustainable processes for polymer film production, aligning with EU directives. |
Research Approach
Document review covered academic journals, patent databases, and company annual reports, complemented by interviews with R&D directors and material scientists. Primary research involved discussions with product managers and procurement leads at leading organic electronics manufacturers and material suppliers. Secondary data sources included EPA guidelines, REACH directives, and EU Green Deal reports. This approach facilitated bottom-up and top-down triangulation for market sizing and trend analysis.
The quantitative model generated market size and growth projections across the analysis window, integrating historical performance and technological adoption curves. Segmentation dimensions modeled included product type, technology, application, end-user, and regional R&D investment. Compound Annual Growth Rates were derived from projected market values and volumes over the forecast period. Key industry-specific forecast inputs included material innovation timelines and manufacturing process scalability.
Revisions become necessary when significant shifts in regulatory frameworks, unforeseen material science breakthroughs, or geopolitical disruptions to supply chains materialize. Forecasts reflect assumptions regarding operational lifetime improvements and process scalability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
High Reliability Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Global Organic Semiconductor Market
Semiconductors
North America Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
IV-IV Compound Semiconductor Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Asia Pacific Flash Memory Market
Semiconductors
United States Discrete Semiconductors Market
Semiconductors
Semiconductor in Military and Aerospace Market