
 Power Electronics Market | 2026-2036
Power Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Power Electronics Market Analysis
Software-defined gate control is recalibrating how power electronics vendors monetize hardware, shifting revenue toward firmware subscriptions and predictive maintenance contracts. Infineon Technologies AG leverages its SiC fabrication depth to anchor premium pricing in automotive traction systems. STMicroelectronics competes through integrated module packaging that reduces thermal management overhead for industrial motor drives.
Power electronics encompasses solid-state devices that convert, switch, and condition electrical energy using semiconductor materials operating at frequencies from line-level to megahertz ranges, with voltage ratings spanning tens of volts to tens of kilovolts depending on application. These systems serve as the critical interface between raw electrical sources and end-use loads, enabling variable-speed motor control, grid-tied inverters, and DC fast-charging infrastructure. Silicon Carbide technology is capturing margin pools in electric vehicle inverters where efficiency gains justify material cost premiums over conventional silicon. The Converters segment sustains volume leadership across renewable energy installations and uninterruptible power supplies, while Gallium Nitride devices are penetrating consumer electronics adapters and telecom rectifiers where power density requirements dominate.
The EPA sets efficiency benchmarks for industrial motor systems under its motor standards program, while the EU Green Deal and F-Gas Regulation constrain refrigerant-based cooling in power-dense installations, pushing thermal design toward liquid-cooled SiC modules. China's MIIT enforces GB standards for EV charging equipment that mandate domestic semiconductor content thresholds. Stakeholders must weigh material transition timelines against certification costs as wide-bandgap substrates redefine performance benchmarks and supply chain sourcing requirements.
Market Dynamics
Wide-bandgap semiconductor migration is compressing incumbent silicon margins while redistributing value capture toward substrate fabricators and module packagers with thermal management expertise.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates are forcing industrial drive manufacturers toward liquid-cooled SiC architectures that eliminate conventional cooling hardware.
- EV traction inverters:Electric vehicle platforms above 800V architecture require SiC MOSFETs to minimize switching losses during rapid charging cycles.
- China's coastal clusters:Shenzhen and Suzhou manufacturing corridors concentrate demand for renewable energy converters and grid-tied inverters serving domestic solar installations.
Market Restraints
- Substrate supply concentration:6-inch SiC wafer production clusters in specific Asian manufacturing zones create single-source vulnerability for automotive qualification programs.
- Technical limitation:Gate oxide reliability in GaN HEMTs remains unresolved for automotive-grade mission profiles exceeding 15-year operational life.
- Regulatory friction:China's GB standards for EV charging equipment impose domestic content thresholds that fragment procurement for multinational OEMs.
Strategic Opportunities
- India's industrial motor retrofits:Bureau of Energy Efficiency mandates for IE4 efficiency classes create replacement demand for variable-frequency drives in textile and cement plants.
- Software-defined gate control:Firmware-over-the-air updates enable recurring revenue streams from predictive thermal monitoring in wind turbine converters.
- Aviation electrification:More Electric Aircraft programs require 270V DC distribution systems that favor SiC-based solid-state power controllers over electromechanical alternatives.
Industry Challenges
- Power electronics talent scarcity:Electromagnetic compatibility engineering and multi-physics simulation expertise concentrates among defense-aerospace contractors, constraining commercial hiring pipelines.
- Qualification timeline compression:AEC-Q101 automotive certification for wide-bandgap devices extends 18-24 months, misaligning with EV platform development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Electronics Market |
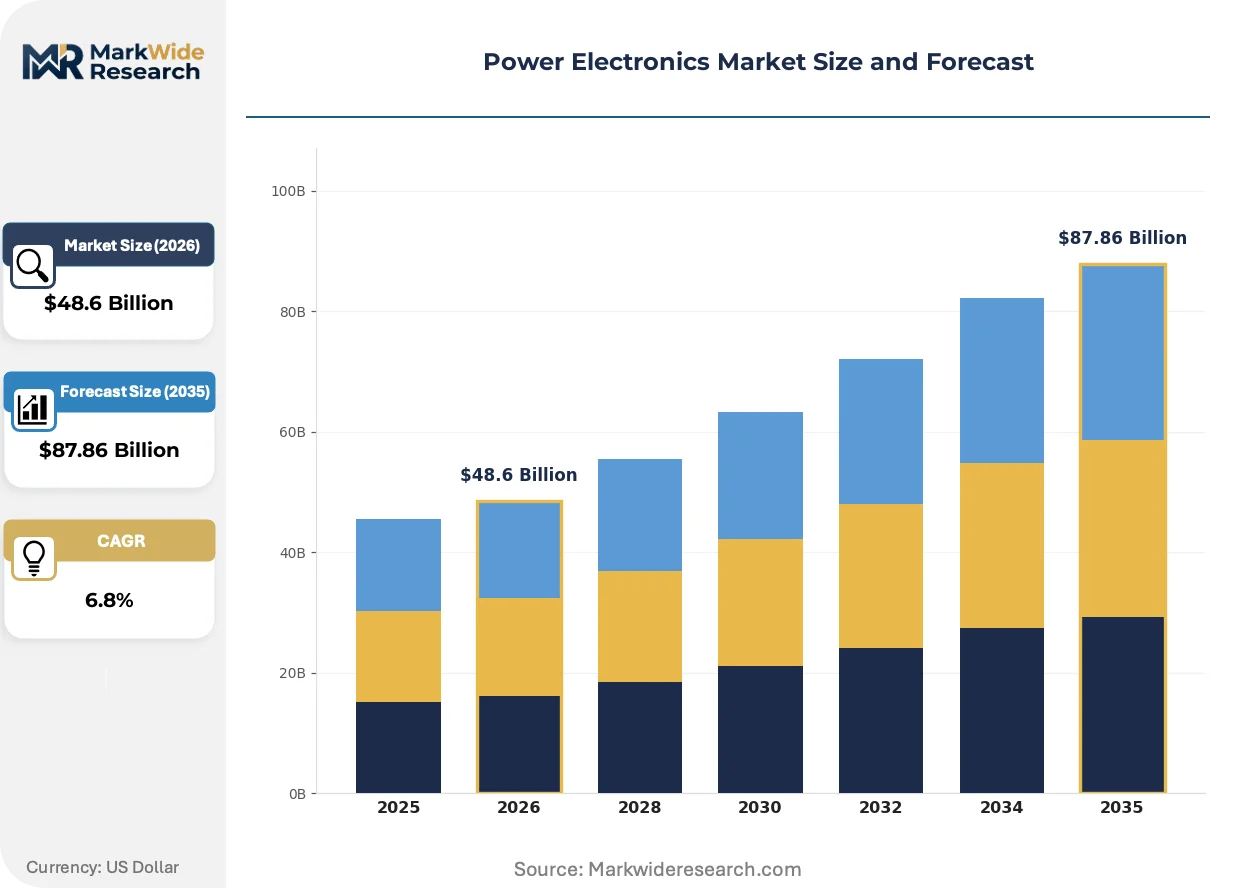
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $87.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Converters, Inverters, Switches, Controllers End User: Industrial, Automotive, Consumer Electronics, Telecommunications Technology: Silicon, Gallium Nitride, Silicon Carbide, Hybrid Application: Renewable Energy, UPS, Electric Vehicles, Robotics |
| Companies Covered | STMicroelectronics, Mitsubishi Electric Corporation, Infineon Technologies AG, Toshiba Corporation, Renesas Electronics Corporation, Texas Instruments Incorporated, Analog Devices, Inc., Fuji Electric Co., Ltd., Semiconductor Components Industries, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Electronics Market Emerging Trajectories
Silicon-to-wide-bandgap substrate transition is fragmenting established supply relationships while enabling new entrants with packaging and thermal expertise to capture margin pools previously held by integrated device manufacturers.
Silicon Carbide MOSFET technology is decentralizing inverter design authority from tier-one automotive suppliers toward OEMs with in-house powertrain engineering capabilities. Volkswagen Group and Hyundai Motor Company now specify die-level procurement rather than module-level sourcing. This shift compresses supplier margins while expanding addressable market for bare-die vendors with automotive qualification.
Europe's F-Gas Regulation and accompanying EU Green Deal efficiency mandates are eliminating refrigerant-based cooling from industrial motor drives above 75kW. Manufacturers including ABB and Siemens now specify liquid-cooled SiC modules for new variable-frequency drive platforms. German machine builders face compressed thermal design cycles as 2027 compliance deadlines approach.
Aftermarket service unbundling is fragmenting long-term maintenance contracts for wind turbine converters. Independent service providers now offer gate driver board replacement and DC-link capacitor refurbishment separate from OEM service agreements. This pattern concentrates in North American wind corridors where turbine fleets exceed 10-year operational age and original warranty periods have expired.
Power Electronics Market Segmentation
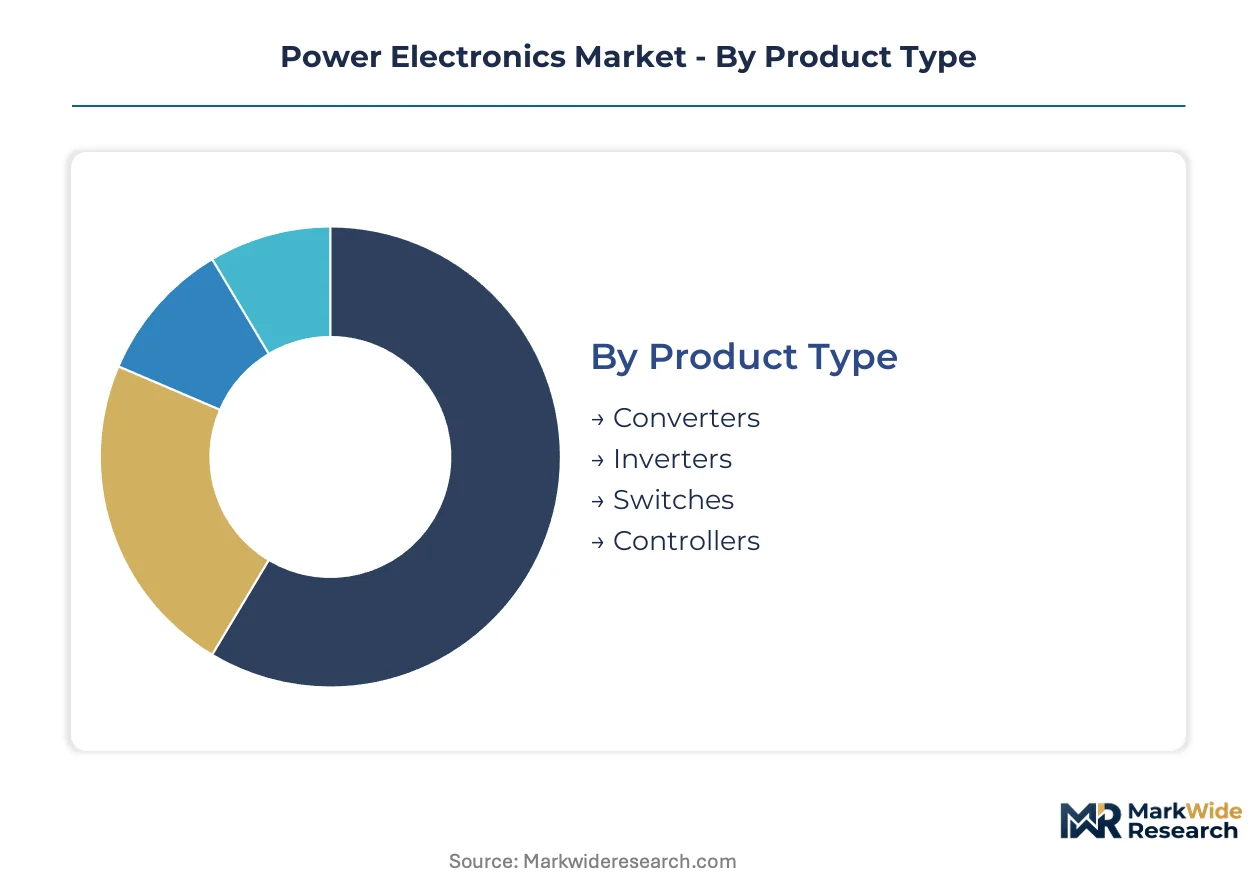
Power electronics segmentation reveals divergent technology maturities and margin structures across product architectures. Each dimension exposes distinct procurement patterns, certification requirements, and supply chain dependencies that reshape competitive positioning.
Product Type:
Converters anchor volume shipments while specialized controllers command premium pricing through firmware integration.
- Converters:AC-DC and DC-DC conversion modules process raw electrical input into conditioned output for industrial motor drives and grid-tied solar installations. Demand concentrates in China's coastal manufacturing clusters where renewable energy converter procurement aligns with domestic solar installation targets under MIIT guidance.
- Inverters:DC-to-AC conversion systems enable grid synchronization for photovoltaic arrays and variable-speed motor control. Automotive OEMs in Germany and South Korea specify 800V SiC-based traction inverters for next-generation electric vehicle platforms, displacing conventional silicon IGBT architectures.
- Switches:Solid-state switching devices including MOSFETs and IGBTs regulate power flow across voltage classes.
- Controllers:Gate driver and control logic modules manage switching sequences and protection algorithms.
Today's leader: Converters. Tomorrow's challenger: Controllers.
End User:
Automotive procurement drives SiC volume while industrial retrofits sustain silicon legacy demand.
- Industrial:Variable-frequency drives, servo systems, and uninterruptible power supplies serve manufacturing automation and process industries. India's Bureau of Energy Efficiency mandates IE4 motor efficiency classes, creating replacement demand across textile plants in Gujarat and cement facilities in Rajasthan.
- Automotive:Traction inverters, onboard chargers, and DC-DC converters for electric vehicle powertrains. Volkswagen Group and Hyundai Motor Company now specify die-level SiC procurement rather than module-level sourcing, compressing supplier margins while expanding addressable market for qualified bare-die vendors.
- Consumer Electronics:Compact adapters and charging bricks for smartphones, laptops, and portable devices.
- Telecommunications:Rectifiers and power supply units for base stations and data center infrastructure.
Industrial installations dominate current shipments. Automotive applications are climbing the fastest as 800V architectures proliferate.
Technology:
Silicon retains cost advantage at lower frequencies while wide-bandgap materials capture efficiency-critical applications.
- Silicon:Mature IGBT and MOSFET technologies manufactured on 8-inch and 12-inch wafer lines. Legacy industrial motor drives and consumer power supplies in Southeast Asian contract manufacturing sustain volume demand despite margin compression from wide-bandgap alternatives.
- Silicon Carbide:Wide-bandgap MOSFETs and Schottky diodes operating at higher temperatures and switching frequencies. EV traction inverters above 75kW now mandate SiC architectures to minimize switching losses during rapid charging cycles, with substrate supply concentration in specific Asian manufacturing zones creating qualification bottlenecks.
- Gallium Nitride:HEMT devices for high-frequency, medium-voltage applications where power density dominates.
- Hybrid:Multi-chip modules combining silicon and wide-bandgap devices for optimized cost-performance tradeoffs.
Silicon Carbide shows the steepest expansion trajectory. Hybrid configurations offer near-term bridging solutions.
Application:
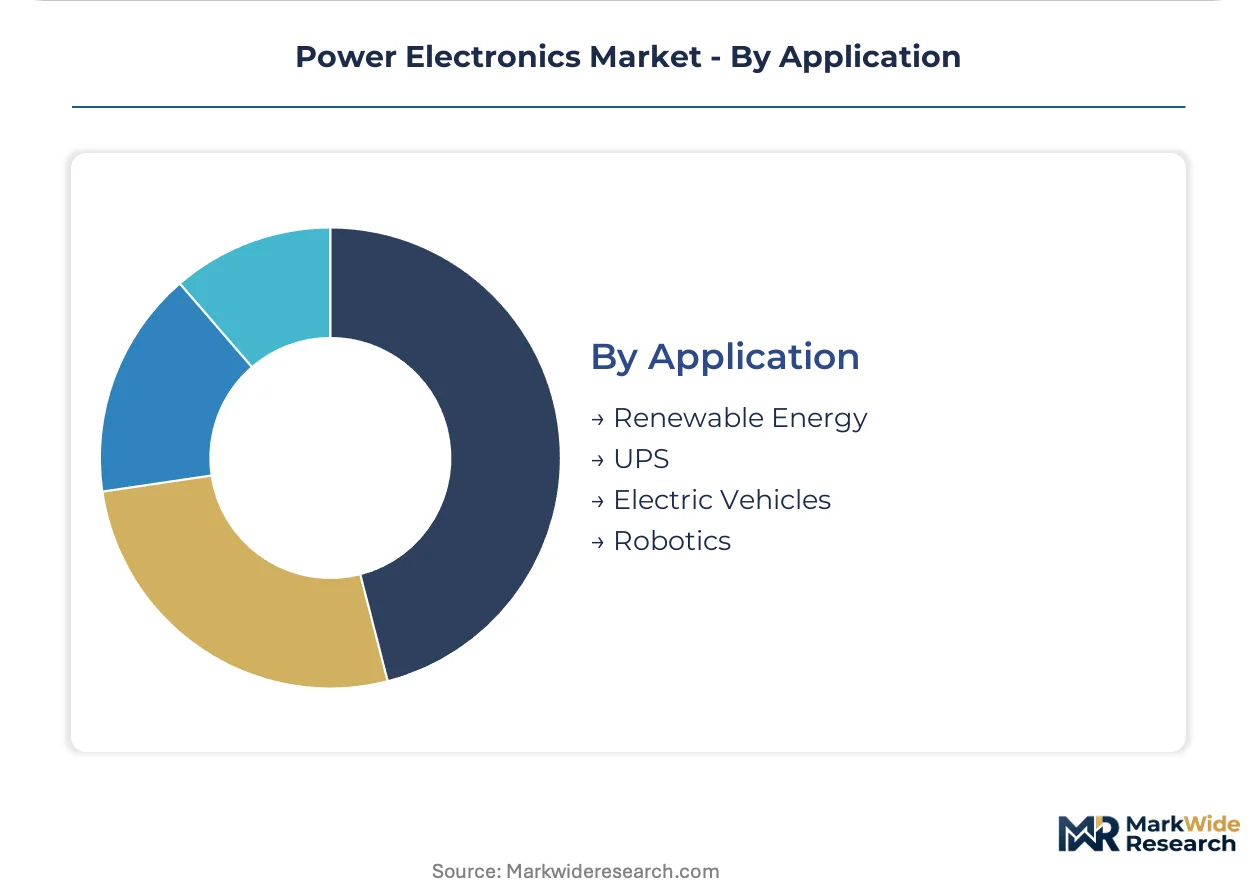
Renewable energy installations sustain converter volume while electric vehicles concentrate premium semiconductor demand.
- Renewable Energy:Grid-tied inverters and power optimizers for photovoltaic and wind turbine installations. Shenzhen and Suzhou manufacturing corridors concentrate procurement for solar converters serving domestic installation targets under China's dual carbon goals.
- Electric Vehicles:Traction inverters, onboard chargers, and battery management systems. Europe's F-Gas Regulation and EU Green Deal efficiency mandates are eliminating refrigerant-based cooling from industrial motor drives above 75kW, pushing liquid-cooled SiC module specifications from ABB and Siemens.
- UPS:Uninterruptible power supply systems for data center and critical infrastructure protection.
- Robotics:Servo drives and motor controllers for industrial automation and collaborative robot platforms.
Renewable Energy commands current volume leadership. Electric Vehicles are gaining share fastest as platform voltages rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial motor drive retrofit mandates outpace Japan's automotive SiC procurement velocity, while China's coastal manufacturing clusters absorb the largest share of renewable energy converter shipments.
China
Shenzhen and Suzhou manufacturing corridors concentrate demand for EV traction inverters and grid-tied solar converters. MIIT enforces GB standards for EV charging equipment that mandate domestic semiconductor content thresholds. The Yangtze River Delta and Pearl River Delta clusters now host the majority of wide-bandgap substrate packaging operations serving domestic renewable installation targets.
Germany
Machine builders in Bavaria and Baden-Württemberg face compressed thermal design cycles as 2027 F-Gas Regulation compliance deadlines approach. The EU Green Deal efficiency mandates eliminate refrigerant-based cooling from industrial drives above 75kW. ABB and Siemens now specify liquid-cooled SiC modules from suppliers concentrated in North Rhine-Westphalia's industrial belt.
United States
Independent service providers fragment aftermarket maintenance contracts for aging wind turbine converters across Texas and Iowa wind corridors. The EPA maintains efficiency benchmarks for industrial motor systems under its motor standards program. California's data center operators drive UPS procurement for critical infrastructure protection.
India
Textile plants in Gujarat and cement facilities in Rajasthan generate replacement demand for variable-frequency drives under Bureau of Energy Efficiency IE4 efficiency mandates. The country's PLI scheme for semiconductor manufacturing attracts packaging investment toward Maharashtra and Karnataka. Tamil Nadu's automotive component suppliers now qualify SiC die for export-bound EV powertrains.
Japan
METI guidance on industrial decarbonization accelerates SiC adoption in factory automation systems across Aichi Prefecture's automotive supplier network. Kansai region semiconductor fabricators specialize in hybrid module packaging combining silicon and wide-bandgap devices. Tokyo-based trading houses coordinate bare-die procurement for domestic OEMs developing 800V EV platforms.
Power Electronics Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device manufacturers defending position in automotive qualification programs while packaging houses capture margin in industrial thermal management. The vendor base organizes around three strategic archetypes: substrate fabricators with captive SiC crystal growth, module packagers with liquid-cooling expertise, and fabless designers licensing wide-bandgap process nodes. Consolidation pressure concentrates among tier-two silicon IGBT suppliers facing margin compression. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines extend.
Among European-based integrated device manufacturers, Infineon Technologies AG and STMicroelectronics exemplify contrasting approaches to value capture. Infineon anchors the substrate-fabricator archetype through SiC crystal growth investments. STMicroelectronics occupies a position emphasizing integrated module packaging for thermal-intensive applications. Texas Instruments Incorporated represents the analog-centric tier with process diversification across voltage classes. Each sits within distinct procurement channels: bare-die supply for OEM direct sourcing versus module-level sales through industrial distributors.
| Leading Market Players |
|---|
| STMicroelectronics |
| Mitsubishi Electric Corporation |
| Infineon Technologies AG |
| Toshiba Corporation |
| Renesas Electronics Corporation |
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| Fuji Electric Co., Ltd. |
| Semiconductor Components Industries, LLC |
| Others |
Supply Flow & Price Mechanics
6-inch SiC wafer spot indices cascade through three distinct pricing tiers for power electronics modules, with automotive-grade die commanding substantial premiums over industrial silicon alternatives due to AEC-Q101 qualification overhead and substrate supply bottlenecks concentrated in Asian manufacturing zones.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade silicon IGBTs while automotive SiC MOSFETs sustain premium positioning. Three-tier pricing structure across automotive-qualified, industrial-performance, and consumer-economy levels reflects certification grade and volume scale differentiation. Cost compression in silicon legacy tiers is intensifying because wide-bandgap substitution erodes incumbent margins. Industrial motor drive OEMs exhibit highest price sensitivity due to retrofit budget constraints, whereas EV platform engineers prioritize efficiency metrics over unit economics.
Supply Chain Analysis
Photoresist and high-purity graphite supply rests on Japanese specialty chemical producers and German industrial carbon manufacturers for SiC crystal growth equipment. Raw material flows concentrate through China, Japan, and Germany for substrate fabrication, module packaging, and thermal management components respectively. Single-source vulnerability clusters around 6-inch SiC wafer production in specific Asian manufacturing zones, creating automotive qualification bottlenecks. Distribution runs through tier-one automotive suppliers and industrial distributor networks serving OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in India's industrial motor retrofit segment, where Bureau of Energy Efficiency IE4 mandates create replacement demand at cost structures 40% below European equivalents for comparable efficiency-class drives.
For Market Incumbents: Acquire captive SiC crystal growth capacity to secure substrate supply amid 18-24 month automotive qualification timelines. Infineon Technologies AG's fabrication depth anchors premium pricing against STMicroelectronics' packaging-centric model. Defend margin position through backward integration into 6-inch wafer production rather than module-level commodity competition. For New Entrants and Emerging Players: Industrial aftermarket service providers offer the most penetrable channel for independent gate driver replacement and DC-link capacitor refurbishment. Target North American wind corridors where turbine fleets exceed original warranty periods. Partner with regional distributors serving textile plants in Gujarat and cement facilities in Rajasthan for variable-frequency drive retrofits. For Investors and Strategic Acquirers: Asymmetric upside sits with fabless designers licensing wide-bandgap process nodes and module packagers with liquid-cooling expertise. Long-term viability favors suppliers with thermal management IP serving 800V EV architectures and industrial drives facing F-Gas Regulation compliance deadlines. Watch AEC-Q101 qualification timeline compression as the inflection signal for bare-die vendor market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Production | Captive wafer supply secures automotive qualification timelines against single-source concentration risk. |
| Liquid-Cooled Module Packaging Expansion | ABB and Siemens specifications for F-Gas Regulation compliance create premium thermal management demand. |
| Software-Defined Gate Control Development | Firmware-over-the-air subscriptions enable recurring revenue from predictive thermal monitoring in wind converters. |
| Automotive Bare-Die Qualification Investment | Volkswagen Group and Hyundai Motor Company die-level procurement expands addressable market beyond module sales. |
| India Industrial Distribution Partnership | Bureau of Energy Efficiency IE4 mandates in Gujarat and Rajasthan create retrofit volume for variable-frequency drives. |
Methodological Framework
Coverage spans China, Germany, India, Japan, and the United States, with primary inputs from each region combining interviews with power electronics procurement managers at automotive OEMs, thermal design engineers at industrial drive manufacturers, and semiconductor fabrication executives. Secondary validation draws from MIIT GB standard filings, EPA motor standards documentation, EU F-Gas Regulation implementation guidance, and SEC 10-K disclosures from listed device manufacturers. Bottom-up shipment data triangulates against top-down market sizing across the analysis window.
Segmentation granularity models product type at the converter-inverter-switch-controller level, technology at silicon-SiC-GaN-hybrid resolution, and end-use across automotive-industrial-consumer-telecom categories. CAGRs derive from unit shipment trajectories and average selling price evolution through the projection horizon. Industry-specific forecast inputs include EV platform voltage migration timelines and renewable energy installation targets under China's dual carbon goals.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to substrate supply expansion rates and automotive qualification timeline compression. Assumptions reflect current regulatory enforcement patterns for F-Gas Regulation and MIIT domestic content thresholds. A small set of triggers warrants ongoing watch: 8-inch SiC wafer commercialization timelines, gate oxide reliability resolution for GaN HEMTs, and India's PLI scheme disbursement velocity for semiconductor packaging investment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Laptop Battery Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Global Flexible Batteries Market
Power Systems
Low Voltage AC Drive Market
Power Systems
Buck-Boost Controller Market
Power Systems
Power Supply Isolation Equipment Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Flyback Transformer Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
South America Battery Management System Market
Power Systems
Modular Inverter Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
String Inverter Market