
 United States Discrete Semiconductors Market | 2026-2036
United States Discrete Semiconductors Market Size, Share, and Industry Trends Forecast 2026-2036
United States Discrete Semiconductors Market Insights
Modular power module packaging is rebalancing procurement patterns across automotive and industrial buyer segments. ON Semiconductor Corp. leverages vertical integration into silicon carbide substrate supply to secure captive wafer capacity. Vishay Intertechnology Inc. anchors broad-line diode and rectifier portfolios through disciplined manufacturing scale across multiple US facilities. Texas Instruments Inc. differentiates by sustaining R&D intensity in gallium nitride process development for next-generation RF applications.
Discrete semiconductors are individual, non-integrated circuit electronic components fabricated from silicon, silicon carbide, or gallium nitride that perform single functions such as switching, rectification, or voltage regulation, typically specified by breakdown voltage, current rating, and switching speed parameters. These components serve as fundamental building blocks in power management, signal conditioning, and protection circuits across every electronic system category. Transistor categories, particularly field-effect and silicon carbide variants, command expanding margin pools as electrification intensifies thermal and efficiency requirements. Diode and rectifier segments maintain mature, high-volume positions in industrial automation and telecommunications infrastructure where replacement cycles generate predictable aftermarket demand.
The CHIPS and Science Act, administered through the Department of Commerce, directs federal incentives toward domestic discrete semiconductor fabrication, altering site selection and capital allocation timelines for producers. EPA emissions standards and NHTSA fuel economy rules indirectly amplify demand for efficient power conversion components in vehicle electrification platforms. OSHA semiconductor fabrication safety protocols shape cleanroom construction and operational compliance costs for new domestic facilities. Stakeholders must monitor how BIS export control classifications on wide-bandgap substrates affect material sourcing strategies and foundry qualification timelines.
Market Dynamics
Silicon carbide substrate shortages are forcing automotive OEMs to redesign inverter architectures around available wafer supply, compressing qualification timelines and locking in multi-year procurement commitments before fabrication capacity comes online.
Growth Catalysts
- NHTSA fuel economy mandates:EPA emissions standards tighten fleet-average requirements, compelling powertrain electrification that multiplies discrete semiconductor content per vehicle.
- Texas-Arizona-California foundry clustering:CHIPS Act incentives concentrate domestic fabrication investments in these three states, accelerating regional supply chain maturation.
- Wide-bandgap material transitions:Silicon carbide and gallium nitride replace silicon in high-voltage applications, opening margin expansion in electric vehicle traction inverters and renewable energy converters.
Market Restraints
- Substrate supply concentration:Silicon carbide wafer production concentrates among limited qualified suppliers, creating allocation bottlenecks that throttle module output expansion.
- Cleanroom construction cost inflation:OSHA semiconductor fabrication safety protocols mandate specialized HVAC and chemical handling infrastructure that extends facility build-out timelines.
- Silicon legacy process lock-in:Mature industrial automation and telecommunications infrastructure segments exhibit slow replacement cycles that delay wide-bandgap adoption.
Strategic Opportunities
- Defense electronics reshoring:BIS export control classifications on wide-bandgap substrates create captive demand for ITAR-qualified domestic fabrication lines serving aerospace and military programs.
- Grid-scale energy storage integration:Battery inverter systems for utility-scale solar and wind installations require high-reliability discrete components with extended temperature ratings.
- Direct OEM-foundry partnerships:Automotive manufacturers are bypassing traditional distribution channels to secure dedicated wafer capacity through long-term offtake agreements.
Industry Challenges
- Compound semiconductor process engineering talent scarcity:Silicon carbide epitaxy and gallium nitride HEMT fabrication require specialized expertise that outpaces domestic training program output.
- Multi-site qualification complexity:Automotive AEC-Q101 certification across geographically dispersed fabrication facilities extends product introduction timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Discrete Semiconductors Market |
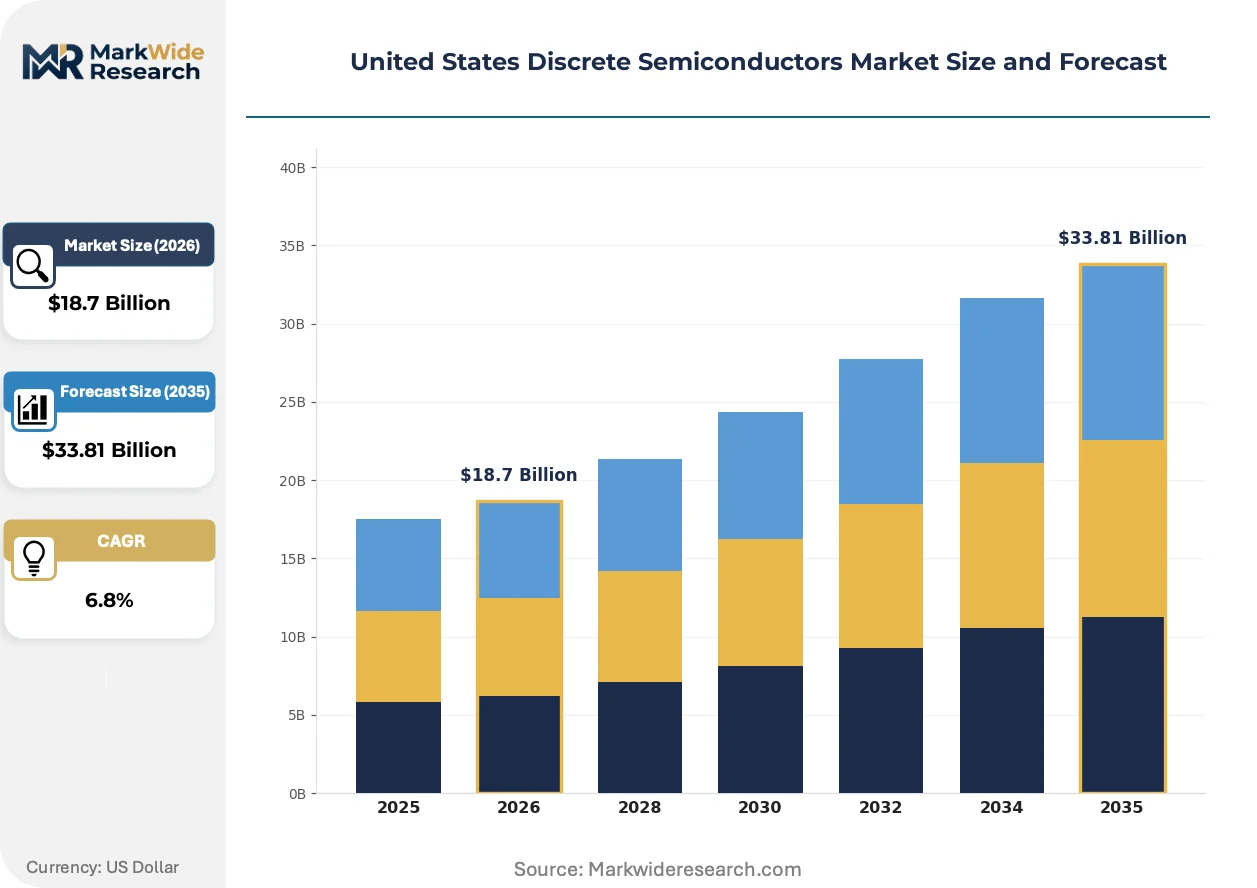
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diodes, Transistors, Thyristors, Rectifiers Application: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Technology: Bipolar Junction, Field Effect, Insulated Gate, Silicon Carbide End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators |
| Companies Covered | ON Semiconductor Corp., Infineon Technologies AG, Vishay Intertechnology Inc., Texas Instruments Inc., STMicroelectronics N.V., Wolfspeed Inc., Diodes Incorporated, Nexperia B.V., Littelfuse Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Discrete Semiconductors Market Trends and Innovations
Material science breakthroughs and federal industrial policy are converging to restructure how discrete semiconductors are designed, sourced, and integrated into electrified systems across transportation and energy infrastructure.
Gallium nitride power transistors is expanding into data center power supplies and consumer fast-charging adapters. Cloud computing operators and mobile device manufacturers are adopting GaN-based solutions at accelerating pace to reduce thermal management overhead and improve conversion efficiency. This technology is expanding into applications previously reserved for silicon MOSFETs, compressing cost premiums and forcing incumbent suppliers to accelerate process node transitions or cede mid-voltage segments.
The CHIPS and Science Act is redirecting capital allocation toward domestic substrate and epitaxy capacity. Department of Commerce incentive structures favor projects with demonstrated end-use commitments from defense and automotive buyers, altering site selection criteria away from pure cost optimization toward supply security metrics. Texas and Arizona project pipelines are absorbing disproportionate funding allocations as these states offer expedited permitting alongside existing semiconductor ecosystem density.
Automotive procurement teams are consolidating supplier relationships around vertically integrated substrate-to-module providers. Tier-1 power module manufacturers face margin compression as OEMs negotiate direct wafer supply agreements that bypass traditional component distribution channels. This consolidation is most visible in Detroit and California automotive engineering centers, where inverter platform teams now embed discrete semiconductor specialists within powertrain development organizations rather than relying on external component engineering support.
United States Discrete Semiconductors Market Segmentation
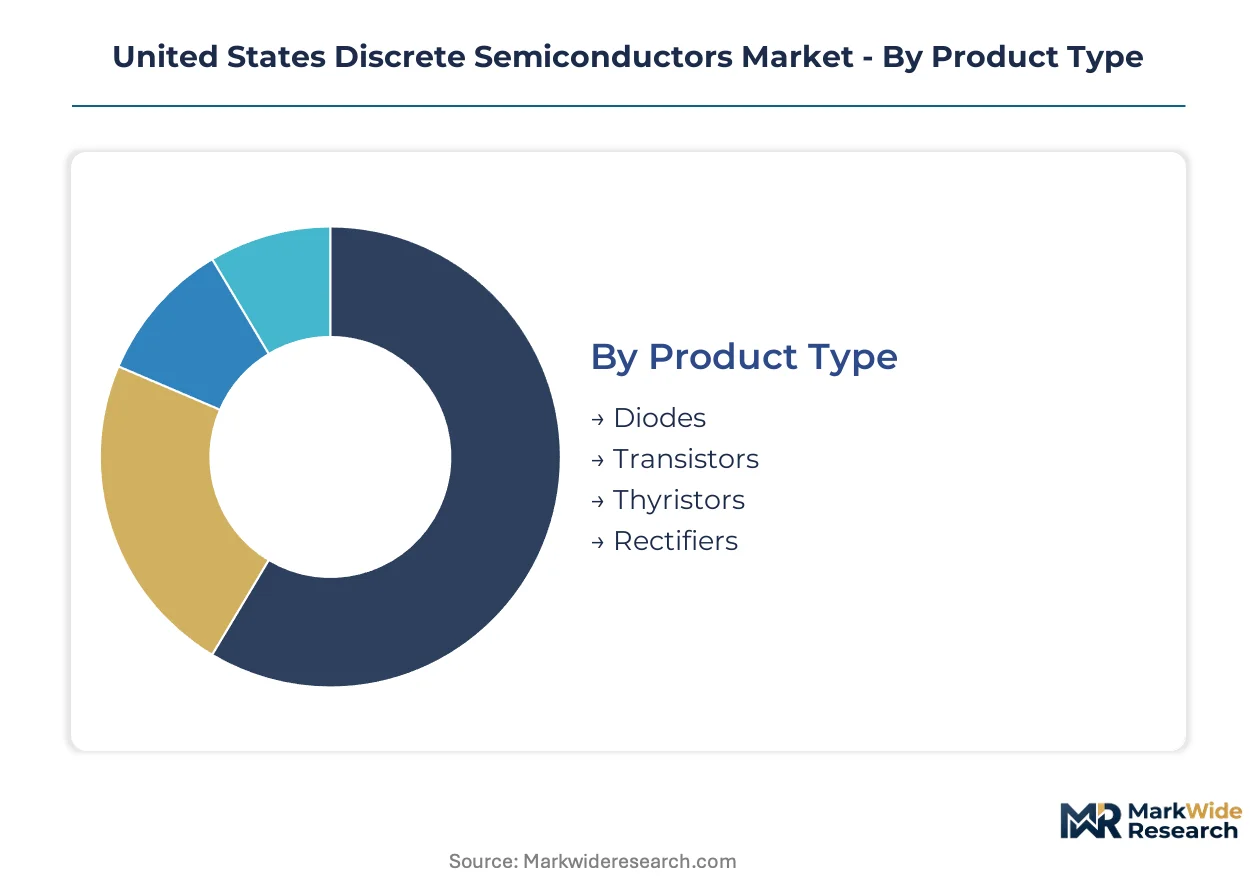
Discrete semiconductor procurement patterns diverge sharply across product categories and end-use applications, with certification requirements and supply chain configuration creating distinct commercial dynamics for each segment. Understanding these structural divisions reveals where margin pools concentrate and which buyer segments command pricing leverage.
Product Type:
AEC-Q101 automotive qualification and JEDEC industrial standards impose divergent testing burdens across product categories, with wide-bandgap variants requiring extended thermal cycling validation that stretches lead times.
- Transistors:Silicon carbide MOSFETs and gallium nitride HEMTs handle switching functions above 600 volts with switching speeds exceeding silicon limits by an order of magnitude. Automotive inverter platforms in Detroit and California engineering centers are consolidating procurement around field-effect variants that reduce thermal management overhead.
- Diodes:Schottky and fast-recovery architectures perform rectification with forward voltage drops between 0.3 and 1.2 volts depending on material system. Industrial automation controllers in Texas manufacturing corridors specify standard silicon for cost-sensitive positions while reserving silicon carbide for high-frequency switching nodes.
- Thyristors:Silicon-controlled rectifiers manage phase-angle control in motor drives and heating systems above 10 kilowatts.
- Rectifiers:Bridge and single-phase configurations convert AC mains to DC rails across consumer power adapters and industrial supplies.
Diodes sit at the top of the volume ranking, with transistors climbing the fastest.
Application:
End-use concentration determines whether procurement flows through distribution channels or direct foundry negotiations, with automotive and industrial buyers pursuing divergent sourcing strategies.
- Automotive:Traction inverters, onboard chargers, and DC-DC converters multiply discrete semiconductor content per vehicle as NHTSA fuel economy mandates tighten fleet-average requirements. OEM powertrain teams in Michigan and California are embedding component specialists within platform development organizations.
- Industrial Automation:Motor drives, power supplies, and programmable logic controllers consume high volumes of mature silicon technologies with replacement cycles extending 10-15 years. Texas and Ohio manufacturing bases generate predictable aftermarket demand through scheduled maintenance intervals.
- Consumer Electronics:Fast-charging adapters and computing power supplies are adopting gallium nitride transistors to reduce form factors.
- Telecommunications:Base station power amplifiers and network infrastructure rectifiers prioritize reliability over switching speed.
Industrial automation commands the largest installed base, while automotive applications are expanding most quickly.
Technology:
Process maturity and substrate availability create tiered supply security profiles, with compound semiconductor categories facing allocation constraints that silicon legacy technologies avoid.
- Silicon Carbide:Wide-bandgap substrates enable blocking voltages above 1200 volts with switching losses below silicon equivalents by 70-90 percent. Arizona and Texas foundry investments are targeting captive wafer supply as BIS export controls concentrate qualified substrate sources.
- Field Effect:MOSFET architectures dominate mid-voltage switching below 200 volts across computing and consumer applications with established supply chains and commoditized pricing.
- Bipolar Junction:Traditional NPN and PNP structures persist in linear amplification and low-frequency switching where cost minimization outweighs efficiency gains.
- Insulated Gate:IGBT modules bridge the voltage gap between 600 and 1700 volts for motor drives and grid-tied inverters.
Field effect technology holds the highest unit volume position, with silicon carbide gaining share fastest.
End User:
Buyer scale and technical capability determine whether procurement emphasizes spot market flexibility or multi-year capacity reservations with foundry partners.
- OEMs:Detroit automotive manufacturers and California EV specialists are negotiating direct wafer supply agreements that bypass traditional distribution, locking in silicon carbide substrate allocations before fabrication capacity comes online.
- Tier-1 Suppliers:Power module integrators face margin compression as OEM consolidation eliminates intermediary value capture in inverter and converter assemblies.
- Aftermarket Providers:Replacement component distributors serve industrial maintenance schedules with mature silicon technologies where qualification timelines are minimal.
- System Integrators:Custom equipment builders combine discrete semiconductors with passive components into application-specific power conversion subsystems.
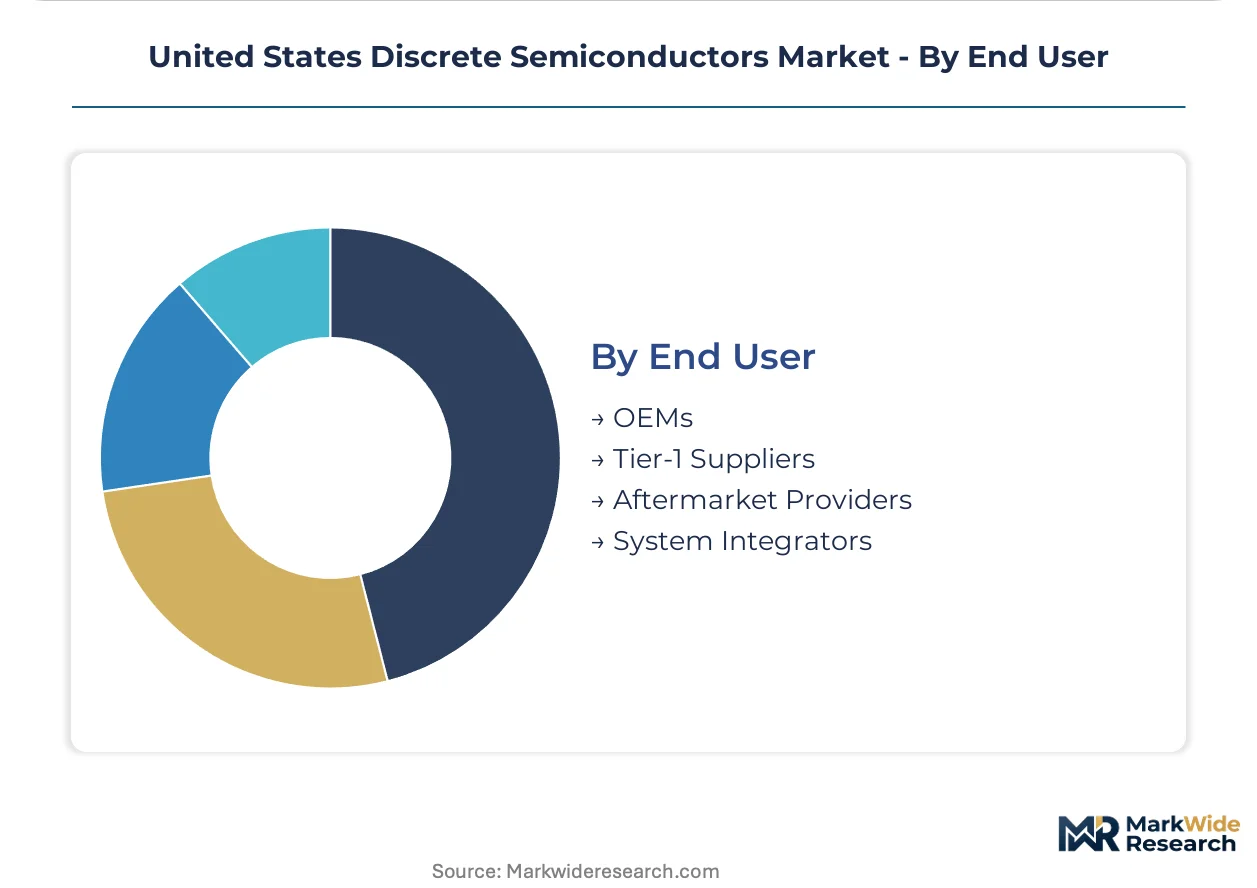
OEMs dominate absolute procurement value, with aftermarket providers maintaining the most stable demand profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US discrete semiconductor industry traces its commercial roots to Bell Labs' transistor invention in New Jersey, with subsequent scaling concentrated in defense-aerospace corridors and automotive manufacturing belts that now anchor domestic fabrication.
Texas
Silicon carbide substrate demand from electric vehicle manufacturers drives foundry investments in the Dallas-Austin corridor. CHIPS Act incentives administered by the Department of Commerce accelerate cleanroom construction timelines for new fabrication facilities. Austin's semiconductor cluster hosts multiple domestic producers expanding captive wafer capacity for automotive power modules.
Arizona
Wide-bandgap epitaxy capacity expansion responds to inverter procurement commitments from Detroit automotive OEMs. EPA emissions standards tighten fleet-average requirements, amplifying powertrain electrification programs. Phoenix-Tucson corridor fabrication sites concentrate CHIPS Act funding allocations due to expedited state permitting frameworks.
California
EV specialists in the Bay Area and Los Angeles engineering centers embed discrete semiconductor specialists within powertrain development organizations. NHTSA fuel economy mandates multiply component content per vehicle across traction inverter platforms. Silicon Valley maintains R&D intensity in gallium nitride process development for RF applications.
Michigan
Detroit automotive engineering centers negotiate direct wafer supply agreements that bypass traditional distribution channels. Tier-1 power module integrators face margin compression from OEM consolidation strategies. Southeast Michigan manufacturing bases generate aftermarket demand through scheduled industrial maintenance intervals.
Ohio
Industrial automation controllers in manufacturing corridors specify mature silicon technologies with replacement cycles extending 10-15 years. OSHA semiconductor fabrication safety protocols shape operational compliance costs for any new facilities. Cleveland-Akron industrial clusters maintain predictable demand through motor drive and programmable logic controller applications.
United States Discrete Semiconductors Market Competitive Landscape
The competitive structure tilts toward vertically integrated substrate-to-module providers. Domestic fabrication capacity expansion concentrates among producers securing CHIPS Act incentives. Three archetypes dominate: silicon carbide substrate specialists, broad-line diode and rectifier manufacturers, and gallium nitride process developers. Capacity expansion and direct OEM-foundry partnerships constitute the dominant competitive moves as automotive procurement teams consolidate supplier relationships.
Among US-based fabricators, ON Semiconductor Corp. and Texas Instruments Inc. occupy positions within the integrated device manufacturer tier, while Wolfspeed Inc. exemplifies the substrate-specialist archetype. These entities represent distinct strategic approaches to securing captive wafer supply and qualifying fabrication lines for automotive AEC-Q101 certification.
| Leading Market Players |
|---|
| ON Semiconductor Corp. |
| Infineon Technologies AG |
| Vishay Intertechnology Inc. |
| Texas Instruments Inc. |
| STMicroelectronics N.V. |
| Wolfspeed Inc. |
| Diodes Incorporated |
| Nexperia B.V. |
| Littelfuse Inc. |
| Others |
Pricing and Supply Chain Analysis
CHIPS Act incentive recipients and vertically integrated substrate specialists anchor pricing discipline through captive wafer supply and multi-year automotive offtake agreements. Texas and Arizona fabrication commitments concentrate procurement leverage among OEMs securing dedicated capacity, compressing margin pools for distributors lacking direct foundry relationships.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for silicon carbide MOSFETs and gallium nitride HEMTs, with pricing stratifying across automotive AEC-Q101 certification tiers, volume scale commitments, and captive substrate ownership. Price differentiation separates vertically integrated producers commanding premium positioning from broad-line distributors competing on silicon diode and rectifier spot markets. Cost compression in standard silicon categories intensifies as Chinese import competition and mature process depreciation erode realized margins. Tier-1 power module integrators exhibit highest price sensitivity due to OEM direct-sourcing bypass, while defense electronics buyers accept substantial premiums for ITAR-qualified domestic fabrication.
Supply Chain Analysis
Domestic-content mandates under the CHIPS and Science Act are redirecting capital toward Texas, Arizona, and California fabrication corridors, reshaping sourcing patterns for automotive and defense buyers. Silicon carbide substrate supply concentrates among qualified US and Japanese producers, with epitaxy equipment and wide-bandgap crystal growth furnaces drawing from German and Swiss precision manufacturing bases. Single-source vulnerability in 200mm silicon carbide wafer qualification creates allocation bottlenecks that throttle module output expansion. Distribution runs through direct OEM-foundry partnerships for wide-bandgap components, while mature silicon technologies maintain traditional authorized distributor channels serving industrial aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Discrete Semiconductors Market functions as a stable compounder underpinned by NHTSA fuel economy mandates that lock in decade-long powertrain electrification procurement cycles.
For Market Incumbents: Deploy backward integration into silicon carbide substrate supply to secure captive wafer capacity against emerging substrate-specialist entrants. Prioritize AEC-Q101 certification investment across geographically dispersed fabrication facilities to compress automotive qualification timelines. Channel control through direct OEM engineering embedding defends margin position against tier-1 power module integrator disintermediation. For New Entrants and Emerging Players: Begin with defense electronics reshoring opportunities created by BIS export control classifications on wide-bandgap substrates, where ITAR qualification barriers limit incumbent saturation. Target grid-scale energy storage inverter applications requiring extended temperature ratings and high-reliability discrete components. Pursue foundry-services positioning supplying epitaxy and fabrication capacity to fabless design houses lacking domestic qualification expertise. For Investors and Strategic Acquirers: Valuations sit cheapest among broad-line diode and rectifier manufacturers with disciplined manufacturing scale but limited wide-bandgap exposure. Long-term viability centers on substrate-to-module vertical integration capability across the 5-10 year electrification investment window. Monitor silicon carbide wafer qualification timelines at Arizona and Texas greenfield facilities as the inflection indicator for supply constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Capacity Expansion | Captive wafer supply secures allocation priority under CHIPS Act incentive structures. |
| Automotive AEC-Q101 Certification Investment | Multi-site qualification compresses product introduction timelines for Detroit OEM platforms. |
| Direct OEM-Foundry Partnership Formation | Long-term offtake agreements bypass tier-1 integrator margin capture in inverter procurement. |
| Gallium Nitride Process Development R&D | Next-generation RF applications in California defense electronics sustain technology leadership. |
| Defense Electronics ITAR Qualification | BIS export controls create captive demand for domestic fabrication serving aerospace programs. |
Research Methodology
Bottom-up automotive and industrial end-use modeling reconciled against top-down fabrication capacity and substrate supply tracking forms the analytical core of this study. Primary interviews with OEM powertrain procurement directors, tier-1 power module engineering leads, foundry operations managers, and defense electronics program officers combine with secondary validation from SEC 10-K filings, Department of Commerce CHIPS Act award announcements, EPA emissions standard dockets, and NHTSA fuel economy rulemaking records. Triangulation between demand-side consumption patterns and supply-side capital expenditure commitments ensures coherence across volume and value estimates.
Historical trendline analysis of silicon carbide adoption rates in electric vehicle traction inverters and industrial motor drives informs the projection framework across the analysis window. Segmentation dimensions span product type, application, technology, and end user, with additional modeling of regional foundry clustering patterns in Texas, Arizona, and California. CAGRs derive from fitted growth curves calibrated to announced fabrication capacity timelines and automotive platform electrification commitments. Forecast inputs include silicon carbide substrate yield improvement trajectories and gallium nitride cost-parity crossover points with silicon MOSFETs.
Caveats apply where BIS export control expansion, OSHA cleanroom construction delays, or silicon carbide epitaxy talent scarcity could materially shift the outlook. Forecasts reflect assumptions regarding CHIPS Act disbursement pacing and automotive OEM electrification timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Discrete Semiconductor Market
Semiconductors
North America Semiconductor Market
Semiconductors
Organic Polymer Electronics Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Wide Bandgap Semiconductors Market
Semiconductors
Compound Semiconductor Market
Semiconductors
High Reliability Semiconductor Market
Semiconductors
India Semiconductor Market
Semiconductors
Japan Discrete Semiconductors Market
Semiconductors
Organic Electronics Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
ASEAN Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Europe Automotive Semiconductor Market