
 Printed Electronics Market | 2026-2036
Printed Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Printed Electronics Market Intelligence
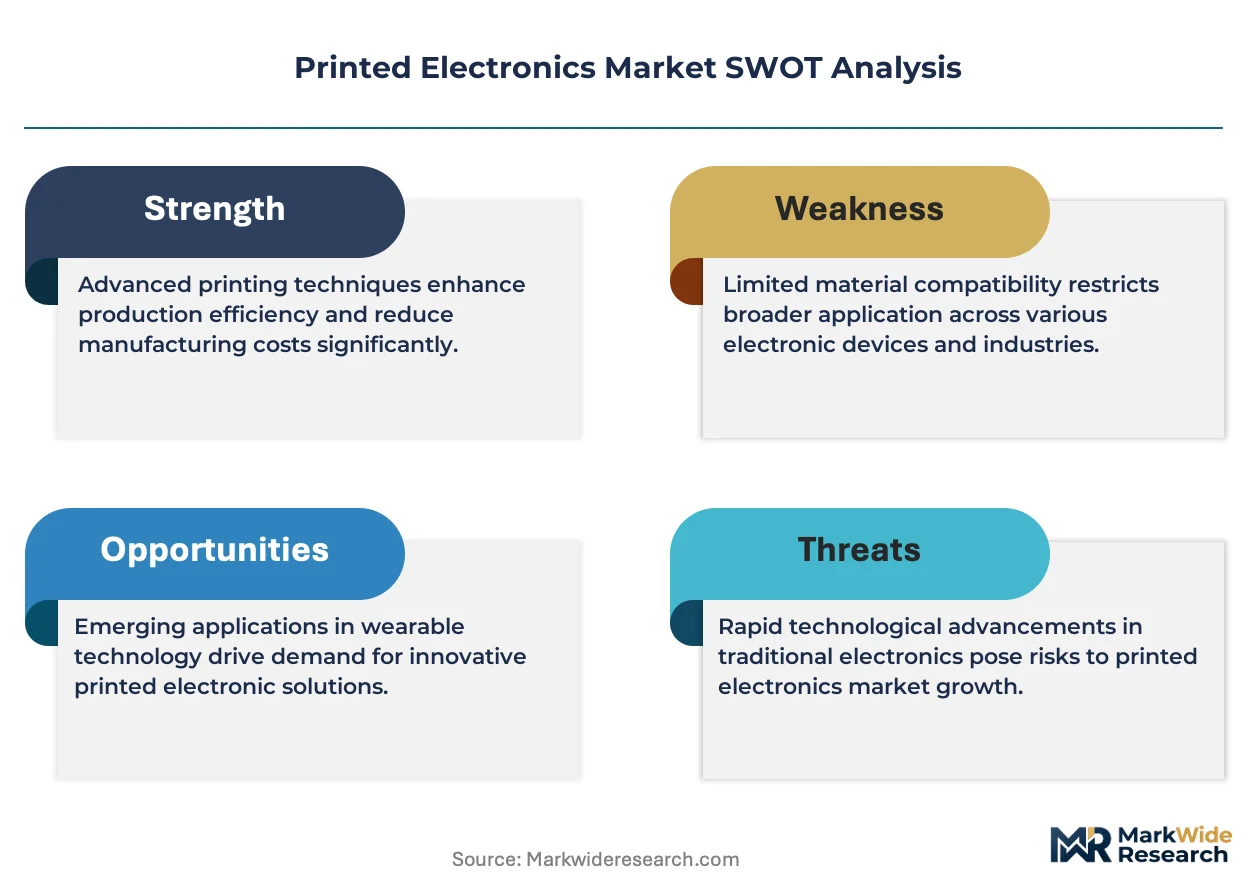
High-resolution aerosol jet deposition is redrawing quality benchmarks for conformal antenna traces on curved automotive surfaces. DuPont leverages its fluoropolymer ink portfolio to sustain margins in RF substrate applications. BASF anchors European supply through captive precursor chemistry for conductive polymers. NovaCentrix specializes in photonic curing systems that compete with thermal sintering on speed and energy efficiency.
Printed electronics encompasses additive manufacturing of functional devices through deposition of conductive, semiconductive, and dielectric inks onto flexible substrates such as PET, PEN, and thin glass at temperatures below 150°C, enabling circuitry on non-planar or temperature-sensitive surfaces. The primary commercial purpose centers on replacing rigid PCB assemblies with lightweight, conformal alternatives in weight-critical and form-factor-constrained applications. Printed sensors currently occupy the largest product-type margin pool due to recurring replacement cycles in industrial IoT deployments, while flexible displays represent the fastest-growing application segment as foldable smartphone architectures mature. Inkjet printing leads technology adoption for prototyping and short-run customization, though gravure dominates high-volume roll-to-roll production of transparent conductive films for touch modules.
FDA scrutiny of biocompatible materials governs wearable medical patches incorporating printed glucose sensors, while EPA regulations on volatile organic compounds constrain solvent-based ink formulations in US manufacturing. The EU RoHS directive and REACH substance restrictions drive reformulation of lead-free solders and halogen-free substrates across European supply chains. Stakeholders must monitor evolving Ecodesign requirements under the EU Green Deal as these frameworks extend from finished electronics to encompass substrate recyclability and ink recovery protocols.
Market Dynamics
Roll-to-roll manufacturing economics are compressing unit costs for printed sensors while EU REACH compliance mandates force mercury-free ink reformulation across European supply chains. This dual pressure—scale efficiency and substance restriction—is restructuring competitive positioning between gravure-dominated high-volume producers and inkjet-focused customization specialists.
Growth Catalysts
- Automotive lightweighting mandates:Structural health monitoring sensors printed directly onto composite body panels eliminate wiring harness weight. German OEMs deploy these in electric vehicle architectures where every kilogram extends range.
- REACH substance restrictions:Mercury-free conductive ink formulations now match legacy performance, unlocking medical wearable applications previously blocked by biocompatibility concerns. ECHA enforcement accelerates substitution timelines.
- Photonic curing advancement:NovaCentrix pulse-thermal systems sinter silver nanoparticles in milliseconds versus minutes for thermal ovens. Energy consumption drops enable margin recovery for European contract manufacturers facing electricity cost volatility.
Market Restraints
- Silver price volatility:Conductive ink formulations rely on silver flake and nanoparticle feedstocks. London Metal Exchange price swings above 20% annually compress formulation margins and deter long-term supply contracts.
- Substrate supply concentration:High-grade PEN film production concentrates among three Japanese chemical conglomerates. Any disruption to Kobe or Osaka manufacturing corridors propagates through European printed electronics supply within weeks.
- Resolution limitations:Gravure printing struggles below 20-micron line widths required for high-density interconnects. This technical ceiling excludes printed electronics from smartphone mainboard substitution despite foldable display success.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO track-and-trace mandates for exported medicines create demand for printed RFID antennas on blister packs. Domestic gravure infrastructure can pivot from decorative printing to functional electronics with minimal retooling.
- Building-integrated photovoltaics:Organic photovoltaic cells printed onto architectural glass merge energy generation with envelope function. German building codes under the EU Green Deal increasingly mandate renewable surface area ratios.
- AI-assisted print optimization:Machine vision closed-loops adjust ink viscosity and drop placement in real-time. This convergence of additive manufacturing and predictive analytics reduces yield loss for short-run medical device batches.
Industry Challenges
- Cross-disciplinary talent scarcity:Process engineers must simultaneously command fluid rheology, polymer substrate mechanics, and electrical characterization. Universities in Stuttgart and Eindhoven produce insufficient hybrid graduates for current hiring pipelines.
- Medical device certification timelines:FDA 510(k) pathways for printed glucose sensors extend 18-24 months despite predicate device availability. Startups exhaust runway awaiting biocompatibility data package acceptance.
- Legacy PCB integration friction:Automotive Tier-1s struggle to qualify printed sensor networks alongside conventional rigid-flex assemblies. Mixed-technology reliability testing protocols remain undefined under AEC-Q100 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printed Electronics Market |
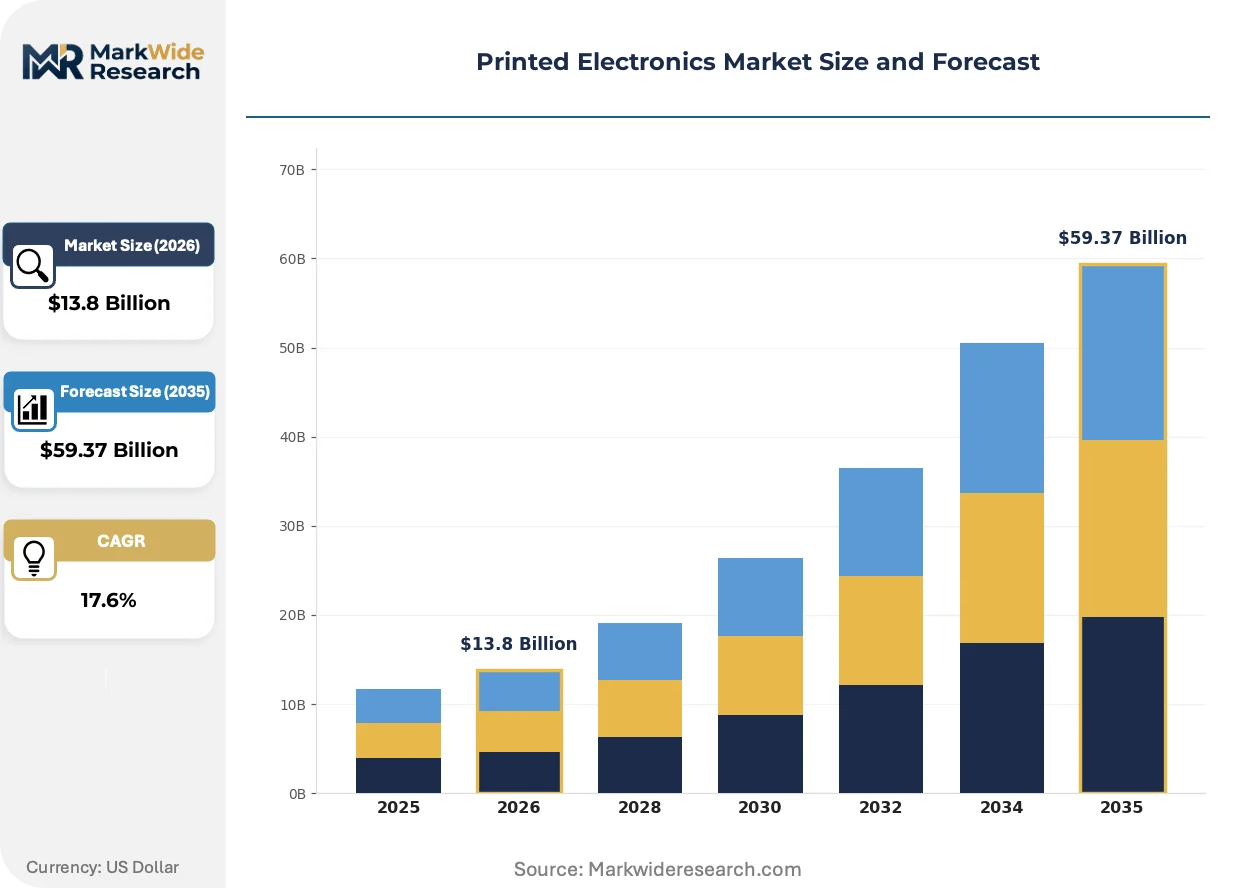
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $59.37 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Printed Sensors, Organic Light Emitting Diodes, Printed Batteries, Thin Film Transistors, Printed Antennas Technology: Inkjet Printing, Screen Printing, Gravure, Flexography, Aerosol Jet Printing Application: Wearable Devices, Smart Cards, Consumer Electronics, Smart Packaging, Flexible Displays End User: Consumer Electronics Manufacturers, Aerospace Companies, Defense Contractors, Textile Producers, Agriculture Equipment Makers |
| Companies Covered | DuPont, BASF, Agfa-Gevaert Group, Henkel AG & Co. KGaA, NovaCentrix, E Ink Holdings, Molex, Nissha Co. Ltd., LG Display Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printed Electronics Market Strategic Shifts & Innovations
Aerosol jet deposition is redrawing quality benchmarks for conformal antenna traces on curved automotive surfaces. Three interconnected developments are accelerating capability expansion across materials, regulation, and procurement models.
Photonic curing systems is decomposing the thermal sintering bottleneck that has constrained printed electronics throughput. Automotive antenna manufacturers adopt pulsed-light processing for conformal radar-transparent traces on bumper fascias. This substitution eliminates 90% of oven energy consumption while enabling heat-sensitive polypropylene substrates previously excluded from metallic deposition.
EU Ecodesign requirements under the Green Deal now extend substrate recyclability mandates to functional electronics. Manufacturers must demonstrate ink recovery protocols and halogen-free substrate compatibility to maintain CE marking. German automotive suppliers face the steepest compliance curves as OEMs cascade circularity requirements through tiered supply contracts.
Pharmaceutical buyers now specify printed sensor integration directly into primary packaging rather than secondary cartons. This disintermediation of the converter tier concentrates procurement authority with Novartis and Roche packaging engineering teams. Swiss and German facilities lead this reconfiguration, bypassing traditional label converters who lack printed electronics capability.
Printed Electronics Market Segmentation
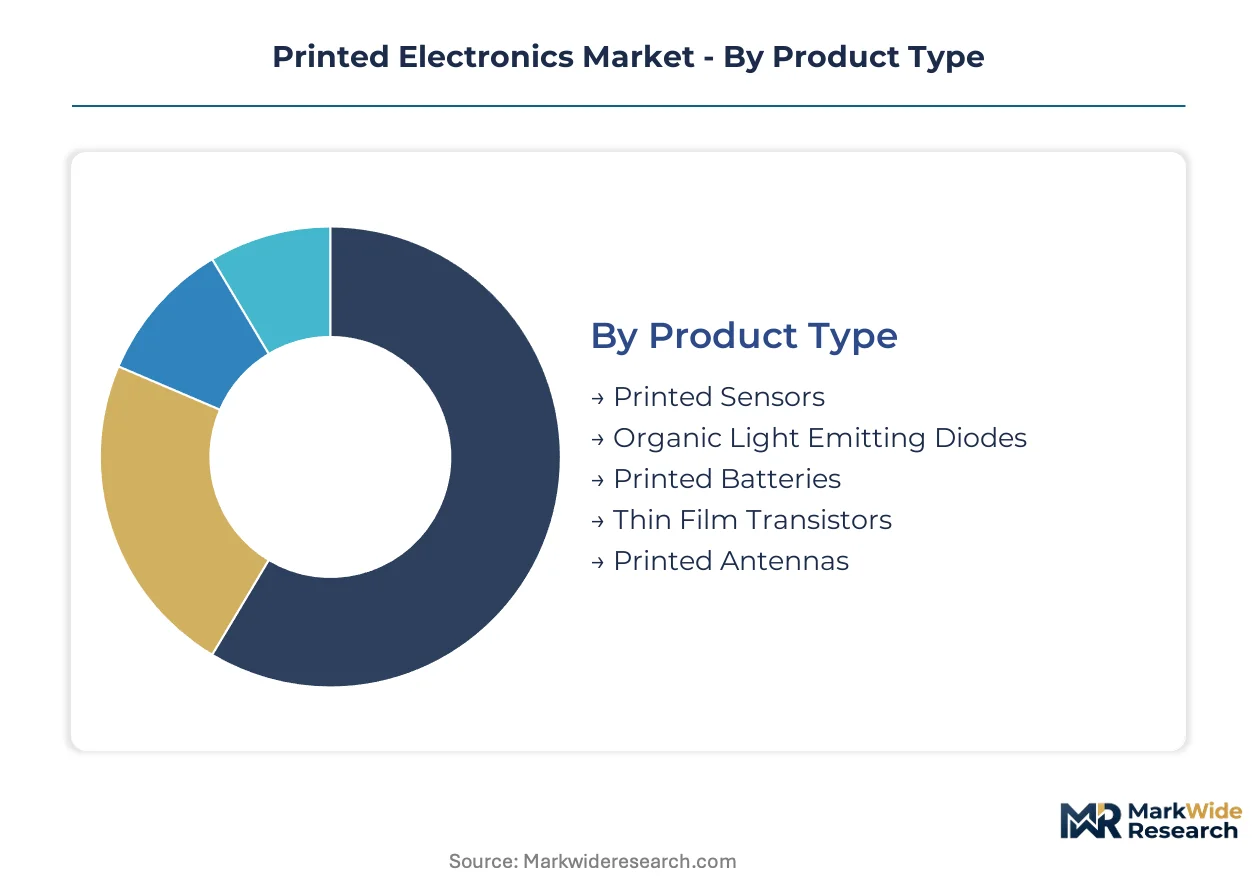
Printed electronics segmentation reveals divergent supply chain architectures across product categories. Some segments serve regional automotive clusters with short logistics loops, while others feed export-dependent consumer electronics assembly concentrated in East Asian manufacturing corridors.
Product Type:
Printed sensors and organic light emitting diodes anchor domestic European production serving automotive and medical device clusters. Printed batteries and thin film transistors rely heavily on Asian contract manufacturing for volume scale.
- Printed Sensors:These devices integrate conductive traces on flexible substrates for strain, temperature, and pressure measurement. German automotive OEMs embed them directly into composite body panels for structural health monitoring, driven by electric vehicle lightweighting mandates under EU fleet emission rules.
- Organic Light Emitting Diodes:OLED layers deposited through solution processing enable conformal illumination on curved surfaces. Korean display manufacturers dominate export volumes for smartphone foldable panels, though Fraunhofer institutes are scaling pilot lines for European automotive interior applications.
- Printed Batteries:Zinc-based and solid-state electrolyte formulations power disposable medical patches and logistics sensors. Japanese chemical conglomerates control high-grade separator film supply.
- Thin Film Transistors:Solution-processed semiconductors enable backplane circuitry for flexible displays. Taiwan-based foundries handle wafer-scale integration for consumer electronics brands.
- Printed Antennas:Silver nanoparticle traces on PET substrates replace etched copper for RFID and NFC applications. Indian pharmaceutical packaging converters are retooling gravure lines for CDSCO track-and-trace compliance.
Printed sensors command the established base. The steepest expansion runs through organic light emitting diodes.
Technology:
Cost tier stratification separates prototyping-grade deposition from high-volume manufacturing. Inkjet and aerosol jet systems serve premium customization at low volumes, while gravure and flexography deliver unit economics for billion-unit consumer electronics runs.
- Inkjet Printing:Piezoelectric drop-on-demand systems enable rapid design iteration without physical masks. Medical device startups in Stuttgart and Eindhoven leverage this for short-run glucose sensor batches where each design requires FDA 510(k) resubmission.
- Screen Printing:Mesh-based stencil deposition remains the workhorse for thick-film conductive layers in automotive defrost circuits. Polish and Czech contract manufacturers maintain competitive positioning through manual line flexibility for sub-10,000 unit orders.
- Gravure:Engraved cylinder printing achieves sub-micron thickness control for transparent conductive oxide replacement in touch modules. Three Japanese equipment builders control precision engraver supply, creating lead time vulnerability for European producers.
- Flexography:Raised rubber plate systems suit high-speed roll-to-roll production of antenna traces on packaging films. Brazilian and Mexican converters serve North American pharmaceutical serialization mandates.
- Aerosol Jet Printing:Atomized ink streams deposit 10-micron features on 3D surfaces without contact. German automotive Tier-1s qualify this for conformal radar-transparent bumper fascia traces.
Gravure dominates volume throughput. Aerosol jet printing is climbing the fastest as automotive conformal applications multiply.
Application:
Customer type fragmentation splits procurement between regulated medical buyers and cost-sensitive consumer electronics brands. Wearable devices and smart packaging demand biocompatibility certification, while flexible displays and consumer electronics prioritize pixel density and yield rates.
- Wearable Devices:Skin-conformal patches integrate printed glucose sensors and electrocardiogram electrodes. FDA biocompatibility requirements and EPA volatile organic compound constraints govern US manufacturing location decisions.
- Smart Cards:Dual-interface payment cards embed printed antenna coils connecting contactless chips to external terminals. EMVCo certification timelines stretch 12-18 months for new substrate-ink combinations.
- Consumer Electronics:Foldable smartphones and tablets drive demand for flexible display backplanes and hinge-integrated circuitry. Korean and Chinese OEMs specify proprietary ink formulations locked to their assembly processes.
- Smart Packaging:Temperature-logging labels and authentication seals incorporate printed sensors and NFC antennas. Swiss pharmaceutical packaging engineering teams now specify direct sensor integration into primary blister packs.
- Flexible Displays:OLED and electrophoretic frontplanes on polymer substrates enable rollable and foldable form factors. Japanese PET film producers concentrate high-grade supply in Kobe and Osaka manufacturing corridors.
Wearable devices command the established base. Flexible displays are gaining share fastest as foldable architectures mature.
End User:
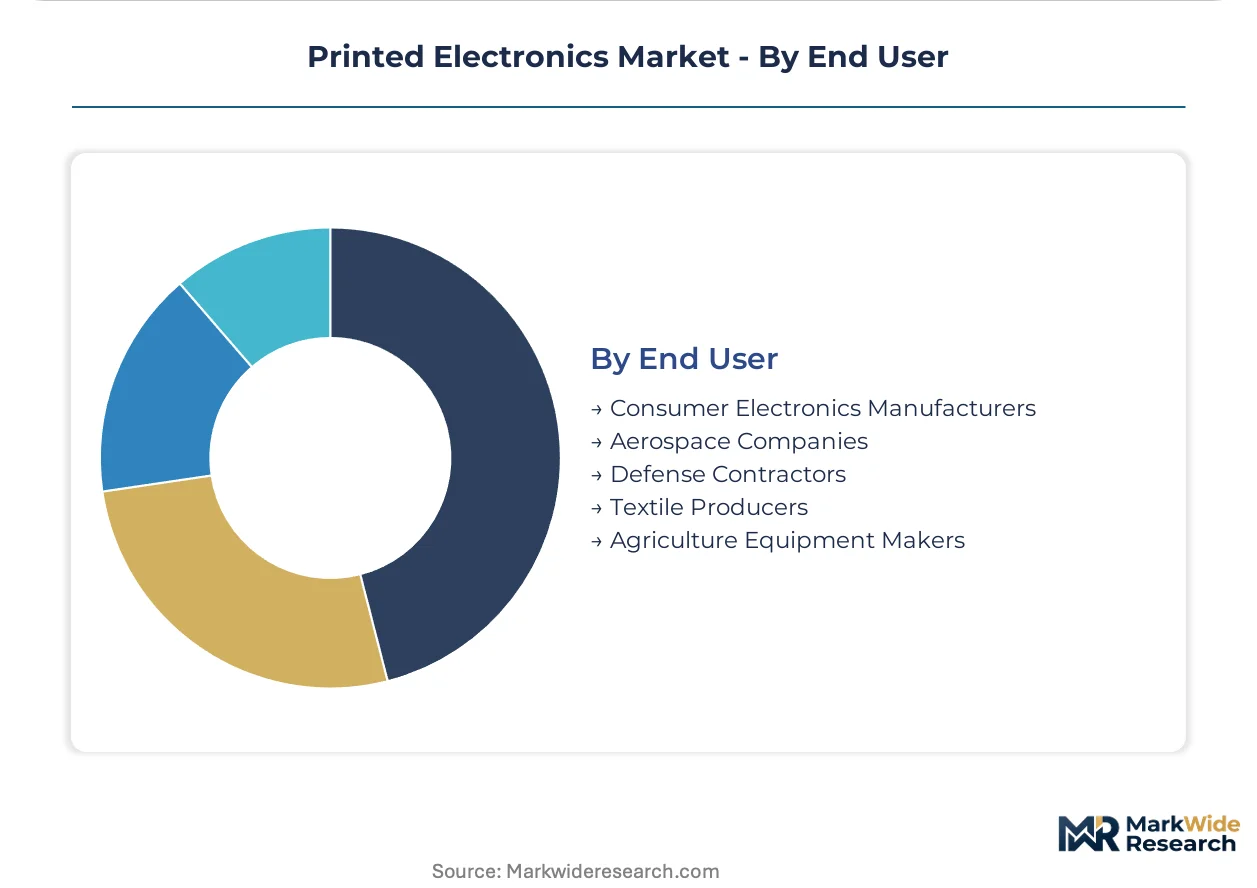
Margin concentration varies sharply across buyer sophistication. Defense contractors and aerospace companies accept premium pricing for qualification documentation, while textile producers and agriculture equipment makers pressure suppliers on unit cost.
- Consumer Electronics Manufacturers:Smartphone and tablet OEMs drive the largest absolute volume demand for flexible display backplanes and touch sensor films. Procurement teams in Korea and China negotiate multi-year ink supply agreements indexed to silver London Metal Exchange pricing.
- Aerospace Companies:Cabin interior lighting and sensor networks prioritize flame retardancy and outgassing compliance. FAA certification protocols for printed wiring on composite structures remain under development, stretching qualification timelines.
- Defense Contractors:Conformal antenna arrays and disposable sensor networks demand ITAR-controlled manufacturing locations. US-based production captures this segment despite higher labor costs.
- Textile Producers:E-textile applications integrate conductive traces into fabric substrates for heated garments and biometric monitoring. Italian and Portuguese mills specialize in wash-cycle durability testing.
- Agriculture Equipment Makers:Soil moisture sensors and crop monitoring labels target cost points below five cents per unit. Brazilian and Indian agricultural equipment assemblers drive specification setting.
Consumer electronics manufacturers anchor volume demand. Aerospace companies represent the steepest expansion trajectory as conformal sensor networks replace conventional harnesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs in Germany absorb premium pricing for conformal sensor networks, while Indian pharmaceutical packaging converters prioritize unit economics for RFID track-and-trace mandates. This demand-elasticity split shapes regional specialization patterns.
Germany
Fraunhofer institutes bridge laboratory inkjet deposition to roll-to-roll manufacturing for automotive structural health monitoring. EU REACH compliance mandates mercury-free conductive ink formulations across Baden-Württemberg supply chains. Stuttgart engineering clusters qualify aerosol jet systems for conformal radar-transparent bumper traces.
United States
FDA biocompatibility requirements govern wearable medical patch production incorporating printed glucose sensors. EPA volatile organic compound regulations constrain solvent-based ink formulations in domestic manufacturing. Boston and San Francisco medical device startups exhaust runway navigating 18-24 month 510(k) certification timelines.
China
MIIT industrial policy prioritizes domestic flexible display backplane capacity for foldable smartphone OEMs. GB standards govern electromagnetic compatibility for printed antenna applications. Yangtze River Delta manufacturing corridors concentrate gravure production for billion-unit touch module runs.
Japan
METI technology roadmaps target high-grade PEN film self-sufficiency for flexible substrate supply. JIS standards define reliability benchmarks for printed battery separators in medical patch applications. Kobe and Osaka chemical conglomerates control global high-performance polymer film output.
India
CDSCO pharmaceutical track-and-trace mandates create demand for printed RFID antennas on export blister packs. Domestic gravure infrastructure pivots from decorative printing to functional electronics with minimal retooling. Gujarat and Maharashtra packaging converters capture contract flows from Swiss and German pharmaceutical engineering teams.
Printed Electronics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Specialty chemical conglomerates with captive precursor chemistry dominate materials innovation, while Asian contract manufacturers capture scale-driven production of commodity transparent conductive films. Three archetypes define positioning: integrated chemical-materials suppliers, equipment-ink specialists, and display-centric diversified electronics groups. Consolidation pressure runs through strategic partnerships linking European formulation expertise to Asian roll-to-roll capacity.
Among integrated chemical conglomerates, DuPont and BASF anchor the premium materials tier through fluoropolymer ink portfolios and captive conductive polymer precursor supply. NovaCentrix occupies a distinct position on the equipment-technology vector, representing photonic curing specialists competing with thermal sintering on speed and energy efficiency. These three exemplify how competitive advantage concentrates either upstream in materials chemistry or downstream in process equipment integration.
| Leading Market Players |
|---|
| DuPont |
| BASF |
| Agfa-Gevaert Group |
| Henkel AG & Co. KGaA |
| NovaCentrix |
| E Ink Holdings |
| Molex |
| Nissha Co. Ltd. |
| LG Display Co., Ltd. |
| Others |
Cost & Logistics Intelligence
EU REACH substance restrictions gate both supplier qualification and price differentiation simultaneously, forcing mercury-free ink reformulation that separates certified medical-grade suppliers from commodity producers while silver price volatility compresses margins across all tiers.
Pricing Analysis
After-sales revenue from sensor replacement cycles in industrial IoT deployments drives lifetime value. Contract-based long-term offtake agreements dominate, with price differentiation hinging on FDA biocompatibility certification tier and volume scale. Cost compression in standard-grade transparent conductive films is intensifying because Korean display OEMs negotiate multi-year supply agreements indexed to London Metal Exchange silver pricing. Agriculture equipment makers exhibit highest price sensitivity, targeting sub-five-cent unit costs, while aerospace contractors accept premium pricing for flame-retardant qualification documentation.
Supply Chain Analysis
Kobe and Osaka manufacturing corridors concentrate high-grade PEN film production, creating a chokepoint that propagates disruption through European supply within weeks. Raw material dependencies center on silver nanoparticle feedstocks, fluoropolymer precursors, and halogen-free substrate films. Single-source vulnerability runs through three Japanese chemical conglomerates controlling precision gravure engraver supply. Distribution runs through tiered automotive supply contracts cascading circularity requirements from German OEMs through Baden-Württemberg engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Printed electronics fragmentation creates opportunity as pharmaceutical buyers disintermediate converter tiers and specify direct sensor integration into primary packaging, splintering procurement authority and opening niches for specialized formulation houses.
For Market Incumbents: Compound defensive positioning through captive precursor chemistry for conductive polymers and backward integration into photonic curing equipment. DuPont and BASF should deepen fluoropolymer ink portfolios to sustain margins against emerging Asian roll-to-roll scale players. Lock in multi-year supply agreements with German automotive OEMs before EU Ecodesign requirements extend substrate recyclability mandates.
For New Entrants and Emerging Players: Post-print technical service and FDA 510(k) navigation support represent gaps where incumbents under-serve, creating entry points for hybrid consulting-manufacturing models. Indian pharmaceutical packaging converters offer the most penetrable geography, with CDSCO track-and-trace mandates forcing gravure line retooling. Pursue white-label partnerships with Swiss and German pharmaceutical engineering teams lacking printed electronics capability.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European contract manufacturers facing electricity cost volatility and seeking photonic curing technology to recover margins. Long-term viability favors equipment-ink specialists with process integration expertise over pure materials plays. Watch for inflection when FDA publishes finalized biocompatibility guidance for printed glucose sensors, accelerating certification timelines and startup runway exhaustion.
| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Curing Technology Licensing | NovaCentrix pulse-thermal systems cut sintering energy by 90% versus thermal ovens. |
| Backward Integration into Silver Precursor Chemistry | BASF captive supply anchors European conductive polymer formulation against Asian competitors. |
| Medical Device Certification Partnership | FDA 510(k) pathway acceleration reduces 18-24 month timelines for glucose sensor startups. |
| Roll-to-Roll Capacity Expansion | Fraunhofer pilot line scaling bridges lab-scale inkjet to automotive volume production. |
| Pharmaceutical Packaging Direct Integration | Novartis and Roche engineering teams bypass converters for primary blister pack sensor specification. |
Research Approach
Initial hypotheses were tested against primary input from ink formulation chemists, automotive Tier-1 procurement managers, medical device regulatory affairs leads, and pharmaceutical packaging engineers, then refined through secondary validation against SEC filings from DuPont and BASF, ECHA REACH substance restriction updates, FDA 510(k) submission databases, and Fraunhofer institute technology roadmaps. Bottom-up segment sizing triangulated with top-down macroeconomic drivers.
Variance-decomposition across the analysis window isolates technology adoption curves, regulatory enforcement intensity, and raw material price swings as primary uncertainty sources. Segmentation dimensions modeled include product type, deposition technology, application vertical, end-user sophistication tier, and regional regulatory cluster. CAGRs derive from fitted adoption S-curves calibrated to historical penetration patterns in comparable flexible electronics markets.
Underlying assumptions cover REACH enforcement consistency, silver price corridor stability, and foldable smartphone architecture maturation, with deviation risk concentrated in Japanese substrate supply disruption or FDA biocompatibility guidance delays. Revision becomes warranted when automotive OEM lightweighting mandates accelerate beyond current EU fleet emission rule trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Medical Terahertz Technology Market
Emerging and Next Generation Technologies
Roll to Roll Flexible Electronics Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Multi-Touch Technology Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
North America Quantum Computing Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Deep Tech Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market