
 UK Outdoor LED Lighting Market | 2026-2036
UK Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
UK Outdoor LED Lighting Market Insights
A capital-intensity divergence between in-house semiconductor fabrication and outsourced assembly is redrawing competitive tiers in the UK outdoor LED sector. Signify N.V. leverages its captive LED chip production to control cost structures across street and flood luminaire portfolios. Dialight PLC specializes in hazardous-area certifications that anchor its position in industrial site applications. Schréder Group competes through municipal framework contracts that dominate large-scale roadway tenders across English cities.
UK outdoor LED lighting comprises solid-state luminaires engineered with efficacy ratings exceeding 130 lumens per watt, typically employing aluminium heat sinks and IP66-rated enclosures for weather resilience in public infrastructure. These systems serve primarily to reduce energy consumption and maintenance cycles across municipally managed public realms. Smart LED technology leads technology segmentation through connected controls that enable remote dimming and fault monitoring across urban networks. Street lights command the largest product-type volume, though solar LED installations are gaining traction in off-grid park and rural pathway applications. Municipalities represent the dominant end-user category, with procurement concentrated through OJEU-compliant framework agreements that favour established suppliers with national maintenance coverage.
The UK Department for Transport's Street Lighting Framework and Part L of the Building Regulations mandate minimum luminous efficacy and glare control standards for all new public installations. BSI Kitemark certification and CE/UKCA marking requirements shape product access by enforcing thermal management and electromagnetic compatibility testing. Stakeholders must monitor evolving smart city procurement criteria that increasingly bundle lighting with sensor networks and data platform integration.
Market Dynamics
Municipal framework procurement across England's metropolitan authorities is compressing supplier selection cycles while elevating smart-control integration requirements. The Department for Transport's Street Lighting Framework now bundles luminaire supply with 25-year maintenance obligations, favoring vendors with captive chip production and national service networks.
Growth Catalysts
- MEES standards tightening:The UK's Minimum Energy Efficiency Standards now mandate 130+ lumens per watt efficacy for all new public installations, forcing accelerated LED retrofits across municipal portfolios.
- Smart city sensor convergence:Metropolitan authorities in Greater Manchester and Birmingham are bundling air quality monitors and traffic sensors with roadway lighting tenders, expanding contract values beyond pure illumination.
- Aluminium heat sink localization:Domestic fabrication of thermal management components is reducing lead times for IP66-rated enclosures serving coastal and industrial applications.
Market Restraints
- GaN-on-silicon wafer supply concentration:Advanced LED chip substrates remain dependent on East Asian foundry capacity, exposing UK luminaire assemblers to input volatility.
- Part L Building Regulations compliance costs:Thermal imaging documentation and electromagnetic compatibility testing add 12-18% to product development budgets for smaller fixture manufacturers.
- Solar-hybrid substitution in off-grid segments:Standalone photovoltaic pathway systems are capturing park and rural applications where grid connection costs previously justified conventional LED investment.
Strategic Opportunities
- Wales and Northern England underpenetration:County councils outside England's metropolitan cores lag in smart-control deployment, presenting first-mover advantages for connected roadway systems.
- CE-UKCA dual certification services:Post-Brexit marking complexity creates advisory revenue streams for testing houses guiding mid-tier manufacturers through electromagnetic compatibility validation.
- LiDAR-traffic camera convergence:Intersection luminaire poles are becoming mounting infrastructure for autonomous vehicle navigation sensors, opening new hardware integration contracts.
Industry Challenges
- BSI Kitemark testing backlog:Thermal management validation queues at accredited laboratories now extend 14-16 weeks, delaying product launches for seasonal tender windows.
- Legacy sodium inventory stranding:Municipalities with recently replaced high-pressure sodium assets face political resistance to second-generation LED upgrades despite efficacy gaps.
- Smart platform interoperability:Proprietary control protocols from competing vendors prevent unified city-wide management systems, fragmenting maintenance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Outdoor LED Lighting Market |
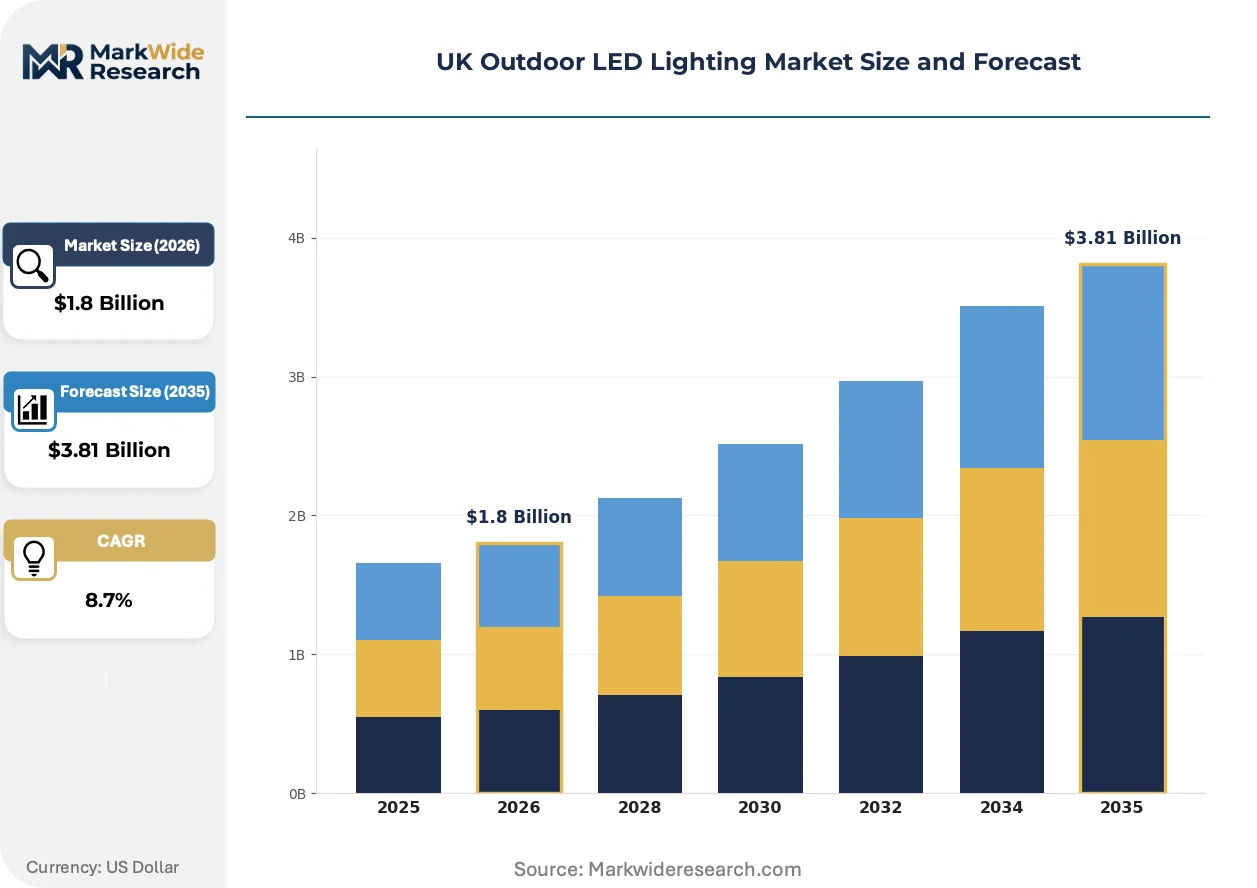
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, Bollard Lights, Wall Lights Technology: Smart LED, Solar LED, Traditional LED, Dimmable LED Application: Parks, Roadways, Parking Lots, Sports Facilities End User: Municipalities, Commercial Properties, Residential Areas, Industrial Sites |
| Companies Covered | Signify N.V., Zumtobel Group AG, TRILUX, Acuity Brands Lighting, Inc., ams-OSRAM AG, Hubbell Incorporated, Dialight PLC, Schréder Group, Philips Lighting UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Outdoor LED Lighting Market Trends and Innovations
Connected control architectures are displacing passive luminaire specifications across UK municipal tenders. Procurement teams now weight remote dimming and fault detection capabilities above raw efficacy metrics, reshaping vendor qualification criteria.
Tunable white LED systems with circadian rhythm programming are fragmenting the traditional street lighting category. NHS trusts and university campuses in Sheffield and Bristol are specifying dynamic colour temperature ranges for pedestrian zones. This capability compression is forcing pure roadway specialists to develop human-centric lighting competencies or exit mixed-use tenders.
The UK government's Part L Building Regulations 2023 amendments now mandate glare control metrics alongside efficacy minimums. Specifiers must document Unified Glare Rating calculations for all public realm installations. Industrial site applications in the Midlands are responding by adopting batwing optic designs previously reserved for premium architectural segments.
Framework aggregation is consolidating buyer power across England's combined authorities. Greater Manchester's ten-district joint procurement now represents single-entry access to 2.1 million luminaire installation opportunities. Tier-two contractors without national maintenance coverage are retreating to parish council and private estate niches where OJEU thresholds do not apply.
UK Outdoor LED Lighting Market Segmentation
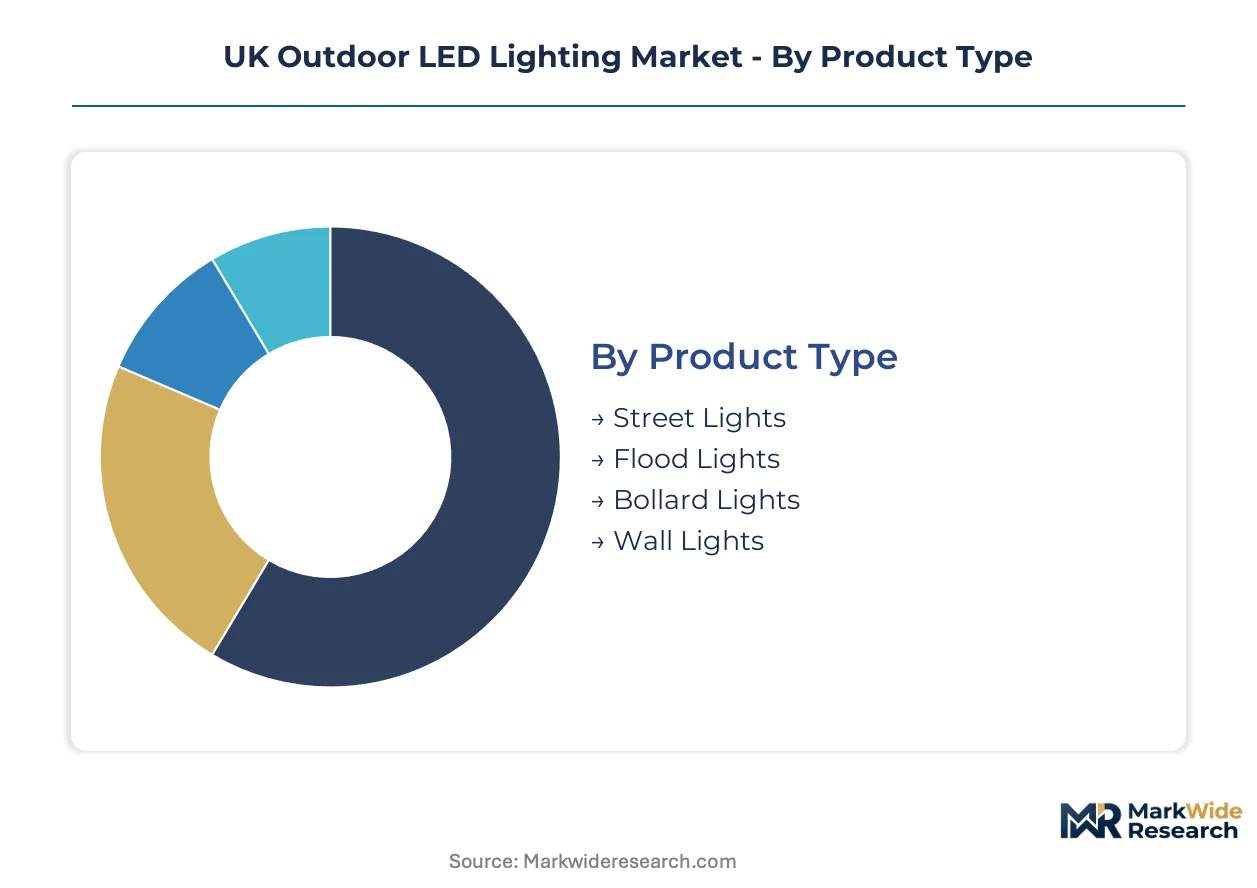
Segmentation in the UK outdoor LED lighting sector reveals how procurement channels, technical specifications, and end-use requirements fragment demand across distinct commercial pathways. Understanding these divisions illuminates where margin pools concentrate and which integration strategies unlock framework contract access.
Product Type:
Channel flows diverge sharply: street and flood luminaires move through municipal framework agreements with 25-year maintenance bundles, while bollard and wall fixtures distribute via electrical wholesalers serving private estate contractors.
- Street Lights:These high-output roadway luminaires deploy aluminium heat sinks and IP66-rated enclosures engineered for 130+ lumens per watt efficacy. Demand concentrates across Greater Manchester and Birmingham's metropolitan replacement programmes, where the Department for Transport's Street Lighting Framework mandates smart-control compatibility as a baseline qualification.
- Flood Lights:High-intensity area illumination systems employ precision optics and advanced thermal management for industrial site and sports facility applications. Procurement flows through hazardous-area certification requirements that anchor Dialight PLC's position in petrochemical and mining installations across the Midlands.
- Bollard Lights:Low-level pedestrian pathway fixtures with vandal-resistant polycarbonate diffusers serve park and campus applications where human-centric lighting specifications are emerging.
- Wall Lights:Compact facade-mounted units with downward-facing optics address residential estate and commercial perimeter security requirements through merchant distribution channels.
By volume, Street Lights leads. By growth pace, Flood Lights is ahead.
Technology:
Cost tiers separate technology adoption: smart-enabled systems command premium municipal pricing through bundled sensor integration, while traditional LED competes on first-cost efficiency in budget-constrained parish council tenders.
- Smart LED:Connected architectures enabling remote dimming, fault monitoring, and air quality sensor integration now dominate metropolitan authority tenders. NHS trusts in Sheffield and Bristol specify tunable white variants with circadian programming for pedestrian zones.
- Solar LED:Standalone photovoltaic systems with battery storage capture park and rural pathway applications where grid connection costs previously justified conventional infrastructure investment.
- Traditional LED:Passive luminaire specifications without network connectivity serve residual high-pressure sodium replacement cycles in counties with constrained capital budgets.
- Dimmable LED:Basic brightness adjustment capabilities address energy management requirements in commercial parking facilities without full smart-city platform investment.
Smart LED holds the dominant revenue share. Solar LED is expanding most quickly in off-grid segments.
Application:
Geography shapes application demand: England's combined authorities concentrate roadway and parking procurement through aggregated frameworks, while Wales and Northern England counties lag in smart-control deployment.
- Roadways:Arterial and residential street networks constitute the core volume driver, with Greater Manchester's ten-district joint procurement representing single-entry access to 2.1 million luminaire opportunities.
- Parking Lots:Commercial and municipal garage illumination increasingly bundles with EV charging infrastructure and LiDAR-traffic camera convergence for autonomous vehicle navigation support.
- Parks:Recreational and pathway lighting applications face substitution pressure from solar-hybrid systems in remote or heritage-sensitive locations.
- Sports Facilities:Stadium and training ground floodlighting requires broadcast-quality colour rendering and glare control metrics mandated by Part L Building Regulations amendments.
Roadways dominates installation volumes. Parking Lots shows the steepest expansion trajectory through sensor convergence.
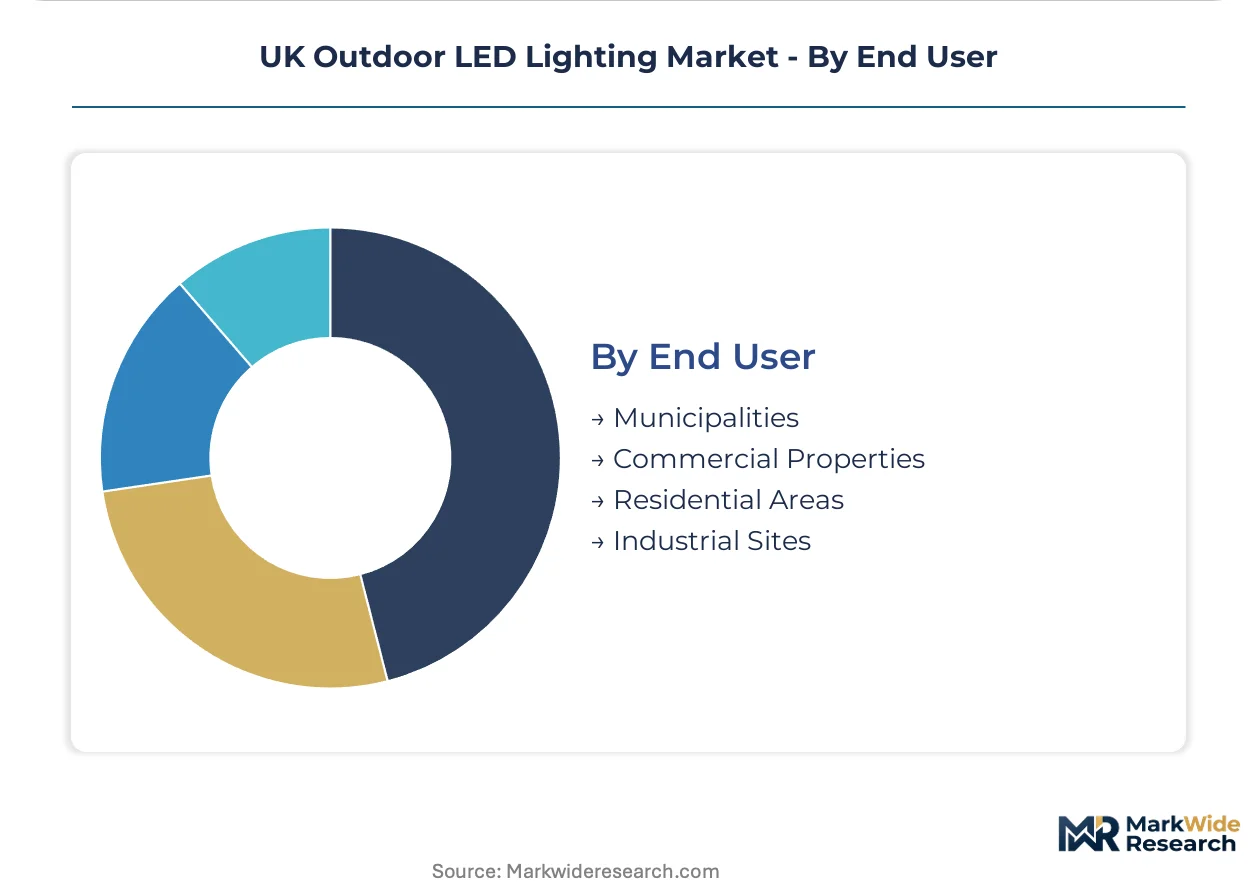
End User:
Customer type determines procurement mechanics: municipalities deploy OJEU-compliant frameworks favouring national maintenance coverage, while commercial and industrial buyers prioritise hazardous-area certifications and shorter payback periods.
- Municipalities:England's metropolitan authorities, county councils, and district councils represent the dominant demand channel through framework agreements that bundle luminaire supply with 25-year maintenance obligations.
- Industrial Sites:Petrochemical, mining, and manufacturing facilities in the Midlands require ATEX and IECEx certified fixtures with specialised thermal management for hazardous atmospheres.
- Commercial Properties:Retail parks, logistics hubs, and office campuses specify lighting through facilities management contractors with shorter replacement cycles than municipal portfolios.
- Residential Areas:Private estates and housing association developments source through electrical wholesalers outside OJEU thresholds, enabling tier-two contractor participation.
Municipalities lead by contract value. Industrial Sites are gaining share fastest through hazardous-area specialisation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan authorities in Greater Manchester command pricing premiums that county councils in Wales cannot match, creating a two-tier procurement landscape across the United Kingdom. This asymmetry concentrates smart-control deployment in England's combined authorities while leaving peripheral regions dependent on passive LED specifications.
Greater Manchester
The ten-district joint procurement programme represents the UK's largest consolidated lighting tender, bundling 2.1 million luminaire installations with 25-year maintenance obligations. The Department for Transport's Street Lighting Framework mandates smart-control compatibility as a baseline qualification. Manchester City Council's Smart City Programme is integrating air quality sensors and traffic monitors into roadway lighting infrastructure.
Birmingham
England's second-largest metropolitan authority is accelerating fixture replacement cycles through aggregated framework agreements that favour national service coverage. Birmingham City Council's Highways Maintenance Programme aligns with Part L Building Regulations 2023 amendments requiring glare control documentation. The West Midlands Combined Authority is piloting LiDAR-traffic camera convergence on intersection luminaire poles for autonomous vehicle navigation support.
Wales
County councils outside England's metropolitan cores lag in smart-control deployment, presenting first-mover advantages for connected roadway systems. The Welsh Government's energy efficiency standards follow UK-wide MEES requirements but lack equivalent procurement aggregation mechanisms. Cardiff Council's street lighting replacement programme remains fragmented across 22 principal areas with inconsistent tender specifications.
Scotland
Local authorities in Glasgow and Edinburgh are advancing LED retrofits through Scotland's Energy Efficiency Programme, though framework structures remain less consolidated than English combined authorities. Transport Scotland's street lighting guidance references UKCA marking and BSI Kitemark certification requirements. Glasgow City Council is deploying tunable white systems with circadian programming for NHS trust pedestrian zones.
Northern England
Former industrial centres in Yorkshire and the North East are replacing legacy high-pressure sodium assets through regional framework contracts. Leeds City Council and Sheffield City Council participate in the Yorkshire Purchasing Organisation's aggregated lighting tenders. South Yorkshire's Mayoral Combined Authority is bundling EV charging infrastructure with parking lot illumination upgrades.
UK Outdoor LED Lighting Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UK outdoor LED lighting sector. Signify N.V. leverages captive LED chip production to control cost structures, while Dialight PLC anchors premium positioning through hazardous-area certifications. The market structure separates into three strategic tiers: vertically integrated multinationals with semiconductor fabrication, specialized industrial fixture manufacturers, and regional assemblers dependent on outsourced components. Competitive moves concentrate on framework contract aggregation and smart-platform interoperability alliances.
Among Netherlands-based lighting multinationals, Signify N.V. exemplifies the captive-production archetype that dominates municipal framework procurement. Dialight PLC and Schréder Group represent contrasting specializations—British hazardous-area certification expertise against Belgian municipal contracting scale—that fragment competitive positioning across industrial site and roadway applications respectively.
| Leading Market Players |
|---|
| Signify N.V. |
| Zumtobel Group AG |
| TRILUX |
| Acuity Brands Lighting, Inc. |
| ams-OSRAM AG |
| Hubbell Incorporated |
| Dialight PLC |
| Schréder Group |
| Philips Lighting UK |
| Others |
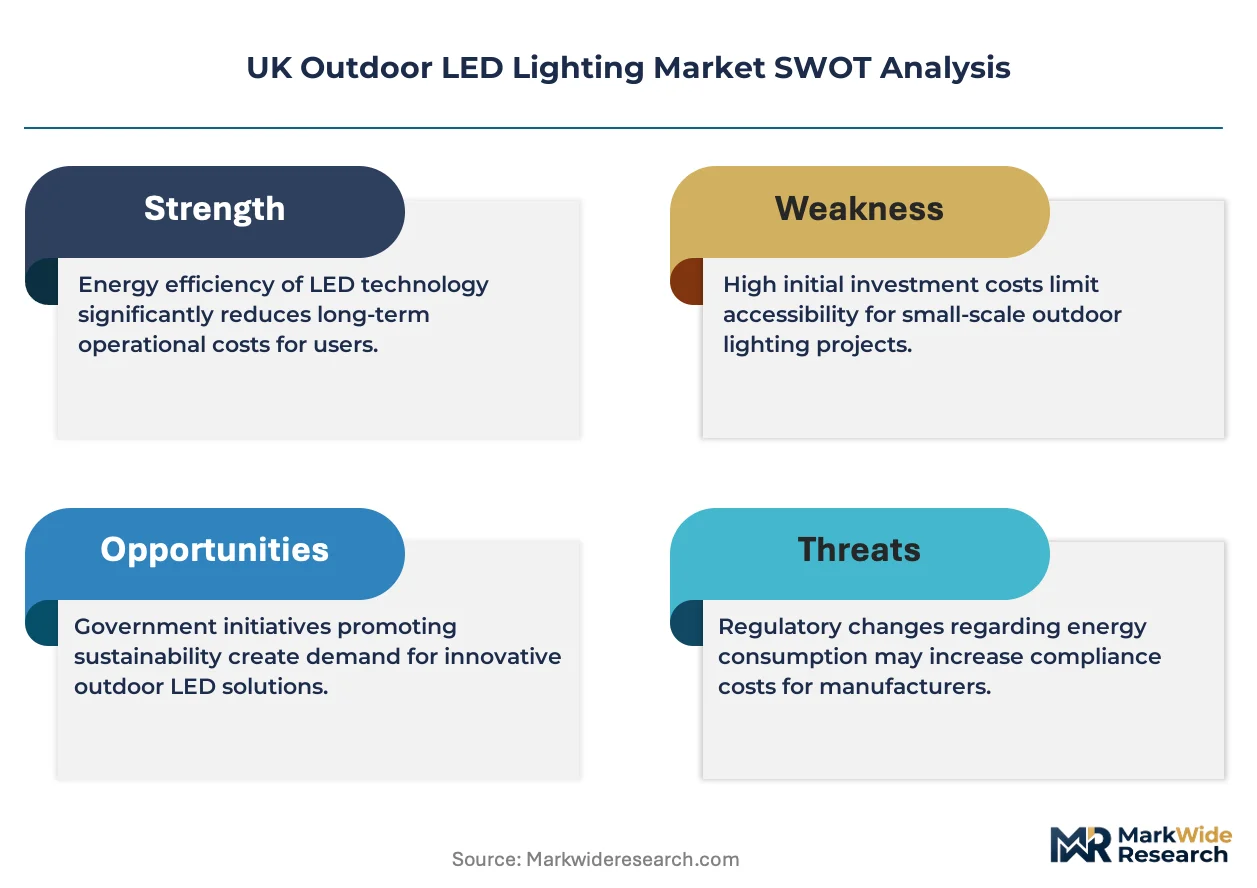
Pricing and Supply Chain Analysis
Captive LED chip production at Signify N.V. and ams-OSRAM AG establishes asymmetric scale economies that compress price floors for UK luminaire assemblers while elevating margin capture for vertically integrated multinationals. This concentration cascades through municipal framework procurement, where 25-year maintenance bundling amplifies pricing power for vendors with in-house semiconductor fabrication.
Pricing Analysis
Configured-to-order pricing for smart-enabled street luminaires with sensor integration commands substantial premiums over standard passive LED specifications. Three-tier pricing structure across premium smart-control systems, standard connected fixtures, and economy passive units separates vendors by certification grade and after-sales service scope. Cost compression in economy tiers is intensifying because East Asian foundry capacity constraints limit component availability for smaller assemblers. Parish councils and private estate contractors exhibit highest price sensitivity, while metropolitan authorities prioritize lifecycle value over first-cost efficiency.
Supply Chain Analysis
Strategic stockpiling of GaN-on-silicon wafers and aluminium heat sinks dominates inventory strategy among tier-one vendors confronting East Asian foundry lead time volatility. Semiconductor substrates concentrate in Taiwan and South Korea, while precision aluminium extrusion for thermal management feeds from Germany and domestic UK fabrication. UK luminaire assemblers draw from Chinese component suppliers for driver electronics and polycarbonate optical diffusers. Single-source vulnerability in advanced LED chip substrates exposes the sector to input disruption. Distribution runs through OJEU-compliant framework agreements for municipal volumes and electrical wholesale channels for private estate contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK outdoor LED lighting market functions as a service-attach opportunity where 25-year maintenance obligations and smart-platform subscriptions expand recurring revenue faster than hardware replacement cycles. Municipal framework procurement increasingly weights national service coverage above unit pricing, elevating long-term contract economics.
For Market Incumbents: Consolidate framework contract aggregation through exclusive maintenance network coverage across England's combined authorities. Deepen captive chip production scale to offset East Asian foundry price volatility threatening margin structures. Acquire regional service contractors in Wales and Northern England to preempt emerging entrant platform plays. For New Entrants and Emerging Players: Maintenance service gaps in Welsh county councils and Northern English parish councils offer white-space entry points where national incumbents lack localized response capabilities. Solar-hybrid pathway systems in heritage-sensitive park applications present penetrable segments with limited established vendor presence. Pursue CE-UKCA dual certification advisory services as a low-capital go-to-market angle for mid-tier manufacturers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized industrial fixture manufacturers with hazardous-area certification moats over commodity roadway assemblers. Five-to-ten year viability hinges on smart-control interoperability rather than proprietary protocol lock-in. Monitor BSI Kitemark testing queue lengths as inflection indicator for product launch velocity and seasonal tender capture rates.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Platform Interoperability Alliance | Unified city-wide management systems fragment maintenance contracts across competing proprietary protocols. |
| Backward Integration into GaN-on-Silicon Capacity | Captive wafer supply insulates cost structures from East Asian foundry concentration risk. |
| LiDAR-Traffic Camera Hardware Integration | Intersection luminaire poles become mounting infrastructure for autonomous vehicle navigation sensors. |
| CE-UKCA Dual Certification Service Expansion | Post-Brexit marking complexity creates advisory revenue streams for electromagnetic compatibility validation. |
| Wales and Northern England First-Mover Deployment | County councils outside metropolitan cores lag in smart-control deployment, presenting connected system advantages. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal procurement officers, facilities management contractors, lighting manufacturer product managers, and electrical wholesale distribution heads. Secondary validation drew from Department for Transport Street Lighting Framework documentation, Part L Building Regulations amendments, BSI Kitemark certification records, and OJEU tender award notices. Bottom-up luminaire volume estimates triangulated against top-down municipal capital expenditure projections across England's combined authorities.
Across the analysis window, forecasts model product type segmentation by street, flood, bollard and wall fixture categories; technology tiers separating smart LED, solar LED, traditional and dimmable systems; application splits across roadways, parking lots, parks and sports facilities; and end-user distinctions between municipalities, industrial sites, commercial properties and residential areas. CAGRs derive from replacement cycle velocity, regulatory efficacy mandate tightening schedules, and smart city sensor convergence adoption curves. Specific inputs include MEES standards implementation timelines and metropolitan authority framework aggregation patterns.
Underlying assumptions cover continued Part L efficacy requirement tightening, stable East Asian semiconductor foundry capacity allocation, and sustained municipal budget availability for 25-year maintenance bundling, with deviation risk concentrated in GaN-on-silicon supply disruption and solar-hybrid substitution acceleration in off-grid segments. Revision becomes warranted when BSI Kitemark testing queue durations exceed seasonal tender windows or when proprietary smart-control protocol fragmentation prevents unified city-wide management system deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
North America Commercial LED Lighting Market
LED
India LED Outdoor Lighting Market
LED
Gan Micro LED Market
LED
United States Micro LED Market
LED
US and Europe LED Lighting Market
LED
China LED Lighting Market
LED
LED Digital Scoreboard Market
LED
Global Waterproof LED Module Market
LED
LED Services Market
LED
Monochrome Outdoor LED Display Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
India LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
LED Power Supplies Market
LED
7 Segment LED Displays Market
LED
North America LED Lighting Market