
 Quantum Cascade Lasers Market | 2026-2036
Quantum Cascade Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Quantum Cascade Lasers Market Analysis
United States manufacturing capacity for quantum cascade lasers is tilting toward defense-aerospace integration. Alpes Lasers leverages its Swiss heritage to sustain leadership in custom epitaxial designs for spectroscopy. Block Engineering anchors North American supply through specialized chemical detection platforms. Hamamatsu Photonics K.K. dominates photonics component channels with vertically controlled detector-laser pairing.
Quantum cascade lasers are semiconductor devices built from alternating layers of gallium arsenide and aluminum gallium arsenide that generate coherent mid-infrared light through intersubband transitions, typically operating at wavelengths from 3 to 25 micrometers for molecular fingerprinting. Their primary commercial purpose centers on trace gas detection where absorption signatures are strongest in the mid-infrared atmospheric window. Distributed feedback lasers command premium positioning due to single-mode stability required for precision spectroscopy, while sensing applications outpace optical communications in absolute growth as industrial safety mandates proliferate. Edge-emitting architectures occupy mature volume tiers despite thermal management constraints that vertical cavity formats are engineered to address.
FDA device classification rules shape medical imaging system entry pathways for QCL-based diagnostic platforms, while EPA compliance protocols for continuous emissions monitoring directly specify tunable laser performance thresholds. ISO 10110 optical drawing standards govern substrate specifications across international procurement chains. Stakeholders must weigh dual-use export control alignment against commercial spectroscopy scaling as semiconductor fabrication investments mature.
Market Dynamics
Defense procurement cycles in the United States are compressing development timelines for infrared countermeasure systems, pulling epitaxial foundry capacity toward military specifications and away from commercial spectroscopy customers.
Growth Catalysts
- EPA continuous emissions mandates:Stack gas monitoring regulations now require tunable laser absorption spectroscopy for real-time pollutant quantification, forcing utility and petrochemical operators to upgrade legacy analyzer fleets.
- Germany:Fraunhofer institutes anchor a dense cluster of applied spectroscopy research, transferring intersubband physics directly into industrial OEM roadmaps for process analytics.
- DFB architecture maturation:Distributed feedback quantum cascade lasers achieve single-mode stability at watt-scale output, unlocking precision molecular fingerprinting for pharmaceutical quality control lines.
Market Restraints
- MBE equipment concentration:Molecular beam epitaxy reactor supply concentrates among a handful of European and Japanese vendors, creating multi-year lead times for capacity expansion.
- Indium phosphide substrate costs:InP wafer pricing volatility constrains cost-down trajectories for mid-infrared devices targeting price-sensitive environmental monitoring deployments.
- Fourier-transform infrared substitution:Benchtop FTIR systems retain cost advantages for non-continuous analysis, limiting QCL penetration in academic and small-laboratory settings.
Strategic Opportunities
- India industrial safety mandates:Central Electricity Authority regulations are tightening leak detection requirements at petrochemical complexes, opening import substitution pathways for mid-infrared analyzer suppliers.
- Vertical cavity surface-emitting convergence:VCSEL-derived thermal management architectures promise to relax packaging constraints currently limiting high-duty-cycle operation in portable field instruments.
- CE-IVD regulatory pathway:The EU Medical Device Regulation creates a harmonized certification route for QCL-based breath analysis platforms targeting metabolic disease screening.
Industry Challenges
- Intersubband physics talent scarcity:Quantum engineering programs produce fewer device physicists than foundry expansion requires, elongating R&D cycle times for custom wavelength designs.
- ISO 10110 substrate qualification:Optical drawing standard compliance for defense-aerospace supply chains demands extended metrology protocols that compress gross margins on small-batch contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quantum Cascade Lasers Market |
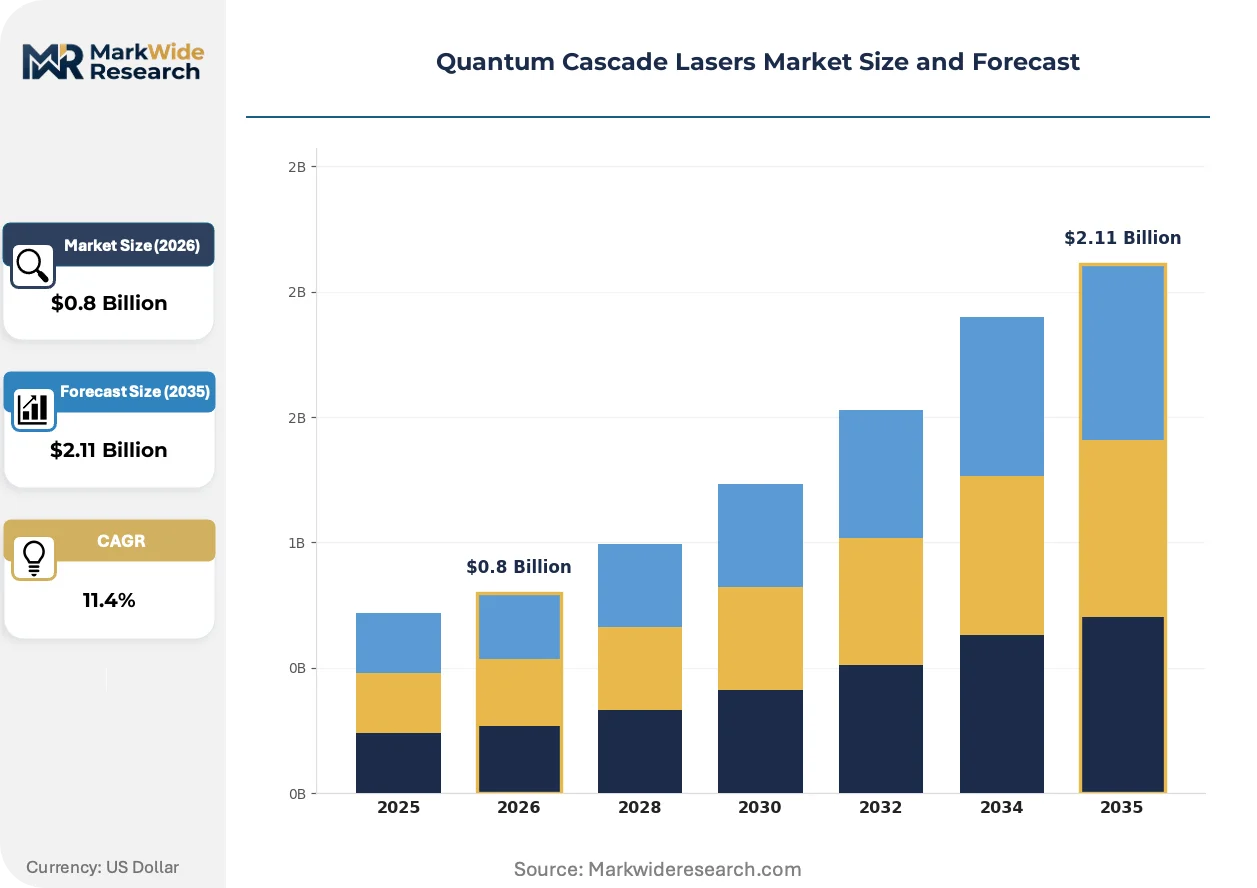
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $2.11 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surface-Emitting Lasers, Edge-Emitting Lasers, Vertical Cavity Lasers, Distributed Feedback Lasers Technology: Optical Communications, Sensing Applications, Spectroscopy, Imaging Systems End User: Aerospace, Telecommunications, Medical Devices, Research Institutes Application: Environmental Monitoring, Gas Analysis, Industrial Process Control, Defense |
| Companies Covered | Emerson Electric Co., Alpes Lasers, Thorlabs, Inc., Akela Laser Corporation, nanoplus Nanosystems and Technologies GmbH, Hamamatsu Photonics K.K., Block Engineering, Wavelength Electronics, Inc., MirSense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quantum Cascade Lasers Market Emerging Trajectories
Packaging architectures and regulatory compliance protocols are converging to redefine competitive advantage, with thermal management and certification speed displacing raw wavelength coverage as primary buying criteria.
Monolithic beam-steering integration is rendering obsolete external mechanical choppers and scanning mirrors in standoff chemical detection systems. Defense integrators in the United States are specifying chip-scale steering for next-generation infrared countermeasure pods. This compression of optical train complexity is collapsing subsystem supplier tiers and concentrating value capture at the epitaxial device level.
REACH chemical authorization procedures are tightening substance restrictions on gallium and indium compounds used in III-V epitaxy, forcing European foundries to document alternative precursor chemistries in regulatory dossiers. The burden falls heaviest on custom wavelength houses serving pharmaceutical analytical instrument OEMs, who must now dual-source qualified material streams to maintain CE-marked product lines.
Analyzer procurement is consolidating under integrated service contracts that bundle hardware, calibration gas, and predictive maintenance subscriptions. Petrochemical operators in the Texas Gulf Coast and Rotterdam harbor districts are shifting capital expenditure to operational expenditure models, favoring vendors with captive field service organizations over pure-play device manufacturers. This unbundling of equipment from service is compressing pricing transparency and locking incumbents into multi-year sole-source relationships.
Quantum Cascade Lasers Market Segmentation
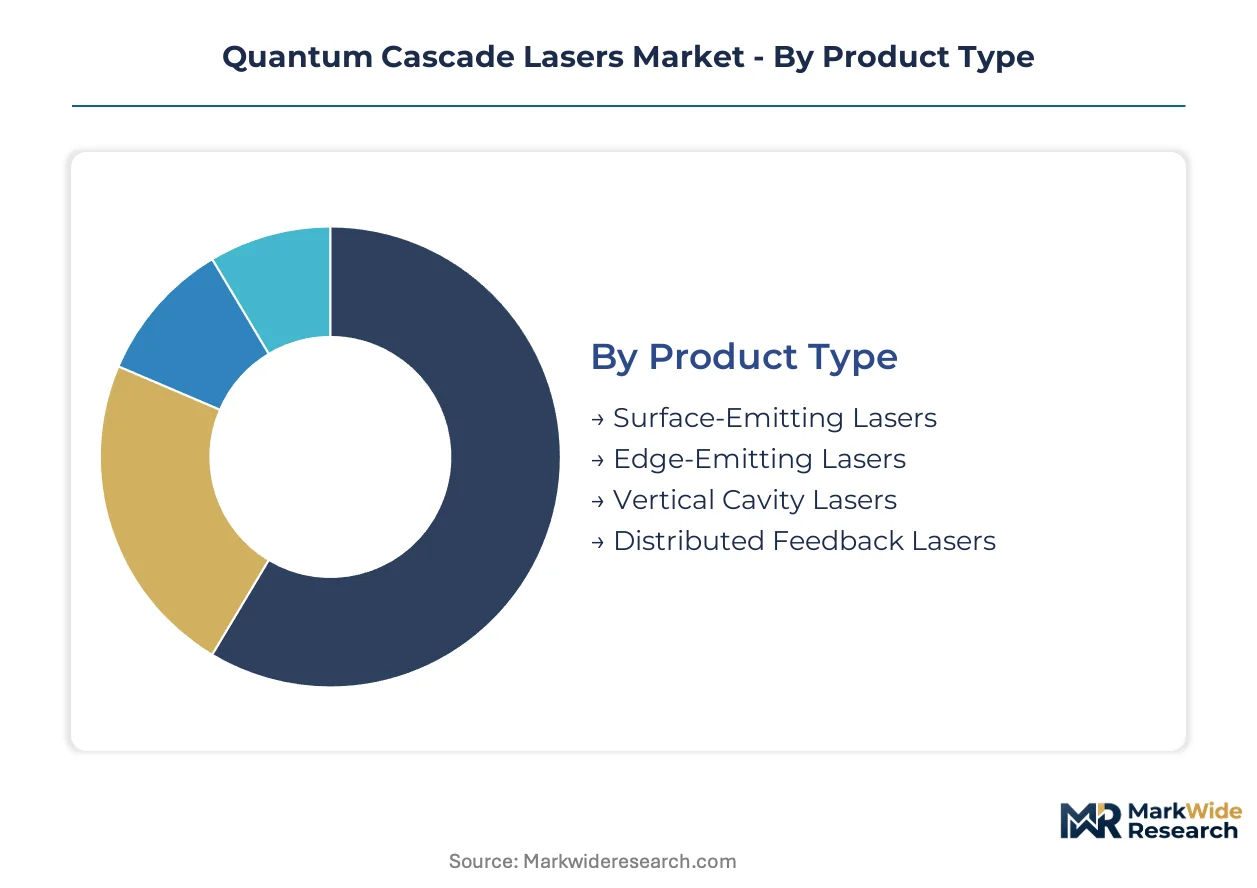
Segmentation in quantum cascade lasers reveals how technology choices lock customers into distinct procurement cycles. Product architecture determines thermal management requirements, while end-use verticals impose divergent certification timelines that reshape vendor priorities.
Product Type:
Cycle times vary dramatically across architectures, with defense-aerospace procurement compressing development for edge-emitting formats while spectroscopy customers tolerate longer lead times for distributed feedback precision.
- Distributed Feedback Lasers:Bragg grating structures enforce single-mode operation at specific wavelengths through precise intersubband transition engineering. Pharmaceutical quality control lines in Germany and the United States now specify DFB sources for real-time reaction monitoring, though molecular beam epitaxy reactor bottlenecks stretch delivery schedules to 18-24 months.
- Edge-Emitting Lasers:Fabry-Perot cavities emit from cleaved crystal facets, delivering higher output powers at the cost of multimode spectral content. United States defense contractors are pulling epitaxial foundry capacity toward military specifications for infrared countermeasure pods, accelerating volume turnover despite thermal management constraints in high-duty-cycle operation.
- Vertical Cavity Lasers:Distributed Bragg reflectors perpendicular to the substrate plane enable surface-normal emission with superior beam quality.
- Surface-Emitting Lasers:Grating-coupled or photonic crystal architectures extract light from the chip surface for compact packaging in portable field instruments.
Distributed feedback lasers anchor the volume base while vertical cavity formats gain share at the steepest rate as thermal management architectures mature.
Technology:
Application pull determines which physics packages command premium positioning, with sensing and spectroscopy outpacing optical communications in absolute growth as regulatory mandates proliferate.
- Sensing Applications:Tunable laser absorption spectroscopy platforms detect trace gases through molecular fingerprinting in the mid-infrared atmospheric window. EPA continuous emissions monitoring mandates now require real-time stack gas analysis at United States petrochemical facilities, forcing utility operators to upgrade legacy analyzer fleets and concentrate procurement under integrated service contracts.
- Spectroscopy:High-resolution molecular absorption studies demand wavelength stability across temperature excursions and vibration environments. Fraunhofer institutes in Germany anchor applied research clusters that transfer intersubband physics directly into industrial OEM roadmaps for process analytics and pharmaceutical quality control.
- Imaging Systems:Thermal cameras and standoff chemical detection exploit atmospheric transmission windows for long-range identification.
- Optical Communications:Free-space links and fiber-coupled transmission leverage mid-infrared transparency for specialized military and scientific networks.
Sensing applications dominate current procurement volumes while spectroscopy climbs fastest as industrial safety mandates tighten across European and North American jurisdictions.
End User:
Customer type segmentation exposes how certification requirements fragment addressable markets, with medical device pathways stretching timelines while defense procurement compresses them.
- Aerospace:Infrared countermeasure systems and standoff chemical detection pods demand ruggedized packaging for vibration and temperature extremes. United States defense integrators are specifying chip-scale beam steering for next-generation pods, collapsing subsystem supplier tiers and concentrating value capture at the epitaxial device level.
- Medical Devices:Breath analysis platforms for metabolic disease screening must navigate FDA device classification rules and the EU Medical Device Regulation harmonized certification route. CE-IVD regulatory pathways create structured entry points for QCL-based diagnostic platforms, though clinical validation cycles extend commercialization timelines.
- Research Institutes:Academic laboratories and national facilities drive custom wavelength development for fundamental spectroscopy studies.
- Telecommunications:Specialized fiber and free-space links serve scientific and military communication networks with limited commercial scale.
Aerospace anchors near-term revenue concentration while medical devices expand most quickly as CE-IVD pathways mature and breath analysis platforms approach clinical validation.
Application:
Use-case segmentation maps directly onto regulatory jurisdiction, with environmental mandates in the United States and industrial safety requirements in India reshaping geographic demand concentration.
- Environmental Monitoring:Continuous stack gas analysis for EPA compliance requires tunable laser absorption spectroscopy with specified performance thresholds. Petrochemical operators on the Texas Gulf Coast are shifting capital expenditure to operational expenditure models, favoring vendors with captive field service organizations over pure-play device manufacturers.
- Defense:Infrared countermeasure systems and standoff chemical detection represent the highest unit value segment. Procurement cycles are compressing development timelines and pulling epitaxial foundry capacity toward military specifications, creating supply tension for commercial spectroscopy customers.
- Gas Analysis:Process analytics and leak detection serve petrochemical, pharmaceutical, and utility verticals with varying duty cycle requirements.
- Industrial Process Control:Real-time reaction monitoring and quality assurance lines integrate QCL sources for pharmaceutical manufacturing.
Environmental monitoring commands the largest installed base while defense procurement delivers the steepest value expansion as infrared countermeasure specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Epitaxial foundry capacity concentrates among Swiss precision houses, German Fraunhofer-affiliated institutes, and United States defense-aerospace integrators. This geographic clustering shapes wavelength availability and delivery timelines across application verticals.
United States
Defense contractors compress procurement cycles for infrared countermeasure systems, pulling molecular beam epitaxy capacity toward military specifications. EPA continuous emissions monitoring mandates require tunable laser absorption spectroscopy at petrochemical facilities on the Texas Gulf Coast. Houston-area operators now favor integrated service contracts bundling hardware, calibration gas, and predictive maintenance subscriptions.
Germany
Fraunhofer institutes anchor applied spectroscopy research clusters that transfer intersubband physics directly into industrial OEM roadmaps. REACH chemical authorization procedures tighten substance restrictions on gallium and indium compounds, forcing foundries to document alternative precursor chemistries. Munich and Berlin-Brandenburg regions concentrate pharmaceutical quality control line deployments specifying distributed feedback sources.
Switzerland
Custom epitaxial design houses sustain leadership in precision wavelength engineering for molecular fingerprinting applications. Swissmedic medical device pathways create structured certification routes for diagnostic platforms, though clinical validation cycles extend commercialization timelines. Neuchâtel-Jura microtechnology corridor hosts vertically integrated device physics specialists serving European analytical instrument OEMs.
Japan
Photonics component channels dominate through vertically controlled detector-laser pairing architectures. METI industrial technology roadmaps prioritize mid-infrared sensing for manufacturing process analytics. Hamamatsu-Tokyo corridor concentrates packaging expertise for high-duty-cycle portable field instruments targeting environmental monitoring deployments.
India
Central Electricity Authority regulations tighten leak detection requirements at petrochemical complexes, opening import substitution pathways for mid-infrared analyzer suppliers. BIS standards alignment creates compliance entry barriers for foreign equipment vendors. Gujarat and Maharashtra industrial corridors concentrate demand for continuous stack gas analysis as utility operators upgrade legacy analyzer fleets.
Quantum Cascade Lasers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling epitaxial design and detector pairing. The vendor base organizes around three archetypes: defense-aerospace integrators compressing development timelines, spectroscopy platform builders bundling hardware with predictive maintenance subscriptions, and precision wavelength houses serving custom analytical instrument OEMs. Competitive moves concentrate on captive field service organization expansion and monolithic beam-steering integration that collapses subsystem supplier tiers.
Among Swiss-German precision fabricators, Alpes Lasers and nanoplus Nanosystems and Technologies GmbH exemplify the custom wavelength archetype anchored to Fraunhofer research transfer channels. United States-based Block Engineering occupies a position within the chemical detection platform tier, while Hamamatsu Photonics K.K. represents the vertically integrated photonics component model. These three anchors illustrate how geographic clustering around epitaxial foundry capacity, defense procurement gravity, and analytical instrument OEM relationships shapes competitive positioning.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Alpes Lasers |
| Thorlabs, Inc. |
| Akela Laser Corporation |
| nanoplus Nanosystems and Technologies GmbH |
| Hamamatsu Photonics K.K. |
| Block Engineering |
| Wavelength Electronics, Inc. |
| MirSense |
| Others |
Supply Flow & Price Mechanics
Molecular beam epitaxy reactor undercapacity across European and Japanese foundries compresses delivery schedules to 18-24 months, forcing buyers into long-term offtake commitments that lock in premium pricing tiers and reshape supplier bargaining power.
Pricing Analysis
EPA continuous emissions monitoring mandates dictate the pricing tier structure across environmental analyzer procurement, separating bundled service contracts from bare-hardware transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 10110-compliant defense-aerospace tiers commanding substantial premiums over commercial spectroscopy units. Cost compression in standard-tier environmental monitoring deployments intensifies because Fourier-transform infrared systems retain cost advantages for non-continuous analysis. Academic and small-laboratory settings exhibit the highest price sensitivity, while United States defense contractors demonstrate the least.
Supply Chain Analysis
Veeco Instruments and Riber hold dominant positions in molecular beam epitaxy reactor manufacturing, concentrating critical equipment supply among European and Japanese vendors. Switzerland, Germany, and the United States anchor epitaxial foundry capacity, with InP wafer supply drawing from Japanese and Chinese substrate producers. Single-source vulnerability in MBE equipment creates multi-year lead times for capacity expansion that constrain foundry output scaling. Distribution runs through specialized photonics component channels and integrated platform vendors serving defense-aerospace and analytical instrument OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where EPA compliance protocols and ISO 10110 substrate qualification standards create certification barriers that elongate competitor entry timelines.
For Market Incumbents: Insulate core spectroscopy margins by deepening backward integration into indium phosphide substrate supply and expanding captive field service organizations along the Texas Gulf Coast. Fourier-transform infrared substitution threats in academic settings demand tiered product-line differentiation, while ISO 10110 metrology protocol investments reinforce defense-aerospace sole-source positioning.
For New Entrants and Emerging Players: Establish a beachhead in India's industrial safety monitoring segment, where Central Electricity Authority leak detection mandates outpace domestic supply capacity. Petrochemical complexes in Gujarat and Maharashtra represent the most penetrable geography, with BIS standards alignment serving as the critical go-to-market angle for import substitution pathways.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across custom wavelength design houses as molecular beam epitaxy reactor scarcity elongates R&D cycle times. Long-term viability favors precision epitaxial specialists with Fraunhofer research transfer relationships and dual-use export control clearances. Watch MBE equipment order backlogs as the signal indicating foundry capacity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | InP wafer sourcing control mitigates pricing volatility from Japanese and Chinese producers. |
| Captive Field Service Organization Expansion | Houston-area petrochemical operators now favor operational expenditure models bundling predictive maintenance subscriptions. |
| Monolithic Beam-Steering Integration | Chip-scale steering collapses subsystem supplier tiers and concentrates value capture at the epitaxial device level. |
| Dual-Source Material Stream Qualification | REACH chemical authorization procedures force European foundries to document alternative gallium and indium precursor chemistries. |
| CE-IVD Regulatory Pathway Investment | EU Medical Device Regulation creates harmonized certification routes for QCL-based breath analysis diagnostic platforms. |
Methodological Framework
Cross-validation between primary interviews with epitaxial foundry managers, defense procurement officers, and pharmaceutical analytical instrument OEMs anchors the qualitative findings against secondary validation from EPA regulatory filings, ISO standards documentation, and SEC disclosures from listed photonics component suppliers. Bottom-up triangulation across molecular beam epitaxy reactor utilization rates and top-down calibration against environmental monitoring equipment procurement databases ensures dimensional consistency.
Calibration against historical capacity expansion cycles and defense procurement award patterns validates the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, application vertical, end-user certification pathway, and regional regulatory cluster. CAGRs derive from curve-fitting across disclosed order backlogs and foundry utilization signals, with intersubband physics talent scarcity and MBE equipment lead times serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in indium phosphide substrate pricing and defense budget appropriations would shift the trajectory. Forecasts reflect documented assumptions regarding EPA mandate enforcement timelines and REACH authorization scope expansion. Quarterly review of MBE equipment order intake and Fraunhofer institute technology transfer announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Global Optocoupler Market
Optoelectronics
Photoluminescent Film Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Global Optoelectronic Components Market