
 Oral Chemotherapy Market | 2026-2036
Oral Chemotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Chemotherapy Market Intelligence
The shift toward outcome-based reimbursement models is tilting the competitive landscape toward manufacturers with robust clinical data. Pfizer Inc. leverages its extensive clinical trial capabilities to validate efficacy for these models. Novartis AG specializes in targeted therapies that align well with pay-for-performance contracts. F. Hoffmann-La Roche Ltd. sustains its market position through a deep pipeline of personalized oncology medicines.
Oral chemotherapy involves the administration of cytotoxic or targeted anti-cancer drugs in forms like tablets or capsules. These formulations, including alkylating agents that disrupt DNA synthesis, are designed to treat various malignancies outside of a clinical infusion setting. Targeted therapies like enzyme inhibitors represent the fastest-growing product category. While breast neoplasms constitute a major application area, specialty pharmacies are becoming the primary channel for dispensing these advanced medications.
Regulatory oversight from bodies such as the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) governs market entry. These agencies, along with China's NMPA, mandate rigorous clinical trial data to ensure drug safety and efficacy before approval. Stakeholder success depends on navigating complex reimbursement pathways and ensuring patient adherence programs are effective.
Market Dynamics
The fundamental shift toward patient-centric care models is the central force shaping the oral chemotherapy market. This transition prioritizes at-home administration, driven by patient convenience and the development of targeted therapies that reduce the need for clinical infusions.
Growth Catalysts
- Targeted Therapy Advances:The development of highly specific enzyme inhibitors and other targeted agents offers improved efficacy and better tolerability profiles, encouraging physician prescription and patient acceptance over traditional intravenous chemotherapy.
- Demographic Shifts in Developed Nations:Aging populations in countries like Japan and Germany are leading to a higher incidence of cancer, spurring demand for less burdensome treatment regimens that can be managed outside of a hospital setting.
- Expansion of Specialty Pharmacy Channels:The increasing reliance on specialty pharmacies for dispensing complex oncology medications provides a dedicated infrastructure for managing patient adherence, side effects, and reimbursement, facilitating broader access.
Market Restraints
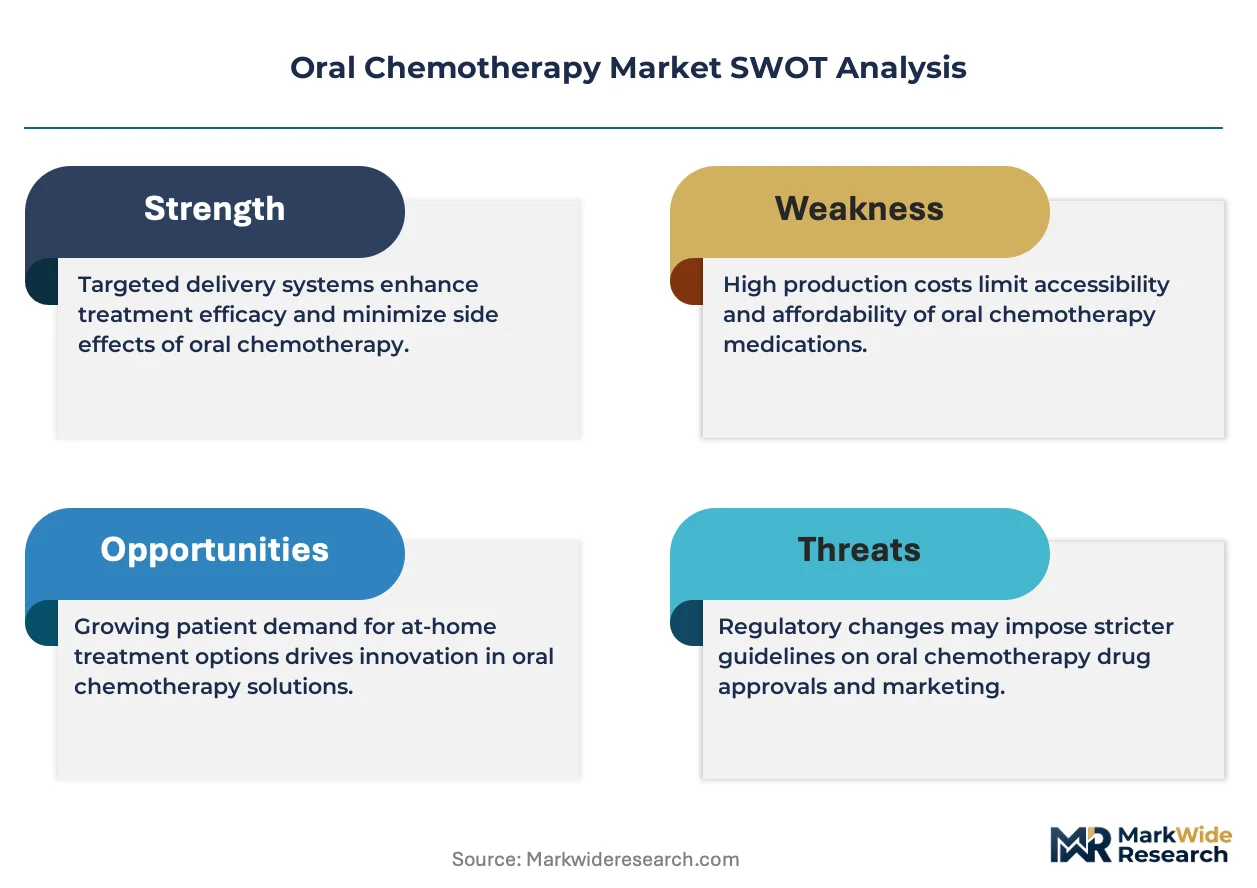
- High Drug Development Costs:The significant financial investment required for researching and developing novel targeted therapies, including extensive clinical trials for small molecule drugs, creates a high barrier to entry and contributes to premium pricing.
- Stringent Regulatory Hurdles:Navigating the rigorous approval pathways of agencies such as the US FDA, EMA, and China's NMPA demands comprehensive safety and efficacy data, leading to long development timelines and significant compliance costs.
- Patient Adherence Complexity:Ensuring patients correctly follow complex dosing schedules and manage side effects at home, without direct clinical supervision, remains a significant structural barrier to achieving optimal treatment outcomes.
Strategic Opportunities
- Emerging Market Penetration:There is a significant opportunity to expand into markets like Brazil and India, where rising healthcare spending and regulatory streamlining by bodies like ANVISA are creating a more favorable environment for advanced cancer therapies.
- Digital Health Integration:Incorporating mobile applications and wearable sensors to monitor patient adherence, track side effects, and facilitate communication with healthcare providers represents a major white-space opportunity for enhancing treatment effectiveness.
- Pediatric and Rare Cancer Formulations:Developing oral chemotherapy agents specifically for pediatric oncology and rare malignancies addresses significant unmet medical needs, offering pathways for orphan drug designations and expedited regulatory reviews.
Industry Challenges
- Complex Logistics Management:The distribution of certain oral oncolytics requires sophisticated cold chain logistics to maintain drug stability, posing an operational challenge for specialty pharmacies and distributors, especially in diverse climates.
- Reimbursement Model Navigation:Securing favorable reimbursement is a persistent challenge, as payors increasingly implement pay-for-performance contracts that require manufacturers to provide extensive real-world evidence of drug efficacy and value.
- Intensive Educational Demands:Effectively scaling the use of oral chemotherapy requires substantial investment in educating both patients and community-based healthcare providers on proper administration, side effect management, and safe handling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Chemotherapy Market |
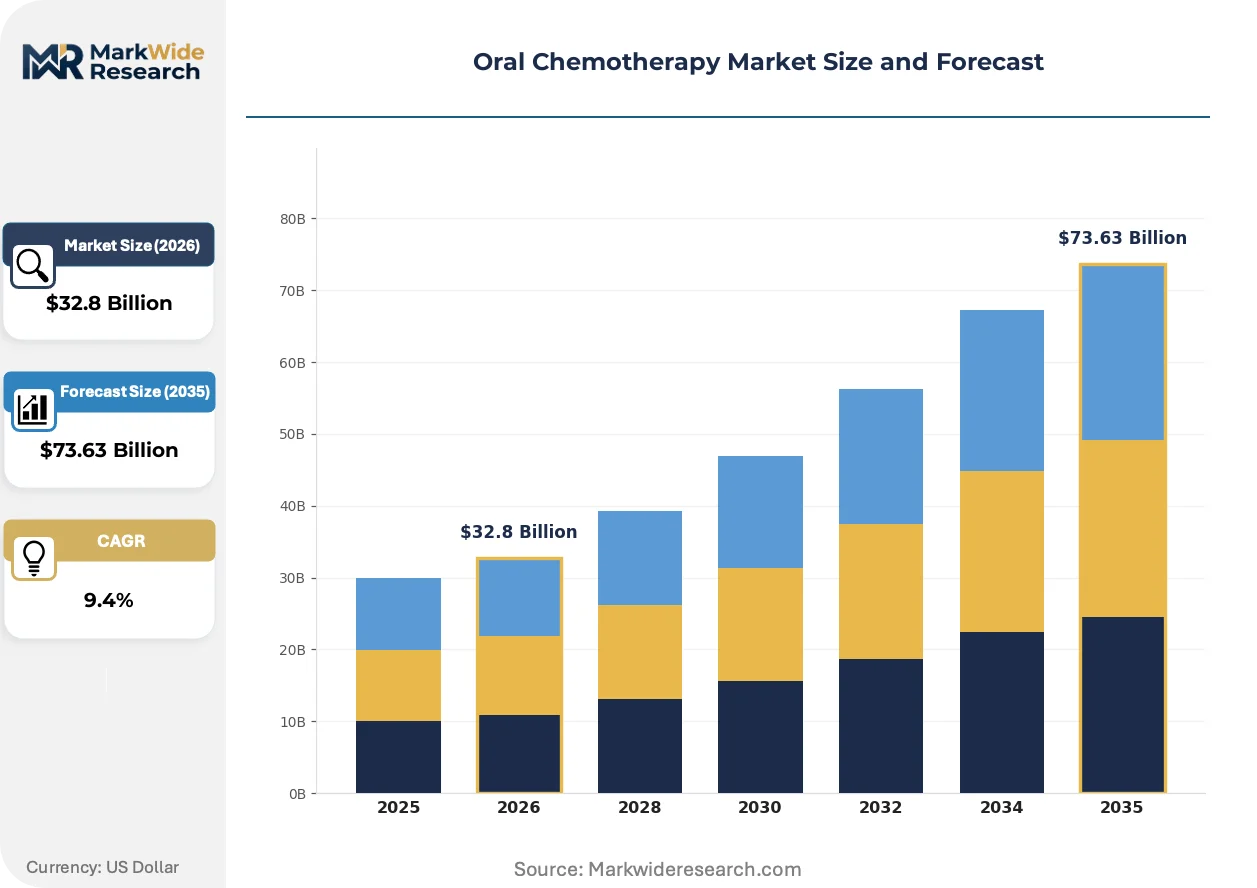
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $73.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylating Agents, Antimetabolites, Mitotic Inhibitors, Hormonal Agents, Enzyme Inhibitors Application: Hematologic Malignancies, Breast Neoplasms, Lung Carcinoma, Gastrointestinal Tumors, Gynecologic Neoplasms End User: Oncology Clinics, Specialty Pharmacies, Ambulatory Surgery Centers, Community Health Facilities, Home Healthcare Providers Delivery Mode: Capsules, Tablets, Oral Suspensions, Films, Sublingual Tablets |
| Companies Covered | Amgen Inc., Pfizer Inc., Novartis AG, Sanofi S.A., Johnson & Johnson, Merck & Co. Inc., F. Hoffmann-La Roche Ltd., Bristol-Myers Squibb, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Chemotherapy Market Strategic Shifts & Innovations
The convergence of precision medicine and patient-centric delivery is redefining the standards of cancer care. This evolution is driven by innovations that tailor treatment to individual patient biology while moving the point of care from the clinic to the home.
Companion diagnostics are tests designed to identify specific biomarkers that predict a patient's response to a particular targeted oral therapy. Major oncology centers and hospital networks are rapidly integrating these diagnostic tools into their standard treatment protocols. The use of companion diagnostics is collapsing the traditional separation between drug development and diagnostic testing, forging a unified and more effective therapeutic strategy from the outset.
The European Union's Clinical Trials Regulation (CTR) harmonizes the processes for submitting, assessing, and supervising clinical trials across all member states. This framework significantly streamlines the execution of multi-country trials, which are essential for developing oral chemotherapy drugs for genetically diverse cancer populations. The oncology drug sector is adapting its research protocols to utilize the centralized EU Portal, enabling faster and more efficient data aggregation for new drug applications.
A notable behavioral shift involves payors and health systems mandating that high-cost oral oncolytics be dispensed through a narrow network of specialty pharmacies. This model concentrates distribution and patient support, displacing the role of traditional retail pharmacies for these advanced medications. This trend is most visible in the United States, where these specialized pharmacies provide critical adherence programs and data reporting that manufacturers and insurers require.
Oral Chemotherapy Market Segmentation
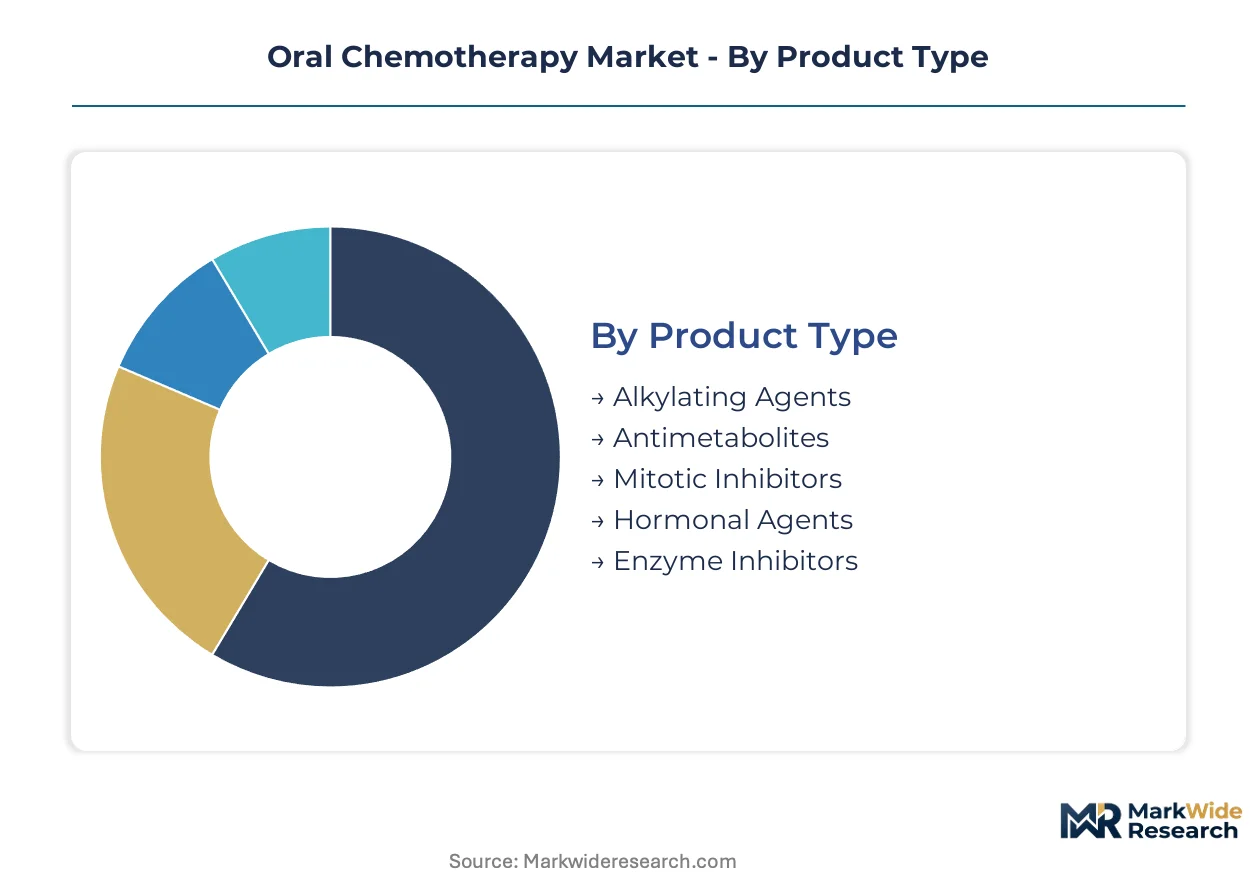
Market segmentation provides a granular view of the oral chemotherapy landscape, revealing distinct pockets of demand, technological maturity, and patient care models. Understanding these segments is crucial for manufacturers and healthcare providers to tailor strategies for product development, distribution, and patient support programs.
Product Type:
Segments within product type exhibit varying development cycles, from established cytotoxic agents to rapidly evolving targeted therapies.
- Enzyme Inhibitors:These highly specific agents target particular enzymes involved in cancer cell growth and survival, offering improved efficacy and reduced side effects. Demand is concentrating in advanced oncology centers in the United States for precision medicine applications.
- Alkylating Agents:These traditional cytotoxic drugs disrupt DNA synthesis, preventing cancer cell proliferation across a broad range of malignancies. Demand remains consistent in community oncology settings for established treatment regimens.
- Antimetabolites:These compounds interfere with DNA and RNA synthesis, inhibiting cell division.
- Mitotic Inhibitors:These agents disrupt cell division by targeting microtubules.
- Hormonal Agents:These therapies modulate hormone levels or block hormone receptors, primarily used in hormone-sensitive cancers.
Alkylating Agents dominates installed base. Enzyme Inhibitors is where expansion concentrates.
Application:
The application landscape demonstrates diverse patient populations and treatment protocols, influencing therapeutic volume.
- Breast Neoplasms:This major application area drives significant demand for oral chemotherapy, often as part of long-term maintenance or adjuvant therapy. Demand is strong in specialized breast cancer clinics across Europe for sustained patient management.
- Lung Carcinoma:The high incidence of lung cancer, particularly non-small cell lung cancer, fuels demand for targeted oral therapies. Demand is growing in major cancer treatment centers in Japan for advanced disease management.
- Hematologic Malignancies:Oral agents are widely used for various blood cancers, offering convenience for chronic conditions.
- Gastrointestinal Tumors:Oral chemotherapy plays a role in treating cancers of the digestive system, including colorectal and gastric cancers.
- Gynecologic Neoplasms:This category includes ovarian, cervical, and endometrial cancers, where oral agents offer treatment flexibility.
Breast Neoplasms currently holds the largest treatment volume. Lung Carcinoma applications are gaining share at the fastest rate.
End User:
End-user channels reflect the evolving distribution and support models required for complex oral oncology medications.
- Specialty Pharmacies:These pharmacies specialize in dispensing complex, high-cost medications, providing critical patient support, adherence programs, and data reporting. Demand is concentrating in the United States due to stringent payor mandates and manufacturer requirements.
- Home Healthcare Providers:This segment involves administering oral chemotherapy in the patient's home, enhancing convenience and reducing clinic visits. Demand is accelerating among aging populations in countries like Germany, seeking less burdensome treatment regimens.
- Oncology Clinics:Traditional settings for cancer treatment, these clinics manage patient assessment and prescription of oral therapies.
- Ambulatory Surgery Centers:These facilities primarily focus on outpatient surgical procedures but may dispense some oral medications post-procedure.
- Community Health Facilities:These centers offer primary care services and may facilitate access to oral chemotherapy in underserved areas.
Specialty Pharmacies manage the majority of high-value oral chemotherapy dispensing. Home Healthcare Providers are seeing the most significant expansion in patient reach.
Delivery Mode:
Delivery modes are diversifying to enhance patient adherence and bioavailability, reflecting ongoing pharmaceutical innovation.
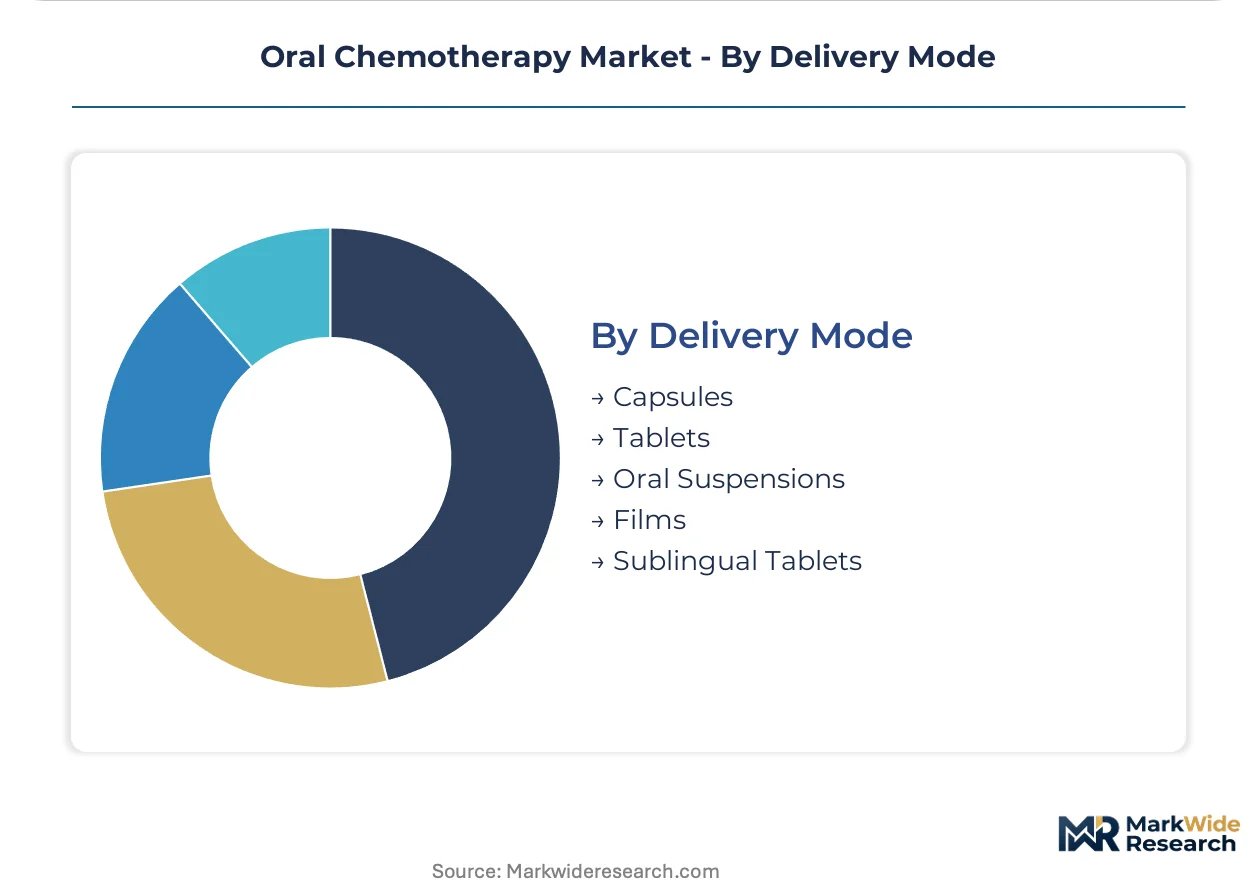
- Tablets:The most common and widely accepted delivery mode, offering ease of administration and patient familiarity. Demand remains high across all treatment settings due to established use.
- Capsules:These formulations allow for flexible dosing and often encapsulate targeted therapies, protecting sensitive compounds. Demand is strong for new drug formulations in Brazil and India.
- Oral Suspensions:Liquid formulations provide an alternative for patients with swallowing difficulties, particularly in pediatric oncology.
- Films:Thin, dissolvable films offer rapid absorption and convenience, especially for patients with nausea or dysphagia.
- Sublingual Tablets:These tablets dissolve under the tongue for direct absorption into the bloodstream, bypassing first-pass metabolism.
Tablets maintain the largest market presence. Innovation in Films and Sublingual Tablets is focused on improved patient experience and absorption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient-centric care models drive the oral chemotherapy market's regional dynamics. Demand concentrates in advanced healthcare economies with robust infrastructure and aging populations. Emerging markets also present expansion opportunities with rising healthcare spending.
United States
Demand for oral chemotherapy in the United States stems from its advanced oncology care infrastructure and the increasing adoption of patient-centric models. The US FDA mandates rigorous clinical trial data to ensure drug safety and efficacy before market approval. Major oncology centers in cities like Boston and Houston integrate precision medicine applications for complex cases.
Germany
Germany's aging population and the accelerating adoption by home healthcare providers fuel demand for oral chemotherapy. The European Medicines Agency (EMA) governs market entry and drug safety for all member states, including Germany. Pharmaceutical hubs like Frankfurt and Munich focus on developing and distributing targeted therapies.
Japan
The high incidence of lung cancer and the need for less burdensome treatment regimens for Japan's aging population drive oral chemotherapy demand. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) ensures drug safety and efficacy through strict approval processes. Major cancer treatment centers in Tokyo and Osaka lead advanced disease management.
Brazil
Rising healthcare spending and regulatory streamlining by bodies like ANVISA are creating a more favorable environment for advanced cancer therapies in Brazil. This expansion creates significant opportunities for oral chemotherapy market penetration. São Paulo and Rio de Janeiro are key centers for new drug formulations and clinical trials.
India
India's growing healthcare spending and increasing access to advanced cancer therapies are spurring demand for oral oncolytics. The Central Drugs Standard Control Organization (CDSCO) regulates drug approvals and ensures pharmaceutical quality. Major metropolitan areas like Mumbai and Bangalore are seeing increased demand for oral chemotherapy medications.
Oral Chemotherapy Market Key Industry Players
Channel-controlling players compete with product-specialist players, shaping the oral chemotherapy market. The landscape exhibits a tiered structure, from large diversified pharmaceutical conglomerates to focused biotech innovators. Strategic archetypes include companies prioritizing broad portfolio coverage, those specializing in targeted therapies, and firms emphasizing adherence programs. Companies frequently engage in strategic partnerships and extensive R&D investments to maintain relevance and expand their therapeutic reach.
Manufacturers leveraging extensive clinical trial capabilities, such as Pfizer Inc., represent a segment focused on validating efficacy for outcome-based models. Novartis AG occupies a position emphasizing targeted therapies that align with pay-for-performance contracts. Furthermore, F. Hoffmann-La Roche Ltd. exemplifies a strategy centered on a deep pipeline of personalized oncology medicines to sustain market presence and address unmet patient needs.
| Leading Market Players |
|---|
| Amgen Inc. |
| Pfizer Inc. |
| Novartis AG |
| Sanofi S.A. |
| Johnson & Johnson |
| Merck & Co. Inc. |
| F. Hoffmann-La Roche Ltd. |
| Bristol-Myers Squibb |
| AbbVie Inc. |
| Others |
Cost & Logistics Intelligence
India's and China's concentration in active pharmaceutical ingredient (API) manufacturing directly influences the cost structure for oral chemotherapy drugs, impacting margins for downstream specialty pharmacies. This upstream concentration dictates the availability and initial cost of key components for pharmaceutical companies.
Pricing Analysis
FDA and EMA certification levels create the primary spread in oral chemotherapy pricing. Value-based pricing models dominate, particularly for novel targeted therapies with robust clinical data. Price differentiation stems from proven efficacy and specialized patient adherence programs. Pricing pressure stems from high R&D investments, yet payors remain highly sensitive to demonstrated long-term patient outcomes.
Supply Chain Analysis
Extended payment terms for raw material procurement shape the financial flow within the oral chemotherapy supply chain. Supply concentration centers on India and China for active pharmaceutical ingredients (APIs), alongside advanced formulation capabilities in the United States. The supply chain relies on specialized excipients and packaging. Regulatory compliance shifts and complex cold chain logistics for specific formulations pose a structural risk. Distribution runs through a narrow network of specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oral chemotherapy market is in an early-cycle expansion phase, driven by the strong tailwind of patient-centric care models favoring convenient home administration. This shift reshapes competitive positioning, rewarding innovation in targeted therapies.
For Market Incumbents: Insulate core franchises by accelerating R&D into next-generation targeted therapies and companion diagnostics. Invest heavily in extensive clinical trial capabilities to validate efficacy for outcome-based reimbursement models, countering threats from emerging biotech innovators. Reinforce channel control through strategic partnerships with specialty pharmacies, ensuring patient adherence and data reporting. Focus on personalized oncology medicines to maintain market relevance against new entrants.
For New Entrants and Emerging Players: Pediatric and rare cancer formulations represent the most penetrable entry points for emerging players. Develop oral chemotherapy agents specifically for these unmet medical needs, leveraging orphan drug designations for expedited regulatory reviews. Integrate digital health solutions like mobile applications to monitor patient adherence and side effect management, offering a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward companies specializing in highly specific enzyme inhibitors or advanced digital health integration platforms. The market exhibits strong long-term viability, driven by sustained demand for patient-centric oral oncology solutions over the next decade. Target acquisition archetypes include agile biotechs with robust pipelines in personalized oncology. Widespread adoption of companion diagnostics in community oncology settings serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates drug approval processes and validates efficacy for new oral chemotherapy agents. |
| Regulatory Approval Pathway | Streamlines market entry for novel therapies across diverse global health agencies. |
| Licensing Agreement | Expands product portfolios and geographic reach without extensive in-house R&D. |
| Manufacturing Scale-Up | Ensures consistent supply and reduces per-unit costs for high-demand oral oncolytics. |
| Pipeline Diversification | Mitigates risks associated with single-product reliance and addresses broader oncology needs. |
Research Approach
Desk research of regulatory filings, clinical trial databases, and scientific publications preceded structured interviews with oncology key opinion leaders, pharmaceutical R&D executives, and specialty pharmacy managers. This approach combined primary insights with secondary validation from sources like FDA filings and EMA submissions. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation.
Assumptions regarding regulatory stability and sustained R&D investment were held constant across the analysis window. The analytical framework modeled growth along product type, application, end user, and delivery mode dimensions, alongside regional regulatory clusters. Compound annual growth rates (CAGRs) were derived from historical trends and projected market dynamics. Key forecast inputs included cancer incidence rates and anticipated new drug approvals.
Macroeconomic conditions sit as an overlay; deviation in global healthcare spending or regulatory policy would shift the trajectory. Forecasts reflect documented assumptions regarding clinical development and market access. Unforeseen clinical trial failures or major shifts in payor reimbursement policies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Rivaroxaban Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Global Incretin-Based Drugs Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Chronic Phase Markers Market