
 Neurodegenerative Diseases Drugs Market | 2026-2036
Neurodegenerative Diseases Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Neurodegenerative Diseases Drugs Market Intelligence
North American biologics manufacturing is restructuring its fill-finish capacity to accommodate monoclonal antibody therapies targeting amyloid and tau pathologies. Biogen leverages its established neurology infrastructure to sustain distribution networks for infused therapies. F. Hoffmann-La Roche Ltd anchors its competitive position through deep clinical trial investments across multiple indications. Novartis AG differentiates via gene therapy platforms addressing rare neurodegenerative conditions.
Neurodegenerative diseases drugs comprise small molecules, biologics, and emerging nucleic acid therapies formulated to slow or modify disease progression rather than merely managing symptoms; these agents typically require blood-brain barrier penetration strategies, subcutaneous or intravenous delivery, and cold-chain logistics to maintain molecular stability. Cholinesterase inhibitors occupy the largest revenue pool among drug classes due to entrenched prescribing habits in Alzheimer's care, while immunomodulators represent the fastest-expanding category as anti-amyloid antibodies gain regulatory traction. Oral administration routes dominate current volume, though intravenous delivery commands premium pricing and tighter prescriber control.
The FDA, EMA, and WHO each enforce distinct evidentiary standards for cognitive endpoint validation, creating fragmented market access conditions that developers must navigate simultaneously. The FDA's accelerated approval framework permits biomarker-based endpoints, whereas EMA's CHMP typically demands functional outcome confirmation before granting full authorization. Stakeholders must monitor how payer evidence requirements evolve alongside regulatory flexibility for novel surrogate markers.
Market Dynamics
The FDA's accelerated approval pathway for Alzheimer's therapies is compressing traditional clinical trial timelines, forcing developers to validate biomarker endpoints before functional outcomes mature. This regulatory flexibility is reshaping capital allocation across neurology pipelines.
Growth Catalysts
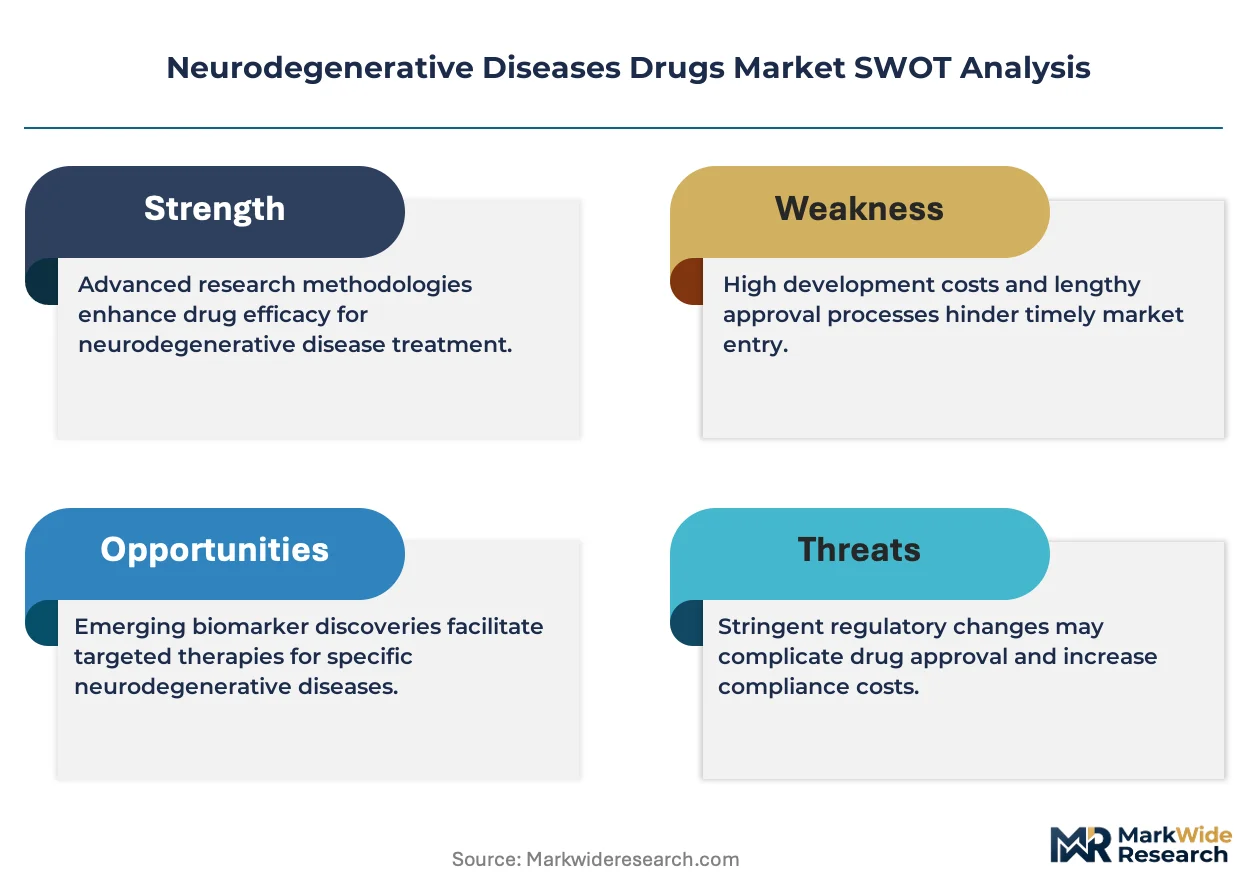
- Biomarker-Based Approvals:The FDA permits amyloid PET and CSF tau markers as surrogate endpoints, shortening Phase III duration for disease-modifying therapies.
- Medicare Reimbursement Expansion:United States coverage decisions for infused monoclonal antibodies are expanding prescriber willingness to adopt high-cost therapies in specialty clinic settings.
- Specialty Clinic Infrastructure:Neurology departments in tertiary care centers are adding infusion suites and MRI capacity to handle rising patient volumes for antibody therapies.
Market Restraints
- Cold-Chain Distribution Costs:Monoclonal antibodies require continuous 2-8°C logistics from fill-finish through patient administration, elevating per-dose supply costs.
- Blood-Brain Barrier Engineering:Lipid nanoparticle and receptor-mediated transport technologies remain technically immature for nucleic acid therapies, limiting CNS delivery efficacy.
- EMA Confirmation Requirements:The CHMP's insistence on functional cognitive endpoints delays European market entry even after FDA accelerated approval, fragmenting launch sequencing.
Strategic Opportunities
- Gene Therapy Platforms:AAV vector manufacturing scale-up for rare neurodegenerative indications offers first-mover advantages in ultra-orphan pricing environments.
- Subcutaneous Formulation Switching:Auto-injector delivery for anti-amyloid antibodies could displace infusion center dependency and expand prescriber base to community neurology.
- India's CDSCO Fast-Track:The country's orphan drug designation pathway for neurodegenerative conditions provides accelerated review timelines for imported innovator therapies.
Industry Challenges
- Biomarker Standardization Gaps:Inter-laboratory variability in amyloid PET quantification complicates patient selection and reimbursement justification across health systems.
- Infusion Center Capacity Constraints:Biweekly antibody dosing protocols strain nursing staff availability and chair time in existing neurology suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurodegenerative Diseases Drugs Market |
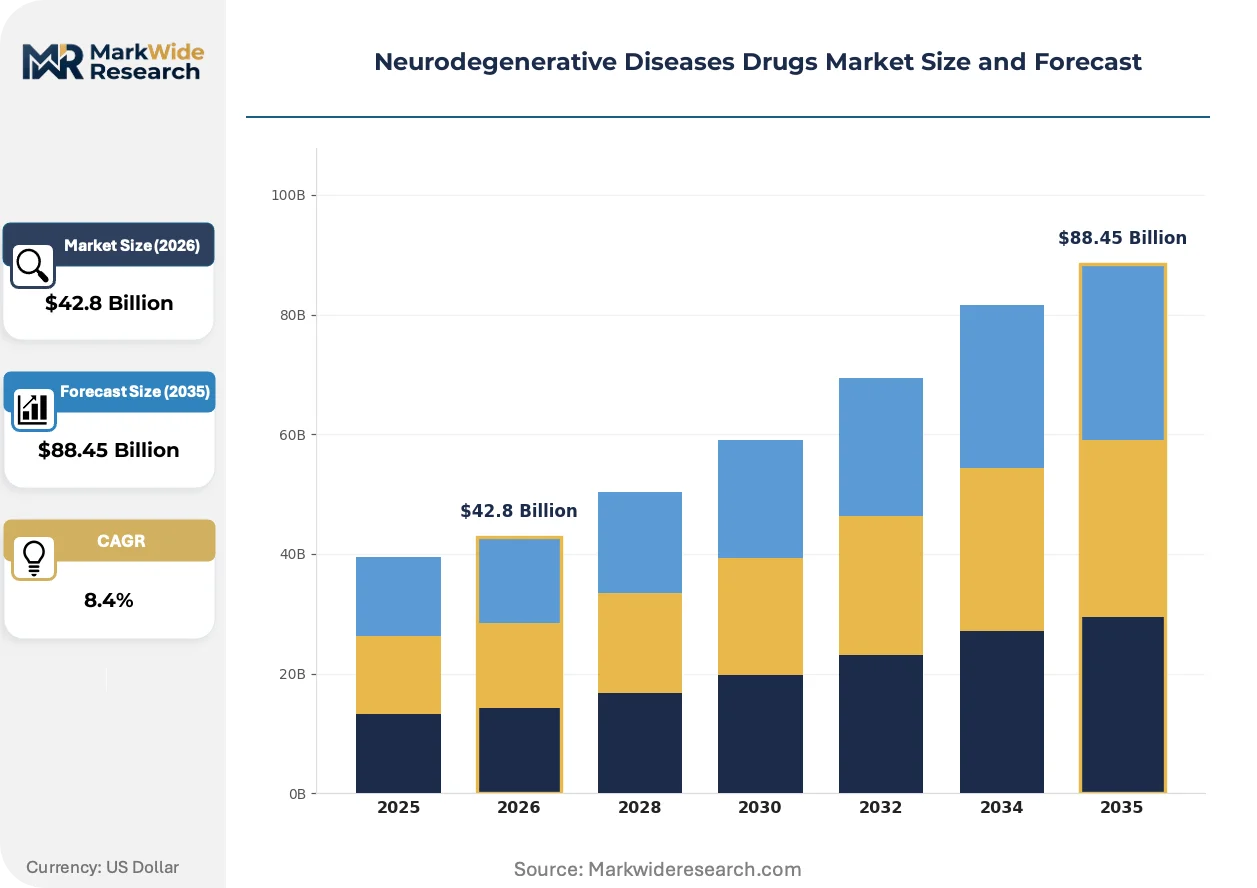
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Cholinesterase Inhibitors, NMDA Receptor Antagonists, Dopamine Agonists, Antioxidants, Immunomodulators Indication: Alzheimer's Disease, Parkinson's Disease, Huntington's Disease, Amyotrophic Lateral Sclerosis, Multiple Sclerosis Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular, Transdermal End User: Neurologists, Research Institutes, Specialty Clinics, Home Care Providers, Pharmaceutical Companies |
| Companies Covered | Biogen, F. Hoffmann-La Roche Ltd, Novartis AG, Merck & Co., Inc., Pfizer Inc., Sanofi, Teva Pharmaceutical Industries Ltd, ACADIA Pharmaceuticals Inc., H. Lundbeck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurodegenerative Diseases Drugs Market Strategic Shifts & Innovations
Neurodegenerative drug development is pivoting from symptomatic management toward pathological intervention, with manufacturing and delivery technologies racing to match mechanistic ambition.
Antisense oligonucleotides targeting SOD1 and C9orf72 in amyotrophic lateral sclerosis are absorbing intrathecal delivery infrastructure investments previously dedicated to pain management pumps. Biogen and Ionis partnerships have validated this route for CNS penetration. The modality is absorbing spinal injection training costs across specialty pharmacy networks.
Europe's MDR recertification requirements for in-vitro diagnostic companion devices are extending approval timelines for amyloid PET tracers co-developed with therapeutic candidates. Siemens Healthineers and GE Healthcare face parallel technical documentation demands. French and German notified bodies are prioritizing neurology imaging submissions given therapeutic interdependence.
United States academic medical centers are unbundling cognitive assessment services from drug acquisition, with Mayo Clinic and Cleveland Clinic establishing separate billing codes for longitudinal neuropsychological monitoring. This splits the economic unit that manufacturers previously captured through bundled pricing. The shift is most visible in Medicare Advantage contracts where risk-bearing entities seek granular outcome attribution.
Neurodegenerative Diseases Drugs Market Segmentation
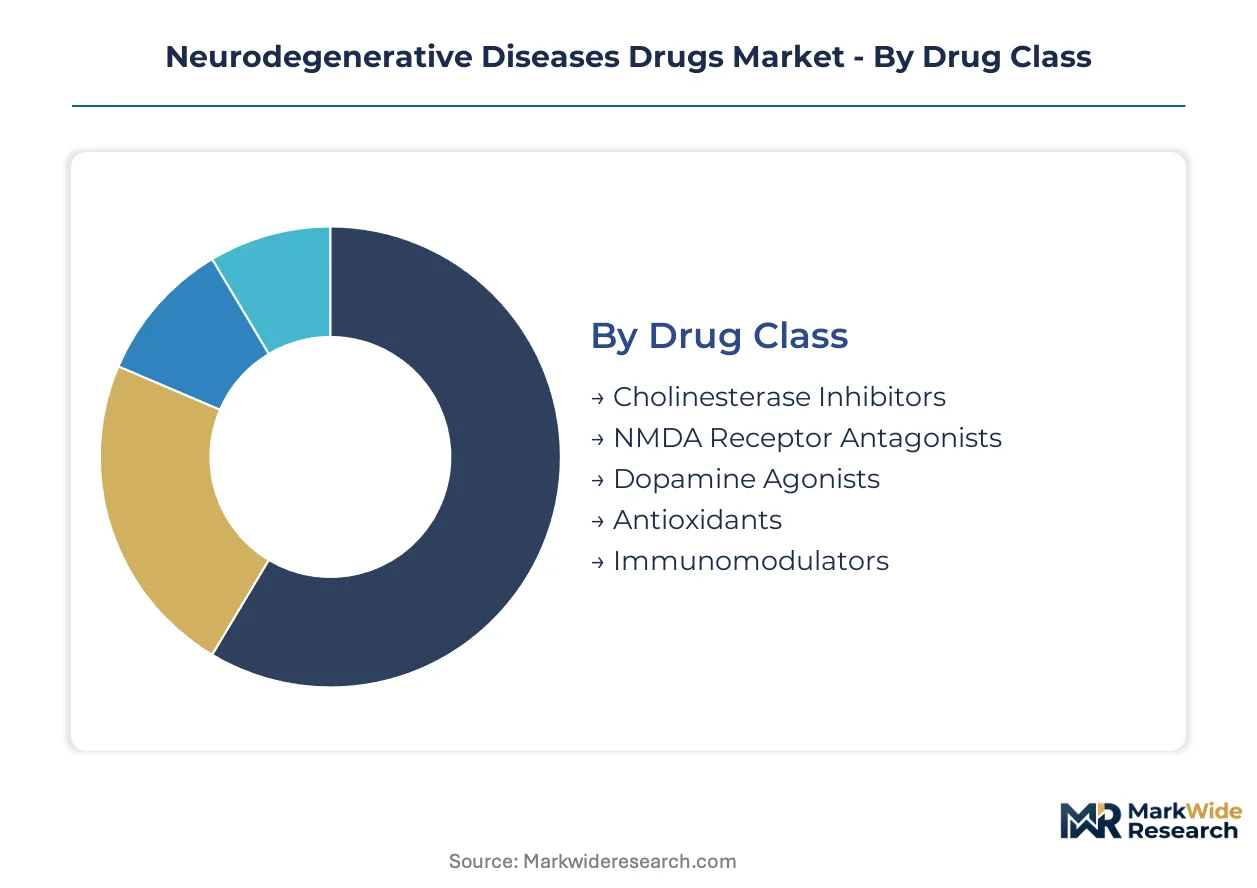
Segmentation in neurodegenerative therapeutics reveals distinct commercial ecosystems where drug class maturity, delivery complexity, and prescriber setting interlock. Each dimension carries separate reimbursement logic and supply chain requirements that shape portfolio allocation decisions.
Drug Class:
Standalone oral formulations dominate outpatient prescribing, while infused biologics require embedded infrastructure within specialty clinic networks.
- Cholinesterase Inhibitors:Small-molecule acetylcholinesterase blockers including donepezil and rivastigmine constitute the established oral standard. United States Medicare Part D formularies anchor volume in community neurology practices where pill burden drives adherence monitoring investments.
- Immunomodulators:Monoclonal antibodies targeting amyloid-beta and emerging anti-tau candidates demand cold-chain distribution and infusion suite capacity. The FDA's accelerated approval framework compresses launch timelines for developers validating biomarker endpoints.
- NMDA Receptor Antagonists:Memantine formulations for moderate-to-severe Alzheimer's provide symptomatic benefit through glutamate pathway modulation.
- Dopamine Agonists:Parkinson's disease mainstays spanning immediate-release oral and extended-release formulations.
- Antioxidants:Emerging neuroprotective candidates addressing oxidative stress mechanisms in ALS and Huntington's pipelines.
Volume placements concentrate in cholinesterase inhibitors; the faster expansion belongs to immunomodulators.
Indication:
Patient pool scale and unmet medical need intensity create divergent pricing power across neurological conditions.
- Alzheimer's Disease:The largest addressable population drives blockbuster economics for disease-modifying entrants. United States CMS coverage determinations for anti-amyloid antibodies reshape prescriber willingness to adopt high-cost therapies in memory clinic settings.
- Amyotrophic Lateral Sclerosis:Rapid disease progression and orphan designation enable premium pricing for modest clinical benefits. Intrathecal delivery infrastructure investments by Biogen and Ionis validate antisense oligonucleotide platforms.
- Parkinson's Disease:Levodopa adjunct therapies and emerging gene therapy targets occupy pipeline resources.
- Huntington's Disease:Rare hereditary indication with limited approved options and active RNA interference development.
- Multiple Sclerosis:Established immunomodulatory landscape with oral sphingosine modulators displacing earlier injectables.
Patient volumes cluster in Alzheimer's disease; ALS commands the steepest expansion trajectory for novel mechanism entrants.
Administration Route:
Delivery modality determines site-of-care economics and prescriber addressability in neurology practice.
- Oral:Immediate and extended-release tablets dominate first-line prescribing with lowest per-dose logistics burden. Community neurologists in Germany and France favor oral initiation before escalating to infused options.
- Intravenous:Monoclonal antibodies require infusion center capacity and MRI monitoring protocols. United States academic medical centers unbundle cognitive assessment services from drug acquisition, splitting previous bundled pricing units.
- Subcutaneous:Auto-injector platforms for interferon and emerging antibody candidates target community practice expansion.
- Intramuscular:Long-acting depot formulations in Parkinson's disease reduce dosing frequency.
- Transdermal:Rivastigmine patches address pill burden and caregiver administration challenges.
Dose volumes concentrate in oral administration; intravenous delivery captures premium positioning.
End User:
Prescriber setting and purchasing authority fragment demand across institutional and retail channels.
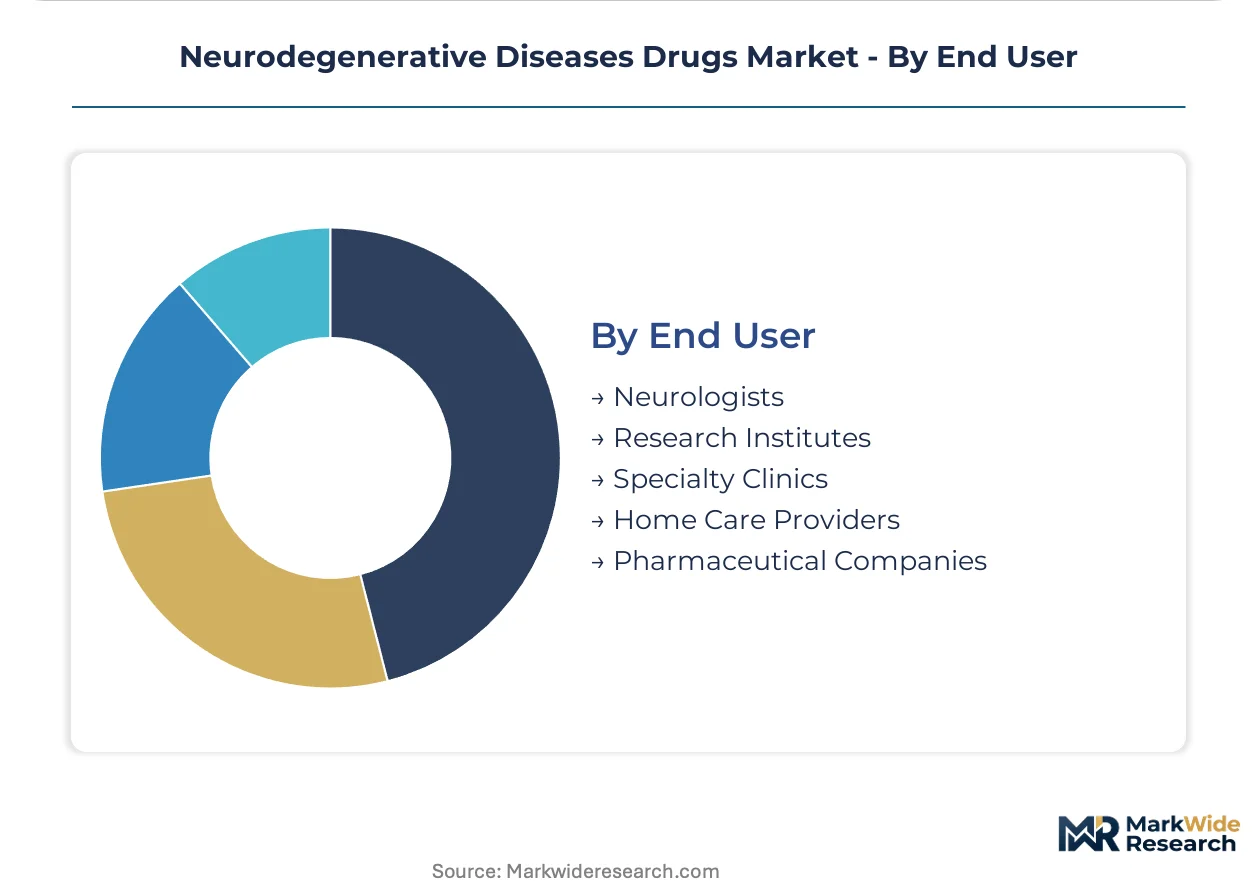
- Specialty Clinics:Tertiary care neurology departments with infusion suites and imaging capacity anchor biologic adoption. Mayo Clinic and Cleveland Clinic establish separate billing codes for longitudinal neuropsychological monitoring.
- Neurologists:Office-based practitioners drive oral therapy initiation and patient selection for escalated care.
- Research Institutes:Academic centers manage clinical trial enrollment and biomarker validation cohorts.
- Home Care Providers:Transdermal and oral administration support aging-in-place models.
- Pharmaceutical Companies:In-licensing and partnership activities concentrate pipeline assets.
Prescription volumes concentrate in specialty clinics; neurologist offices provide the broadest prescriber reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in Switzerland and Massachusetts anchor neurodegenerative drug development, with monoclonal antibody fill-finish capacity expanding near patient populations in Germany and Japan.
United States
Medicare reimbursement determinations for anti-amyloid antibodies drive prescribing patterns in memory clinics across the Midwest and Southeast. The FDA's accelerated approval pathway permits biomarker-based endpoints, compressing Phase III timelines for disease-modifying entrants. Mayo Clinic and Cleveland Clinic anchor demand in tertiary neurology centers with dedicated infusion suites.
Germany
EMA confirmation requirements for functional cognitive endpoints delay market entry even after FDA approval, fragmenting launch sequencing. The country's statutory health insurance funds negotiate reference pricing for cholinesterase inhibitors. Bavaria's Munich cluster concentrates biologics manufacturing investments from Roche and Novartis.
Japan
PMDA reviews prioritize amyloid PET tracer validation for patient selection in academic medical centers. The aging population density in Kanto and Kansai regions sustains demand for Parkinson's disease dopamine agonists. Tokyo's neurology departments absorb intrathecal delivery training costs for antisense oligonucleotide platforms.
Switzerland
Roche's Basel headquarters anchors monoclonal antibody development for tau and amyloid pathologies. Swissmedic maintains alignment with EMA standards while offering rapid scientific advice for orphan neurodegenerative indications. The country's biologics fill-finish infrastructure exports to EU and US markets.
India
CDSCO's orphan drug designation pathway provides accelerated review timelines for imported innovator therapies in neurodegenerative conditions. Maharashtra's Mumbai-Pune corridor attracts contract manufacturing for oral generic formulations. Domestic demand concentrates in government hospital neurology departments for affordable cholinesterase inhibitors.
Neurodegenerative Diseases Drugs Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue gene therapy and antisense platforms in rare neurodegenerative indications. The market structure concentrates around large-cap biopharmaceuticals with neurology infrastructure, mid-cap specialists in intrathecal delivery, and gene therapy pure-plays. Three archetypes dominate: integrated biologics manufacturers with cold-chain distribution, CNS-focused developers with blood-brain barrier engineering capabilities, and rare disease specialists with ultra-orphan pricing power. Competitive moves center on subcutaneous formulation switching to displace infusion dependency, and AAV manufacturing scale-up for first-mover gene therapy positioning.
Within the integrated biologics tier, Biogen and F. Hoffmann-La Roche Ltd exemplify infrastructure-heavy positioning with established neurology distribution networks and fill-finish capacity. Novartis AG occupies the gene therapy specialist archetype, leveraging AAV platform investments for rare neurodegenerative conditions. These three entities represent divergent strategic vectors: antibody infusion maintenance, subcutaneous transition, and nucleic acid modality expansion.
| Leading Market Players |
|---|
| Biogen |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Sanofi |
| Teva Pharmaceutical Industries Ltd |
| ACADIA Pharmaceuticals Inc. |
| H. Lundbeck A/S |
| Others |
Cost & Logistics Intelligence
Biologics manufacturing specialists concentrated in Basel and Boston command wage premiums that widen spreads between infused antibody therapies and oral generic alternatives. Labor-cost differentials between Swiss fill-finish facilities and Indian API operations sustain three-tier pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Warranty and service-bundling unbundling reshapes neurology drug economics as Mayo Clinic and Cleveland Clinic separate longitudinal neuropsychological monitoring from drug acquisition. The dominant structure runs through value-based contracting tied to cognitive endpoint achievement, with price differentiation resting on biomarker validation status and infusion-suite service inclusion. Pricing pressure stems from Medicare Advantage risk-bearing entities demanding granular outcome attribution. Community neurologists exhibit highest price sensitivity; academic medical centers with dedicated memory clinics demonstrate lowest sensitivity due to separate billing code capture.
Supply Chain Analysis
EMA MDR recertification requirements for companion diagnostic devices gate European market entry for amyloid PET tracer co-developments. Manufacturing concentrates in Switzerland, Massachusetts, and Bavaria for monoclonal antibody fill-finish, with cold-chain logistics drawing from specialized 2-8°C distribution networks anchored in Germany and Japan. Single-source vulnerability pervades AAV vector manufacturing for gene therapy platforms. Distribution runs through specialty pharmacy networks with intrathecal delivery training infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with captive fill-finish capacity as EMA confirmation requirements and biomarker standardization gaps force asset-light developers toward partnership or exit.
For Market Incumbents: Lock in infusion center capacity through exclusive neurology suite partnerships before subcutaneous formulation switching displaces site-of-care dependency. Secure backward integration into AAV vector manufacturing to capture first-mover positioning in ultra-orphan gene therapy pricing environments. Biogen's established distribution infrastructure exemplifies the defensive moat that cold-chain logistics and prescriber relationships create against emerging antisense platform entrants. For New Entrants and Emerging Players: Subcutaneous auto-injector platforms for anti-amyloid antibodies offer the most penetrable wedge into community neurology practices currently excluded from infusion economics. India's CDSCO orphan drug fast-track provides accelerated review timelines for imported innovator therapies with limited domestic competition. Target prescriber education investments toward office-based neurologists in Germany and France who favor oral initiation protocols before escalating to infused options. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap CNS-focused developers possessing blood-brain barrier engineering capabilities given FDA accelerated approval pathway expansion. Long-term viability centers on 5-10 year windows for nucleic acid modality validation through intrathecal delivery infrastructure. Acquisition target archetypes include antisense oligonucleotide platforms with validated spinal injection training networks. Watch for biomarker standardization consensus across amyloid PET quantification methodologies as inflection indicator for reimbursement stability.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Auto-injector platforms displace infusion center dependency and expand prescriber addressability to community neurology. |
| AAV Manufacturing Scale-Up | First-mover gene therapy positioning in ultra-orphan pricing environments requires captive viral vector production. |
| Biomarker Companion Diagnostic Co-Development | FDA accelerated approval pathway demands validated amyloid PET and CSF tau markers for surrogate endpoints. |
| Specialty Clinic Infusion Suite Partnerships | Exclusive capacity agreements with Mayo Clinic and Cleveland Clinic secure prescriber control for antibody therapies. |
| EMA Functional Endpoint Confirmation Strategy | Parallel European trial designs address CHMP cognitive outcome requirements that delay market entry post-FDA approval. |
Research Approach
Multi-period observation of FDA accelerated approval decisions, EMA CHMP outcome requirements, and Medicare coverage determinations anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors at United States payers, and hospital procurement managers. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov enrollment data, and CMS Medicare Part D formulary databases. Bottom-up patient-flow modeling and top-down therapeutic class revenue triangulation cross-checked volume and value estimates.
Segment-weighting across drug class, indication, administration route, and end-user setting shaped the analytical framework throughout the projection horizon. CAGRs were derived from fitted growth curves applied to biomarker-validated therapy adoption trajectories and oral generic erosion patterns. Modeled inputs included Medicare reimbursement policy evolution, specialty clinic infusion capacity expansion, and EMA MDR recertification timelines for companion diagnostics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated FDA biomarker flexibility or EMA functional endpoint delays. Forecasts reflect assumptions regarding payer evidence requirements and regulatory alignment for novel surrogate markers. A model refresh is warranted upon material change in Medicare Advantage risk-bearing entity contracting practices or biomarker standardization consensus across inter-laboratory quantification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Combination Antibody Therapy Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Purified Protein Derivative Market