
 Ovarian Cancer Drugs Market | 2026-2036
Ovarian Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Ovarian Cancer Drugs Market Intelligence
The direct-to-specialty-clinic distribution channel is narrowing as large hospital networks and integrated delivery systems consolidate purchasing power. This shift favors manufacturers with extensive supply chain capabilities and established payer relationships. AstraZeneca leverages its leadership in PARP inhibitors to secure formulary placement. F. Hoffmann-La Roche sustains its market presence through a strong portfolio of anti-angiogenic agents and biologics.
Ovarian cancer drugs are pharmacological agents that target malignant cell proliferation in ovarian tissues through specific biological mechanisms. These include DNA repair pathway inhibition, characteristic of PARP inhibitors, and the blockade of tumor blood vessel formation. PARP inhibitors represent the fastest-growing drug class, especially for maintenance therapy following initial chemotherapy. In contrast, platinum-based agents remain a cornerstone of first-line treatment, often used in combination therapy regimens.
Market access is governed by stringent regulatory reviews from agencies like the United States FDA and the European Medicines Agency (EMA). These bodies mandate rigorous clinical trials to prove efficacy and safety, increasingly requiring companion diagnostics. Stakeholders must now focus on demonstrating superior long-term survival outcomes and cost-effectiveness to navigate complex reimbursement landscapes.
Market Dynamics
The central dynamic in the ovarian cancer drugs market is the tension between the development of highly specific, biomarker-driven therapies and the consolidating purchasing power of large hospital networks, which prioritizes cost-effectiveness and broad formulary contracts over niche treatments.
Growth Catalysts
- Companion Diagnostics:The mandatory use of companion diagnostic tests to identify patients with specific genetic mutations, such as BRCA, for PARP inhibitor eligibility is expanding the addressable market for targeted therapies.
- Regulatory Incentives:Accelerated approval pathways offered by regulators like the United States FDA and the EMA for drugs addressing high unmet medical needs are shortening development timelines for novel treatments.
- Demographic Shifts:An aging population in developed nations, particularly in Japan and Germany, is increasing the overall incidence of ovarian cancer, thereby expanding the base patient population requiring treatment.
Market Restraints
- High Drug Development Costs:The substantial financial investment required for research, development, and multi-phase clinical trials for novel biologics and targeted agents acts as a significant barrier for new market entrants.
- Stringent Efficacy Hurdles:Payers and health technology assessment bodies increasingly demand evidence of superior long-term overall survival, not just progression-free survival, creating high evidence-generation burdens for manufacturers.
- Patent Expirations:The looming patent cliffs for established first-line chemotherapy agents and some older targeted drugs expose the market to competition from lower-cost generics and biosimilars.
Strategic Opportunities
- Platinum-Resistant Ovarian Cancer (PROC):A significant unmet need exists for effective therapies in the PROC setting, creating a substantial opportunity for drugs that can demonstrate efficacy after primary treatments have failed.
- Combination Therapy Regimens:Exploring the synergistic effects of combining PARP inhibitors with other drug classes, such as anti-angiogenic agents or immunotherapies, opens new avenues for improved treatment outcomes and market expansion.
- Emerging Market Infrastructure:As oncology care infrastructure improves in countries like Brazil and South Korea, there is a clear opportunity to introduce advanced targeted therapies to previously underserved patient populations.
Industry Challenges
- Complex Treatment Logistics:Administering biomarker-guided therapies requires sophisticated diagnostic infrastructure and specialized expertise in genomic pathology, creating an operational challenge for healthcare providers outside of major academic centers.
- Payer Resistance to High Costs:The premium pricing of novel targeted therapies faces significant pushback from reimbursement authorities, necessitating complex negotiations and the development of robust pharmacoeconomic data.
- Managing Acquired Resistance:A key clinical challenge is the development of acquired resistance to PARP inhibitors and other targeted agents, which limits their long-term effectiveness and drives research into next-generation therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ovarian Cancer Drugs Market |
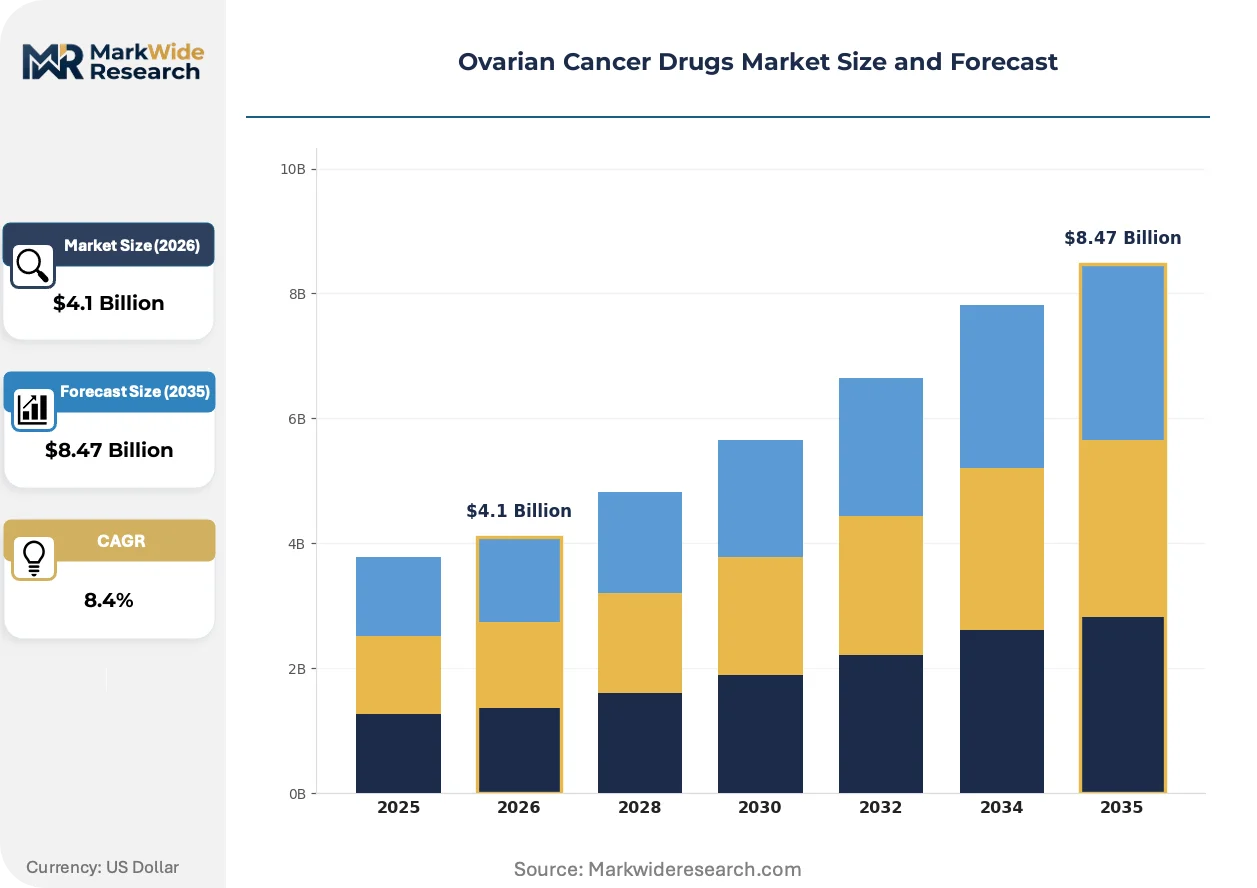
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.47 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Platinum-Based, PARP Inhibitors, Anti-Angiogenic Agents, Hormonal Therapies, Immunotherapy Therapy Stage: First-Line Treatment, Maintenance Therapy, Recurrent Disease Management, Neoadjuvant Therapy Regimen Type: Monotherapy, Combination Therapy, Targeted Therapy, Chemotherapy, Biologic Agents End User: Oncology Centers, Research Institutions, Specialty Clinics, Pharmaceutical Companies |
| Companies Covered | AstraZeneca, F. Hoffmann-La Roche, GlaxoSmithKline, Merck & Co., Pfizer, AbbVie, Bristol Myers Squibb, Clovis Oncology, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ovarian Cancer Drugs Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive pivot towards personalized medicine. This shift is driven by advancements in genomic sequencing and a deeper biological understanding of tumor heterogeneity, moving treatment paradigms away from one-size-fits-all approaches.
Companion diagnostics, which analyze a patient's genetic profile for specific biomarkers like BRCA mutations, are a critical enabling technology. Oncology centers and specialty clinics are rapidly incorporating these tests into standard diagnostic workflows for newly diagnosed patients. This technology is digitizing patient stratification, moving treatment decisions from broad protocols to individualized, data-driven prescriptions based on molecular tumor characteristics.
Regulatory frameworks are adapting to the pace of innovation, with programs like the EMA's PRIME (PRIority MEdicines) scheme gaining prominence. This initiative provides enhanced support for medicines that target an unmet medical need, accelerating the scientific assessment process. This shift most affects developers of novel biologics for rare ovarian cancer subtypes, encouraging earlier and more frequent interaction with regulatory bodies to align clinical trial designs with approval requirements.
A fundamental change in treatment philosophy is occurring, emphasizing long-term maintenance therapy following initial chemotherapy. This disrupts the previous model focused solely on acute, cyclical treatment, creating a new, extended phase of care where drugs like PARP inhibitors are used for disease management. The trend is most advanced in healthcare systems within the United States and parts of the European Union, where reimbursement policies and clinical guidelines support this proactive approach.
Ovarian Cancer Drugs Market Segmentation
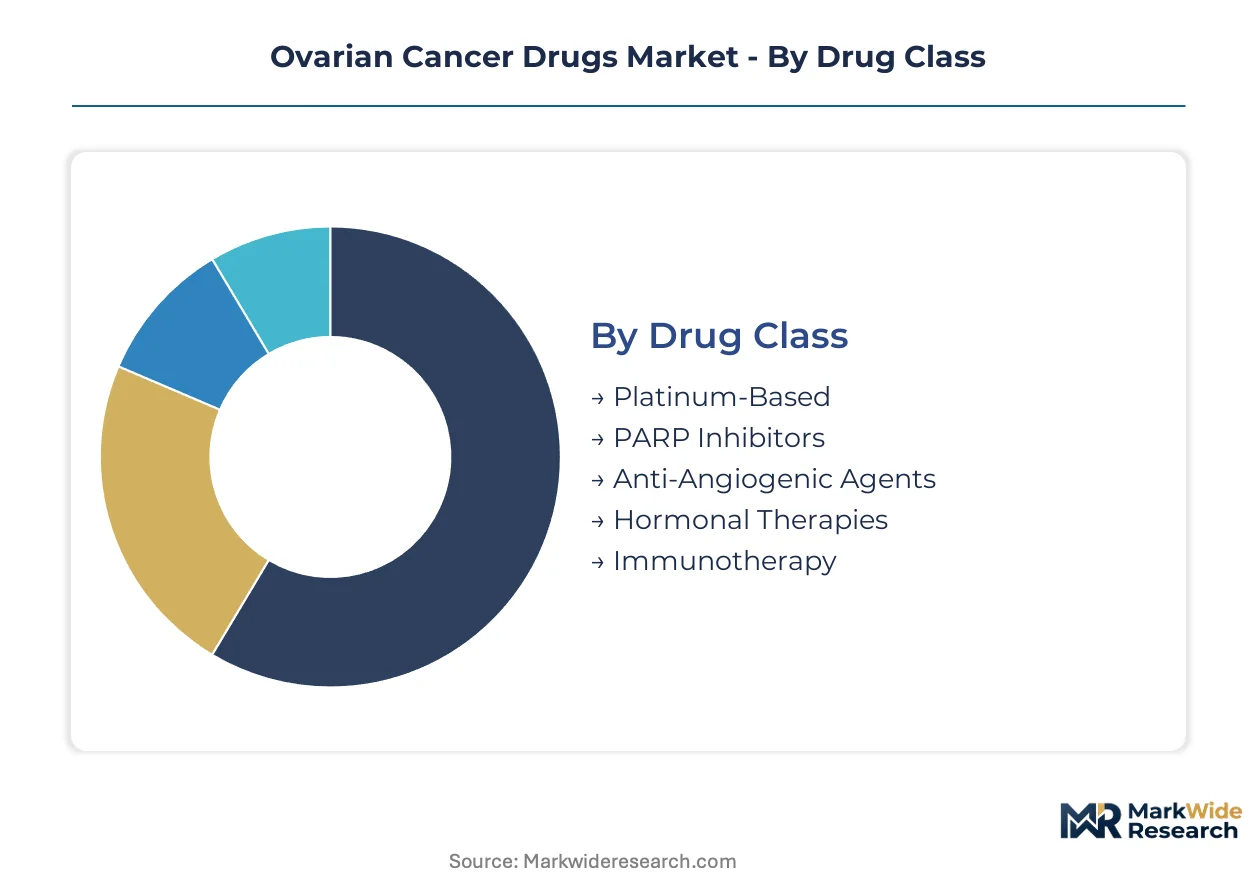
The ovarian cancer drugs market segmentation provides a granular view of therapeutic approaches, drug classes, and treatment settings. Understanding these distinct segments helps manufacturers align product development with clinical needs and market demand.
Drug Class:
The drug class segmentation highlights a spectrum from established, mature treatments to rapidly emerging, targeted therapies.
- PARP Inhibitors:These agents block DNA repair pathways in cancer cells, specifically targeting BRCA-mutated tumors. Demand for PARP inhibitors concentrates in countries with advanced genomic testing infrastructure, such as the United States and Germany, driven by their efficacy in maintenance therapy.
- Platinum-Based:Platinum-based agents, including carboplatin and cisplatin, induce DNA damage in cancer cells, forming the backbone of initial chemotherapy regimens. These agents see widespread use globally due to their established efficacy and position as a first-line treatment standard.
- Anti-Angiogenic Agents:These drugs inhibit the formation of new blood vessels that tumors need to grow, thereby starving the cancer. F. Hoffmann-La Roche sustains its market presence with a strong portfolio of these biologics.
- Hormonal Therapies:These agents modulate hormone levels or block hormone receptors to inhibit cancer cell growth, primarily used in specific ovarian cancer subtypes. Hormonal therapies offer an alternative for patients with hormone-sensitive disease.
- Immunotherapy:This class of drugs harnesses the body's immune system to identify and destroy cancer cells. Immunotherapy represents a newer treatment modality with ongoing research into its efficacy for ovarian cancer.
Platinum-Based agents retain volume leadership; PARP Inhibitors hold the steepest expansion curve.
Therapy Stage:
Segmentation by therapy stage delineates treatment applications based on disease progression and clinical objectives.
- First-Line Treatment:This initial therapy, administered after diagnosis, typically involves surgery and chemotherapy, aiming for maximal tumor reduction. This stage represents a significant volume segment, especially in healthcare systems with well-defined treatment protocols like those in Japan.
- Maintenance Therapy:This long-term treatment follows an initial response to prevent disease recurrence, primarily utilizing targeted agents like PARP inhibitors. This stage is expanding significantly due to improved long-term survival outcomes and evolving clinical guidelines.
- Recurrent Disease Management:These treatments address cancer that has returned after initial therapy, often involving different drug regimens. Effective management of recurrent disease remains a significant unmet medical need.
- Neoadjuvant Therapy:This treatment is given before the main treatment, such as surgery, to shrink the tumor. Neoadjuvant approaches are employed to improve surgical outcomes for patients with advanced disease.
First-Line Treatment remains the foundational stage; Maintenance Therapy is gaining share rapidly.
Regimen Type:
Regimen type segmentation categorizes therapeutic approaches by their complexity and mechanism of action.
- Combination Therapy:This approach integrates multiple agents, often chemotherapy with targeted drugs, to enhance efficacy and overcome resistance mechanisms. Combination regimens are widely adopted in advanced disease settings across major oncology markets.
- Targeted Therapy:Agents designed to interfere with specific molecular pathways involved in cancer growth and progression, often requiring companion diagnostics. Demand for targeted therapies is robust in developed markets with strong research and development investments.
- Chemotherapy:Traditional cytotoxic drugs that kill rapidly dividing cells, including cancer cells, often associated with systemic side effects. Chemotherapy agents remain a cornerstone, particularly in initial treatment regimens.
- Monotherapy:Treatment using a single drug, often for patients who cannot tolerate combination regimens or for specific targeted indications. Monotherapy provides a simpler treatment option in certain clinical scenarios.
- Biologic Agents:Drugs derived from living organisms that target specific biological processes in cancer, including anti-angiogenic agents and immunotherapies. Biologic agents offer advanced treatment options with novel mechanisms.
Combination Therapy is currently the most prevalent approach; Targeted Therapy shows strong growth potential.
End User:
End user segmentation identifies the primary healthcare settings and organizations responsible for drug administration and research.
- Oncology Centers:Specialized medical facilities providing comprehensive cancer care, including diagnosis, treatment, and follow-up. These centers represent the largest volume segment for ovarian cancer drug administration due to their infrastructure and patient flow.
- Specialty Clinics:Outpatient facilities focusing on specific medical conditions, increasingly administering advanced targeted therapies. These clinics are expanding their role, particularly in regions like the United States, by offering personalized treatment options.
- Research Institutions:Academic and private organizations dedicated to discovering new therapies and understanding disease mechanisms. Research institutions are critical for advancing the pipeline of novel ovarian cancer drugs.
- Pharmaceutical Companies:These entities develop, manufacture, and market ovarian cancer drugs, often conducting clinical trials. Pharmaceutical companies are key players in drug innovation and market supply.
Oncology Centers process the largest patient volumes; Specialty Clinics are expanding their therapeutic scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pricing power for advanced ovarian cancer drugs exhibits regional asymmetry, with the United States supporting premium valuations for novel therapies. In contrast, European markets, including Germany, frequently exert greater pressure on drug manufacturers for cost-effectiveness. This difference influences market access strategies and product launch sequencing across global geographies.
United States
High incidence of ovarian cancer and rapid adoption of PARP inhibitors drive significant demand in the United States. The FDA's accelerated approval pathways shorten development timelines for novel treatments. Major oncology centers in Boston and Houston drive clinical research and early adoption of targeted therapies.
Germany
An aging population and strong healthcare infrastructure support demand for advanced oncology treatments in Germany. The EMA's stringent regulatory reviews influence market entry and reimbursement decisions. Pharmaceutical hubs in Bavaria, particularly around Munich, focus on biomarker-driven therapy development and patient stratification.
Japan
Increasing overall incidence of ovarian cancer due to demographic shifts creates sustained demand in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) mandates rigorous clinical trials for new drug approvals. Tokyo's leading academic medical centers are central to implementing advanced chemotherapy and maintenance therapy guidelines.
South Korea
Improving oncology care infrastructure and rising patient awareness of targeted therapies contribute to market expansion in South Korea. The Ministry of Food and Drug Safety (MFDS) oversees drug efficacy and safety evaluations. Seoul's major university hospitals are actively integrating companion diagnostics for personalized ovarian cancer treatment.
Brazil
Expanding access to advanced healthcare and significant unmet medical needs in oncology present opportunities in Brazil. ANVISA, the national health surveillance agency, regulates drug approvals and market entry. São Paulo's private hospital networks are increasingly adopting targeted therapies and combination regimens for ovarian cancer patients.
Ovarian Cancer Drugs Market Key Industry Players
Large pharmaceutical conglomerates and specialized biotech innovators split the ovarian cancer drugs market, reflecting a tiered competitive structure. Established global players dominate through broad portfolios and extensive market access networks. Smaller, research-intensive firms focus on niche targeted therapies and novel mechanisms of action. Dominant competitive moves include strategic partnerships for pipeline development and portfolio diversification to address various treatment stages.
Within the established pharmaceutical archetype, AstraZeneca, a UK-based public limited company, represents leadership in the PARP inhibitor segment. F. Hoffmann-La Roche, a Swiss multinational healthcare company, exemplifies sustained market presence through its strong portfolio of anti-angiogenic agents and biologics. Merck & Co., Inc., a US-based pharmaceutical company, occupies a position focused on expanding its oncology footprint, including through immunotherapy research. These entities leverage their R&D capabilities and global distribution channels to maintain competitive advantages.
| Leading Market Players |
|---|
| AstraZeneca |
| F. Hoffmann-La Roche |
| GlaxoSmithKline |
| Merck & Co. |
| Pfizer |
| AbbVie |
| Bristol Myers Squibb |
| Clovis Oncology |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
The trans-Atlantic pharmaceutical shipping lanes, crucial for advanced biologics, directly influence cost dynamics, which in turn affect supply concentration and price differentiation for ovarian cancer drugs. This global network determines market access and final drug pricing.
Pricing Analysis
Value-based pricing, reflecting clinical outcomes and patient benefit, dominates the ovarian cancer drugs market for novel therapies. Price differentiation stems from drug efficacy, regulatory approvals from agencies like the United States FDA and the European Medicines Agency (EMA), and the level of companion diagnostic integration. Pricing softness affects older, off-patent chemotherapy agents due to generic competition. Oncology centers and large hospital networks are highly price-sensitive, while individual patients often prioritize efficacy.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly critical for managing pharmaceutical inventory across diverse geographies. Geographic supply concentration for active pharmaceutical ingredients (APIs) primarily resides in India and China, with specialized biologics often sourced from the United States. Raw material dependencies include complex chemical precursors and cell culture media. Single-source vulnerability for novel biologics poses a significant supply chain risk. Distribution runs through specialized pharmaceutical wholesalers and direct-to-hospital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ovarian cancer drugs market represents a high-growth disruption driven by the rapid evolution of personalized medicine. Companion diagnostics and targeted therapies are fundamentally reshaping treatment paradigms, creating new opportunities and challenges.
For Market Incumbents: Insulate core market share by continuously investing in next-generation PARP inhibitors and combination therapies, particularly for maintenance settings. Diversify portfolios to address platinum-resistant ovarian cancer, a significant unmet medical need. Control of specialized distribution channels and established payer relationships acts as a critical lever against emerging biotech entrants. Regulatory shifts favoring superior long-term survival outcomes threaten older drug classes and require proactive clinical development.
For New Entrants and Emerging Players: Build out niche expertise in novel mechanisms targeting rare ovarian cancer subtypes, leveraging accelerated approval pathways. The underpenetrated platinum-resistant ovarian cancer segment offers a compelling white-space opportunity for therapies demonstrating durable responses. Focus on developing treatments with superior long-term survival data to gain market access and payer acceptance. A direct-to-specialty-clinic go-to-market angle allows for focused outreach.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotech innovators with advanced clinical pipelines in targeted therapies, especially those addressing acquired resistance. Long-term viability in this market depends on demonstrating superior efficacy in maintenance settings and navigating complex reimbursement landscapes. Acquisition targets should include firms with promising assets that offer novel mechanisms of action. The signal to watch is the accelerated approval of novel immunotherapies for ovarian cancer.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification | Pharmaceutical companies expand their therapeutic offerings to address multiple ovarian cancer subtypes. |
| Clinical Trial Advancement | New drug candidates progress through rigorous trials, demonstrating efficacy for regulatory approval. |
| Licensing Agreement | Biotech firms partner with larger entities to accelerate development and market access for novel agents. |
| Manufacturing Scale-Up | Production capabilities expand to meet the growing demand for advanced targeted therapies. |
| Regulatory Approval Pathway | Developers navigate FDA and EMA processes to secure market authorization for innovative treatments. |
Research Approach
A standing panel of drug development executives, regulatory affairs leads, and hospital procurement managers provided ongoing calibration and validation of market dynamics. This study combined extensive primary interviews with rigorous secondary validation, drawing insights from FDA filings, EMA submissions, and ClinicalTrials.gov data. Bottom-up market sizing was triangulated with top-down industry reports to ensure data accuracy.
Scenario-bracketing provided a robust framework for projecting future market trajectories, accounting for varying adoption rates and regulatory changes. The analytical framework modeled market evolution across the analysis window, segmenting by drug class, therapy stage, and end-user. Compound annual growth rates were derived from historical trends and anticipated pipeline advancements. Key forecast inputs included patient incidence rates and companion diagnostic uptake.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large pharmaceutical companies or novel biotech firms would shift outcomes. Forecasts reflect assumptions regarding clinical trial success rates and reimbursement policy stability. Unforeseen breakthroughs in immunotherapy or significant changes in regulatory approval timelines represent risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Prokaryotic Recombinant Protein Market
Biopharmaceuticals
North America Vaccines Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Levofloxacin Cyclized Ester Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Oligonucleotide API Market