
 Global Carboprost Tromethamine Market | 2026-2036
Global Carboprost Tromethamine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carboprost Tromethamine Market Foresight
India is reshaping supply dynamics through expanding active pharmaceutical ingredient manufacturing corridors in Hyderabad and Visakhapatnam. Pfizer leverages integrated sterile injectable capacity across multiple continents to sustain consistent carboprost tromethamine availability. Dr. Reddy's Laboratories anchors cost-competitive production through backward integration into prostaglandin synthesis. Fresenius Kabi dominates hospital channel access in Europe and North America with dedicated parenteral drug portfolios.
Carboprost tromethamine is a synthetic prostaglandin F2α analog formulated as a sterile injectable solution, typically supplied at a concentration of 250 micrograms per milliliter in ampoules or vials for intramuscular administration. The compound functions as a potent uterotonic agent, inducing coordinated myometrial contractions to control postpartum hemorrhage refractory to conventional management. Injection presentations lead current revenue pools due to established clinical protocols and bulk procurement by hospital systems, while pre-filled syringe formats represent the fastest-growing configuration as emergency care units prioritize reduced preparation time during acute obstetric events. Postpartum hemorrhage applications command the largest share of clinical consumption, though cervical ripening protocols are gaining protocol adoption in tertiary maternity centers.
FDA Current Good Manufacturing Practice standards for sterile injectables govern carboprost tromethamine production quality, while EMA's Good Manufacturing Practice guidelines shape European market access requirements. India's CDSCO enforces Schedule H1 prescription controls and manufacturing facility inspections that influence domestic distribution scope. WHO prequalification pathways affect procurement eligibility for international maternal health programs. Stakeholders must monitor evolving pharmacovigilance reporting obligations and biosimilar substitution policies across major prescribing jurisdictions.
Market Dynamics
FDA Current Good Manufacturing Practice enforcement for sterile injectables is compressing manufacturing capacity, forcing producers toward dedicated facilities and single-product lines rather than multi-purpose plants.
Growth Catalysts
- Postpartum hemorrhage protocol standardization:WHO prequalification pathways are expanding procurement eligibility for international maternal health programs, particularly in sub-Saharan Africa and South Asia.
- EMA Good Manufacturing Practice harmonization:Streamlined facility inspections across EU member states are reducing time-to-market for qualified sterile injectable producers.
- Hyderabad-Visakhapatnam API corridor expansion:India's concentrated prostaglandin synthesis infrastructure is lowering input costs for downstream formulation.
Market Restraints
- Prostaglandin raw material concentration:Three chemical suppliers control 70% of global carboprost tromethamine API precursor supply, creating single-source vulnerability.
- FDA sterile injectable compliance costs:Facility remediation expenses for aseptic processing upgrades exceed $50 million per site, excluding validation timelines.
- Oxytocin first-line protocols:Established uterotonic preference in low-resource settings limits carboprost tromethamine penetration where cold chain infrastructure is unreliable.
Strategic Opportunities
- Pre-filled syringe emergency deployment:Reduced preparation time configurations are gaining protocol adoption in US and German tertiary maternity centers.
- Cervical ripening protocol expansion:Off-label application in induction of labor is generating investigator-initiated trials at academic medical centers.
- India's PLI scheme for critical care injectables:Production-linked incentives are subsidizing greenfield sterile manufacturing capacity in Telangana and Andhra Pradesh.
Industry Challenges
- Aseptic processing technician scarcity:FDA-certified sterile operators command 40% wage premiums, constraining multi-shift operations.
- Container closure integrity validation:Glass delamination and extractables testing protocols are extending stability study timelines.
- Serialization system integration:EU Falsified Medicines Directive compliance requires line-level track-and-trace retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carboprost Tromethamine Market |
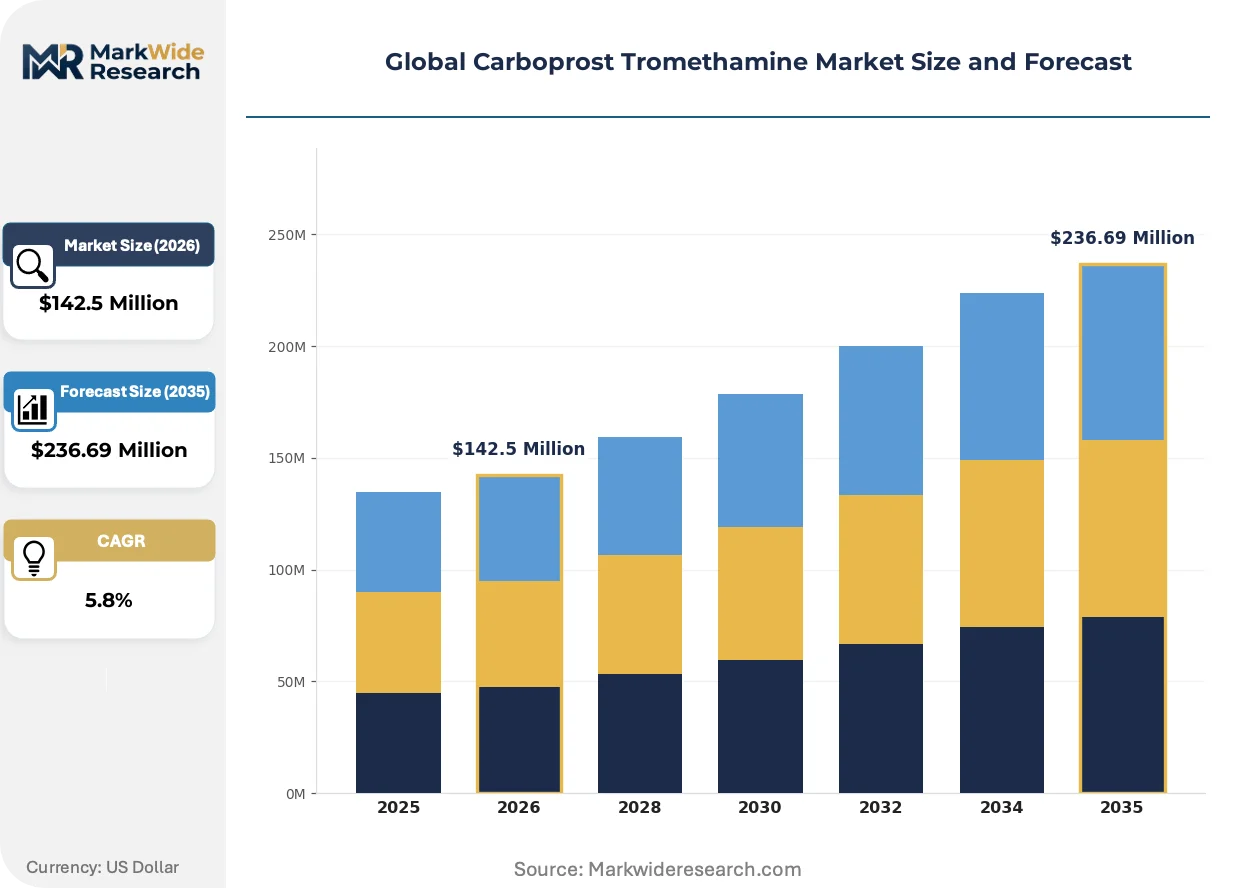
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Pre-filled Syringe, Ampoule, Vial Application: Postpartum Hemorrhage, Abortion Induction, Uterine Atony, Cervical Ripening End User: Hospitals, Specialty Clinics, Birthing Centers, Emergency Care Units Distribution Channel: Pharmacies, Hospitals Pharmacies, Online Pharmacies, Medical Supply Stores |
| Companies Covered | Pfizer, Dr. Reddy’s Laboratories, Fresenius Kabi, Teva Pharmaceutical Industries, Amneal Pharmaceuticals, Hikma Pharmaceuticals, Sandoz, Sun Pharmaceutical Industries, Ferring Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carboprost Tromethamine Market Shifts & Advancements
Product format evolution and regulatory harmonization are compressing traditional competitive advantages, while procurement centralization is rewriting channel economics for hospital-system buyers.
Pre-filled syringe presentations are migrating from niche emergency applications toward standard-of-care protocols in high-acuity obstetric units. Tertiary maternity centers in the United States and Germany are adopting these formats to reduce medication preparation errors during acute hemorrhage events. The technology is migrating from premium positioning toward mid-tier hospital procurement tiers as manufacturing scale economies emerge.
EMA's revised Good Manufacturing Practice Annex 1 for sterile medicinal products is mandating barrier isolation technology and continuous environmental monitoring. European facilities must complete facility upgrades or face marketing authorization suspension. Small and mid-sized producers without dedicated aseptic lines are exiting the market rather than absorbing capital requirements.
Hospital system procurement consolidation is compressing distributor margins and favoring direct manufacturer contracts. Integrated delivery networks in the United States are unbundling emergency obstetric kits to source carboprost tromethamine separately from anesthesia and surgical supplies. This pattern is most visible in multi-hospital systems exceeding 50 beds where pharmacy and therapeutics committees wield centralized formulary control.
Global Carboprost Tromethamine Market Segmentation
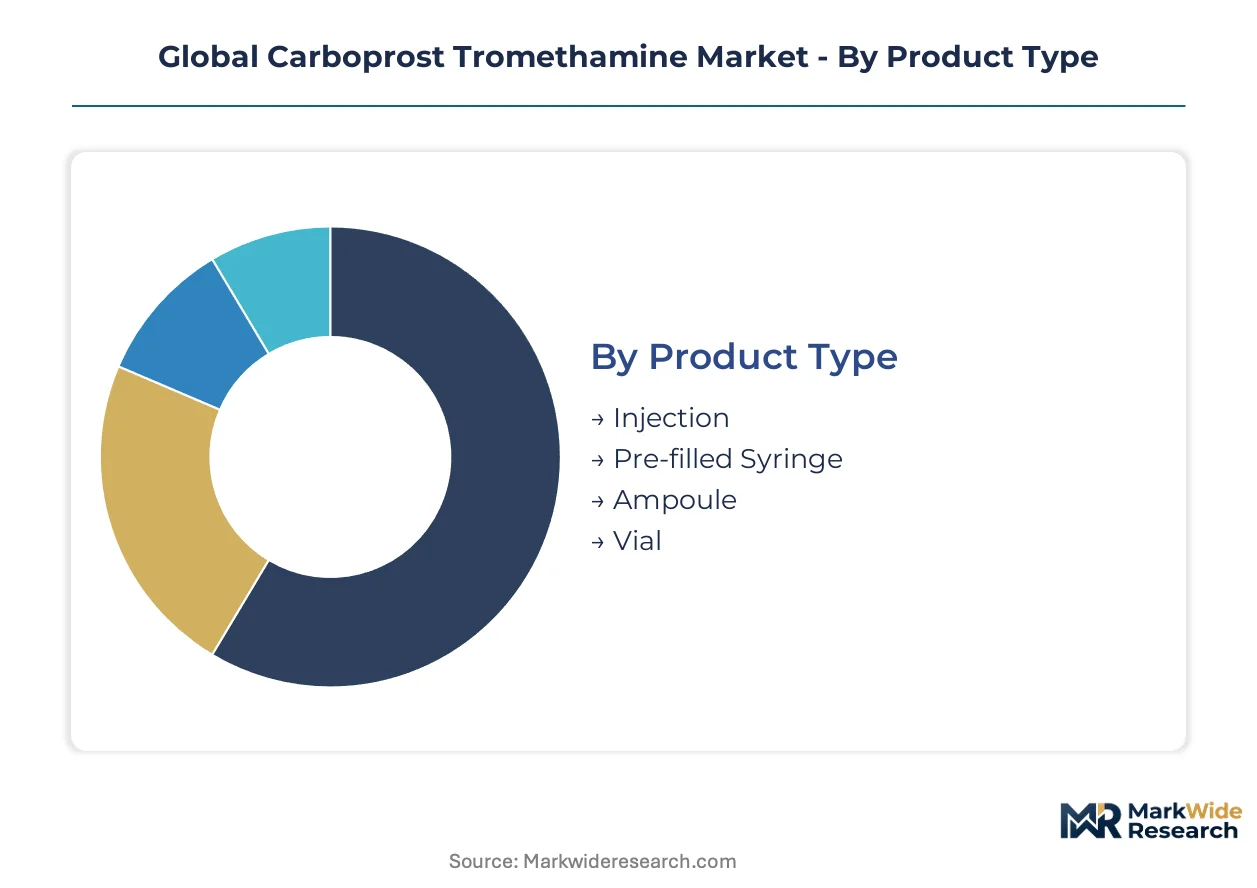
Carboprost tromethamine procurement patterns diverge sharply across clinical settings, with emergency deployment protocols dictating format preferences and channel economics. Understanding how product configurations, application protocols, and distribution pathways fragment reveals where margin pools concentrate and where access barriers persist.
Product Type:
Cost tier differentiation separates commodity ampoules from premium-ready pre-filled configurations, with manufacturing complexity driving procurement stratification.
- Injection:Sterile solution supplied in multi-dose vials requiring compounding prior to intramuscular administration. Hospital obstetric wards in the United States and Germany standardize on this format for bulk procurement, though preparation time constraints limit utility in acute hemorrhage scenarios.
- Pre-filled Syringe:Single-unit presentation with fixed 250 microgram dosing eliminates compounding steps. Emergency care units across tertiary maternity centers are adopting this configuration to reduce medication errors during time-critical postpartum events, with demand climbing fastest in high-acuity settings.
- Ampoule:Glass-sealed unit dose requiring breaking and aspiration before administration. Cost-sensitive hospital systems in India favor this format for routine postpartum protocols where cold chain reliability is established.
- Vial:Multi-dose rubber-stoppered container enabling partial content extraction. Specialty clinics with lower patient throughput prefer this presentation to minimize inventory carrying costs.
Injection holds installed capacity. Pre-filled Syringe is rotating up the share rankings.
Application:
Clinical protocol hierarchies determine utilization intensity, with obstetric emergency applications commanding procurement priority over elective procedures.
- Postpartum Hemorrhage:Refractory uterine bleeding management following vaginal or cesarean delivery represents the foundational indication. WHO prequalification pathways are expanding access across sub-Saharan Africa and South Asia where maternal mortality reduction programs prioritize uterotonic availability.
- Cervical Ripening:Off-label labor induction application is gaining investigator-initiated trial momentum at academic medical centers in Germany and the United States, though regulatory approval remains pending for formal protocol adoption.
- Abortion Induction:Second-trimester pregnancy termination protocols utilize carboprost tromethamine for uterine evacuation. Access concentrates in jurisdictions with permissive reproductive health legislation, creating geographic demand fragmentation.
- Uterine Atony:Prevention and treatment of failed uterine contraction post-delivery follows oxytocin-first protocols in most settings, limiting carboprost tromethamine to refractory cases.
Postpartum Hemorrhage anchors volume commitments. Cervical Ripening is expanding most quickly through academic channel adoption.
End User:
Customer type determines purchasing authority, with centralized hospital pharmacy committees wielding formulary control distinct from decentralized clinic procurement.
- Hospitals:Integrated delivery networks exceeding 50 beds dominate consumption through centralized pharmacy and therapeutics committees. These entities unbundle emergency obstetric kits to source carboprost tromethamine separately, compressing distributor margins.
- Emergency Care Units:Standalone acute response facilities within hospital campuses prioritize pre-filled syringe formats for reduced preparation time. Adoption is concentrating in United States and German tertiary centers with established rapid response protocols.
- Specialty Clinics:Focused obstetric and gynecological practices with lower case volumes purchase through wholesale distributors rather than direct manufacturer contracts.
- Birthing Centers:Midwife-led delivery facilities face regulatory constraints on prostaglandin administration scope in multiple jurisdictions, limiting addressable market penetration.
Hospitals lock in multi-year supply agreements. Emergency Care Units are gaining share fastest through format premiumization.
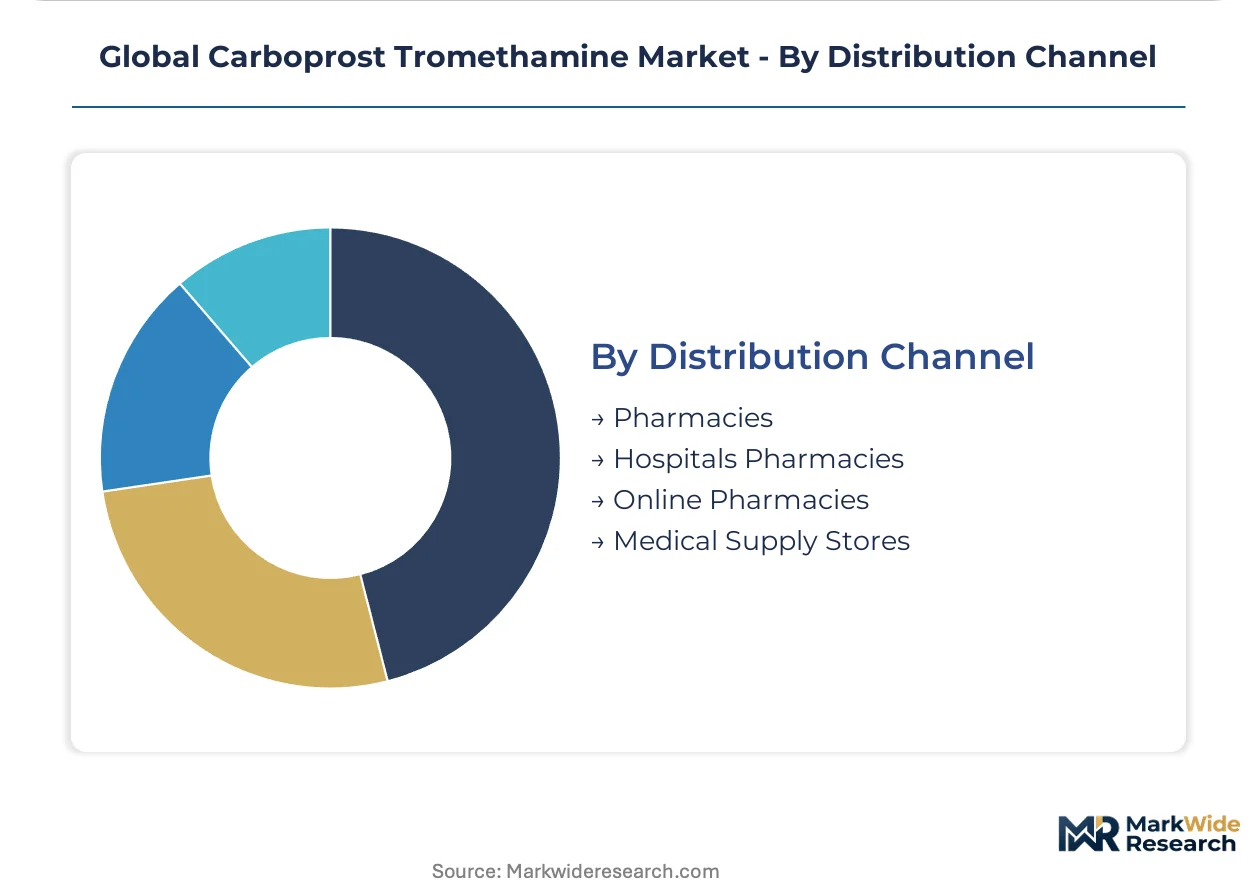
Distribution Channel:
Supply concentration determines price realization, with direct manufacturer contracts displacing traditional wholesale intermediaries in high-volume accounts.
- Hospital Pharmacies:Captive procurement functions within integrated delivery networks negotiate direct contracts with Pfizer and Fresenius Kabi, bypassing distributor markups. This channel commands the largest volume flow.
- Pharmacies:Community and retail pharmacy chains serve outpatient prescription requirements for specialty clinics and individual practitioners, with CDSCO Schedule H1 controls limiting Indian retail availability.
- Medical Supply Stores:Durable medical equipment distributors bundle carboprost tromethamine with surgical and anesthesia supplies for smaller facilities lacking dedicated pharmacy infrastructure.
- Online Pharmacies:Digital procurement platforms are emerging for non-acute replenishment in regulated markets, though cold chain requirements constrain expansion for temperature-sensitive sterile injectables.
Hospital Pharmacies control contract structuring. Online Pharmacies are climbing the fastest despite logistical constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Current Good Manufacturing Practice enforcement anchors the United States as the regulatory benchmark setter, while EMA harmonization and India's PLI scheme create parallel capacity expansion corridors. Demand clusters around hospital obstetric infrastructure in five specific national markets.
United States
Integrated delivery networks exceeding 50 beds drive procurement volume through centralized pharmacy committees. FDA sterile injectable compliance costs exceeding $50 million per facility have forced multi-purpose plants toward dedicated single-product lines. Pfizer maintains integrated sterile injectable capacity across multiple domestic sites to sustain consistent availability.
Germany
Tertiary maternity centers in Bavaria and North Rhine-Westphalia prioritize pre-filled syringe formats for reduced preparation time during acute hemorrhage events. EMA's revised GMP Annex 1 mandates barrier isolation technology upgrades by 2025, with facility remediation timelines compressing smaller producer participation. Fresenius Kabi dominates hospital channel access through dedicated parenteral drug portfolios.
India
Hyderabad and Visakhapatnam anchor expanding prostaglandin synthesis infrastructure that lowers input costs for downstream formulation. CDSCO Schedule H1 prescription controls and manufacturing facility inspections shape domestic distribution scope. The PLI scheme for critical care injectables subsidizes greenfield sterile manufacturing capacity in Telangana and Andhra Pradesh.
United Kingdom
London and Southeast England concentrate academic medical center adoption of cervical ripening protocols through investigator-initiated trials. MHRA alignment with EMA GMP standards streamlines facility inspections for qualified sterile injectable producers. Hospital system procurement consolidation favors direct manufacturer contracts over traditional wholesale intermediaries.
Japan
PMDA sterile injectable manufacturing standards enforce quality benchmarks comparable to FDA and EMA frameworks. The Kanto region around Tokyo hosts tertiary maternity centers with established rapid response protocols for postpartum hemorrhage management. METI industrial policy supports domestic pharmaceutical manufacturing capacity retention for critical care medications.
Global Carboprost Tromethamine Market Competitive Landscape
Capability concentration sits with integrated multinational pharmaceutical manufacturers; scale advantage sits with regional sterile injectable specialists. The market structure tiers across three distinct player categories: global diversified pharmaceutical conglomerates with dedicated parenteral portfolios, mid-sized generic injectable specialists with backward-integrated API capabilities, and emerging market producers leveraging cost-competitive manufacturing corridors. Dominant competitive moves include capacity expansion into dedicated aseptic facilities and strategic partnerships for prostaglandin precursor supply security.
Among integrated multinational manufacturers, Pfizer and Fresenius Kabi occupy positions exemplifying the capability-concentrated tier through established sterile injectable infrastructure across multiple continents. Dr. Reddy's Laboratories represents the emerging market archetype, anchoring cost-competitive production through in-house prostaglandin synthesis capabilities in India's concentrated API manufacturing corridor.
| Leading Market Players |
|---|
| Pfizer |
| Dr. Reddy's Laboratories |
| Fresenius Kabi |
| Teva Pharmaceutical Industries |
| Amneal Pharmaceuticals |
| Hikma Pharmaceuticals |
| Sandoz |
| Sun Pharmaceutical Industries |
| Ferring Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Hyderabad and Visakhapatnam's concentrated prostaglandin synthesis infrastructure anchors input cost structures, directing margin capture toward sterile formulation specialists with captive API access rather than pure-play compounders.
Pricing Analysis
United States and German tertiary centers absorb 30-40% premiums over Indian hospital procurement for identical vial presentations. Pricing stratifies across pre-filled syringe premium tiers, standard multi-dose vial mid-tier, and ampoule economy tiers driven by preparation time requirements and cold chain assurance levels. Cost compression in the ampoule segment is intensifying as CDSCO Schedule H1 enforcement expands domestic Indian competition. Emergency care units demonstrate lowest price sensitivity due to protocol-driven formulary inclusion, while cost-sensitive hospital systems in South Asia prioritize standard vial formats.
Supply Chain Analysis
Single-source vulnerability in prostaglandin precursor supply dominates risk profiles, with three chemical suppliers controlling the majority of global carboprost tromethamine API feedstock. Manufacturing concentration clusters in India, the United States, and Germany, with sterile injectable capacity drawing from Telangana's PLI-subsidized greenfield sites and legacy FDA-registered facilities. Distribution runs through hospital pharmacy direct contracts for high-volume accounts, supplemented by wholesale intermediaries for specialty clinic access. Container closure integrity validation and serialization system integration constitute emerging compliance bottlenecks extending lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA-certified aseptic processing technicians command 40% wage premiums, constraining multi-shift operations and creating a binding constraint on sterile injectable capacity expansion across all producer tiers.
For Market Incumbents: Harden sterile manufacturing capacity through dedicated single-product lines rather than multi-purpose plants, absorbing the $50 million per-site remediation costs to preempt FDA enforcement actions. Anchor prostaglandin precursor supply through long-term offtake agreements with Hyderabad-Visakhapatnam API manufacturers, insulating against single-source vulnerability. Prioritize barrier isolation technology deployment ahead of EMA Annex 1 deadlines to capture market share from smaller producers exiting rather than upgrading. For New Entrants and Emerging Players: Establish a beachhead in cervical ripening protocol supply through investigator-initiated trial partnerships at academic medical centers in Germany and the United Kingdom, where off-label adoption is accelerating fastest. Target India's domestic hospital pharmacy channel leveraging PLI scheme subsidies for greenfield sterile manufacturing in Telangana, positioning below Dr. Reddy's Laboratories on cost while matching CDSCO compliance standards. Lead with pre-filled syringe formats to differentiate from commodity ampoule incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic injectable specialists lacking backward integration into prostaglandin synthesis. The 5-10 year viability window favors platforms with captive API supply and FDA/EMA dual-registered facilities over pure-play compounders exposed to input cost volatility. Monitor WHO prequalification pathway expansion into sub-Saharan Africa and South Asia as the signal indicating addressable market inflection for procurement-eligible producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prostaglandin Synthesis | Captive API supply insulates margin structures from precursor concentration risk among three dominant chemical suppliers. |
| Pre-filled Syringe Manufacturing Scale-Up | Emergency care units in United States and German tertiary centers prioritize reduced preparation time configurations. |
| EMA Annex 1 Barrier Isolation Compliance | Facility remediation timelines compress smaller producer participation, concentrating share among capital-rich incumbents. |
| WHO Prequalification Pathway Navigation | Procurement eligibility for international maternal health programs unlocks sub-Saharan Africa and South Asia demand. |
| Hospital Pharmacy Direct Contracting | Integrated delivery networks exceeding 50 beds unbundle emergency obstetric kits, displacing wholesale intermediaries. |
Research Methodology
Cross-validation between primary interviews with sterile manufacturing executives, regulatory affairs leads, hospital procurement managers, and formulary directors anchors the qualitative findings against secondary sources including FDA filings, EMA submissions, CDSCO manufacturing facility inspection records, and WHO prequalification databases. Bottom-up demand modeling triangulates against top-down market sizing derived from customs data and hospital procurement database aggregation.
Calibration against historical volume trajectories and capacity utilization rates across the analysis window informs the analytical framework. Segmentation dimensions include product format, clinical application protocol, end-user purchasing authority, and regional regulatory cluster. CAGRs were derived from trend-line extrapolation adjusted for facility compliance timelines and procurement centralization patterns. Sterile injectable capacity expansion schedules and prostaglandin precursor supply commitments constitute key forecast inputs.
Stress conditions across FDA enforcement intensity, EMA Annex 1 compliance deadlines, and PLI scheme subsidy duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained hospital obstetric infrastructure investment and stable prostaglandin precursor supply availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Chemotherapy Drugs Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Recombinant Human Interferon Protein Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market