
 Somatropin Market | 2026-2036
Somatropin Market Size, Share, and Industry Trends Forecast 2026-2036
Somatropin Market Insights
The EU Green Deal's pharmaceutical sustainability targets is consolidating procurement standards for biologic therapies across European hospital networks. Novo Nordisk leverages its recombinant DNA manufacturing scale to sustain supply security for European pediatric endocrinology centers. Pfizer anchors North American distribution through specialty pharmacy partnerships, while Eli Lilly and Company differentiates via sustained-release formulation technology.
Somatropin is a recombinant human growth hormone produced through Escherichia coli or mammalian cell expression systems, consisting of 191 amino acids identical to pituitary-derived hGH; it stimulates linear growth, protein synthesis, and lipolysis in patients with endogenous growth hormone deficiency. Injectable formulations dominate current revenue due to established reimbursement pathways and clinician familiarity, while lyophilized presentations are gaining traction in emerging markets where cold-chain infrastructure remains limited. Pediatric growth hormone deficiency applications command the largest patient volume, though adult GHD represents a higher-margin segment with longer treatment durations and less price sensitivity.
FDA's biosimilar approval framework and EMA's biosimilar guidelines shape competitive entry timelines, while WHO prequalification requirements influence procurement decisions in low-income countries. The central bank and national health technology assessment bodies in major markets increasingly tie reimbursement to real-world evidence generation. Stakeholders must monitor evolving interchangeability designations and their cascading effects on pharmacy benefit manager formulary placement.
Market Dynamics
EMA's tightening biosimilar interchangeability guidelines and FDA's evolving substitution rules are forcing manufacturers to rebuild clinical evidence packages, while cold-chain infrastructure gaps in emerging markets fragment distribution economics.
Growth Catalysts
- Pediatric hospital networks:Specialized endocrinology centers in Germany, Japan, and the United States are expanding hormone therapy protocols, creating dedicated demand corridors for recombinant growth hormone formulations.
- WHO prequalification pathways:The framework is unlocking procurement access across low-income country immunization programs, enabling volume scaling for lyophilized presentations that tolerate temperature excursions.
- Sustained-release engineering:Polymer-based depot formulations reduce injection frequency from daily to weekly, improving pediatric adherence and extending treatment persistence in long-duration adult GHD protocols.
Market Restraints
- Recombinant protein input volatility:Fermentation-grade amino acid costs fluctuate with agricultural commodity cycles, compressing margin buffers for E. coli expression system operators.
- Single-source supplier concentration:Mammalian cell culture media production clusters in Switzerland and South Korea, exposing fill-finish networks to geopolitical transit disruptions.
- Interchangeability designation friction:FDA's heightened pharmacokinetic equivalence requirements delay biosimilar substitution authority, prolonging reference product market protection.
Strategic Opportunities
- Brazilian public health expansion:ANVISA's accelerated review track for orphan biologics opens procurement channels through the Sistema Único de Saúde for pediatric GHD patients in underserved interior states.
- Adult metabolic syndrome overlap:Emerging protocols targeting sarcopenia and visceral adiposity in aging populations extend somatropin addressable indications beyond traditional deficiency diagnoses.
- Direct-to-patient pharmacy models:Specialty distributors are building temperature-controlled home delivery networks that bypass hospital markup structures and capture adherence data.
Industry Challenges
- Bioprocess engineering talent scarcity:Recombinant protein purification and viral clearance validation expertise concentrates in Basel and Boston corridors, inflating compensation for facility scale-up teams.
- Serialization compliance timelines:EU Falsified Medicines Directive and Drug Supply Chain Security Act track-and-trace mandates require packaging line retrofits that strain capital deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Somatropin Market |
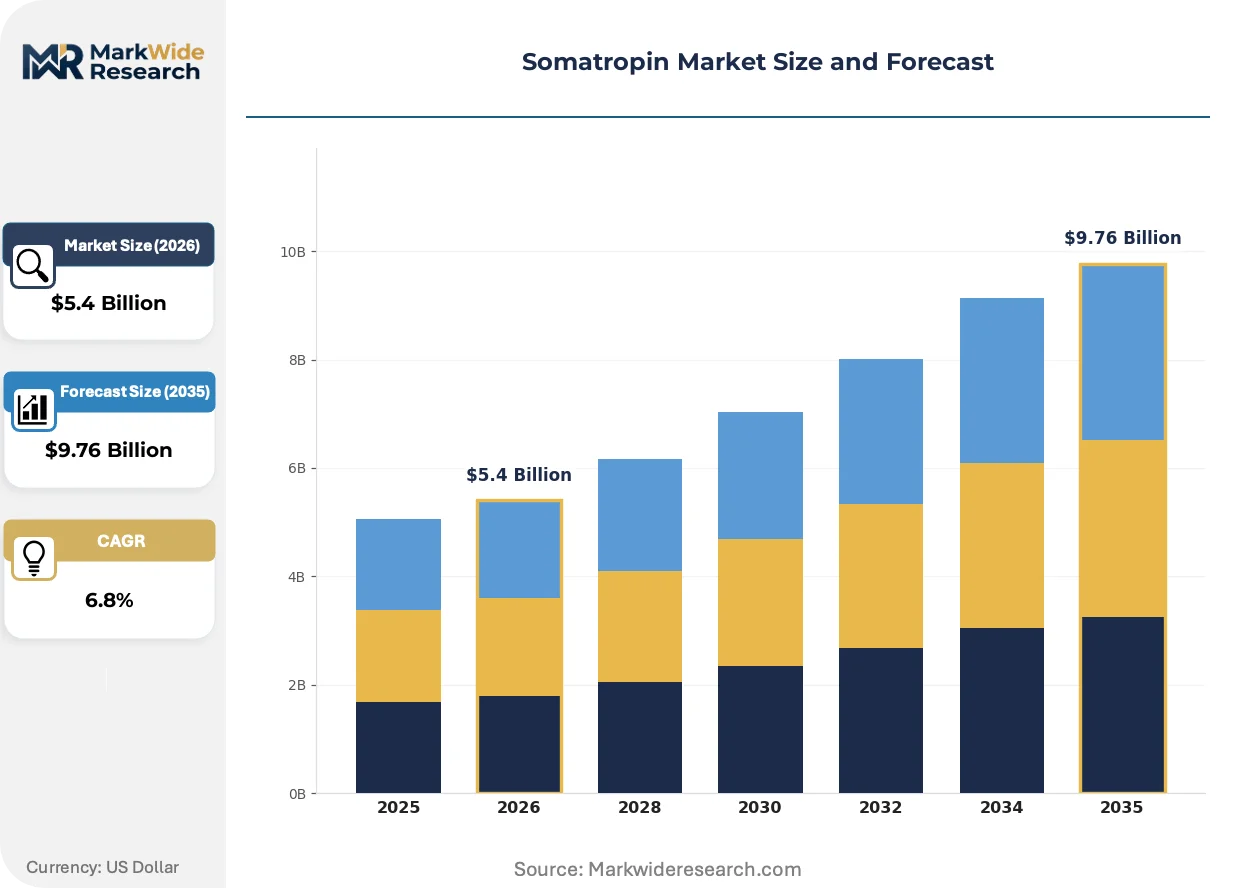
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Powder, Solution, Lyophilized End User: Pediatric Patients, Adults, Clinics, Hospitals Application: Growth Hormone Deficiency, Turner Syndrome, Chronic Kidney Disease, Short Stature Distribution Channel: Hospital Pharmacies, Online Pharmacies, Retail Pharmacies, Specialty Pharmacies |
| Companies Covered | Novo Nordisk, Pfizer, Eli Lilly and Company, Sandoz, Genentech, Merck KGaA, Ferring, Teva Pharmaceutical Industries, Ipsen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Somatropin Market Trends and Innovations
Biologic delivery systems and regulatory evidence standards are converging to redefine competitive differentiation, with formulation innovation outpacing molecular engineering in near-term value creation.
Needle-free recombinant protein delivery is rewriting administration economics for pediatric populations. Jet injector platforms eliminate needle anxiety and sharps disposal burdens in school-based care settings. Hospital systems in Scandinavia and the Netherlands are piloting these devices for routine growth hormone protocols, compressing nursing time per dose and enabling caregiver self-administration training.
REACH-compliant solvent substitution mandates are forcing reformulation of protein stabilization buffers across European manufacturing networks. ECHA's 2024 restrictions on dimethyl sulfoxide in parenteral applications require validation of alternative cryoprotectants in lyophilized somatropin presentations. German and French fill-finish contractors are absorbing six-to-nine month requalification delays while maintaining supply continuity for existing EMA-approved stocks.
Hospital procurement consortia are consolidating biologic purchasing through centralized tendering platforms that unbundle device and drug components. Pediatric endocrinology departments in the United Kingdom and Australia are negotiating direct manufacturer contracts for multi-year supply security, displacing traditional wholesale distribution markups. This concentration shifts price discovery power toward formulary committees and away from individual prescriber preference.
Somatropin Market Segmentation
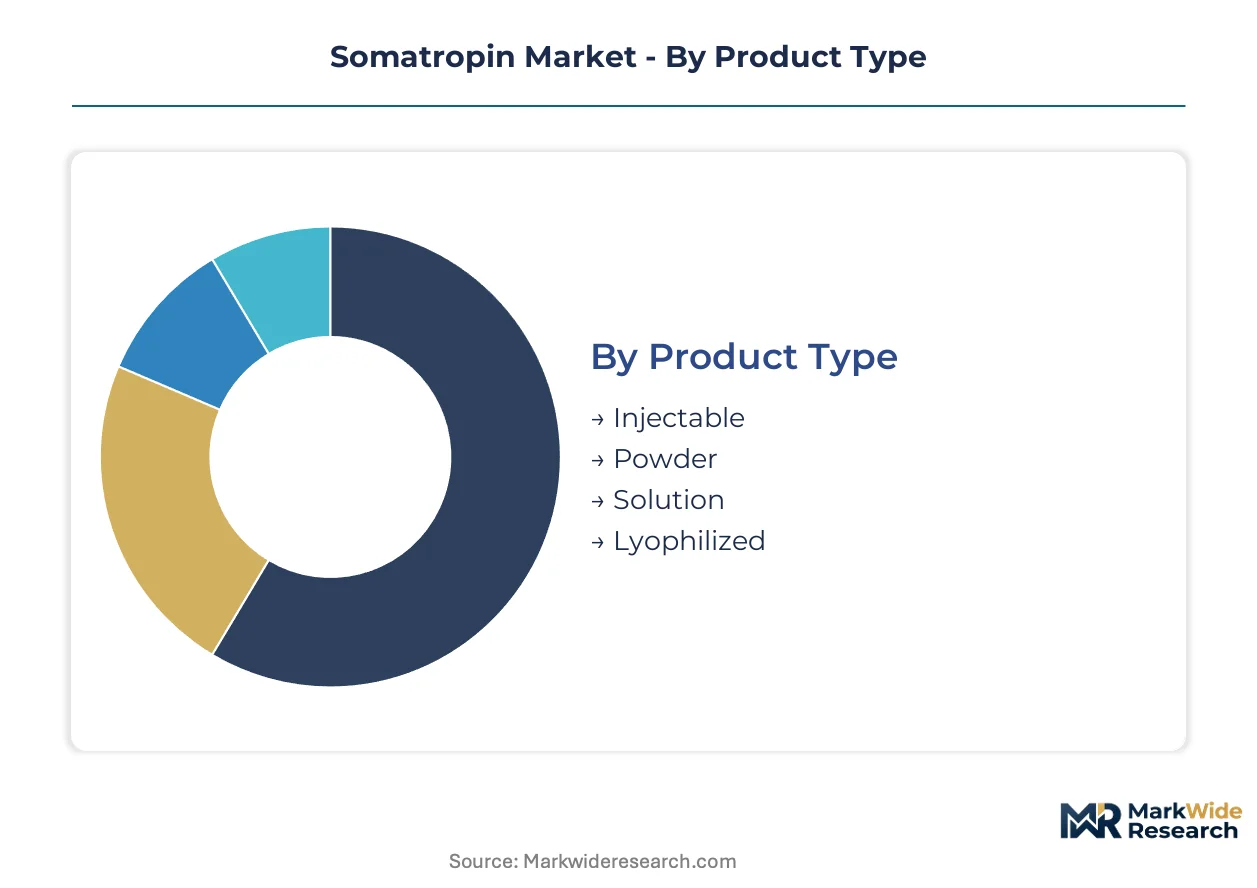
Somatropin segmentation reveals how formulation choices, patient demographics, and channel access create distinct commercial battlegrounds. Each dimension carries unique regulatory burdens and margin profiles that shape manufacturer strategy.
Product Type:
EMA stability guidelines and FDA sterility requirements impose divergent validation timelines across liquid and solid presentations, with cold-chain tolerance becoming the critical differentiator for market access.
- Injectable:Ready-to-use liquid formulations in pre-filled pens dominate reimbursed prescriptions in Germany and Japan due to nursing workflow efficiency. Hospital procurement teams in these markets prioritize needle-retraction safety mechanisms and automated dose-counters over unit cost.
- Lyophilized:Freeze-dried cakes reconstituted with bacteriostatic water tolerate temperature excursions up to 25°C for 72 hours, unlocking distribution to interior Brazilian states and Nigerian tertiary centers where cold-chain continuity fails. WHO prequalification for this presentation is accelerating volume tenders.
- Powder:Bulk active pharmaceutical ingredient for compounding pharmacies serving rare metabolic protocols.
- Solution:Multi-dose vials for institutional purchasing in cost-constrained Eastern European markets.
Injectable sits at the top of the volume ranking, with lyophilized climbing the fastest.
End User:
Reimbursement pathways fragment sharply between pediatric and adult populations, with age-based coverage determinations creating distinct pricing corridors across national health technology assessment regimes.
- Pediatric Patients:School-age cohorts with idiopathic short stature or genetic syndromes generate the largest absolute prescription volumes. Parents in the United States and United Kingdom drive device selection through adherence preferences, with weekly depot injections commanding premium co-pay tolerance over daily alternatives.
- Adults:Post-pituitary surgery or cranial irradiation survivors require indefinite replacement therapy. This segment carries minimal price elasticity in Swiss and Dutch markets where metabolic quality-of-life endpoints justify sustained reimbursement.
- Clinics:Private endocrinology practices in São Paulo and Mumbai handling diagnosis and initiation.
- Hospitals:Academic medical centers managing complex multi-hormone deficiencies and transition care.
Pediatric patients anchor absolute volume, while adults deliver superior per-patient lifetime value.
Application:
Indication-specific clinical trial requirements and orphan drug designations create segmented competitive moats, with diagnostic coding precision determining formulary placement speed.
- Growth Hormone Deficiency:The foundational indication spans congenital, acquired, and idiopathic etiologies. Diagnostic confirmation via insulin tolerance testing or glucagon stimulation protocols is mandatory for French and Italian reimbursement, creating a controlled-access funnel that limits prescription expansion.
- Turner Syndrome:45,X karyotype patients require estrogen-coordinated protocols from age 4-6. Swedish and Danish national registries track long-term cardiovascular outcomes, generating real-world evidence that supports extended labeling.
- Chronic Kidney Disease:Pre-transplant growth failure in pediatric dialysis populations.
- Short Stature:Idiopathic cases below 2.25 standard deviations without biochemical deficiency.
Growth hormone deficiency commands the widest prescriber base, with Turner syndrome gaining share fastest in screened newborn programs.
Distribution Channel:
Cold-chain custody requirements and patient counseling intensity favor channel specialization, with temperature monitoring liability pushing consolidation toward certified operators.
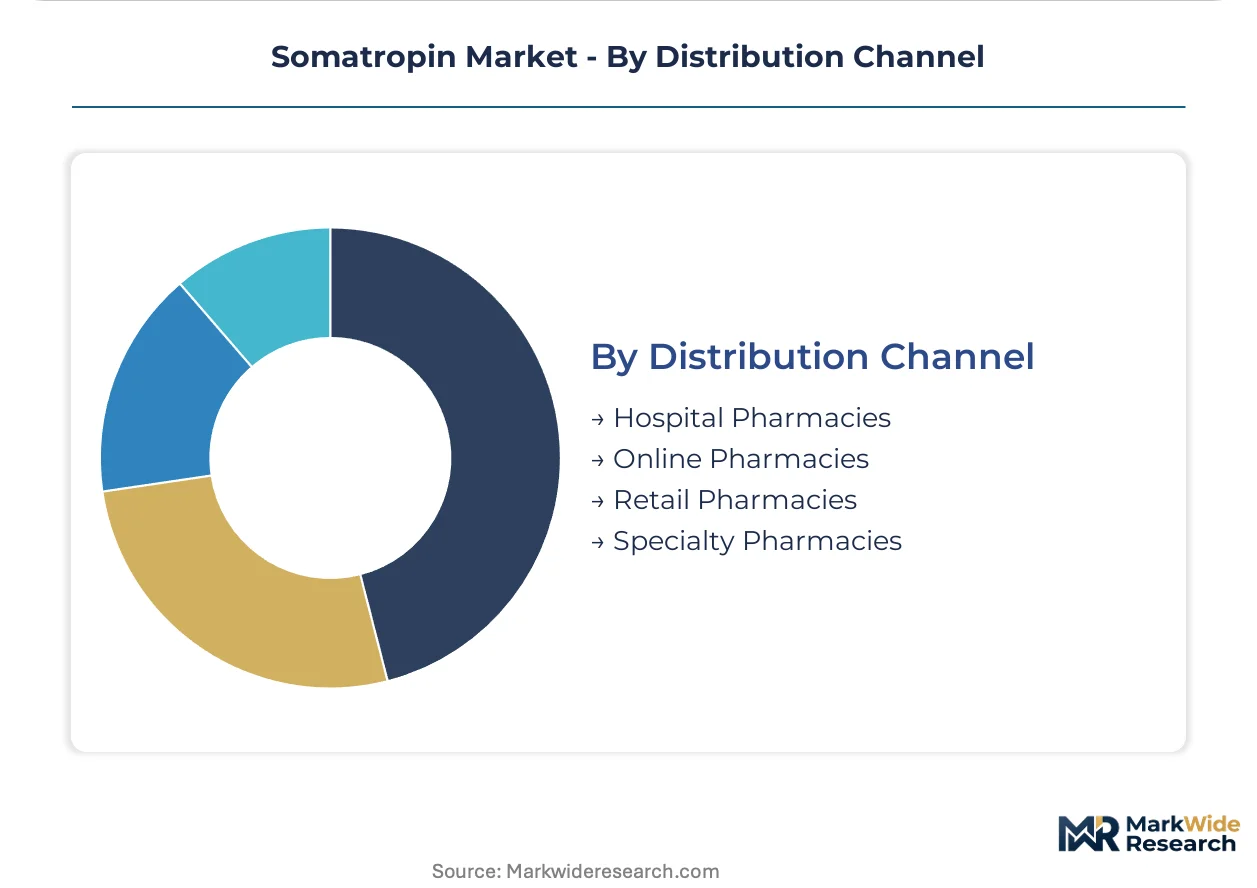
- Hospital Pharmacies:Integrated with pediatric endocrinology wards in Tokyo, Berlin, and Boston, these sites manage dose titration and adverse event reporting. Their captive patient flows insulate them from retail price competition.
- Specialty Pharmacies:Accredited hubs in the United States coordinate prior authorization, benefits investigation, and home nursing training. Their data capture supports manufacturer adherence programs and outcomes contracting with pharmacy benefit managers.
- Retail Pharmacies:Limited to stable maintenance prescriptions in markets with relaxed cold-chain requirements.
- Online Pharmacies:Direct-to-patient models piloting in Nordic markets with integrated telemedicine follow-up.
Hospital pharmacies handle the greatest prescription volume, while specialty pharmacies are expanding most quickly through integrated care contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant growth hormone therapy originated in Swiss and American university laboratories during the 1980s, with commercial scale-up following shortly in German and Japanese pharmaceutical corridors. National reimbursement frameworks and pediatric endocrinology infrastructure now determine where patient access expands fastest.
United States
Specialty pharmacy networks and integrated delivery systems drive prescription fulfillment for pediatric and adult growth hormone deficiency patients. FDA's evolving interchangeability guidelines for biosimilars shape formulary placement timelines for new entrants. Boston and San Francisco anchor clinical trial density for sustained-release formulation development.
Germany
Pediatric hospital networks in Bavaria and North Rhine-Westphalia maintain dedicated endocrinology wards with standardized hormone replacement protocols. EMA stability guidelines and the EU Green Deal's pharmaceutical sustainability targets consolidate procurement standards across university hospital consortia. The Basel-Mannheim corridor concentrates fill-finish manufacturing for European distribution.
Japan
Aging demographics and screened newborn programs expand the addressable patient base for both pediatric idiopathic short stature and adult metabolic syndrome applications. PMDA's streamlined orphan drug designation accelerates review timelines for novel formulations. Tokyo and Osaka academic medical centers generate real-world evidence supporting extended treatment durations.
Brazil
ANVISA's accelerated review track for orphan biologics opens procurement channels through the Sistema Único de Saúde for underserved interior states. Lyophilized presentations that tolerate temperature excursions unlock distribution beyond cold-chain-dependent coastal metros. São Paulo's private endocrinology practices handle diagnosis and initiation for affluent patient segments.
India
Domestic fermentation capacity and cost-engineered E. coli expression systems position local manufacturers for WHO prequalification and low-income country tenders. CDSCO's tightening biosimilar guidelines align with global reference product standards. Hyderabad and Mumbai clusters specialize in recombinant protein purification and viral clearance validation for export markets.
Somatropin Market Competitive Landscape
Capital-heavy producers with captive fermentation capacity compete with asset-light formulation specialists who outsource biologic drug substance manufacturing. The market structure consolidates around a handful of integrated innovators while fragmenting across regional biosimilar challengers and niche device-technology partners. Three archetypes dominate: full-stack innovators controlling expression systems and delivery devices, biosimilar pure-plays leveraging contract manufacturing, and sustained-release engineering specialists. Capacity expansion in mammalian cell culture and strategic partnerships for polymer-based depot formulations represent the dominant competitive moves.
Among integrated innovators, Novo Nordisk and Pfizer exemplify the archetype of manufacturers combining recombinant DNA production scale with proprietary delivery device ecosystems. Eli Lilly and Company occupies a position within the sustained-release engineering tier, anchoring competitive differentiation through formulation technology rather than molecular innovation alone.
| Leading Market Players |
|---|
| Novo Nordisk |
| Pfizer |
| Eli Lilly and Company |
| Sandoz |
| Genentech |
| Merck KGaA |
| Ferring |
| Teva Pharmaceutical Industries |
| Ipsen |
| Others |
Pricing and Supply Chain Analysis
Captive fermentation capacity anchors supply security and pricing power for integrated innovators, while outsourced biologic drug substance manufacturing fragments cost control for pure-play formulators. This structural split between in-house E. coli expression systems and contract mammalian cell culture operations creates divergent margin trajectories across the competitive landscape.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by device sophistication and cold-chain requirements. Premium pre-filled pens with automated dose-counters command higher reimbursement in German and Japanese hospital networks, while lyophilized presentations in cost-constrained markets compete on temperature tolerance. Cost compression in the economy tier is intensifying because WHO prequalification pathways unlock volume tenders from low-income country procurement pools. Pediatric endocrinology departments demonstrate the highest price sensitivity due to budget constraints in public health systems, whereas adult GHD replacement protocols in Swiss and Dutch markets show minimal elasticity.
Supply Chain Analysis
Direct-to-hospital specialty pharmacy channels handle reimbursed prescriptions in Germany, Japan, and the United States, bypassing wholesale markups through integrated care contracts. Fermentation-grade amino acid inputs draw from agricultural commodity suppliers in the United States and Brazil, while mammalian cell culture media production clusters in Switzerland and South Korea. Single-source supplier concentration for critical media components exposes fill-finish networks to geopolitical transit disruptions. Distribution runs through temperature-controlled logistics partners certified under EU Falsified Medicines Directive and Drug Supply Chain Security Act track-and-trace mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Somatropin functions as a regulatory compounder where EMA biosimilar interchangeability tightening and FDA substitution rule evolution continuously reshape competitive access. These regulatory milestones extend reference product protection periods and redirect manufacturer investment toward clinical evidence generation.
For Market Incumbents: Acquire sustained-release formulation patents to extend device-technology moats against polymer-based depot competitors. Consolidate backward integration into fermentation-grade amino acid supply through long-term offtake agreements with agricultural processors, insulating margin buffers from commodity volatility. Defend against biosimilar pure-plays by accelerating real-world evidence generation through pediatric registry partnerships in Sweden and Denmark.
For New Entrants and Emerging Players: Underserved interior Brazilian states present the most penetrable geography, where ANVISA accelerated review tracks and Sistema Único de Saúde procurement channels remain underdeveloped. Target lyophilized presentation tenders for Nigerian tertiary centers and Indian public health expansion, leveraging WHO prequalification as market entry credential. Build direct-to-patient pharmacy models with integrated telemedicine follow-up to bypass established hospital markup structures.
For Investors and Strategic Acquirers: Roll-up economics work for regional biosimilar pure-plays because EMA and FDA regulatory harmonization creates scalable approval pathways across multiple jurisdictions. The five-to-ten year viability window favors manufacturers with captive E. coli expression capacity and validated viral clearance expertise. Watch FDA interchangeability designation grants as the critical inflection signal for substitution authority expansion and reference product revenue erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive fermentation capacity in Basel-Mannheim corridor secures European supply continuity. |
| Regulatory Approval Pathway | WHO prequalification unlocks volume tenders across low-income country immunization programs. |
| Pipeline Diversification | Adult metabolic syndrome protocols extend addressable indications beyond deficiency diagnoses. |
| Licensing Agreement | Polymer-based depot formulation partnerships reduce injection frequency and improve adherence. |
| Hospital System Partnership | Pediatric endocrinology ward integration in Tokyo and Berlin insulates from retail price competition. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided qualitative insights through structured interviews. FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases supplied secondary data. Bottom-up prescription volume modeling and top-down market sizing triangulated value estimates.
Rate-of-change decomposition separates volume expansion from price evolution across the projection horizon. Segmentation dimensions include product type, end user demographic, application indication, and distribution channel, with regional regulatory cluster as an additional modeled variable. CAGRs were derived from patient population growth, treatment penetration rates, and reimbursement trajectory assumptions. Forecast inputs incorporate insulin tolerance testing protocol adoption and sustained-release formulation launch timelines.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-world adherence data from emerging markets introduce uncertainty bands around volume projections. Forecasts reflect assumptions regarding EMA interchangeability guideline implementation speed and WHO prequalification pathway expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Purified Protein Derivative Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Recombinant Human Interferon Protein Market
Biopharmaceuticals
Global Human Recombinant Insulin Market