
 Canada Generic Drug Market | 2026-2036
Canada Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Generic Drug Market Intelligence
Bioequivalence certification to Health Canada's highest tier is rotating the competitive landscape toward manufacturers with advanced analytical capabilities. Apotex Inc. anchors domestic production with vertically integrated API-to-finished-dose operations in Ontario. Teva Canada leverages its respiratory and central nervous system portfolios to sustain hospital formulary positions. Novartis (Sandoz Group) differentiates through complex injectable and biosimilar development pipelines.
Canada generic drugs are chemically identical, bioequivalent copies of brand-name pharmaceuticals, manufactured after patent expiry and meeting identical strength, dosage form, route of administration, and performance characteristics for therapeutic equivalence. These products serve primarily to reduce public and private drug plan expenditures while maintaining clinical outcomes across chronic and acute care settings. Oral solid dosage forms dominate volume through retail pharmacy channels, though injectable generics capture disproportionate margin pools in hospital settings. Metformin and other diabetes management active ingredients represent mature, high-volume categories with intense price competition, while complex topical and inhalable formats offer structural insulation from commoditization.
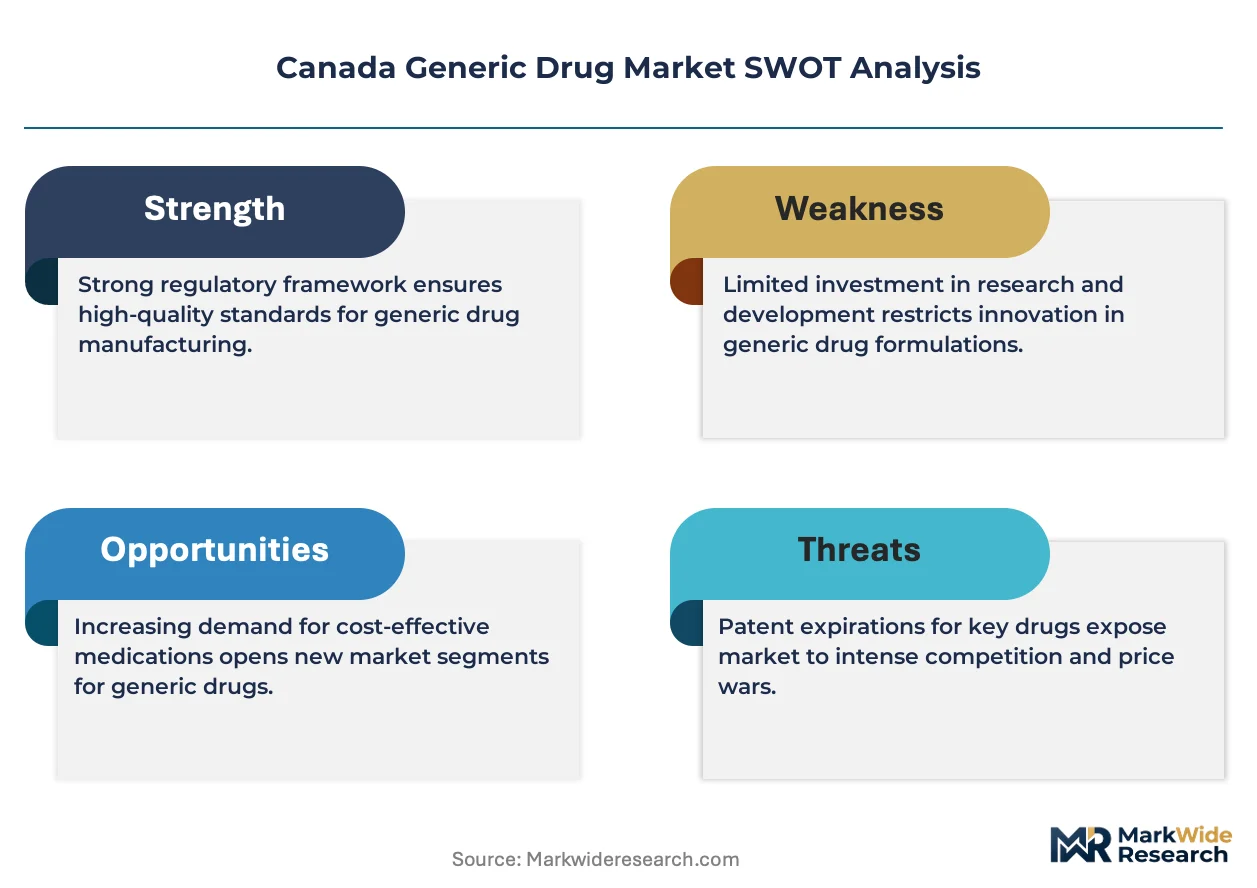
Health Canada, the Patented Medicine Prices Review Board (PMPRB), and provincial formularies including Ontario's Drug Benefit Program collectively shape market access, pricing ceilings, and reimbursement eligibility for generic entrants. PMPRB's revised pricing guidelines constrain maximum allowable prices relative to international benchmarks, while Health Canada's ICH-aligned bioequivalence standards determine which manufacturers qualify for accelerated listing. Stakeholders must monitor evolving provincial tendering consolidation and the federal government's pharmacare expansion negotiations to anticipate shifts in procurement leverage and formulary priority.
Market Dynamics
Provincial formulary consolidation is concentrating procurement leverage among fewer buyers, forcing manufacturers to compete on bioequivalence certification tiers rather than price alone. Health Canada's accelerated review pathways for complex generics are redistributing market position toward facilities with advanced analytical capabilities.
Growth Catalysts
- Health Canada Bioequivalence Tiering:Manufacturers achieving highest-tier certification gain priority listing on Ontario's Drug Benefit Program, creating procurement advantages for chronic disease categories.
- Hospital Injectable Concentration:Prairie provinces are consolidating hospital pharmacy procurement of sterile injectables, generating volume commitments that stabilize manufacturing utilization.
- Complex Generic Pipeline:Inhalable and topical formats with specialized delivery mechanisms command formulary preference due to limited substitutability and higher therapeutic value.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient sourcing depends heavily on offshore suppliers, exposing finished-dose manufacturers to customs delays and quality variability.
- PMPRB Pricing Compression:The Patented Medicine Prices Review Board's international benchmark ceilings constrain generic pricing flexibility even for differentiated formulations.
- Bioanalytical Capacity Bottleneck:Limited domestic facilities capable of Health Canada's most stringent bioequivalence studies create queuing delays for market entrants.
Strategic Opportunities
- British Columbia Formulary Expansion:Provincial authorities are broadening chronic disease coverage, opening access for cardiovascular and diabetes management portfolios.
- Complex Injectable Manufacturing:Hospital demand for lyophilized and pre-filled syringe formats exceeds domestic supply, rewarding capital investment in sterile fill-finish lines.
- Pharmacare Negotiation Positioning:Federal expansion discussions create early-mover advantages for manufacturers aligning product portfolios with anticipated national formulary priorities.
Industry Challenges
- Bioequivalence Study Talent Scarcity:Clinical pharmacokinetic specialists and biostatisticians with Health Canada submission experience command premium compensation, constraining study throughput.
- Legacy ERP Integration:Provincial tendering platforms require real-time inventory and pricing data feeds that strain older manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Generic Drug Market |
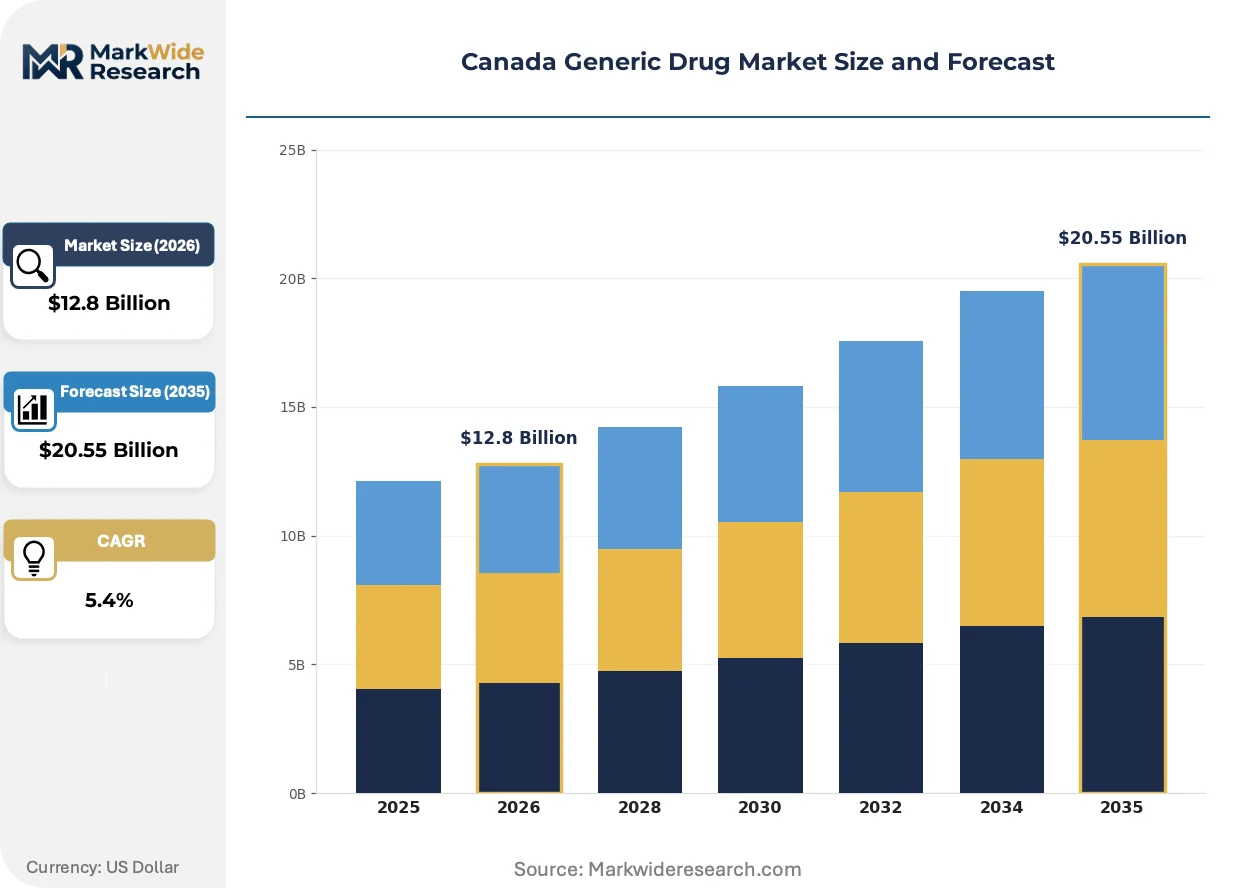
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Oral, Injectable, Topical, Inhalable Active Ingredient: Ibuprofen, Amoxicillin, Metformin, Omeprazole Therapy Area: Pain Relief, Infection Control, Diabetes Management, Gastrointestinal Health Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Wholesalers |
| Companies Covered | Novartis (Sandoz Group), AstraZeneca, Apotex Inc., Bayer, Pfizer, Teva Canada, Roche (generic division), Merck, Pharmascience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Generic Drug Market Strategic Shifts & Innovations
Continuous manufacturing platforms and real-time release testing are restructuring how Canadian facilities validate batch quality, compressing inspection timelines while raising capital requirements. These shifts favor producers with captive analytical capabilities and integrated quality systems.
Continuous direct compression technology is bifurcating the oral solid dosage landscape. Facilities in Ontario adopting this platform reduce batch cycle times from weeks to days. Health Canada is aligning inspection protocols with real-time release parameters, enabling faster market entry for qualified sites while marginalizing traditional batch-release operations.
The Patented Medicine Prices Review Board's revised pricing guidelines are tightening allowable ceilings against international benchmarks. Generic manufacturers must now demonstrate value through bioequivalence tiering rather than cost positioning alone. Ontario's Drug Benefit Program has responded by weighting procurement scores toward highest-tier certified suppliers.
Hospital pharmacy consortiums across Alberta and Saskatchewan are consolidating injectable purchasing through single-source agreements. This buyer concentration is displacing fragmented multi-vendor arrangements that characterized past procurement cycles. Manufacturers with dedicated sterile manufacturing lines and Prairie distribution infrastructure capture disproportionate volume allocation.
Canada Generic Drug Market Segmentation
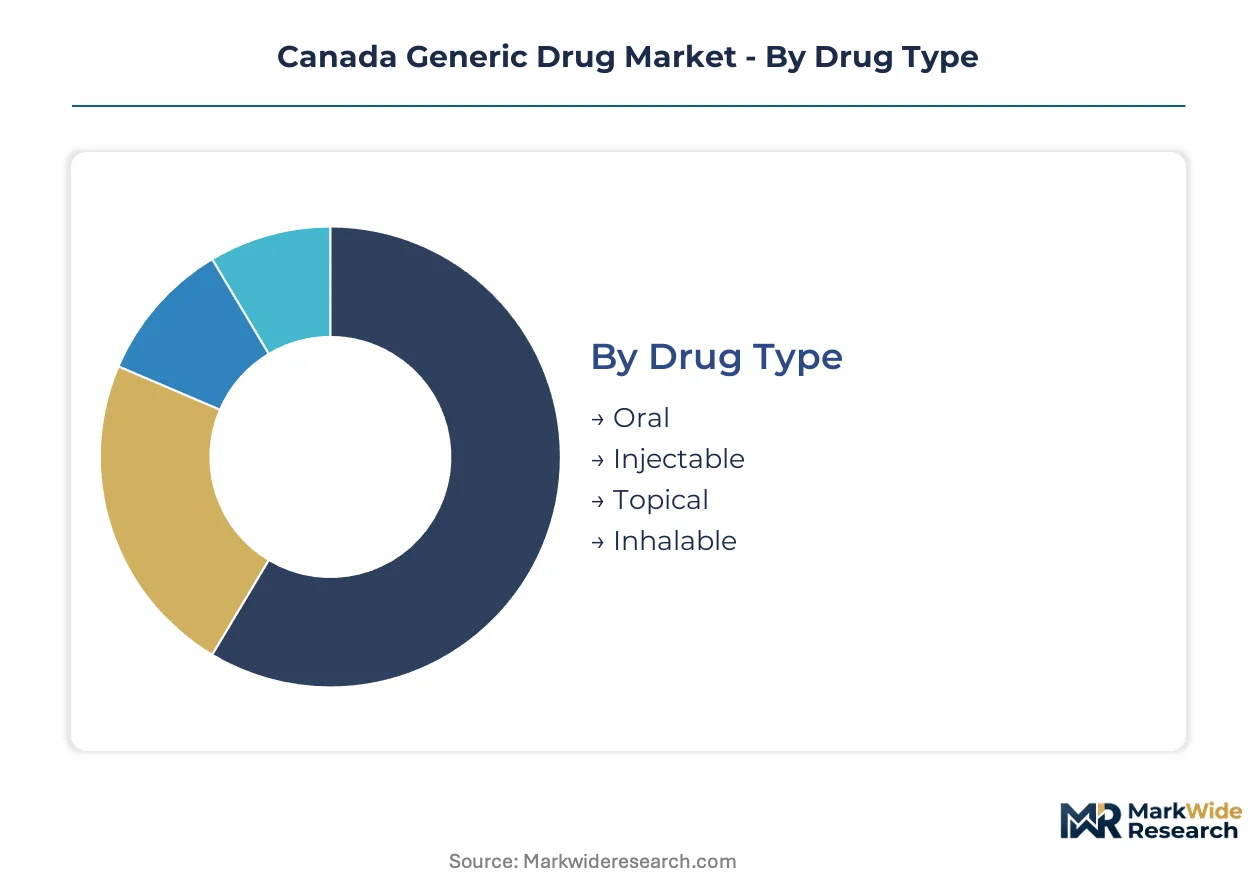
Canada's generic drug market segments along four functional dimensions that determine regulatory pathway, manufacturing investment, and procurement access. Provincial formularies apply distinct weighting schemes across these categories, creating divergent margin profiles for manufacturers.
Drug Type:
Injectable and inhalable formats dominate export-oriented production from Ontario and Quebec facilities, while oral solids serve primarily domestic retail demand.
- Oral:Compressed tablets and capsules constitute the highest-volume category, with metformin and cardiovascular actives moving through Ontario's Drug Benefit Program in bulk tenders. Price compression is most severe here due to multi-source substitutability.
- Injectable:Sterile vials, pre-filled syringes, and lyophilized formats command premium positioning through hospital procurement consortiums in Alberta and Saskatchewan. Prairie provinces are consolidating single-source agreements for these products.
- Topical:Creams, gels, and transdermal patches require specialized bioequivalence studies for absorption kinetics. Limited domestic manufacturing capacity creates import dependence for complex formulations.
- Inhalable:Metered-dose and dry-powder devices face the steepest technical barriers, with Health Canada requiring device-specific bioequivalence demonstrations that few manufacturers can satisfy.
Oral holds the largest share; momentum sits with injectable formats as hospital procurement consolidates.
Active Ingredient:
Cost tiering separates mature high-volume actives from specialized molecules with limited supplier bases.
- Ibuprofen:A mature non-steroidal anti-inflammatory with API sourcing concentrated in India and China. Finished-dose manufacturers compete on Health Canada bioequivalence tiering rather than molecular differentiation.
- Amoxicillin:Beta-lactam antibiotic production requires dedicated penicillin-handling facilities. Domestic capacity constraints force reliance on European and Indian finished-dose imports.
- Metformin:The reference standard for diabetes management volume, with Ontario's Drug Benefit Program driving procurement scale. Intense price competition has compressed margins to cost-plus levels.
- Omeprazole:Proton pump inhibitor demand concentrates in retail pharmacy channels for chronic gastrointestinal maintenance. Bioequivalence studies for delayed-release formulations require specialized dissolution profiling.
Metformin captures the greatest procurement volume; omeprazole is expanding most quickly as proton pump inhibitor prescribing extends to younger demographics.
Therapy Area:
Application urgency determines channel access, with acute care categories receiving faster formulary review.
- Pain Relief:NSAIDs and acetaminophen combinations face the most aggressive generic substitution policies. Provincial formularies mandate lowest-cost alternatives unless contraindicated.
- Infection Control:Antibiotic stewardship programs in British Columbia and Ontario hospitals restrict broad-spectrum generic use. Narrow-spectrum alternatives with microbiological specificity gain preferential access.
- Diabetes Management:Metformin and sulfonylurea volumes anchor retail pharmacy procurement, though insulin biosimilars are displacing traditional generic small-molecule categories.
- Gastrointestinal Health:Chronic acid suppression therapies generate recurring prescription volume. British Columbia's formulary expansion is broadening coverage for these maintenance categories.
Pain relief holds the largest share; diabetes management is gaining share fastest as population aging accelerates chronic disease prevalence.
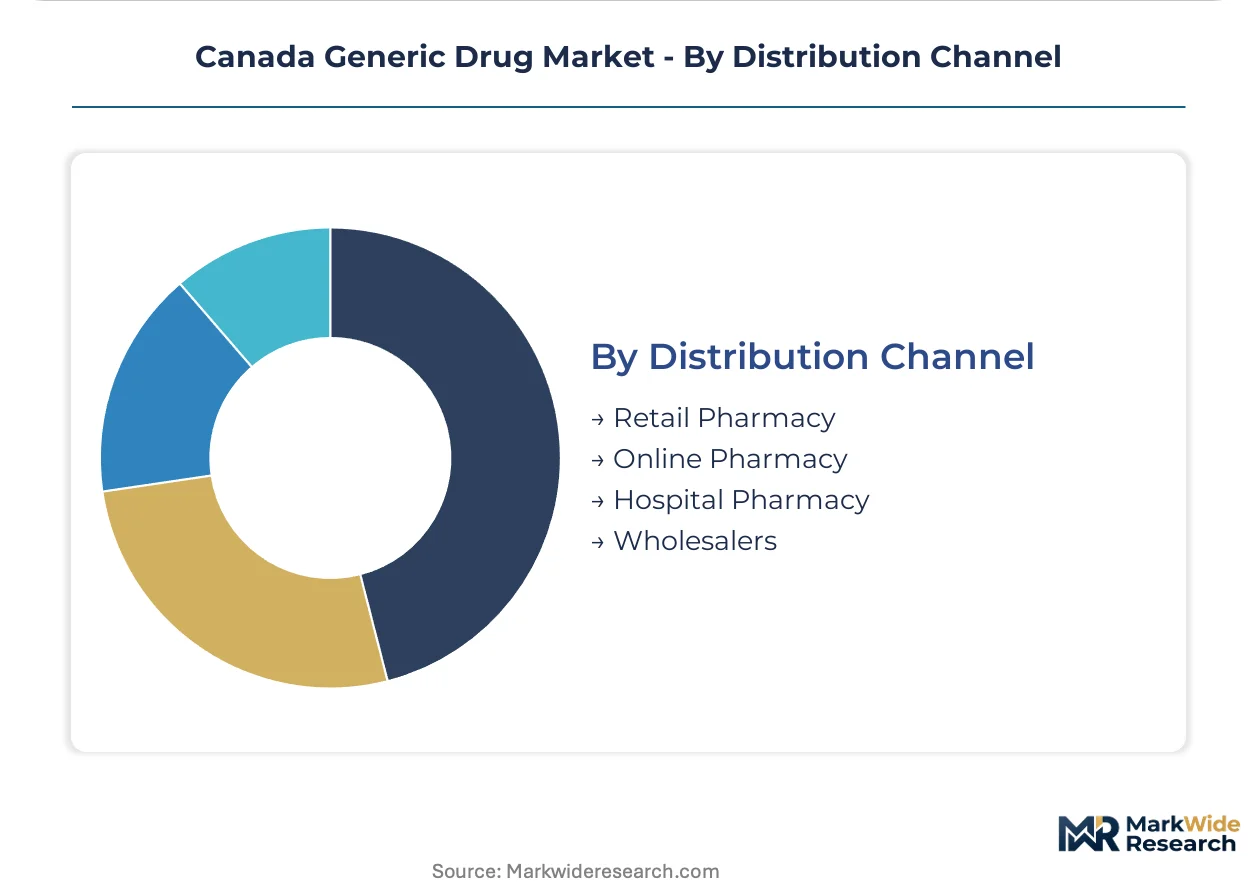
Distribution Channel:
Customer type dictates pricing transparency and inventory commitment requirements.
- Retail Pharmacy:Independent and chain pharmacies across Ontario and Quebec handle the majority of oral solid volume. Real-time inventory systems are becoming mandatory for provincial tender participation.
- Online Pharmacy:Digital dispensing platforms face Health Canada verification requirements for cross-provincial shipment. Regulatory clarity is still emerging for remote patient consultation protocols.
- Hospital Pharmacy:Consolidated procurement through Prairie province consortiums and Ontario hospital networks concentrates buying power. Injectable generics dominate this channel by value.
- Wholesalers:McKesson and other national distributors maintain inventory buffers that smooth manufacturer production scheduling. Wholesaler margins are compressing under direct-to-hospital contracting trends.
Retail pharmacy holds the largest share; hospital pharmacy is climbing the fastest as procurement consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's generic drug trade flows reflect a structural import dependence for active pharmaceutical ingredients, with finished-dose exports concentrated in Ontario and Quebec facilities serving North American markets. Provincial procurement policies create divergent demand profiles across sub-regions.
Ontario
Toronto and Mississauga host vertically integrated manufacturing clusters producing oral solids and injectables for domestic and export markets. Health Canada's accelerated review pathways prioritize submissions from Ontario-based facilities with advanced bioanalytical capabilities. The province's Drug Benefit Program drives volume procurement for chronic disease categories including diabetes and cardiovascular therapies.
Quebec
Montreal and Laval facilities specialize in sterile injectable and complex dosage forms with higher technical barriers to entry. The province's formulary expansion for biologics and biosimilars is reshaping procurement toward specialized manufacturing. Quebec-based producers leverage proximity to Ontario distribution networks while maintaining distinct provincial tendering relationships.
British Columbia
Vancouver and Lower Mainland distribution centers handle substantial import volumes from Asian API suppliers for West Coast markets. Provincial authorities are broadening chronic disease coverage, creating formulary access for cardiovascular and diabetes management portfolios. Health Canada bioequivalence tiering determines which manufacturers qualify for priority listing.
Alberta
Calgary and Edmonton hospital pharmacy consortiums are consolidating injectable purchasing through single-source agreements. Prairie province procurement concentration displaces fragmented multi-vendor arrangements. Manufacturers with dedicated sterile manufacturing lines and regional distribution infrastructure capture disproportionate volume allocation.
Atlantic Canada
Halifax serves as a distribution hub for regional hospital networks with limited local manufacturing presence. Provincial formularies rely on central Canadian supply chains with extended logistics lead times. Health Canada's regulatory harmonization efforts aim to reduce inter-provincial listing delays for generic entrants.
Canada Generic Drug Market Key Industry Players
Listed leaders compete with private specialists across bioequivalence certification tiers, creating a bifurcated structure where scale advantages meet regulatory agility. The vendor base clusters around three archetypes: vertically integrated domestic producers with captive API supply, multinational subsidiaries leveraging global R&D pipelines, and specialized injectable manufacturers with sterile fill-finish capabilities. Consolidation pressures favor M&A activity among mid-tier players seeking critical mass for provincial tender participation, while capacity expansion concentrates in complex generic formats with higher barriers to substitution.
Within the domestic integrated tier, Apotex Inc. anchors Ontario-based production with API-to-finished-dose operations. Teva Canada occupies a position among multinational subsidiaries drawing on respiratory and central nervous system portfolios. Novartis through its Sandoz Group exemplifies the complex generic specialist archetype with emphasis on injectable and biosimilar development pipelines.
| Leading Market Players |
|---|
| Novartis (Sandoz Group) |
| AstraZeneca |
| Apotex Inc. |
| Bayer |
| Pfizer |
| Teva Canada |
| Roche (generic division) |
| Merck |
| Pharmascience |
| Others |
Cost & Logistics Intelligence
API sourcing substitution from Indian and Chinese suppliers to domestic North American production simultaneously reshapes supply geography and pricing economics for Canadian finished-dose manufacturers. Health Canada's bioequivalence tiering system rewards higher certification grades with formulary priority, compressing margins for uncertified imports while creating premium capture opportunities for compliant domestic facilities.
Pricing Analysis
Hospital pharmacy buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Canadian generic market. Price differentiation rests on Health Canada bioequivalence certification grade and volume scale commitments to provincial tendering consortiums. Cost compression in oral solid categories is intensifying because Ontario's Drug Benefit Program weights procurement scores toward lowest-cost alternatives. Retail pharmacy chains exhibit the highest price sensitivity due to thin dispensing margins, while hospital networks with single-source injectable agreements show reduced elasticity.
Supply Chain Analysis
Shanghai and Mumbai port congestion periodically chokes active pharmaceutical ingredient flows into Canadian finished-dose facilities. API supply draws from India, China, and selected European sources for beta-lactam and specialized sterile actives. Finished-dose manufacturers face single-source vulnerability for penicillin-handling inputs due to limited domestic capacity. Distribution runs through McKesson and national wholesaler networks with regional distribution centers in Toronto, Montreal, and Vancouver.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada generic drug market sits in a cyclical recovery phase as provincial formulary expansion for chronic disease management drives procurement volume normalization following pandemic-era disruption.
For Market Incumbents: Fortify sterile manufacturing capabilities in Ontario and Quebec to capture Prairie hospital consortium volume as single-source agreements displace fragmented procurement. Secure backward integration into API supply for high-volume diabetes and cardiovascular actives to defend against Indian import price erosion. Prioritize Health Canada highest-tier bioequivalence certification investment to maintain Ontario Drug Benefit Program listing priority. For New Entrants and Emerging Players: Health Canada's accelerated review pathway for complex generics creates fast-track access for manufacturers with advanced analytical capabilities. Target British Columbia's expanding cardiovascular and diabetes coverage as the most penetrable provincial formulary opportunity. Pursue hospital pharmacy direct contracting in Alberta and Saskatchewan with dedicated sterile fill-finish capacity as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier injectable specialists lacking Prairie distribution infrastructure but holding Health Canada certification assets. Five-to-ten year viability hinges on pharmacare negotiation outcomes and federal formulary harmonization progress. Monitor provincial tendering consolidation announcements as the critical inflection signal for manufacturing utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Bioequivalence Certification Investment | Health Canada highest-tier status unlocks Ontario Drug Benefit Program priority listing and procurement advantages. |
| Sterile Manufacturing Scale-Up | Alberta and Saskatchewan hospital consortiums reward dedicated fill-finish capacity with single-source volume commitments. |
| API Supply Backward Integration | Captive sourcing of metformin and cardiovascular actives insulates margins from Indian customs delays. |
| Prairie Distribution Infrastructure | Regional warehousing in Calgary and Edmonton reduces logistics lead times for consolidated hospital procurement. |
| Complex Generic Pipeline Development | Inhalable and topical formats with limited substitutability command formulary preference and pricing power. |
Research Approach
Operator-level perspectives from formulary directors, hospital procurement managers, regulatory affairs leads, and pharmacy benefit administrators anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through Health Canada submission databases, provincial formulary listings, and Patented Medicine Prices Review Board guideline documents. Bottom-up facility capacity assessments and top-down provincial expenditure data were triangulated to establish market size parameters.
Sensitivity analysis tested forecast outputs against alternative bioequivalence certification adoption rates and pharmacare expansion scenarios across the projection horizon. Segmentation modeling incorporated drug type, active ingredient category, therapy area, and distribution channel dimensions with regional regulatory cluster overlays. CAGRs were derived from fitted growth curves applied to provincial drug plan expenditure trajectories and hospital procurement volume trends.
Decision-makers should treat outputs as directional under current Health Canada review timelines and provincial tendering consolidation pace; material deviation in federal pharmacare negotiations would warrant model refresh. Practitioners should keep alternative scenarios live as PMPRB pricing guideline enforcement and international API supply stability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
Rivaroxaban Market
Biopharmaceuticals
Protein Kinase B Inhibitors Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
North America Vaccines Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market