
 PCSK9 Inhibitors Market | 2026-2036
PCSK9 Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
PCSK9 Inhibitors Market Outlook
Good Manufacturing Practice certification for monoclonal antibody production is collapsing the field of contract manufacturers qualified to supply active pharmaceutical ingredients for PCSK9 programs. Amgen Inc. anchors the segment with vertically integrated biologics manufacturing in California and Puerto Rico. Regeneron Pharmaceuticals sustains its position through sustained R&D intensity in antibody engineering platforms. Sanofi competes via its commercial infrastructure and European manufacturing footprint.
PCSK9 inhibitors are recombinant monoclonal antibodies or small interfering RNA molecules that bind to proprotein convertase subtilisin/kexin type 9, preventing its degradation of hepatic LDL receptors and thereby reducing circulating LDL cholesterol by approximately 50-60%. These biologics serve patients with heterozygous familial hypercholesterolemia or established atherosclerotic cardiovascular disease who fail statin therapy. Alirocumab and Evolocumab dominate the product type landscape as the two approved agents with longest commercial track records. Subcutaneous injection remains the principal delivery mode, though oral administration candidates are advancing through clinical pipelines. Hospitals capture the largest end-user volume due to infusion protocols and prior authorization complexity.
FDA cardiovascular outcomes trial requirements, EMA biosimilar guidance, and national health technology assessment frameworks in Germany and France collectively determine market access timelines and reimbursement levels. The FDA's emphasis on hard cardiovascular endpoints extends development cycles but validates long-term clinical utility for payers. Stakeholders must monitor evolving LDL target guidelines from cardiology societies and corresponding payer formulary adjustments.
Market Dynamics
Injectable biologics manufacturing capacity constraints are reshaping competitive positioning in LDL-lowering therapeutics, as GMP-certified monoclonal antibody production lines consolidate among vertically integrated pharmaceutical manufacturers.
Growth Catalysts
- Familial Hypercholesterolemia Prevalence:Undiagnosed heterozygous FH populations in cardiology referral networks create sustained demand for specialist-administered biologics.
- EMA Biosimilar Pathways:Streamlined European regulatory frameworks for biosimilar monoclonal antibodies accelerate market entry timelines for follow-on manufacturers.
- Specialty Pharmacy Networks:United States hub-and-spoke distribution models resolve cold-chain logistics complexity for patient self-injection programs.
Market Restraints
- Reimbursement Compression:PBM formulary exclusion lists and prior authorization requirements create access friction in commercial insurance segments.
- Manufacturing Concentration:California and Puerto Rico biologics production clusters expose supply continuity risks to hurricane and seismic disruption events.
- Statin Therapy Dominance:Generic atorvastatin and rosuvastatin prescribing patterns limit eligible patient pools to refractory or intolerant subpopulations.
Strategic Opportunities
- Oral Small Molecule Candidates:Non-injectible PCSK9-targeting compounds in Phase II pipelines address patient preference barriers and expand primary care prescribing.
- German AMNOG Assessments:Early benefit evaluation frameworks reward cardiovascular outcomes data with premium reimbursement positioning.
- Combination Formulation Development:Co-formulated statin-PCSK9 inhibitor fixed-dose products streamline therapy initiation in hospital outpatient settings.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Mammalian cell culture scale-up expertise concentrates among legacy biologics manufacturers, constraining contract development capacity.
- CVOT Timeline Burden:FDA-mandated cardiovascular outcomes trial completion requirements extend development cycles and capital lock-up periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCSK9 Inhibitors Market |
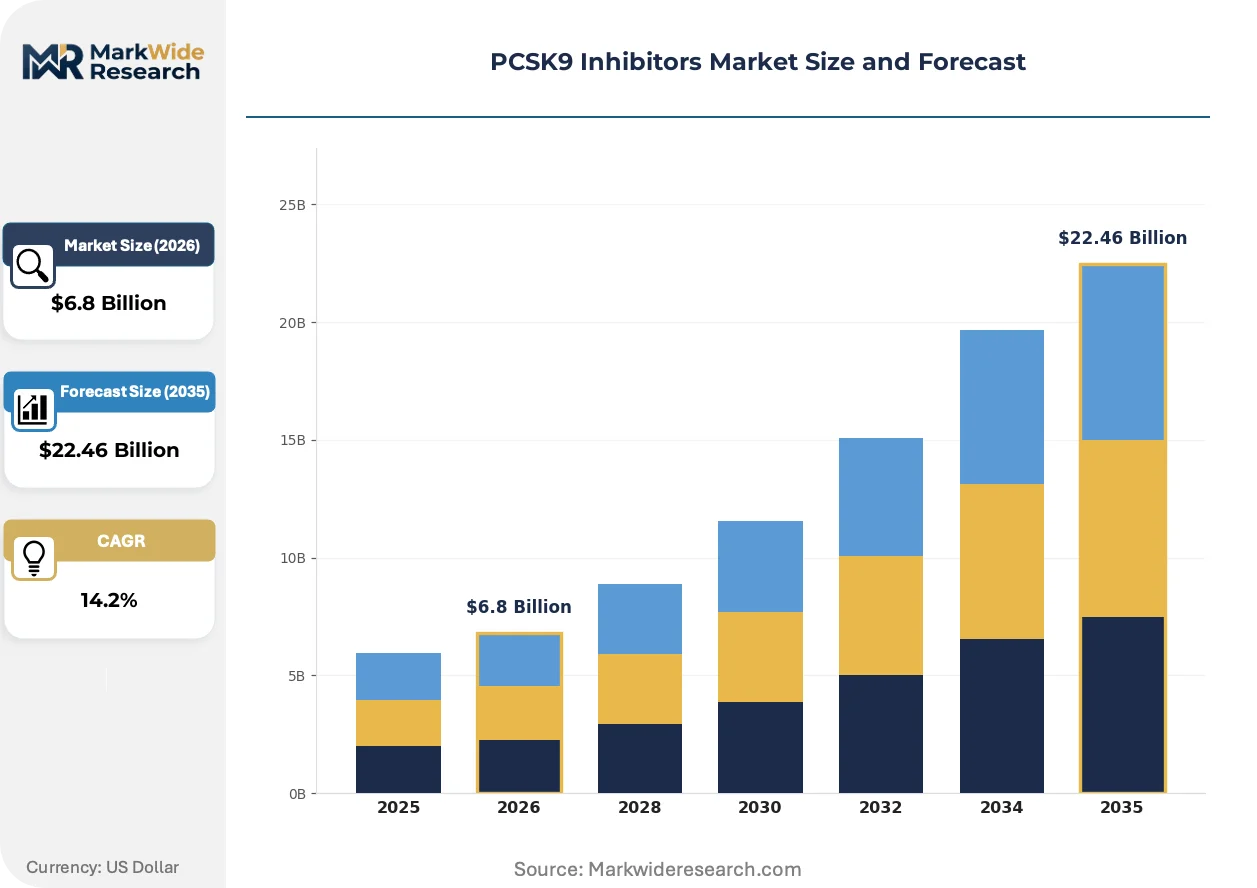
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alirocumab, Evolocumab, Bococizumab, Others Delivery Mode: Subcutaneous Injection, Intravenous Injection, Oral Administration, Others End User: Hospitals, Clinics, Homecare Settings, Ambulatory Surgical Centers Indication: Hypercholesterolemia, Cardiovascular Risk Reduction, Familial Hyperlipidemia, Others |
| Companies Covered | Amgen Inc., Regeneron Pharmaceuticals, Sanofi, Novartis AG, Innovent Biologics, Merck & Co., Inc., AstraZeneca, Shanghai Junshi Biosciences Co., Ltd, LIB Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCSK9 Inhibitors Market Strategic Shifts
Antibody engineering platforms and RNA interference modalities are bifurcating the therapeutic landscape, creating parallel development tracks with distinct manufacturing requirements and clinical positioning strategies.
Small interfering RNA molecules targeting PCSK9 hepatic expression are bifurcating the injectable biologics category into antibody-dependent and nucleic-acid-based mechanisms. Infusion centers and specialty pharmacies in the United States are adopting siRNA dosing schedules for patient convenience. This technology compression is enabling annualized dosing regimens that challenge quarterly antibody injection protocols.
EMA's evolving biosimilar guidance for monoclonal antibodies is compressing exclusivity periods for originator products in European markets. Manufacturers are accelerating head-to-head immunogenicity studies to preempt regulatory scrutiny. Cardiology departments in France and Germany are responding with therapeutic substitution protocols that prioritize cost-effectiveness thresholds.
Prior authorization automation through electronic health record integration is displacing manual specialty pharmacy intake processes. Hospital systems with embedded specialty pharmacies are capturing patient volumes previously routed to external mail-order channels. This channel consolidation is most visible in United States integrated delivery networks with captive payer relationships.
PCSK9 Inhibitors Market Segmentation
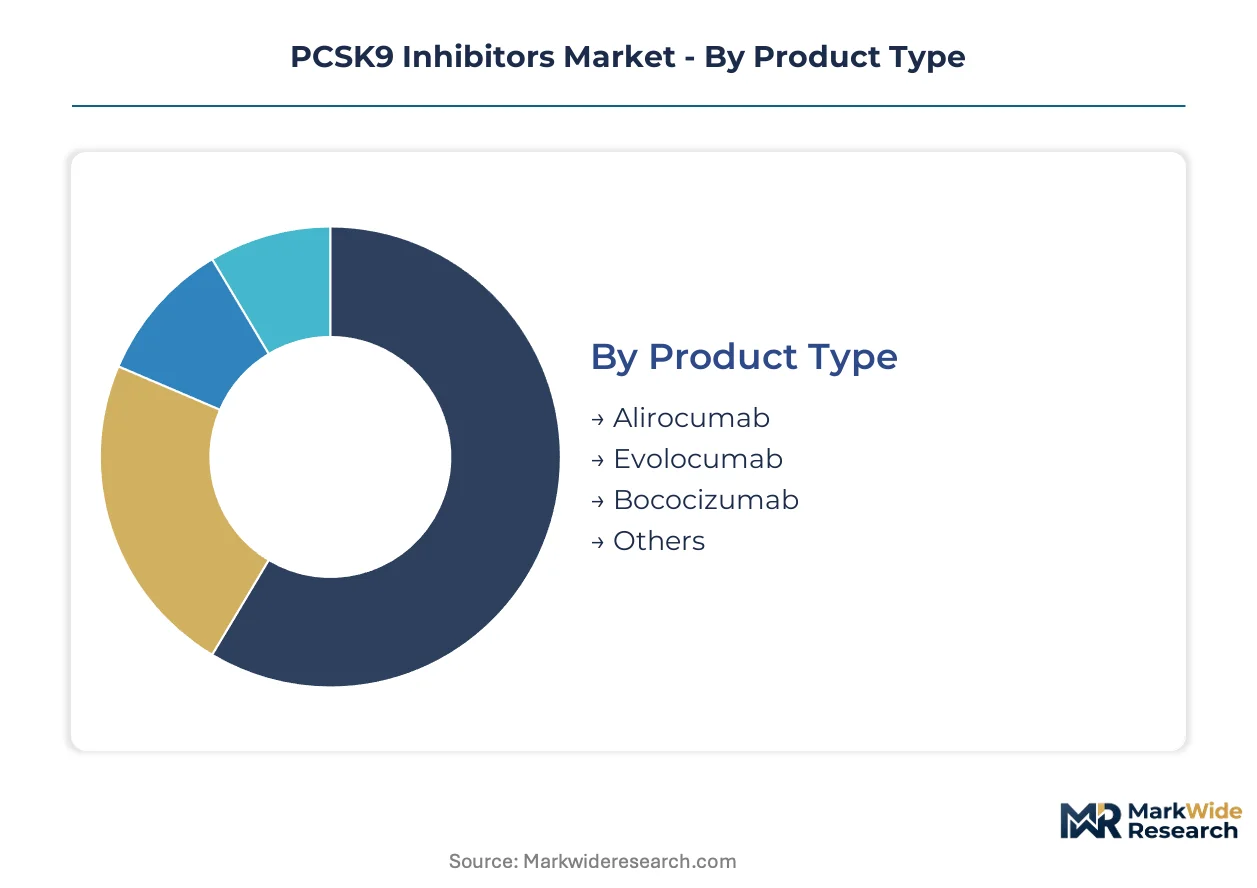
PCSK9 inhibitor segmentation reflects divergent regulatory pathways across delivery technologies and care settings. Each dimension carries distinct reimbursement codes, cold-chain requirements, and prescriber authorization protocols that shape commercial viability.
Product Type:
FDA approval chronology and EMA biosimilar guidance create tiered competitive moats among monoclonal antibody franchises.
- Alirocumab:Fully human IgG2 monoclonal antibody administered via prefilled pen or syringe. Cardiology departments in Germany and France prioritize this agent for heterozygous familial hypercholesterolemia patients failing maximally tolerated statins, driven by EMA's favorable early benefit assessment under AMNOG.
- Evolocumab:Human monoclonal antibody with monthly and biweekly dosing options. United States specialty pharmacy networks concentrate volume here due to established prior authorization automation and Amgen's integrated manufacturing in California and Puerto Rico.
- Bococizumab:Discontinued development candidate; immunogenicity concerns terminated Phase III programs.
- Others:Investigational small interfering RNA molecules and oral small molecule candidates targeting PCSK9 hepatic expression.
Established volume favors Alirocumab in European markets; emerging adoption favors siRNA candidates in United States infusion networks.
Delivery Mode:
Route of administration determines prescriber specialty, patient training burden, and reimbursement category within hospital outpatient versus pharmacy benefit structures.
- Subcutaneous Injection:Self-administered biweekly or monthly dosing via prefilled autoinjector devices. United States hub-and-spoke specialty pharmacy models resolve cold-chain logistics for home injection programs, with volume concentrating in cardiology referral networks managing refractory hyperlipidemia.
- Intravenous Injection:Hospital-administered infusion requiring clinical monitoring. Academic medical centers capture this volume for patients with complex comorbidities or prior authorization delays requiring inpatient initiation protocols.
- Oral Administration:Small molecule candidates in Phase II development targeting PCSK9 protein-protein interactions. Primary care prescribing expansion depends on FDA cardiovascular outcomes trial completion and formulary tier placement against generic statins.
- Others:Investigational depot formulations and implantable delivery systems in preclinical evaluation.
Injectable modalities dominate current revenue; oral candidates are climbing the fastest toward primary care access.
End User:
Site-of-care economics and specialty pharmacy integration determine patient capture rates across institutional settings.
- Hospitals:Capture the largest volume through outpatient infusion centers and embedded specialty pharmacies. Prior authorization complexity and requirement for specialist oversight concentrate refractory patient populations in academic medical centers with captive payer relationships.
- Clinics:Cardiology and lipid specialist practices with in-office injection capabilities. United States integrated delivery networks are consolidating this channel through acquisition of independent cardiology groups.
- Homecare Settings:Self-injection programs supported by specialty pharmacy nursing services. Patient preference for reduced clinic visits is expanding this segment fastest in United States commercial insurance populations.
- Ambulatory Surgical Centers:Minimal volume; occasional perioperative lipid management in high-risk cardiovascular surgery candidates.
Hospital systems retain the highest-value patients; homecare settings are gaining share fastest through convenience-driven channel shift.
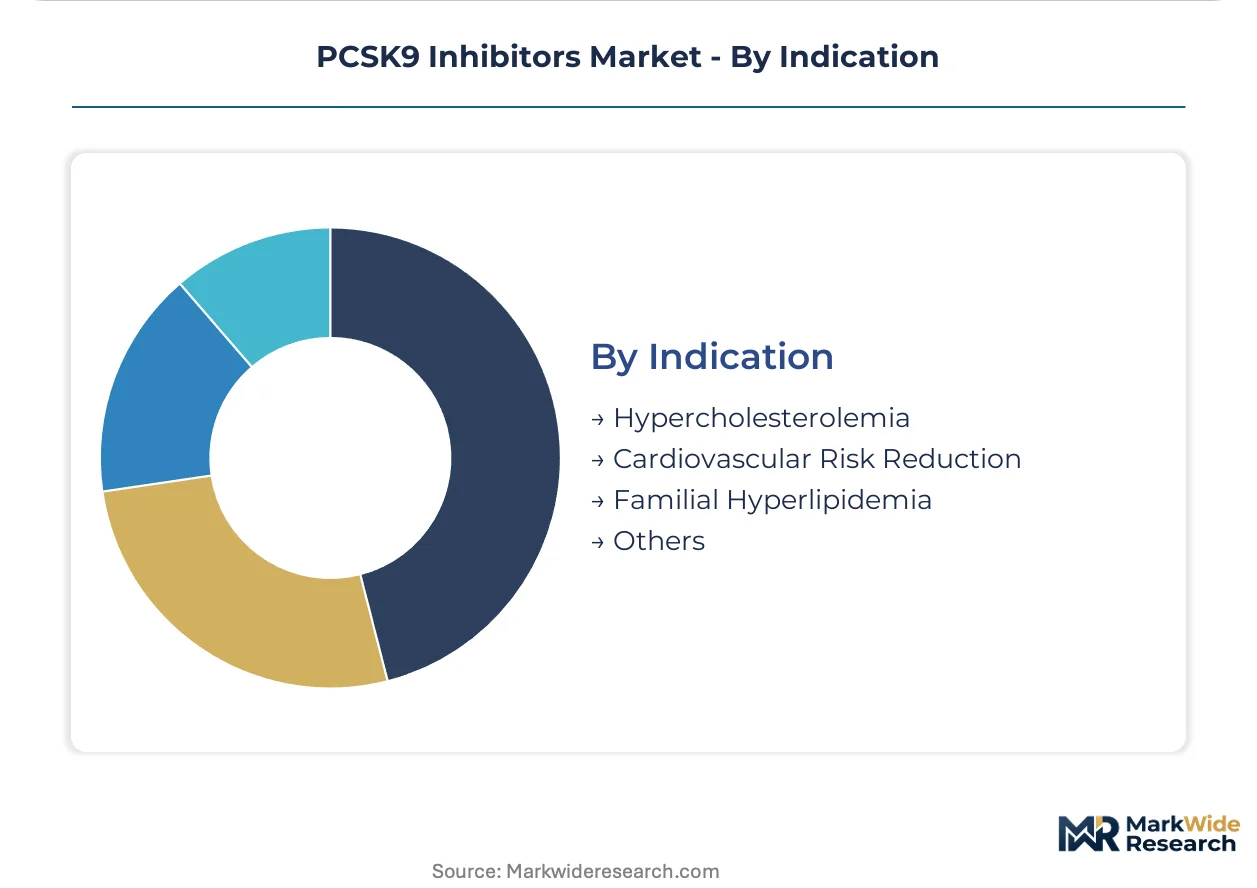
Indication:
Label expansion and cardiovascular outcomes trial results determine addressable patient pools and payer coverage policies.
- Hypercholesterolemia:Broad label for LDL reduction in adults with primary hypercholesterolemia. United States PBM formulary placement hinges on documented statin intolerance or failure to achieve LDL targets below 70 mg/dL in high-risk patients.
- Cardiovascular Risk Reduction:Secondary prevention indication requiring FDA-mandated cardiovascular outcomes trial evidence. German AMNOG assessments reward this endpoint with premium reimbursement positioning above standard lipid-lowering therapies.
- Familial Hyperlipidemia:Orphan indication for heterozygous and homozygous familial hypercholesterolemia. Undiagnosed populations in United States cardiology referral networks create sustained demand for genetic testing cascade protocols.
- Others:Investigational applications in statin-associated muscle symptoms and pediatric populations.
Established volume anchors hypercholesterolemia prescribing; cardiovascular risk reduction is expanding most quickly through outcomes-based contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cardiovascular outcomes trial mandates and EMA biosimilar pathways are reshaping commercial access timelines across major pharmaceutical markets. Payer negotiation intensity varies sharply by geography, with German AMNOG assessments and United States PBM formulary exclusions representing the most influential pricing mechanisms.
United States
Specialty pharmacy hub-and-spoke networks resolve cold-chain logistics for patient self-injection programs. Medicare Part D coverage determinations and commercial PBM prior authorization protocols create access friction for refractory hyperlipidemia patients. California and Puerto Rico biologics manufacturing clusters concentrate active pharmaceutical ingredient production for Amgen's vertically integrated supply chain.
Germany
AMNOG early benefit assessments reward cardiovascular outcomes data with premium reimbursement positioning above standard lipid-lowering therapies. Federal Joint Committee decisions determine whether PCSK9 inhibitors receive added benefit ratings versus generic statin comparators. Bavarian and North Rhine-Westphalian hospital systems anchor specialist prescribing through embedded cardiology referral networks.
France
HAS transparency committee evaluations determine SMR and ASMR ratings that translate into reimbursement rates for hospital-administered biologics. ANSM pharmacovigilance requirements shape post-market surveillance obligations for monoclonal antibody products. Paris and Lyon academic medical centers concentrate infusion center volume for complex familial hypercholesterolemia cases.
United Kingdom
NICE technology appraisals set cost-effectiveness thresholds that filter PCSK9 inhibitor access to highest-risk cardiovascular populations. NHS England specialized commissioning frameworks route prescribing through lipid clinics and inherited metabolic disease centers. London and Manchester hospital trusts dominate outpatient biologic administration through integrated care system consolidation.
China
NMPA priority review pathways accelerate approval timelines for cardiovascular outcomes trial-positive biologics with domestic manufacturing commitments. National reimbursement drug list negotiations determine hospital procurement pricing for imported monoclonal antibodies. Shanghai and Beijing biotech clusters anchor Innovent Biologics and Junshi Biosciences development programs targeting hepatic PCSK9 expression modulation.
PCSK9 Inhibitors Market Competitive Environment
Player mix skews toward vertically integrated biologics manufacturers with captive mammalian cell culture capacity and antibody engineering platforms. Market structure concentrates around three strategic archetypes: originator monoclonal antibody developers with cardiovascular outcomes trial data, emerging siRNA modality specialists with annualized dosing regimens, and biosimilar entrants leveraging EMA streamlined pathways. Dominant competitive moves include backward integration into bioprocess engineering talent pools and strategic partnerships with specialty pharmacy networks for patient onboarding automation.
Within the originator antibody tier, Amgen Inc. and Regeneron Pharmaceuticals occupy positions defined by FDA approval chronology and manufacturing footprint scale. Sanofi S.A. exemplifies the European commercial infrastructure archetype through its German and French market access capabilities. Innovent Biologics represents the China-based development specialist model targeting NMPA priority review pathways and domestic reimbursement list inclusion.
| Leading Market Players |
|---|
| Amgen Inc. |
| Regeneron Pharmaceuticals |
| Sanofi |
| Novartis AG |
| Innovent Biologics |
| Merck & Co., Inc. |
| AstraZeneca |
| Shanghai Junshi Biosciences Co., Ltd |
| LIB Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Single-use bioreactor utilization rates above 85% in California and Puerto Rico manufacturing clusters concentrate cost leverage among vertically integrated antibody producers, compressing price floors for contract manufacturing-dependent entrants while elevating margin capture for captive production networks.
Pricing Analysis
Certification level (FDA-grade GMP versus EMA biosimilar pathway) creates the primary spread between originator monoclonal antibodies and follow-on entrants. Pricing stratifies across innovator, biosimilar, and investigational tiers based on cardiovascular outcomes trial completion status and cold-chain reliability guarantees. Cost compression in the biosimilar tier is intensifying as European tender mechanisms consolidate purchasing volume. Hospital procurement committees exhibit the highest price sensitivity due to fixed DRG reimbursement ceilings, while specialty pharmacy networks show greater elasticity for patient convenience features.
Supply Chain Analysis
Chinese Hamster Ovary cell line access in South Korea and Singapore biologics parks constrains rapid capacity scaling for Western contract manufacturers. Active pharmaceutical ingredient production draws from Puerto Rico, California, and Irish mammalian cell culture hubs, with chromatography resin and single-use bioreactor bags as critical consumable dependencies. Single-source vulnerability concentrates in gamma-irradiated closure component supply from limited qualified vendors. Distribution runs through United States hub-and-spoke specialty pharmacy networks with cold-chain validation at every node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mammalian cell culture scale-up expertise concentrates among legacy biologics manufacturers with decades of platform refinement, creating a capability moat that constrains new entrant manufacturing options and elevates acquisition premiums for proven bioprocess engineering teams.
For Market Incumbents: Shield cardiovascular outcomes trial data assets through continued investment in long-term follow-up studies that reinforce formulary exclusion defenses against biosimilar entrants. Deepen backward integration into gamma-irradiated component supply to mitigate single-source closure risks. Prioritize specialty pharmacy partnership exclusivity in United States integrated delivery networks to lock patient onboarding workflows against channel competitors. For New Entrants and Emerging Players: Oral small molecule formulation gaps in primary care prescribing represent the most penetrable white-space target, as incumbent antibodies remain confined to specialist-administered settings. Homecare self-injection training services offer a service-layer entry point where established players under-invest in patient adherence support. Pursue German AMNOG early benefit assessment pathways to secure premium reimbursement positioning ahead of cardiovascular outcomes trial completion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors siRNA modality specialists with annualized dosing regimens that challenge quarterly antibody injection protocols. Long-term viability hinges on pipeline diversification beyond LDL-lowering into broader cardiometabolic indications. Watch FDA guidance evolution on cardiovascular outcomes trial requirements as the primary inflection signal for development cycle capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcomes Trial Advancement | FDA-mandated endpoint completion validates long-term clinical utility for payer formulary placement. |
| GMP Manufacturing Scale-Up | California and Puerto Rico biologics clusters anchor supply continuity for vertically integrated producers. |
| Specialty Pharmacy Partnership | Hub-and-spoke distribution networks resolve cold-chain logistics for patient self-injection programs. |
| Oral Formulation Development | Small molecule candidates address patient preference barriers and expand primary care prescribing access. |
| Biosimilar Regulatory Pathway | EMA streamlined frameworks accelerate market entry timelines for follow-on monoclonal antibody manufacturers. |
Study Parameters
The analysis maps monoclonal antibody, siRNA, and oral small molecule sub-sectors, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interview findings triangulate against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary database audits. Bottom-up patient volume modeling and top-down pharmaceutical spending allocation converge through iterative reconciliation across the analysis window.
Consistency checks against external cardiovascular outcomes trial timelines and biosimilar approval benchmarks validate projection outputs. The analytical framework segments by product type, delivery mode, end-user setting, and indication across the modeling period. CAGRs derive from patient population epidemiology, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporate AMNOG assessment outcomes and United States PBM formulary exclusion dynamics as segment-specific modifiers.
Underlying assumptions cover cardiovascular outcomes trial completion rates, biosimilar immunogenicity profiles, and specialty pharmacy network consolidation, with deviation risk concentrated in FDA guidance shifts and hurricane disruption to Puerto Rico manufacturing. Practitioners should keep alternative scenarios live as EMA biosimilar pathway evolution and German reimbursement negotiations progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Vaccine Adjuvants Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Chronic Phase Markers Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
Levofloxacin Cyclized Ester Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
US Influenza Vaccine Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Influenza Vaccine Market