
 Global Endocrinology Drugs Market | 2026-2036
Global Endocrinology Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endocrinology Drugs Market Foresight
European biologics manufacturing is hardening as a supply anchor for peptide-based therapies. Novo Nordisk dominates recombinant insulin and GLP-1 production through captive fermentation capacity in Denmark. Eli Lilly and Company extends its position in tirzepatide manufacturing through specialized fill-finish networks across North America. Merck anchors European distribution of biosimilar thyroid hormones through established wholesale partnerships.
Endocrinology drugs comprise synthetic and recombinant hormone preparations, peptide analogs, and steroid formulations that modulate metabolic, growth, and reproductive pathways through receptor-mediated cellular signaling. These agents restore deficient hormonal states, suppress hypersecretory conditions, or mimic endogenous physiological feedback loops in diabetes, thyroid dysfunction, and adrenal disorders. Insulin and GLP-1 segments command the largest revenue pools due to chronic administration requirements in type 2 diabetes. Thyroid hormones sustain mature margins through stable levothyroxine prescribing patterns. Injectable delivery modes capture premium pricing against oral alternatives in hospital and specialty clinic settings.
FDA, EMA, and WHO prequalification frameworks govern bioequivalence standards, cold-chain integrity, and immunogenicity surveillance for biologic hormone products. These agencies mandate comparability protocols that extend development timelines but protect incumbent manufacturers with validated manufacturing platforms. Stakeholders must monitor evolving pharmacovigilance requirements for GLP-1 class expansions into obesity and cardiovascular indications.
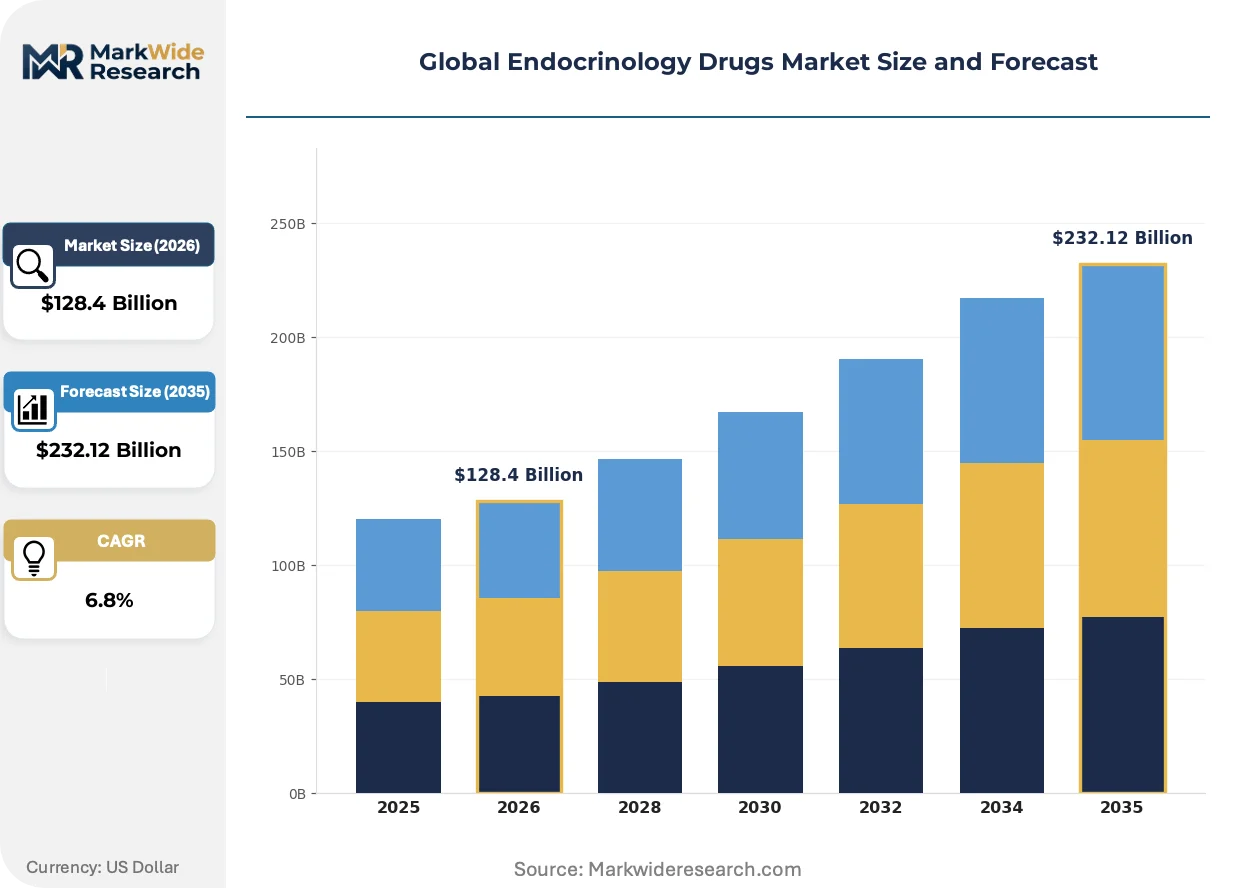
Market Dynamics
GLP-1 receptor agonist expansion into obesity management is compressing development timelines and reallocating manufacturing capacity away from traditional insulin products. This therapeutic pivot is forcing incumbent producers to revalidate fermentation infrastructure for higher-volume peptide output.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's breakthrough therapy designation for cardiometabolic indications compresses Phase III timelines for novel incretin mimetics. Hospital formularies in the United States are expanding prior authorization flexibility for these agents.
- Japan's Super-Aging Demographics:PMDA reimbursement reforms for diabetes management are elevating prescription volumes for long-acting insulin analogs. Specialist clinics in Tokyo and Osaka are consolidating procurement through group purchasing organizations.
- Continuous Glucose Monitoring Integration:Sensor-augmented pump therapy is creating closed-loop demand for rapid-acting insulin formulations. Endocrinology practices are restructuring care protocols around real-time glycemic data streams.
Market Restraints
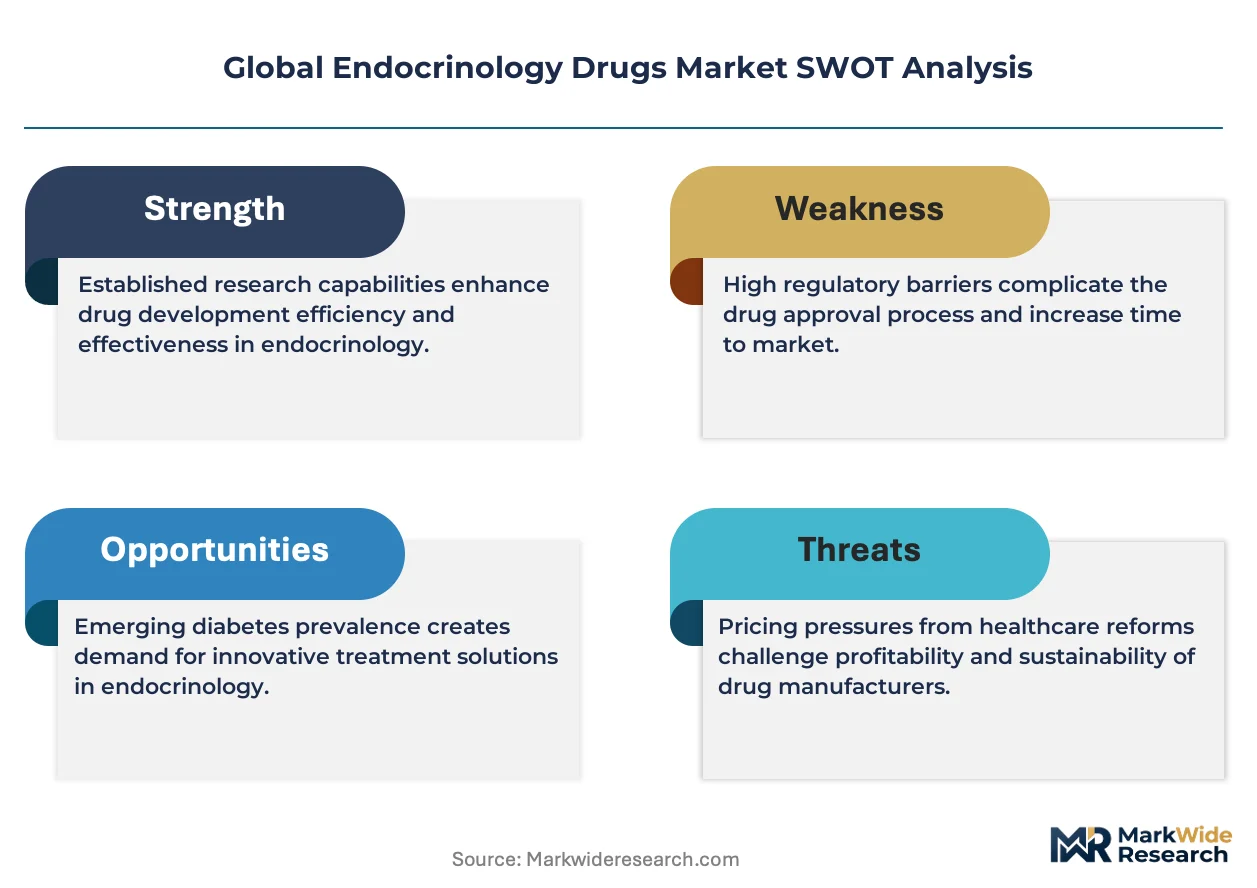
- Recombinant Peptide Input Concentration:Active pharmaceutical ingredient supply for GLP-1 analogs concentrates among Danish and North American fermentation specialists. Any disruption to microbial expression capacity propagates through finished-dose availability.
- Cold-Chain Infrastructure Gaps:Temperature-controlled distribution for biologic hormones remains underdeveloped across secondary cities in emerging markets. Biologics integrity failures erode physician confidence in non-originator products.
- Biosimilar Substitution Limits:EMA immunogenicity surveillance requirements create prescribing hesitation for follow-on insulin products. Endocrinologists in Germany and France maintain originator preference despite cost differentials.
Strategic Opportunities
- Oral GLP-1 Formulation Development:Non-injectible delivery technologies are opening adherence-sensitive patient segments previously lost to pharmacotherapy abandonment. Swallowable peptide analogs address needle aversion in pediatric and geriatric populations.
- India's Biosimilar Export Positioning:CDSCO manufacturing compliance upgrades are qualifying domestic insulin producers for WHO prequalification. Indian bulk peptide manufacturers are securing tenders across Sub-Saharan African public health programs.
- EMA Orphan Designation Expansion:Rare endocrine disorder indications are attracting development investment for ultra-orphan hormone replacement therapies. Pediatric growth hormone deficiency and congenital adrenal hyperplasia represent addressable niches.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Mammalian and microbial cell culture expertise for hormone production concentrates among legacy fermentation specialists. Compensation inflation for skilled bioprocess scientists is compressing R&D margins at mid-scale developers.
- Comparability Protocol Complexity:FDA and EMA analytical similarity requirements for biosimilar insulin extend development timelines by 18-24 months relative to small-molecule generics. Analytical method transfer between reference and test products consumes disproportionate regulatory resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endocrinology Drugs Market |
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $232.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Insulin, Glucagon-Like Peptide-1, Thyroid Hormones, Corticosteroids, Parathyroid Hormones Therapy Area: Diabetes Mellitus, Thyroid Disorders, Adrenal Disorders, Growth Hormone Deficiency, Calcium Metabolism Disorders End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Outpatient Care Centers, Research Institutes Delivery Mode: Injectables, Oral Tablets, Transdermal Patches, Nasal Sprays, Sublingual Tablets |
| Companies Covered | Merck, Novartis, Eli Lilly and Company, Amgen, Johnson & Johnson, Novo Nordisk, AbbVie, Pfizer, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endocrinology Drugs Market Shifts & Advancements
Peptide manufacturing automation and regulatory science convergence are compressing the gap between laboratory-scale hormone analogs and commercial bioproduction. These forces are redrawing competitive boundaries between originator and biosimilar portfolios.
Dual-acting incretin mimetics that co-activate GLP-1 and GIP receptors are overtaking single-mechanism agonists in prescriber preference hierarchies. Academic medical centers in the United States are prioritizing these agents for treatment-naïve type 2 diabetes patients. The technology is overtaking established GLP-1 monotherapy market positions by demonstrating superior glycemic and weight outcomes in head-to-head trials.
EMA's revised guideline on clinical investigation of medicinal products in the treatment of diabetes demands cardiovascular outcome data for novel glucose-lowering therapies. This regulatory posture elevates development costs for entrants lacking cardiology trial infrastructure. Small and mid-cap developers are responding through partnership structures with established cardiovascular outcome trial sponsors.
Specialty pharmacy channel consolidation is compressing wholesale margins for hormone distribution in the United States. Hospital systems are consolidating endocrinology drug procurement through centralized specialty pharmacy arrangements. This pattern is most visible in integrated delivery networks across Texas, Florida, and California where pharmacy benefit manager vertical integration has advanced furthest.
Global Endocrinology Drugs Market Segmentation
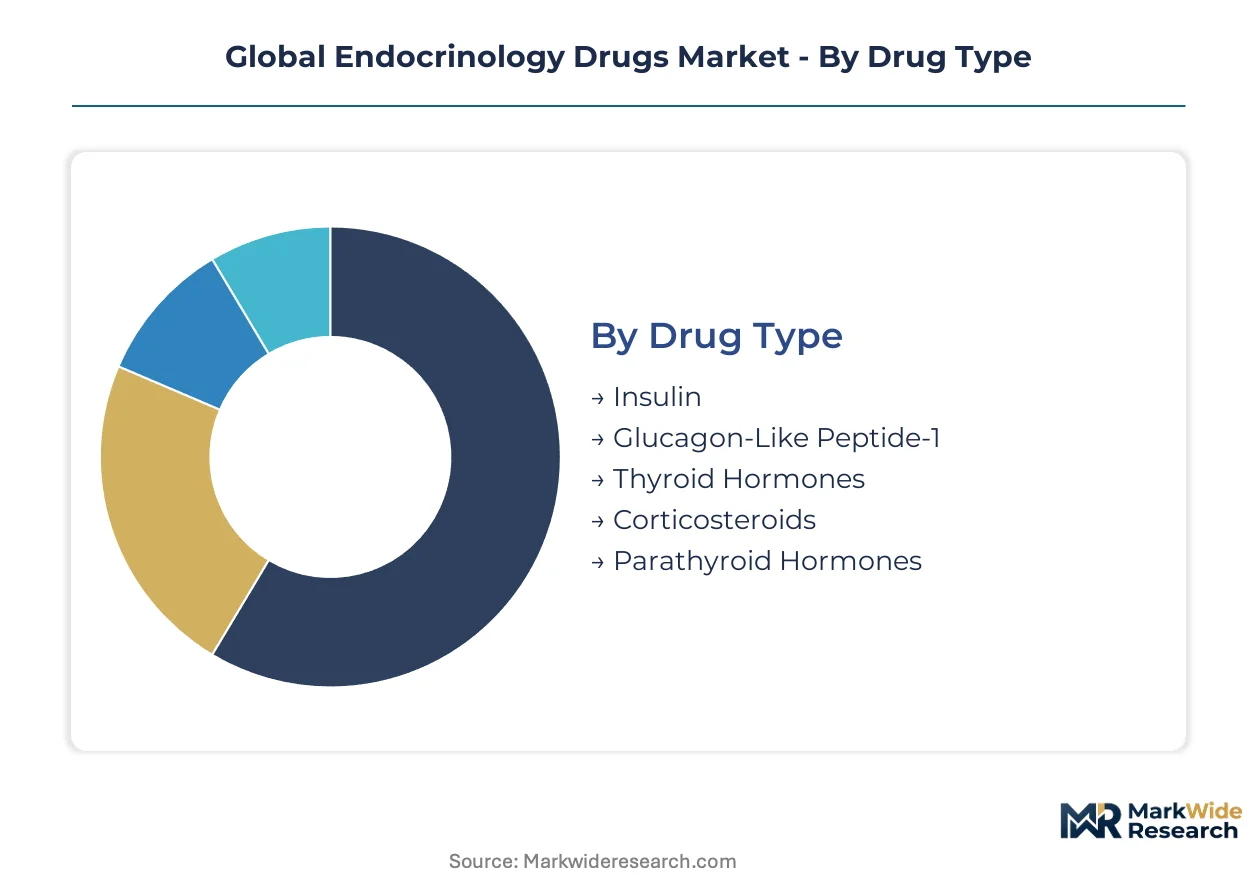
Endocrinology drug procurement decisions hinge on distinct clinical workflows across therapy areas, delivery preferences, and institutional settings. Understanding these segment boundaries illuminates where formulation investments yield differentiated access and where channel concentration creates margin pressure.
Drug Type:
Prescription volume and reimbursement tiering separate chronic maintenance therapies from acute rescue formulations, with fermentation capacity allocation determining supply security.
- Insulin:Recombinant human and analog formulations manufactured through microbial or yeast expression systems command the largest production footprint. Demand concentrates in hospital systems across the United States, Germany, and Japan where closed-loop pump integration is elevating rapid-acting analog preference.
- Glucagon-Like Peptide-1:Peptide agonists engineered for extended half-life through fatty acid acylation or albumin binding are displacing older incretin therapies. Specialist clinics in Denmark and North American academic medical centers are expanding prior authorization for obesity-qualified indications.
- Thyroid Hormones:Synthetic levothyroxine and liothyronine preparations maintain stable prescribing through primary care channels.
- Corticosteroids:Hydrocortisone and fludrocortisone replacement therapies address adrenal insufficiency with established generic availability.
- Parathyroid Hormones:Teriparatide and abaloparatide analogs serve osteoporosis refractory to bisphosphonate therapy.
Volume sits with Insulin; growth tilts toward Glucagon-Like Peptide-1.
Therapy Area:
Regulatory pathway complexity and trial infrastructure requirements segment development investment, with cardiometabolic outcome demands elevating barriers for novel entrants.
- Diabetes Mellitus:Glucose-lowering therapies span injectable peptides, insulin formulations, and oral secretagogues with distinct glycemic targets. Hospital formularies in the United States and Japan are consolidating procurement around agents demonstrating cardiovascular risk reduction.
- Thyroid Disorders:Hypothyroidism replacement and hyperthyroidism suppression therapies operate through mature prescribing patterns with limited pipeline innovation.
- Adrenal Disorders:Congenital adrenal hyperplasia and Addison's disease management relies on glucocorticoid and mineralocorticoid replacement.
- Growth Hormone Deficiency:Pediatric and adult somatropin therapy faces biosimilar penetration with EMA immunogenicity surveillance shaping prescriber confidence.
- Calcium Metabolism Disorders:Hypoparathyroidism and secondary hyperparathyroidism in chronic kidney disease drive calcimimetic and active vitamin D prescribing.
Revenue concentrates in Diabetes Mellitus; pipeline activity is climbing fastest in Growth Hormone Deficiency.
End User:
Procurement scale and clinical decision autonomy differentiate institutional buyers, with integrated delivery networks consolidating purchasing power across outpatient and inpatient settings.
- Hospitals:Inpatient glycemic management and emergency endocrine crisis intervention require rapid-acting insulin and IV hydrocortisone availability. United States health systems in Texas and California are centralizing endocrinology drug procurement through captive specialty pharmacies.
- Specialty Clinics:Outpatient hormone replacement and diabetes optimization concentrates prescriber expertise with direct distribution relationships. Tokyo and Osaka specialist networks are consolidating through group purchasing organizations under PMDA reimbursement reforms.
- Diagnostic Laboratories:Hormone assay calibration materials and reference standards support clinical testing workflows.
- Outpatient Care Centers:Community-based diabetes management extends access beyond academic referral centers.
- Research Institutes:Academic medical centers conduct investigator-initiated trials for novel incretin formulations.
Procurement volume aggregates at Hospitals; patient access expansion is gaining share fastest at Specialty Clinics.
Delivery Mode:
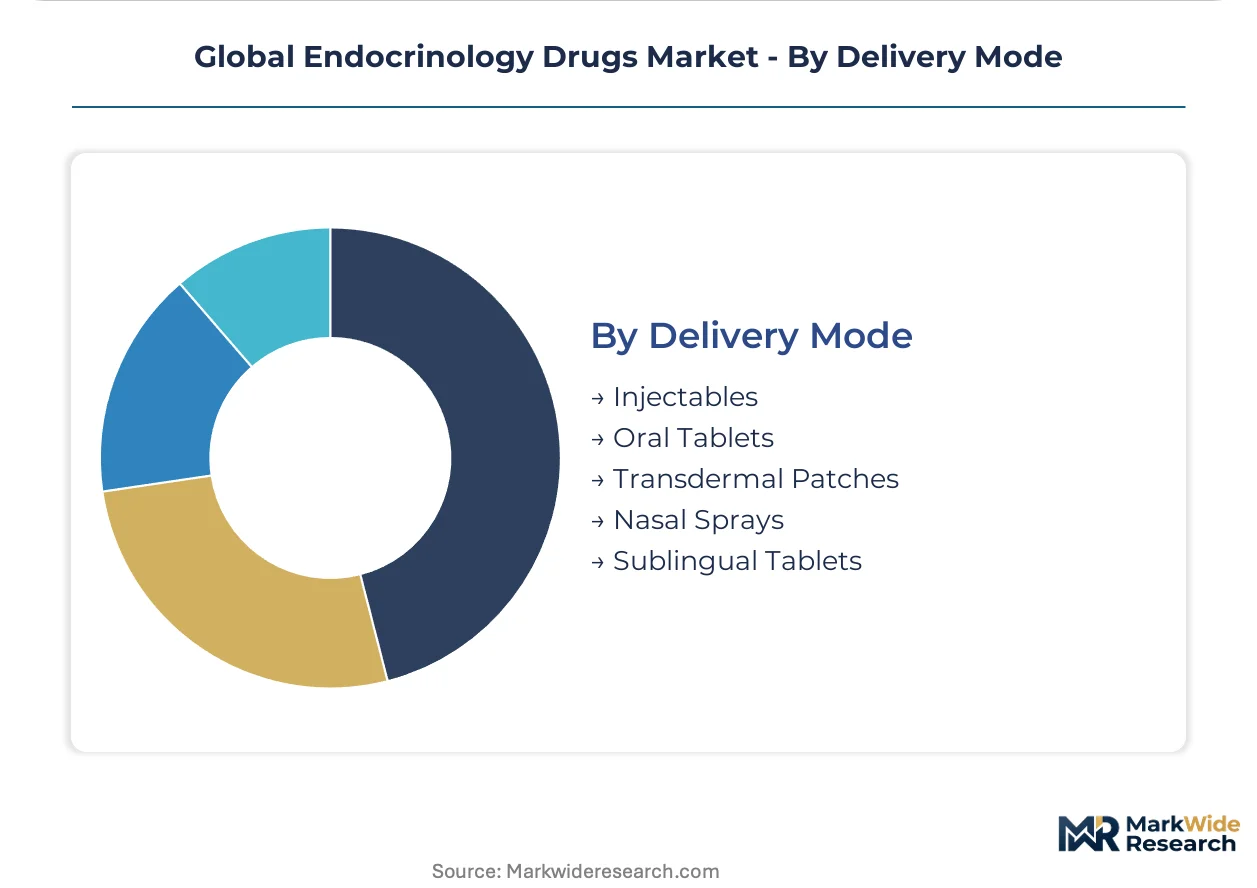
Patient adherence barriers and pharmacokinetic requirements drive formulation technology investment, with injectable platforms capturing premium positioning against oral alternatives.
- Injectables:Subcutaneous peptide delivery via prefilled pens and pump-compatible cartridges dominates GLP-1 and insulin administration. German and French endocrinologists maintain originator preference for biologic injectables despite EMA biosimilar approvals.
- Oral Tablets:Small-molecule hormone replacements and secretagogues offer convenience for thyroid and adrenal indications.
- Transdermal Patches:Estrogen and testosterone hormone replacement leverages skin permeation for steady-state delivery.
- Nasal Sprays:Desmopressin and calcitonin formulations address diabetes insipidus and osteoporosis through mucosal absorption.
- Sublingual Tablets:Rapid dissolution hormone preparations serve patients with swallowing difficulties or malabsorption.
Pricing power resides with Injectables; formulation innovation is expanding most quickly in Oral Tablets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide fermentation capacity in Denmark anchors European supply security for GLP-1 analogs. Hospital procurement networks in the United States, Germany, and Japan concentrate demand for biologic hormone therapies. Regulatory acceleration pathways in these markets compress development timelines while elevating manufacturing compliance burdens.
United States
Closed-loop insulin pump adoption and cardiometabolic outcome trials drive hospital formulary consolidation. FDA breakthrough therapy designations compress Phase III timelines for novel incretin mimetics. Texas and California health systems centralize endocrinology drug procurement through captive specialty pharmacies.
Germany
EMA immunogenicity surveillance requirements sustain originator preference among endocrinologists despite biosimilar availability. Group purchasing organizations in Bavaria and North Rhine-Westphalia negotiate insulin analog tenders. The country's national pharmaceutical regulator maintains stringent comparability protocols for follow-on biologics.
Japan
PMDA reimbursement reforms elevate prescription volumes for long-acting insulin analogs amid super-aging demographics. Tokyo and Osaka specialist clinics consolidate procurement through group purchasing organizations. METI industrial policy supports domestic fermentation capacity for peptide therapeutics.
India
CDSCO manufacturing compliance upgrades qualify domestic insulin producers for WHO prequalification. Maharashtra and Gujarat bulk peptide manufacturers secure tenders across Sub-Saharan African public health programs. The country's national pharmaceutical regulator enforces cold-chain integrity standards for biologic exports.
Denmark
Captive fermentation infrastructure for recombinant insulin and GLP-1 production anchors European biologics manufacturing. Copenhagen-region bioprocess engineering talent concentrates among legacy hormone specialists. EMA centralized procedures expedite market authorization for Danish-origin peptide therapies.
Global Endocrinology Drugs Market Competitive Landscape
Global majors compete with regional champions across fermentation capacity and regulatory science capabilities. Market structure tilts toward consolidated originators with validated manufacturing platforms, though biosimilar specialists fragment pricing in mature hormone segments. Three archetypes dominate: vertically integrated fermentation giants, mid-scale peptide engineering specialists, and emerging-market biosimilar exporters. Capacity expansion and strategic partnerships represent the dominant competitive moves as developers reallocate infrastructure from insulin toward incretin manufacturing.
Among North American and European incumbents, Novo Nordisk, Eli Lilly and Company, and Merck occupy positions spanning the originator-to-biosimilar spectrum. Novo Nordisk exemplifies the fermentation-anchored archetype through Danish-based captive production. Eli Lilly and Company represents the specialized fill-finish network model with North American manufacturing concentration. Merck sits within the European distribution-focused tier, leveraging wholesale partnerships for biosimilar thyroid hormones.
| Leading Market Players |
|---|
| Merck |
| Novartis |
| Eli Lilly and Company |
| Amgen |
| Johnson & Johnson |
| Novo Nordisk |
| AbbVie |
| Pfizer |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fermentation specialists in Denmark and North America anchor peptide API production, translating captive manufacturing discipline into originator pricing power for GLP-1 and insulin analogs. Their long-tenured supplier relationships and validated bioprocess platforms resist commoditization pressure from emerging-market biosimilar entrants.
Pricing Analysis
Warranty and cold-chain integrity guarantees bundle with originator biologics at premium tiers, while unbundled biosimilars compete on net acquisition cost alone. Three-tier pricing structure across originator, authorized generic, and unbranded biosimilar levels separates hospital formularies by immunogenicity surveillance confidence. Cost compression in the biosimilar tier intensifies because EMA comparability protocols extend development timelines without matching prescriber trust. Community health systems in emerging markets exhibit highest price sensitivity; academic medical centers in the United States and Germany demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Danish microbial expression capacity for GLP-1 fatty acid acylation and North American fill-finish networks for rapid-acting insulin. Active pharmaceutical ingredient supply draws from Denmark, the United States, and India, with fermentation media and chromatography resins resting on German and Japanese specialty chemical producers. Tariff exposure on Chinese-sourced recombinant protein raw materials propagates through finished-dose cost structures. Distribution runs through consolidated specialty pharmacy channels in the United States and wholesale partnerships in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GLP-1 receptor agonists are displacing legacy insulin portfolios across hospital formularies, compressing manufacturing allocation decisions and forcing incumbent producers to revalidate fermentation infrastructure for peptide therapeutics.
For Market Incumbents: Anticipate biosimilar substitution pressure in mature insulin segments by accelerating fill-finish capacity expansion in Denmark and North America. Deepen backward integration into recombinant peptide raw materials to defend margin position against Indian CDSCO-qualified exporters. Prioritize cardiovascular outcome trial infrastructure to meet EMA guideline requirements for novel incretin submissions. For New Entrants and Emerging Players: Pediatric endocrinology clinics in secondary Japanese cities represent an underserved buyer archetype with unmet demand for needle-averse oral GLP-1 formulations. Sub-Saharan African public health tenders for WHO-prequalified insulin offer the most penetrable procurement channel. Pursue CDSCO manufacturing compliance upgrades as the primary go-to-market angle to qualify for international bulk supply contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale peptide engineering specialists with validated microbial expression platforms in Maharashtra and Gujarat. Long-term viability hinges on fermentation capacity reallocation from insulin toward incretin manufacturing over the next decade. Watch FDA breakthrough therapy designation velocity for cardiometabolic indications as the inflection signal for GLP-1 class expansion sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Reallocation | Shifts microbial expression output from insulin toward GLP-1 peptide analogs at Danish facilities. |
| Cardiovascular Outcome Trial Infrastructure | Builds EMA-compliant evidence packages for novel incretin mimetics through academic medical center partnerships. |
| Oral Peptide Formulation Development | Addresses needle aversion in pediatric and geriatric populations through swallowable GLP-1 delivery. |
| Cold-Chain Distribution Expansion | Extends temperature-controlled logistics into secondary cities across emerging markets. |
| Biosimilar Immunogenicity Surveillance | Strengthens prescriber confidence in follow-on insulin through EMA-mandated post-market monitoring. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists underwrites the qualitative findings in this study. Primary interviews with formulary directors at integrated delivery networks in Texas and California combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up prescription volume modeling and top-down revenue triangulation anchored segmentation outputs.
Comparable-period anchoring to historical GLP-1 and insulin analog adoption curves structured the forecast window across the projection horizon. Segmentation dimensions modeled include therapy area, delivery mode, end-user institution type, and regional regulatory cluster. CAGRs derived from patient population growth, pricing trajectory assumptions, and manufacturing capacity expansion schedules. Forecast inputs incorporated PMDA reimbursement reform velocity and WHO prequalification pipeline status.
Revisions become necessary when FDA breakthrough therapy designation patterns shift, EMA immunogenicity surveillance requirements tighten, or major fermentation capacity disruptions materialize. Forecasts reflect documented assumptions about peptide manufacturing automation adoption and oral formulation technology maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Chemotherapy Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Somatostatin Analogs Market