
 Pegylated Protein Therapeutics Market | 2026-2036
Pegylated Protein Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Pegylated Protein Therapeutics Market Outlook
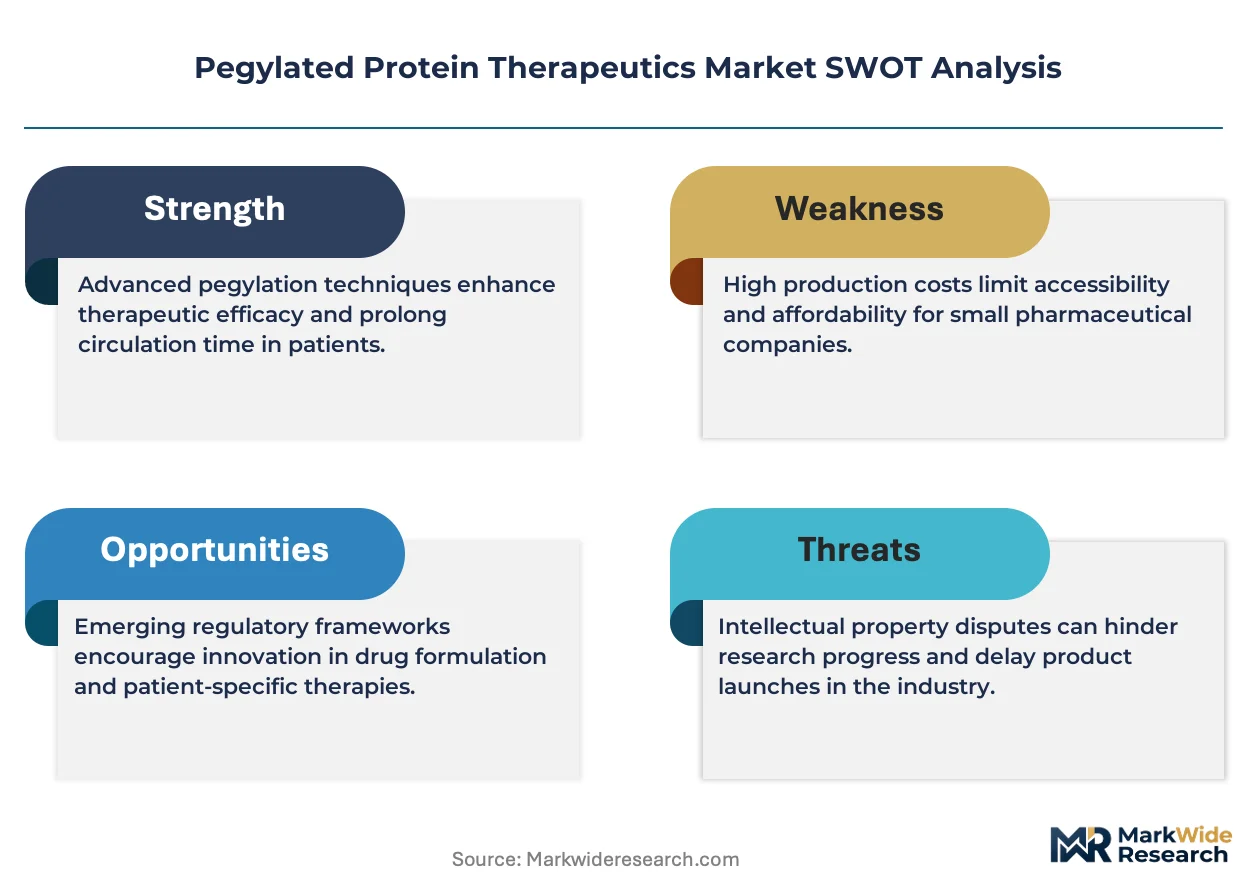
Long-acting biologic specifications is bifurcating the competitive landscape into originator-dominant premium tiers and emerging biosimilar-accessible segments. F. Hoffmann-La Roche Ltd. leverages its established oncology infrastructure to sustain dominance in intravenous pegylated monoclonal antibody distribution. Amgen Inc. anchors the enzyme therapy segment through manufacturing scale advantages in PEG-asparaginase production. Merck & Co., Inc. differentiates via R&D intensity focused on novel branched PEG linker architectures.
Pegylated protein therapeutics are biologic drugs in which polyethylene glycol (PEG) polymers are covalently attached to therapeutic proteins to extend circulating half-life, reduce immunogenicity, and improve solubility through steric stabilization of the protein core. This chemical modification enables less frequent dosing regimens, primarily serving chronic disease management in oncology, hematology, and autoimmune indications where patient adherence and therapeutic durability determine clinical outcomes. Monoclonal antibodies command the largest value pool due to high unit pricing and established reimbursement in hospital settings, while interferons face accelerating biosimilar erosion across European markets. Subcutaneous delivery modes are expanding fastest as prefilled autoinjector formats reduce infusion center dependency and shift administration toward home care environments.
FDA biosimilar guidance and EMA's Committee for Medicinal Products for Human Use (CHMP) scientific advice frameworks shape approval timelines, manufacturing quality standards, and interchangeability designations that determine market access depth for new entrants. REACH chemical registration requirements in Europe impose PEG raw material traceability obligations that filter supplier networks and elevate compliance costs for formulation developers. Stakeholders must monitor evolving FDA interchangeability standards and EMA biosimilar immunogenicity assessment protocols to anticipate competitive entry timing and adapt portfolio positioning accordingly.
Market Dynamics
Branched PEG linker architectures are compressing dosing intervals and forcing incumbent linear-PEG portfolios into defensive positioning against next-generation half-life extension claims.
Growth Catalysts
- FDA Biosimilar Pathway Refinements:Streamlined interchangeability designation protocols are accelerating developer confidence in pegylated interferon and enzyme follow-ons across United States infusion networks.
- EMA Parallel Scientific Advice Programs:Early-stage alignment on immunogenicity assessment frameworks is reducing regulatory risk for novel PEGylation platforms targeting oncology indications.
- Subcutaneous Autoinjector Formats:Prefilled delivery systems are shifting administration from hospital infusion centers to home care environments, expanding addressable patient populations in Germany's centralized pharmacy networks.
Market Restraints
- PEG Raw Material Traceability Costs:REACH chemical registration obligations in Europe are filtering supplier networks and elevating compliance burdens for formulation developers sourcing polyethylene glycol precursors.
- Immunogenicity Assessment Complexity:EMA CHMP protocols for anti-PEG antibody detection are extending preclinical timelines and inflating development costs for novel conjugates.
- Biosimilar Erosion in Interferons:Accelerating substitution of pegylated interferon alfa products across European markets is compressing originator pricing power and deterring R&D reinvestment.
Strategic Opportunities
- Home Care Distribution Channels:Direct-to-patient delivery models for subcutaneous pegylated biologics are capturing margin previously allocated to hospital outpatient departments in United States metropolitan markets.
- Orphan Enzyme Indications:Ultra-rare disease applications for PEG-asparaginase variants are accessing priority review vouchers and extended exclusivity provisions under FDA accelerated approval pathways.
- Convergence with Continuous Manufacturing:Integration of PEGylation chemistry with single-use bioreactor platforms is enabling real-time quality control and reducing batch-to-batch variability for contract development organizations.
Industry Challenges
- Analytical Methodology Standardization:Heterogeneity in PEG chain length distribution assays is creating regulatory submission delays as FDA and EMA diverge on acceptable characterization thresholds.
- Specialized Conjugation Chemistry Talent:Scarce expertise in site-specific PEGylation and linker design is constraining scale-up capabilities at mid-size biologics manufacturers competing for experienced protein engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pegylated Protein Therapeutics Market |
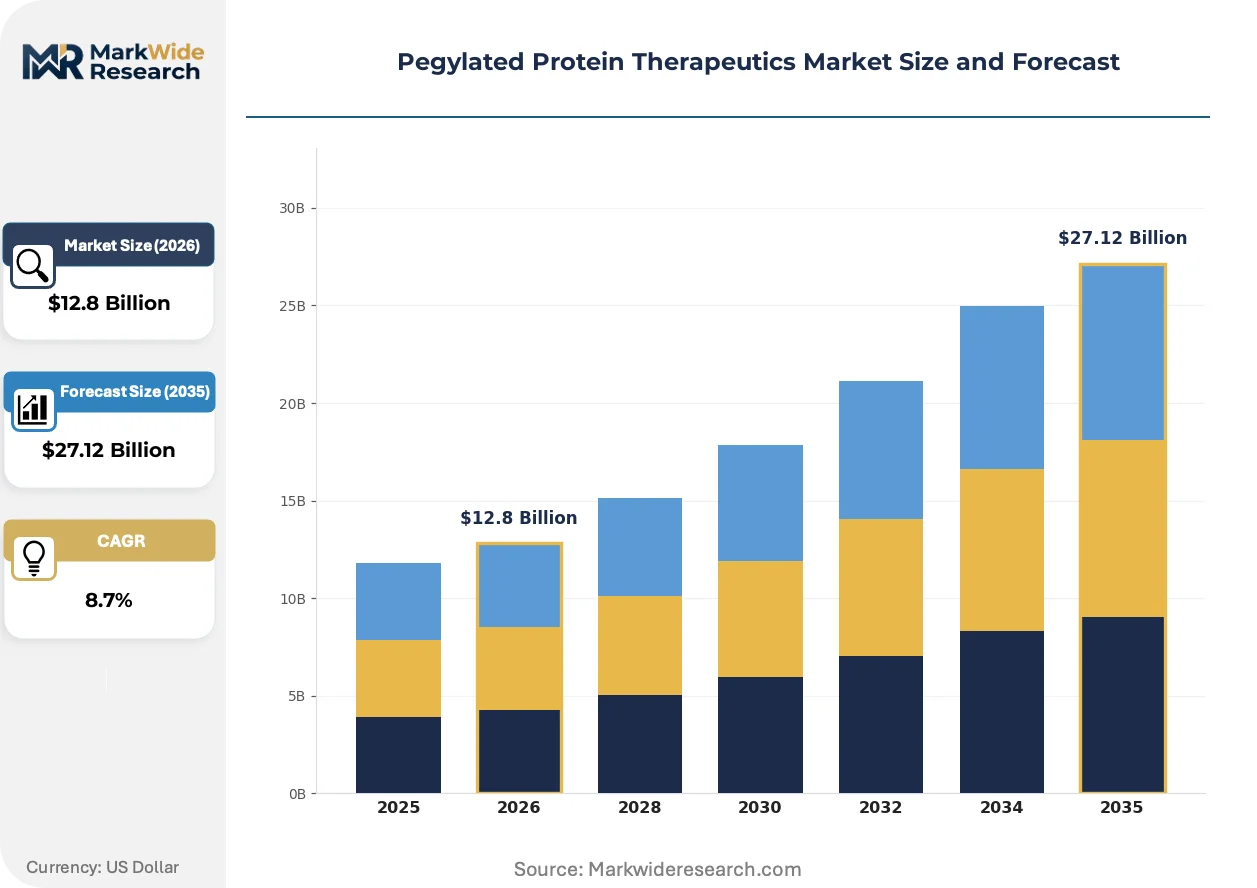
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Enzymes, Interferons, Vaccines Therapy Area: Oncology, Hematology, Infectious Diseases, Autoimmune Disorders Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Intra-articular End User: Hospitals, Clinics, Home Care, Research Laboratories |
| Companies Covered | Amgen Inc., Merck & Co., Inc., AstraZeneca PLC, Biogen Inc., UCB S.A., Pfizer Inc., F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific, Inc., Leadiant Biosciences S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pegylated Protein Therapeutics Market Strategic Shifts
Next-generation half-life extension technologies are fragmenting the competitive landscape as developers abandon conventional linear PEGylation for site-specific conjugation and alternative polymer architectures.
Site-specific PEGylation chemistry is decomposing the traditional trade-off between conjugation efficiency and protein activity retention. Oncology biologics manufacturers are adopting enzymatic ligation and click-chemistry approaches to achieve defined stoichiometry. This precision is decomposing batch rejection rates and enabling abbreviated stability testing protocols that compress development timelines.
EMA's evolving biosimilar immunogenicity assessment protocols are tightening requirements for anti-PEG antibody monitoring in post-market surveillance. Manufacturers must now submit comprehensive immunogenicity risk management plans as condition of CHMP approval. European pegylated monoclonal antibody developers are responding by front-loading comparative immunogenicity studies to preempt regulatory queries.
Hospital procurement consortia are consolidating purchasing power for intravenous pegylated biologics through multi-year tender agreements with inflation-linked pricing mechanisms. Germany's university hospital networks are displacing fragmented pharmacy-level negotiations with centralized framework contracts. This concentration is most visible in oncology infusion centers where formulary access now hinges on total cost-of-care guarantees rather than unit pricing alone.
Pegylated Protein Therapeutics Market Segmentation
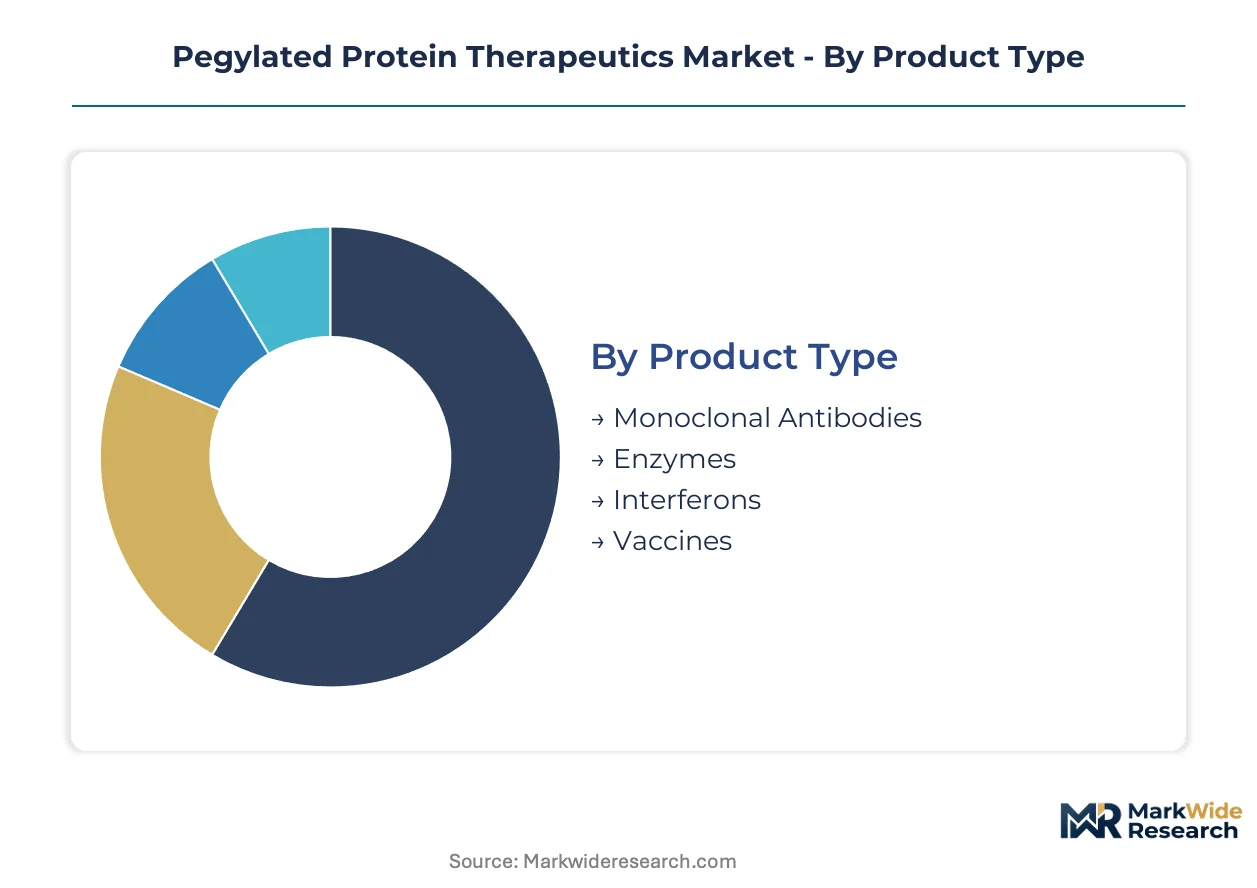
PEGylation chemistry creates distinct formulation requirements across therapeutic classes, channel economics, and administration settings. Understanding segment boundaries clarifies where manufacturing scale advantages concentrate versus where novel conjugation platforms can command premium positioning.
Product Type:
Monoclonal antibodies flow predominantly through hospital oncology infusion centers with centralized procurement, while enzymes and interferons distribute through specialty pharmacy networks with distinct margin structures.
- Monoclonal Antibodies:Large-molecule biologics with branched PEG architectures enabling extended half-life for checkpoint inhibitors and targeted cytotoxic agents. Demand clusters in United States academic medical centers where total cost-of-care contracting favors long-acting formulations reducing infusion frequency.
- Enzymes:PEG-asparaginase and related constructs for hematologic malignancies requiring precise activity retention through site-specific conjugation. Germany's hospital pharmacy networks anchor procurement volume for pediatric acute lymphoblastic leukemia protocols.
- Interferons:Pegylated alfa constructs for hepatitis and multiple sclerosis facing accelerating biosimilar substitution across European tender frameworks.
- Vaccines:Adjuvant and carrier applications in prophylactic immunization with emerging preclinical pipelines targeting sustained antigen presentation.
Monoclonal antibodies dominate installed base. Enzymes are where expansion concentrates.
Therapy Area:
Cost tier stratification separates curative oncology applications with premium pricing from chronic autoimmune management where dosing convenience drives formulary placement.
- Oncology:Solid tumor and hematologic indications commanding highest unit economics through intravenous administration in certified infusion centers. FDA accelerated approval pathways for PEGylated antibody-drug conjugates concentrate developer investment in this segment.
- Hematology:Enzyme replacement and clotting factor applications with orphan drug exclusivity provisions. United States specialty pharmacy distribution captures margin through patient hub services and adherence monitoring.
- Infectious Diseases:Pegylated interferon for hepatitis C faces declining volume as direct-acting antivirals displace combination regimens across European markets.
- Autoimmune Disorders:Multiple sclerosis and rheumatoid arthritis applications where subcutaneous autoinjector formats shift administration toward home care environments in Germany and United States metropolitan markets.
Oncology commands highest revenue per patient. Autoimmune disorders are climbing the fastest as home administration expands addressable populations.
Delivery Mode:
Volume concentration in intravenous formats is displacing toward subcutaneous as prefilled delivery systems reduce healthcare facility dependency.
- Intravenous:Hospital-based administration for high-dose monoclonal antibodies with established reimbursement codes in United States outpatient prospective payment systems. Germany's university hospital networks consolidate purchasing through multi-year framework agreements.
- Subcutaneous:Autoinjector and prefilled syringe formats enabling self-administration for interferons and emerging antibody portfolios. EMA CHMP guidelines on immunogenicity assessment for subcutaneous PEGylated biologics shape approval timelines.
- Intramuscular:Vaccine applications with depot-release kinetics requiring distinct PEG chain length optimization for lymphatic drainage profiles.
- Intra-articular:Localized delivery for inflammatory joint conditions with limited current commercial presence but emerging preclinical interest in sustained-release PEG-hyaluronic acid constructs.
Intravenous maintains volume leadership. Subcutaneous is gaining share fastest through patient preference and total cost reduction.
End User:
Customer type fragmentation creates divergent purchasing logic between institutional procurement committees and individual patient access programs.
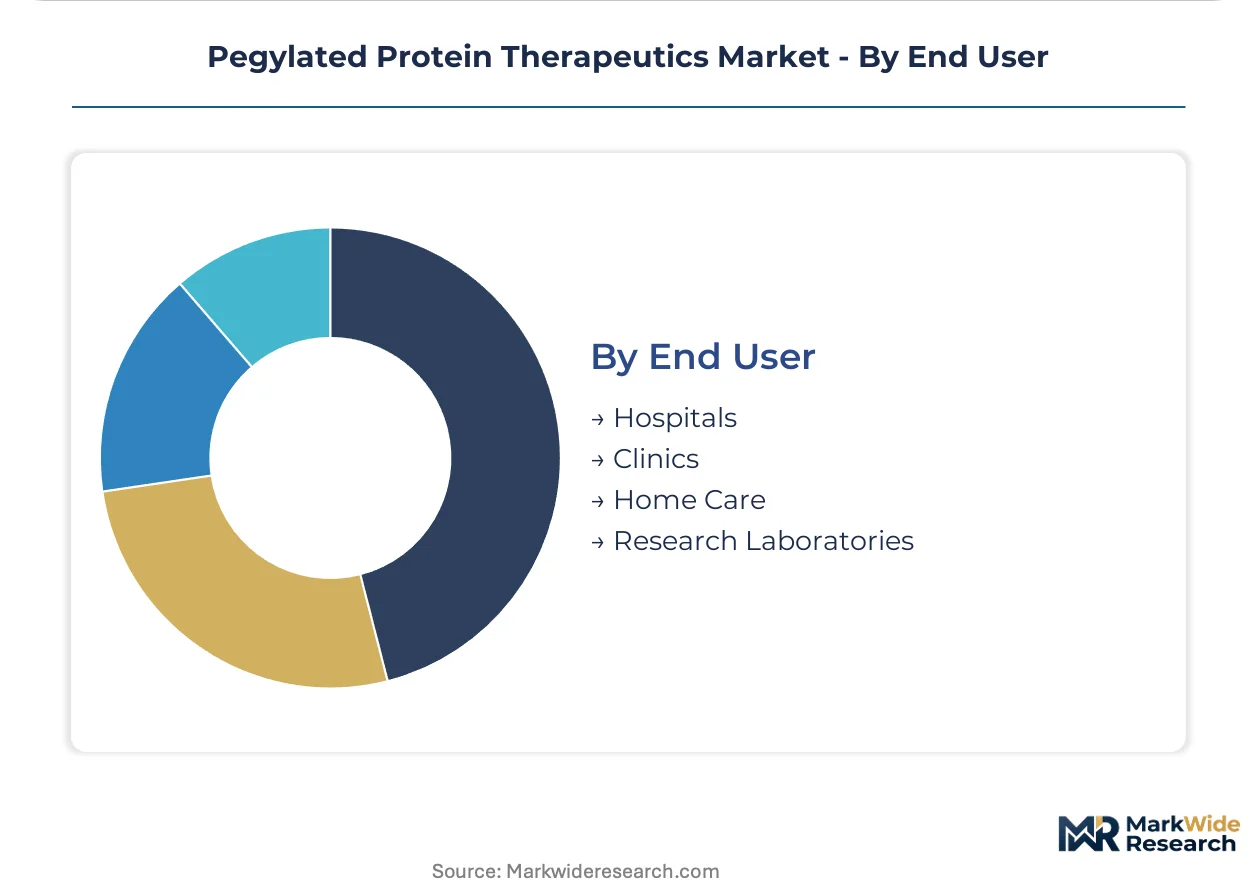
- Hospitals:Integrated delivery networks in United States and centralized pharmacy committees in Germany driving formulary decisions through total cost-of-care analytics rather than unit pricing alone.
- Clinics:Community oncology practices with limited cold-chain infrastructure favoring lyophilized PEGylated formulations with extended room-temperature stability.
- Home Care:Direct-to-patient distribution channels capturing margin previously allocated to hospital outpatient departments, particularly for subcutaneous interferon and emerging antibody portfolios.
- Research Laboratories:Preclinical and clinical trial material supply with distinct quality specifications and regulatory documentation requirements.
Hospitals anchor current revenue. Home care is where expansion concentrates as autoinjector adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of PEGylated biologics concentrate in developed markets with established infusion infrastructure, while import dependency shapes emerging market access patterns. Germany and the United States anchor outbound shipment volumes for finished formulations. Regulatory divergence between FDA and EMA pathways creates distinct commercialization timelines across Atlantic markets.
United States
Oncology infusion centers in metropolitan corridors drive demand for intravenous pegylated monoclonal antibodies. FDA biosimilar interchangeability designations accelerate substitution pathways for pegylated interferon products. Boston and San Francisco biotech clusters host contract development organizations specializing in site-specific PEGylation chemistry.
Germany
Centralized hospital pharmacy networks consolidate procurement for PEG-asparaginase and enzyme replacement therapies. REACH chemical registration requirements impose traceability obligations on PEG raw material suppliers. Bavaria's university hospital systems anchor multi-year tender agreements with inflation-linked pricing mechanisms.
Japan
PMDA accelerated approval pathways attract orphan enzyme indication filings for ultra-rare hematologic disorders. Subcutaneous autoinjector adoption expands patient self-administration beyond traditional infusion center dependency. Kansai region manufacturers supply prefilled delivery systems to domestic and Asia-Pacific markets.
Switzerland
Swissmedic regulatory frameworks support early-stage PEGylation platform development through parallel scientific advice with EMA. Basel-area biologics manufacturing infrastructure exports active pharmaceutical ingredients to European formulation sites. Precision chemistry capabilities concentrate around legacy pharmaceutical and specialty chemical competencies.
India
CDSCO manufacturing licensing requirements filter contract development organization entry for PEGylated biologic exports. Biosimilar development programs target pegylated interferon alfa products for hepatitis and multiple sclerosis indications. Maharashtra and Gujarat clusters house bulk PEG supplier networks serving formulation developers.
Pegylated Protein Therapeutics Market Competitive Environment
Concentration sits with diversified biopharmaceutical conglomerates controlling oncology infrastructure and enzyme manufacturing scale. Three to five originator-dominant entities anchor premium-tier positioning through established hospital formulary relationships. Mid-size specialists compete on novel linker architectures and site-specific conjugation platforms. Competitive moves center on manufacturing capacity expansion for single-use bioreactor integration and strategic partnerships for autoinjector distribution networks.
Among diversified biopharmaceutical conglomerates, Amgen Inc., Merck & Co., Inc., and F. Hoffmann-La Roche Ltd. occupy positions reflecting distinct archetype specializations. Amgen Inc. exemplifies manufacturing scale advantages in enzyme therapy segments. Merck & Co., Inc. represents R&D intensity focused on branched PEG linker innovation. F. Hoffmann-La Roche Ltd. anchors intravenous monoclonal antibody distribution through established oncology infrastructure. These entities collectively illustrate how competitive positioning fragments across therapeutic class expertise rather than converging on uniform platform strategies.
| Leading Market Players |
|---|
| Amgen Inc. |
| Merck & Co., Inc. |
| AstraZeneca PLC |
| Biogen Inc. |
| UCB S.A. |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific, Inc. |
| Leadiant Biosciences S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Single-use bioreactor utilization rates above 80% at Basel-area manufacturing sites compress unit production costs for PEGylated monoclonal antibodies, concentrating supply-side pricing power among originators with validated continuous manufacturing platforms and forcing mid-tier developers toward contract manufacturing partnerships that elevate their effective cost floors.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through multi-year framework agreements with inflation-linked escalators rather than spot purchasing. Three-tier pricing structure across originator premium, authorized biosimilar, and emerging follow-on biologic levels stratifies the market, with FDA interchangeability designation serving as the critical certification tier separating premium from accessible segments. Cost compression in interferon portfolios intensifies as European tender frameworks accelerate substitution, while oncology monoclonal antibodies retain pricing resilience through total cost-of-care contracting. Community oncology practices exhibit highest price sensitivity due to limited cold-chain infrastructure and formulary constraints.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for PEG raw material shipments destined to German formulation sites. Manufacturing concentration clusters in Switzerland for active pharmaceutical ingredient production, Germany for finished dose formulation, and India for bulk PEG chemical supply. PEG precursor sourcing draws from petroleum derivatives and specialized epoxide intermediates with limited qualified supplier pools. Single-source vulnerability permeates the site-specific conjugation enzyme supply tier. Distribution runs through hospital pharmacy networks for intravenous products and specialty pharmacy channels for subcutaneous autoinjector formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among United States integrated delivery networks and Germany's university hospital procurement consortia is shifting buyer power toward centralized formulary committees capable of extracting total cost-of-care guarantees rather than accepting list pricing.
For Market Incumbents: Compound manufacturing scale advantages in enzyme therapy segments through backward integration into PEG raw material purification capabilities. Lock in multi-year exclusive supply agreements with Bavaria's university hospital networks before biosimilar entry accelerates. Site-specific conjugation chemistry expertise represents the critical defensive moat against emerging platform competitors. For New Entrants and Emerging Players: Home care distribution infrastructure gaps expose white-space opportunity for direct-to-patient autoinjector delivery models in United States metropolitan markets. Orphan enzyme indications with priority review voucher eligibility offer the most penetrable regulatory pathway for capital-constrained developers. Partner with Kansai-region device manufacturers to secure prefilled delivery system supply without captive manufacturing investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with approved subcutaneous portfolios and established specialty pharmacy relationships. Long-term viability over the coming decade hinges on regulatory exclusivity duration and immunogenicity risk management capabilities. Acquisition targets should demonstrate validated site-specific PEGylation platforms with abbreviated stability testing protocols. Monitor FDA interchangeability designation grants to pegylated interferon biosimilars as the inflection signal for originator pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Site-Specific Conjugation Platform Development | Precision chemistry reduces batch rejection rates and compresses EMA approval timelines for oncology indications. |
| Autoinjector Distribution Partnership | Prefilled device access shifts administration from hospital infusion centers to home care environments in Germany. |
| Orphan Enzyme Indication Expansion | FDA accelerated approval pathways with priority review vouchers extend exclusivity for ultra-rare hematologic applications. |
| Continuous Manufacturing Integration | Single-use bioreactor platforms enable real-time quality control and reduce batch-to-batch variability for contract organizations. |
| REACH Compliance Certification Program | PEG raw material traceability obligations filter European supplier networks and elevate barriers for formulation developers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors across United States and European markets. Secondary validation incorporated FDA filings, EMA CHMP scientific advice records, ClinicalTrials.gov protocol databases, and hospital procurement database extracts. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segment-level estimates.
Across the analysis window, the analytical framework modeled treatment line stratification, administration route differentiation, regional regulatory cluster divergence, and patient population segmentation. CAGRs were derived from fitted growth curves applied to baseline volume and value estimates. Forecast inputs incorporated PEGylation chemistry platform adoption rates, biosimilar entry timing assumptions, and subcutaneous autoinjector penetration trajectories.
Material uncertainties — regulatory pathway delays, immunogenicity signal emergence, and raw material supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding interchangeability designation timelines and European tender framework evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Macrolide Antibiotics Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Biobetters Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market