
 Chronic Phase Markers Market | 2026-2036
Chronic Phase Markers Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Phase Markers Market Outlook
The gap between premium multiplex platforms and single-analyte commodity tests is repositioning procurement criteria across health systems. Roche leverages its installed base of automated analyzers to sustain high-throughput chemistry workflows in centralized labs. DiaSorin anchors its position through specialized immunodiagnostic reagents that command premium positioning in autoimmune and infectious disease panels. QIAGEN competes with sample-to-answer molecular systems that reduce turnaround time for nucleic acid-based chronic phase monitoring.
Chronic phase markers are measurable biological indicators—encompassing proteins, enzymes, nucleic acids, and specialized biomarkers—that signal persistent disease activity after acute onset, typically quantified through sensitivity thresholds in the picogram-per-milliliter range for high-sensitivity immunoassays. These markers serve primarily to stratify patient risk, monitor therapeutic response, and predict relapse in conditions where disease duration extends beyond initial intervention windows. Biomarkers occupy the largest revenue pool given their breadth across oncology and neurology applications, while mass spectrometry represents the fastest-expanding technology segment as clinical labs adopt proteomics-grade precision for protein quantification. PCR-based platforms retain dominant share in infectious disease monitoring where nucleic acid persistence defines chronicity, and ELISA formats maintain cost-efficient scale in high-volume screening settings where throughput outweighs multiplexing depth.
FDA oversight of companion diagnostics and EPA guidelines for clinical laboratory waste streams shape product development pathways and site certification requirements for manufacturers serving the US market. The Centers for Medicare & Medicaid Services reimbursement coding for multianalyte panels directly influences hospital laboratory adoption velocity for advanced chronic phase marker platforms. Stakeholders must weigh capital intensity against test-menu breadth when configuring platform investments for integrated delivery network tenders.
Market Dynamics
Clinical laboratories are consolidating procurement around automated platforms that compress turnaround time for high-sensitivity immunoassays, while FDA companion diagnostic guidance tightens validation thresholds for nucleic acid-based chronic phase monitoring.
Growth Catalysts
- Integrated Delivery Networks:Hospital system consolidation in the United States is standardizing chronic disease screening panels across multi-site laboratory networks.
- Companion Diagnostic Framework:FDA guidance on co-developed biomarkers is accelerating regulatory clarity for oncology and neurology marker validation pathways.
- Mass Spectrometry Proteomics:Clinical adoption of proteomics-grade protein quantification is expanding test-menu breadth for longitudinal patient monitoring.
Market Restraints
- Capital Equipment Intensity:Multiplex platform deployment requires substantial upfront investment in automated liquid handling and detection systems.
- Reagent Supply Concentration:Specialized immunodiagnostic raw materials concentrate among a limited supplier base, creating input vulnerability.
- PCR Platform Commoditization:Infectious disease nucleic acid testing faces margin compression from single-analyte commodity test alternatives.
Strategic Opportunities
- Sample-to-Answer Systems:Molecular platforms that integrate nucleic acid extraction with real-time detection reduce technical labor requirements for point-of-care deployment.
- CMS Reimbursement Expansion:Medicare coding updates for multianalyte panels create favorable reimbursement velocity for advanced chronic phase marker adoption.
- Point-of-Care Decentralization:Portable immunoassay readers enable chronic disease monitoring outside centralized laboratory infrastructure.
Industry Challenges
- Cross-Platform Standardization:Harmonizing sensitivity thresholds across ELISA, chemiluminescence, and mass spectrometry methods complicates longitudinal data comparison.
- Companion Diagnostic Co-Development Timelines:Synchronized therapeutic and diagnostic approval pathways extend product development cycles and regulatory submission complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Phase Markers Market |
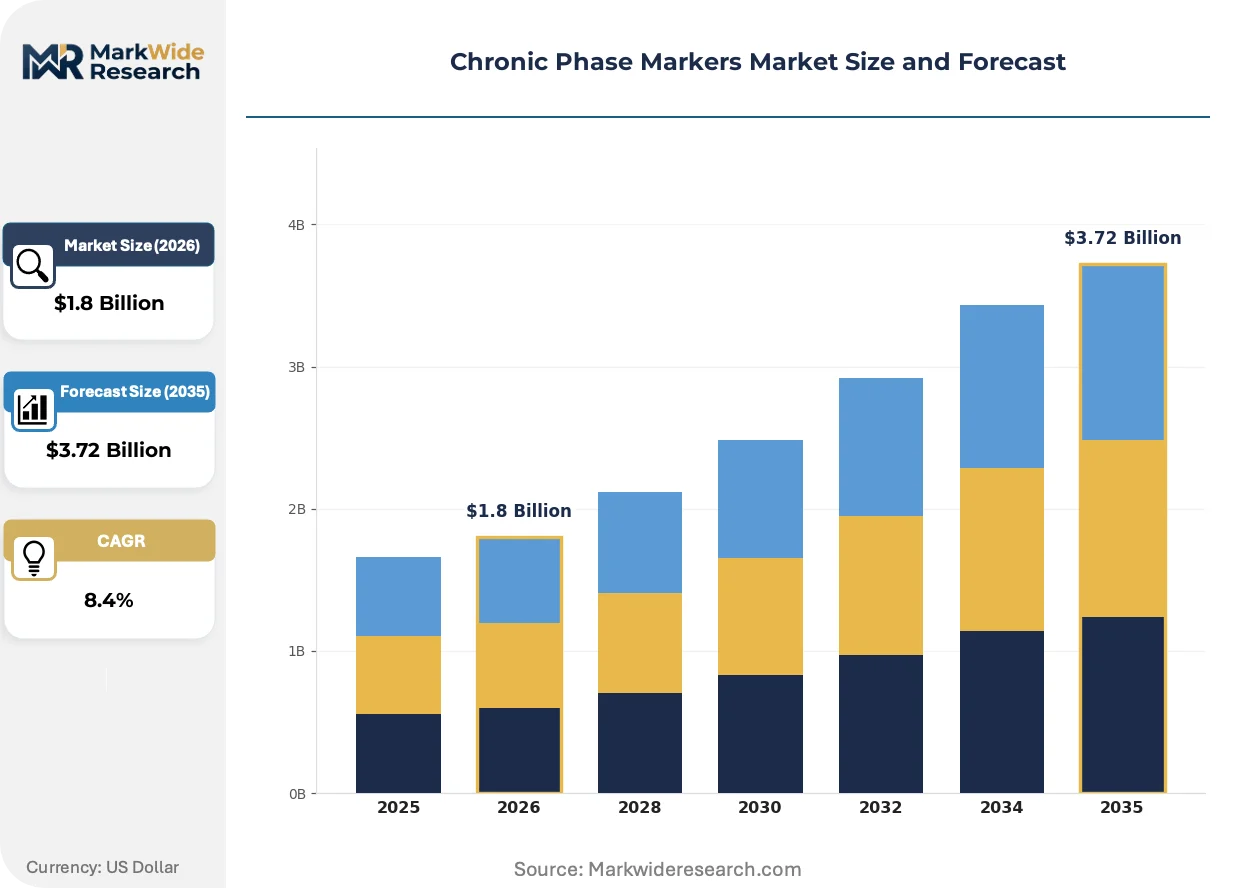
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Enzymes, Proteins, Nucleic Acids Technology: ELISA, PCR, Mass Spectrometry, Microarrays End User: Hospitals, Clinical Laboratories, Research Institutions, Diagnostics Centers Application: Oncology, Neurology, Immunology, Infectious Diseases |
| Companies Covered | Roche, DiaSorin, QIAGEN, Bristol-Myers Squibb, Hologic, Nordic BioSite, Philips, Johnson & Johnson, Lifesign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Phase Markers Market Strategic Shifts
Proteomics-grade instrumentation and regulatory clarity on biomarker validation are compressing the gap between research-grade discovery and clinical-grade deployment for chronic disease monitoring.
High-resolution mass spectrometry is decentralizing protein quantification workflows previously confined to reference laboratories. Regional health systems and academic medical centers are adopting triple-quadrupole and orbitrap platforms for in-house chronic phase marker validation. This instrumentation shift is decentralizing service revenue from national reference laboratories to hospital-based core facilities.
EMA's Medical Device Regulation is tightening post-market surveillance requirements for in-vitro diagnostic devices across European member states. Manufacturers must now maintain systematic clinical evidence collection for chronic phase marker performance claims. Specialized immunodiagnostic reagent suppliers face the steepest compliance burden as they recertify legacy product portfolios under the new framework.
Integrated delivery networks are consolidating laboratory procurement through centralized tender processes that prioritize test-menu breadth over single-platform loyalty. Health system purchasing committees now evaluate total cost of ownership across chemistry, immunoassay, and molecular testing modalities. This buyer concentration is most pronounced in United States metropolitan markets where three to five hospital systems control regional testing volume.
Chronic Phase Markers Market Segmentation
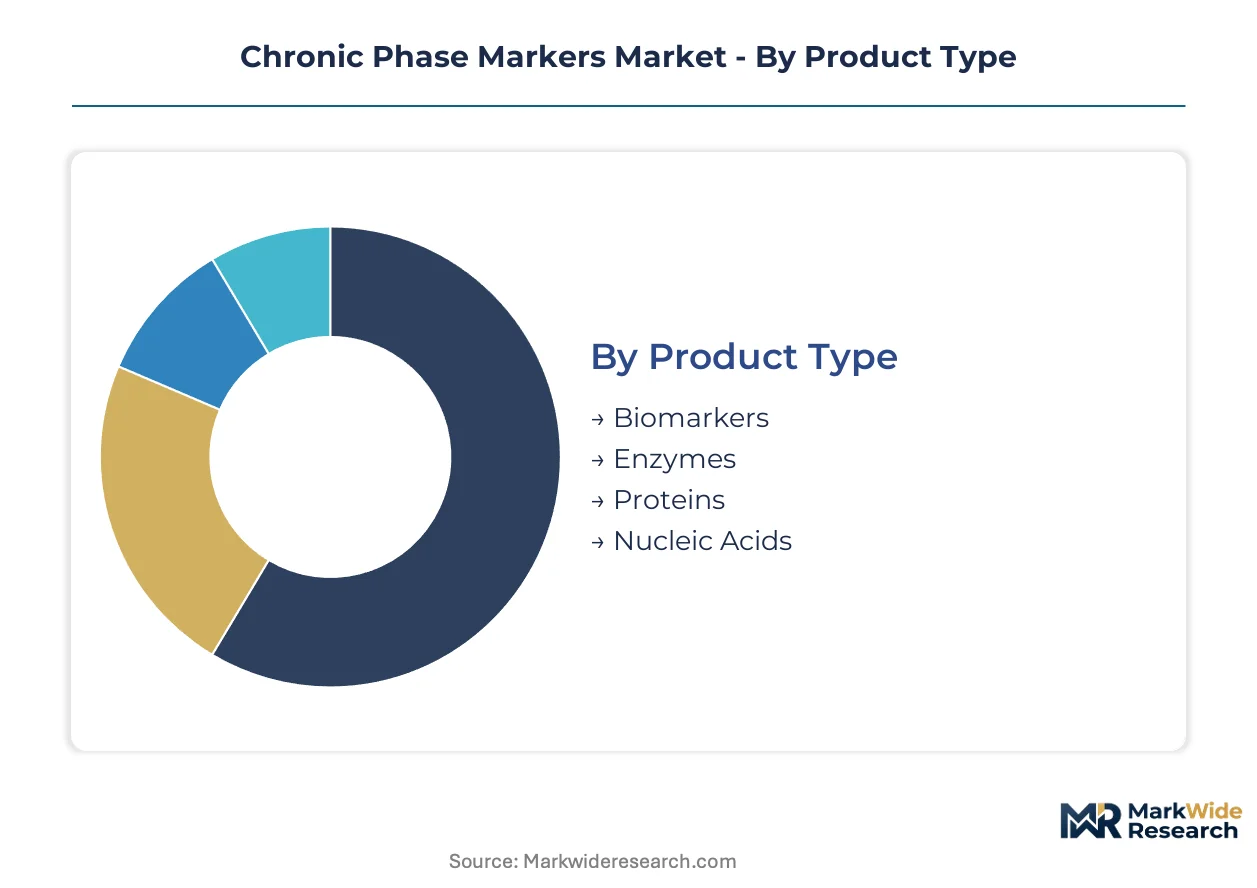
Chronic phase marker procurement varies sharply by integration depth. Standalone platforms serve high-throughput central labs, while embedded systems target point-of-care deployment where workflow compression matters most.
Product Type:
Integration depth separates standalone diagnostic reagents from embedded multi-analyte panels. Biomarkers and nucleic acids anchor multiplexed systems, while enzymes and proteins often deploy as single-analyte additions.
- Biomarkers:These protein, metabolite, and genetic indicators span oncology and neurology panels with sensitivity thresholds reaching picogram-per-milliliter precision. Hospital laboratories in the United States prioritize biomarker breadth when consolidating chronic disease screening across integrated delivery networks, though companion diagnostic validation timelines extend development cycles.
- Nucleic Acids:DNA and RNA persistence markers define chronicity in infectious disease monitoring through quantifiable viral load thresholds. Demand concentrates in clinical laboratories adopting PCR-based platforms, where FDA guidance on co-developed diagnostics tightens quality benchmarks for longitudinal patient tracking.
- Enzymes:Catalytic protein markers signal tissue damage progression in liver and cardiac panels.
- Proteins:Cytokine and antibody quantification supports autoimmune disease stratification.
Volume placements concentrate in biomarkers; the faster expansion belongs to nucleic acids.
Technology:
Cost tier stratification separates premium instrumentation from commoditized formats. Mass spectrometry and microarrays command capital-intensive investment, while ELISA and PCR scale through reagent economics.
- Mass Spectrometry:Triple-quadrupole and orbitrap platforms deliver proteomics-grade protein quantification with unmatched specificity for low-abundance analytes. Academic medical centers in Germany and Switzerland accelerate adoption as regional health systems build in-house chronic phase marker capabilities, displacing reference laboratory revenue.
- PCR:Polymerase chain reaction retains dominant share in infectious disease nucleic acid testing where pathogen persistence defines chronicity. Diagnostics centers across India leverage PCR commoditization to expand test access, though margin compression from single-analyte alternatives pressures platform economics.
- ELISA:Enzyme-linked immunosorbent assays maintain cost-efficient scale in high-volume screening settings.
- Microarrays:Multiplexed nucleic acid detection enables simultaneous profiling of hundreds of genetic markers.
Deployment scale favors ELISA; margin expansion tracks mass spectrometry most closely.
End User:
Customer type determines platform configuration complexity. Hospital systems prioritize test-menu breadth, while research institutions demand analytical flexibility.
- Clinical Laboratories:Centralized facilities consolidate procurement around automated liquid handling and detection systems that compress turnaround time for high-sensitivity immunoassays. Integrated delivery networks in the United States standardize chronic disease screening panels across multi-site laboratory networks, privileging vendors with comprehensive chemistry, immunoassay, and molecular menus.
- Hospitals:Inpatient and outpatient settings require rapid result turnaround for therapeutic decision-making at the point of care.
- Research Institutions:Academic centers drive adoption of novel marker discovery platforms before clinical translation.
- Diagnostics Centers:Independent laboratories compete on price and accessibility for routine chronic monitoring.
Procurement volume pools in clinical laboratories; decentralization momentum favors diagnostics centers.
Application:
Maturity stage separates established therapeutic areas from emerging marker categories. Oncology and infectious diseases command validated reimbursement codes, while neurology and immunology navigate evolving regulatory pathways.
- Oncology:Tumor-associated protein and genetic markers stratify patient risk and monitor therapeutic response across solid and hematologic malignancies. The FDA's companion diagnostic framework accelerates regulatory clarity for co-developed biomarkers, cementing oncology as the revenue anchor for chronic phase marker manufacturers.
- Infectious Diseases:Viral load quantification and seroconversion tracking define chronicity in HIV, hepatitis, and emerging pathogen panels. Clinical laboratories in Brazil and South Africa expand nucleic acid testing infrastructure, though PCR platform commoditization compresses margins in high-prevalence screening programs.
- Neurology:Cerebrospinal fluid and blood-based markers for neurodegenerative progression gain validation traction.
- Immunology:Autoimmune panel expansion targets cytokine profiling for disease activity monitoring.
Revenue concentration sits with oncology; the steepest expansion trajectory belongs to neurology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors chronic phase marker validation activity, with Massachusetts General Hospital and Brigham and Women's Hospital driving proteomics-grade platform adoption. Integrated delivery networks across the United States consolidate procurement around automated immunoassay systems.
United States
Hospital system consolidation and companion diagnostic co-development pipelines concentrate demand in metropolitan markets. The FDA's evolving guidance on biomarker validation tightens quality benchmarks for nucleic acid-based monitoring platforms. The Texas Medical Center in Houston expands high-throughput screening infrastructure for longitudinal patient tracking.
Germany
Academic medical centers accelerate mass spectrometry adoption for in-house chronic phase marker capabilities. The EMA's Medical Device Regulation imposes systematic clinical evidence collection requirements on in-vitro diagnostic manufacturers. The Rhine-Main cluster around Frankfurt displaces reference laboratory revenue as regional health systems build proteomics-grade facilities.
Switzerland
Precision diagnostics specialists leverage the country's pharmaceutical manufacturing density for biomarker co-development partnerships. Swissmedic maintains stringent post-market surveillance protocols for chronic disease monitoring devices. The Basel biotech corridor integrates marker validation workflows with neighboring pharmaceutical R&D operations.
India
Diagnostics centers expand PCR-based infrastructure for infectious disease chronicity monitoring in high-prevalence screening programs. The CDSCO streamlines regulatory pathways for imported molecular diagnostic platforms. Mumbai's private laboratory networks deploy commoditized nucleic acid testing to capture price-sensitive outpatient volume.
Brazil
Clinical laboratories scale viral load quantification capacity for HIV and hepatitis chronic phase tracking. ANVISA harmonizes import certification with Mercosur technical standards for diagnostic reagents. São Paulo's hospital networks centralize procurement through group purchasing organizations serving the Southeast region.
Chronic Phase Markers Market Competitive Environment
Premium-margin players sit above commodity-margin players across platform integration depth and test-menu breadth. The market structures around three tiers: diversified diagnostics conglomerates with automated analyzer installed bases, specialized immunodiagnostic reagent suppliers, and molecular platform specialists with sample-to-answer systems. Consolidation pressures favor vendors with comprehensive chemistry, immunoassay, and molecular menus. Dominant competitive moves include portfolio diversification into adjacent testing modalities and geographic expansion through distributor partnerships in emerging markets.
Within the diversified diagnostics tier, Roche and DiaSorin occupy positions reflecting contrasting strategic anchors. Roche exemplifies the scale-driven archetype leveraging broad installed bases across centralized laboratory networks. DiaSorin represents specialized immunodiagnostic positioning with premium reagent portfolios. QIAGEN sits within the molecular platform specialist category, anchoring sample-to-answer system deployment for nucleic acid-based monitoring applications.
| Leading Market Players |
|---|
| Roche |
| DiaSorin |
| QIAGEN |
| Bristol-Myers Squibb |
| Hologic |
| Nordic BioSite |
| Philips |
| Johnson & Johnson |
| Lifesign |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States concentrate procurement authority for chronic phase marker platforms, compressing vendor margins through centralized tender processes that privilege test-menu breadth over single-platform loyalty.
Pricing Analysis
Value-based pricing anchors chronic phase marker procurement, with reimbursement velocity tied to CMS coding updates for multianalyte panels. Three-tier pricing structure across premium, standard, and economy levels separates proteomics-grade mass spectrometry from automated immunoassay platforms and commoditized PCR reagents. Cost compression in nucleic acid testing intensifies because PCR platform commoditization expands access in price-sensitive diagnostics centers across India and Brazil. Clinical laboratories demonstrate highest price sensitivity due to capital equipment intensity, while academic medical centers absorb premium instrumentation costs for in-house validation capabilities.
Supply Chain Analysis
FDA companion diagnostic qualification and EMA Medical Device Regulation certification gates concentrate specialized immunodiagnostic reagent supply among established manufacturers in Germany, Switzerland, and the United States. Production draws from monoclonal antibody production facilities, magnetic bead substrates, and stabilized enzyme conjugates. Single-source vulnerability persists for high-sensitivity immunoassay raw materials where qualified alternative suppliers require extended validation timelines. Distribution runs through authorized distributor networks serving hospital systems and reference laboratories with cold-chain logistics for temperature-sensitive reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chronic phase marker competition is becoming a vertical-integration race, with manufacturers pursuing captive control over specialized immunodiagnostic raw materials to secure reagent supply continuity against input concentration risks.
For Market Incumbents: Anticipate margin compression from PCR commoditization by deepening backward integration into monoclonal antibody production and magnetic bead substrate manufacturing. Lock in multi-year reagent supply agreements with integrated delivery networks before tender consolidation accelerates. Prioritize FDA companion diagnostic co-development pipelines to anchor premium positioning against emerging sample-to-answer molecular specialists. For New Entrants and Emerging Players: Begin with point-of-care decentralization opportunities where portable immunoassay readers bypass centralized laboratory infrastructure and incumbent installed bases. Neurology biomarker panels offer the most penetrable application segment given evolving regulatory pathways and unmet demand for blood-based neurodegenerative markers. Pursue hospital system partnership models that bundle instrument placement with reagent subscription commitments. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized immunodiagnostic reagent suppliers with FDA-cleared autoimmune and infectious disease portfolios in the European Union. Long-term viability rests on companion diagnostic co-development capabilities spanning oncology and neurology applications. Watch EMA post-market surveillance compliance costs as an inflection indicator for mid-tier manufacturer consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA synchronized approval pathways cement premium pricing for oncology marker portfolios. |
| Mass Spectrometry Platform Deployment | Academic medical centers in Germany displace reference laboratory revenue through in-house proteomics capabilities. |
| Sample-to-Answer System Integration | QIAGEN molecular platforms reduce technical labor requirements for point-of-care nucleic acid testing. |
| Reagent Supply Backward Integration | Roche captive production of immunodiagnostic raw materials insulates against supplier concentration vulnerability. |
| CMS Reimbursement Strategy | Medicare coding updates for multianalyte panels accelerate hospital laboratory adoption velocity. |
Study Parameters
Independent corroboration across laboratory medicine directors, diagnostic platform engineers, and GPO contracts managers underwrites the qualitative findings. Primary interviews with hospital procurement committees and biomedical engineers were cross-referenced against FDA 510(k) filings, CMS Medicare reimbursement databases, and EMA Medical Device Regulation submission records. Secondary validation drew from hospital procurement databases and clinical laboratory accreditation reports. Bottom-up instrument placement modeling and top-down reagent revenue analysis were triangulated against integrated delivery network tender documentation.
Comparable-period anchoring across historical reference periods established baseline trajectories for mass spectrometry adoption curves and PCR platform commoditization patterns. The analytical framework modeled segmentation across technology tier, end-user facility type, application maturity stage, and regional regulatory cluster. CAGRs were derived from instrument placement run rates and reagent consumption per installed base. Forecast inputs included companion diagnostic approval velocity and EMA post-market surveillance compliance cost trajectories.
Underlying measurement precision varies by segment; oncology and infectious disease applications carry tighter precision than emerging neurology biomarker categories due to established reimbursement coding and validation protocols. Forecasts reflect documented assumptions regarding CMS reimbursement expansion timelines and FDA biomarker guidance evolution. A model refresh is warranted upon material change in companion diagnostic co-development pipeline velocity or EMA Medical Device Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Chemotherapy Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market