
 Global Cell Isolation/Cell Separation Market | 2026-2036
Global Cell Isolation/Cell Separation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Isolation/Cell Separation Market Foresight
The cell isolation market is decoupling into two distinct tiers. GMP-grade platforms for commercial cell therapy manufacturing command premium pricing and specialized service relationships. Thermo Fisher Scientific leverages its end-to-end bioproduction portfolio to anchor the premium tier. BD competes through deep integration of flow cytometry hardware with cell sorting workflows. Miltenyi Biotec dominates magnetic cell separation with proprietary column technology that sustains loyalty among academic and clinical researchers.
Cell isolation and cell separation encompass the physical or immunological enrichment of target cell populations from heterogeneous biological samples, typically achieving purity thresholds of 95-99% through antibody-mediated capture, density gradient fractionation, or microfluidic sorting. These processes serve as the foundational step in downstream applications ranging from single-cell genomics to autologous cell therapy manufacturing. Magnetic-Activated Cell Sorting occupies the largest installed base due to its scalability and gentle handling of viable cells, while Microfluidics represents the fastest-growing technology segment as labs miniaturize workflows and reduce reagent consumption. Cell Isolation Kits generate the highest margin pools because recurring consumable purchases lock in long-term customer relationships.
FDA, EMA, and ISO 13485 standards govern cell separation device validation, biocompatibility testing, and traceability requirements for clinical-grade applications. These frameworks elevate barriers for instrument entrants while creating sustained demand for certified reagents and documented protocols. Stakeholders must monitor how evolving cell therapy approval pathways reshape instrument qualification requirements and consumable specification thresholds.
Market Dynamics
Automated cell separation platforms are compressing manual workflow timelines from hours to minutes, forcing incumbent instrument makers to requalify their installed base while contract manufacturers build GMP-grade capacity to serve commercial cell therapy pipelines.
Growth Catalysts
- EMA cell therapy manufacturing guidance:Tighter quality documentation requirements for clinical-grade separation devices are locking in demand for validated instruments and certified consumables across European manufacturing sites.
- Microfluidic miniaturization:Labs in Germany, the United States, and China are shrinking reagent volumes and footprint requirements, expanding addressable lab space in resource-constrained settings.
- CAR-T manufacturing scale-up:Academic medical centers and CMOs are installing high-throughput magnetic sorting systems to meet patient-specific production quotas for approved therapies.
Market Restraints
- Neodymium supply concentration:Magnetic bead production depends on rare earth processing concentrated in China, exposing reagent makers to export quota volatility and price spikes.
- ISO 13485 certification timelines:New device entrants face 18-24 month validation cycles for clinical-grade separation platforms, freezing out capital-constrained innovators.
- Flow cytometry substitution:High-parameter spectral analyzers are capturing applications previously served by dedicated cell sorters in discovery-phase research budgets.
Strategic Opportunities
- India biomanufacturing buildout:CDSCO is streamlining cell therapy trial approvals, attracting CMO investment in Bangalore and Hyderabad that requires GMP-compatible separation infrastructure.
- Point-of-care autologous processing:Portable microfluidic devices are opening bedside cell isolation for military field hospitals and rural oncology clinics lacking central lab access.
- AI-guided sort optimization:Machine learning models trained on multi-parameter flow data are converging with hardware controls to reduce operator-dependent variability in rare cell enrichment.
Industry Challenges
- GMP-grade operator scarcity:Cell therapy manufacturers in the United States and Germany are competing for technicians qualified in aseptic processing and FDA-compliant batch documentation.
- Legacy LIMS integration friction:New automated separation platforms must interface with decade-old laboratory information systems, extending deployment timelines and validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Isolation/Cell Separation Market |
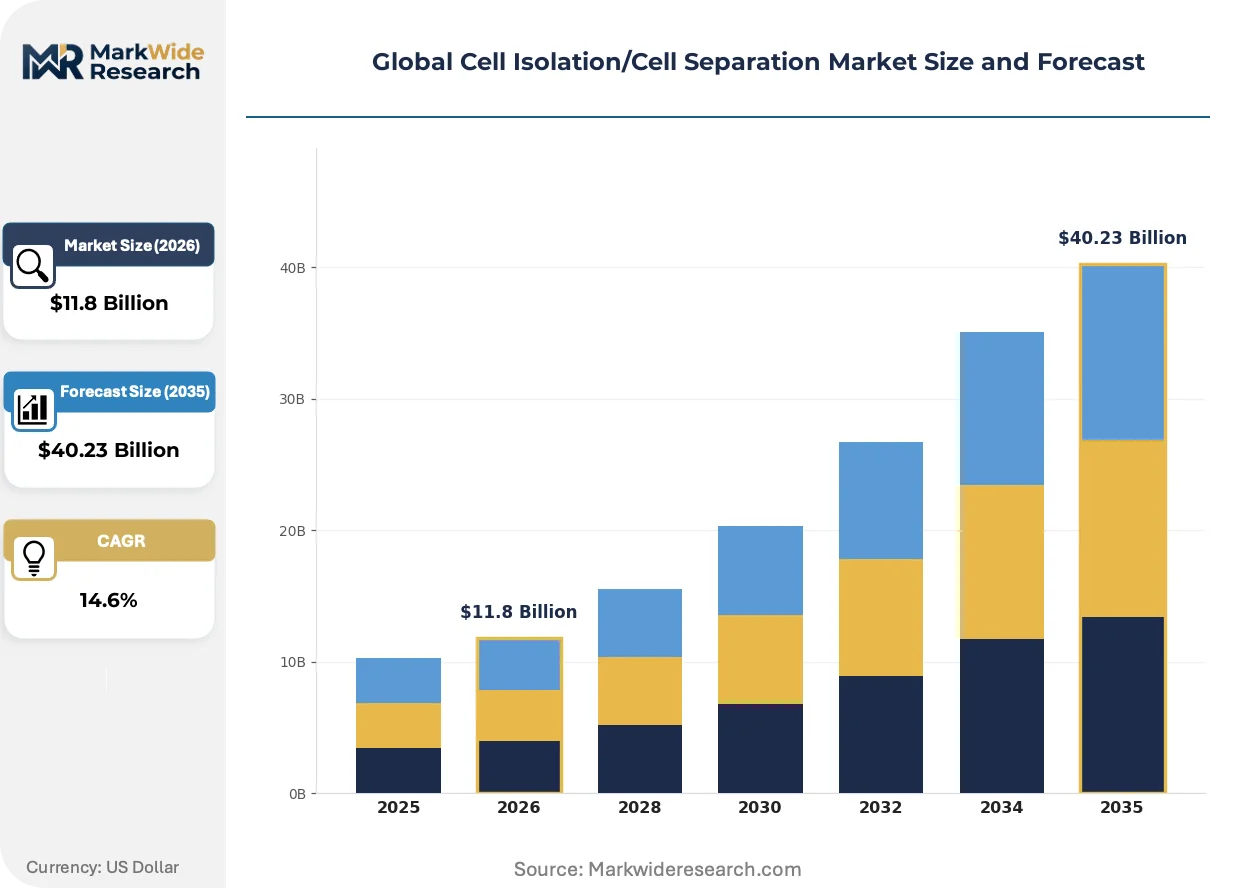
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic-Activated Cell Sorting, Fluorescence-Activated Cell Sorting, Density Gradient Centrifugation, Microfluidics, Immunoaffinity Chromatography Application: Stem Cell Research, Cancer Diagnostics, Drug Discovery, Regenerative Medicine, Immunology Studies Product Type: Cell Isolation Kits, Cell Separation Instruments, Reagents, Consumables, Automation Systems End User: Biotechnology Firms, Pharma Companies, Research Institutes, Academic Laboratories, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, Inc., BD, Danaher, Merck KGaA, STEMCELL Technologies Inc., Bio-Rad Laboratories, Inc., Agilent Technologies, Inc., Terumo Corp., Miltenyi Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Isolation/Cell Separation Market Shifts & Advancements
Workflow digitization and closed-system automation are collapsing contamination risks while compressing the skill gradient required to execute clinical-grade cell isolation.
Microfluidic chip-based sorting is decentralizing cell separation from centralized core facilities into individual research labs and manufacturing suites. Academic groups in the United States and Germany are adopting disposable cartridge systems at twice the pace of traditional sorters. This diffusion is compressing the addressable market for high-maintenance shared instruments while expanding consumable pull-through.
FDA's evolving guidance on cell therapy CMC (Chemistry, Manufacturing, and Controls) is mandating closed-system processing for commercial-scale autologous products. Device makers are redesigning instrument architectures to eliminate open manipulation steps. The United States market is responding fastest, with CMOs pre-qualifying only platforms meeting draft contamination control standards.
Service unbundling is fragmenting the traditional instrument-reagent-software bundle. Cell therapy CMOs in China and Germany are procuring separation consumables through separate tenders from hardware, pressuring integrated suppliers to defend margin on disaggregated SKUs. This pattern is most visible in magnetic bead categories where third-party validated alternatives have achieved regulatory equivalence.
Global Cell Isolation/Cell Separation Market Segmentation
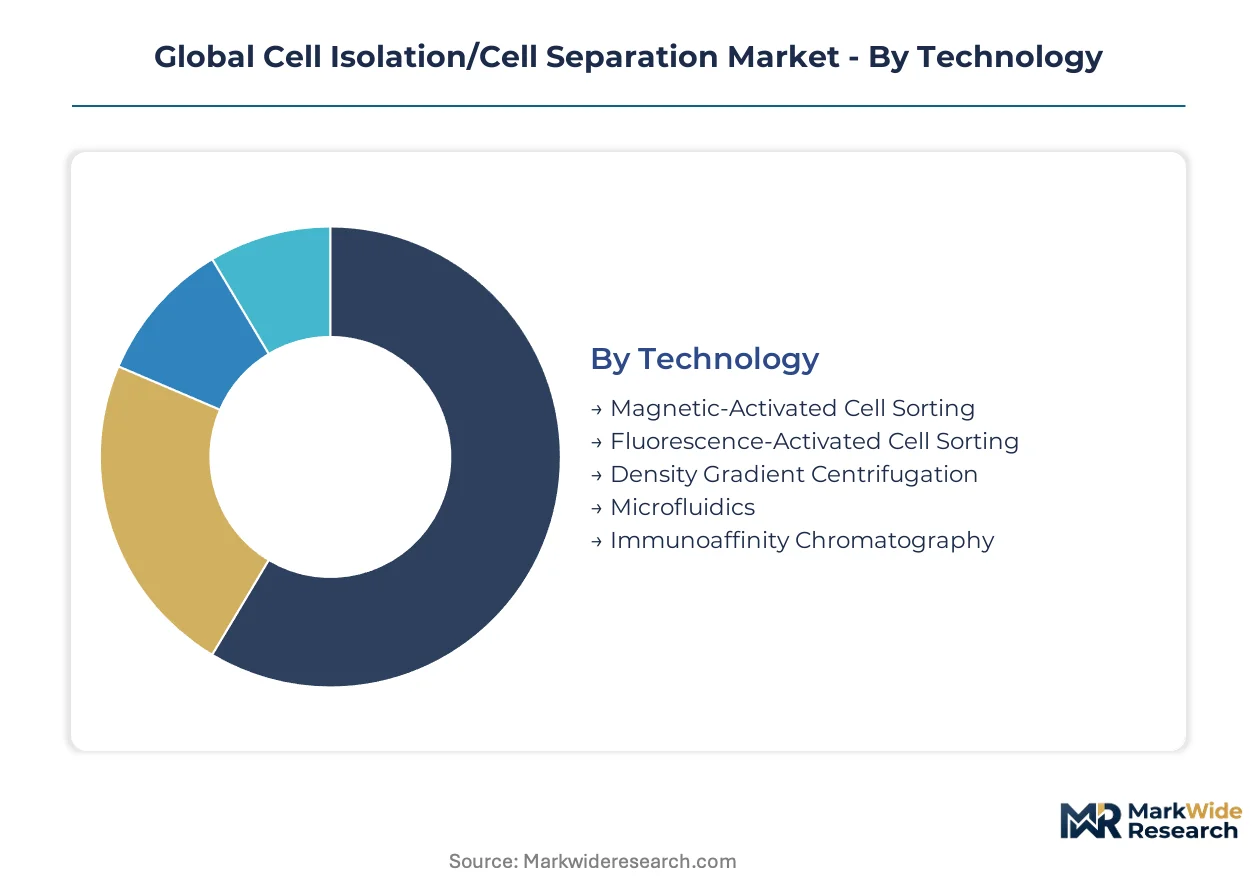
Cell isolation market segmentation reveals how technology choices cascade through procurement decisions, with magnetic platforms dominating high-volume manufacturing while microfluidic systems capture miniaturization budgets. Product type splits expose the recurring revenue logic that separates instrument vendors from consumable suppliers. End-user distinctions map directly onto regulatory complexity tiers, from exploratory academic work to FDA-validated commercial production.
Technology:
Standardization dominates high-throughput manufacturing workflows, while customization prevails in discovery-phase research where protocol flexibility outweighs throughput requirements.
- Magnetic-Activated Cell Sorting:Antibody-coated paramagnetic beads enable gentle, scalable capture of target populations without fluorescent labeling or fluidic shear stress. Demand concentrates in CAR-T manufacturing suites across the United States and Germany, where closed-system magnetic platforms satisfy FDA draft guidance on contamination control in autologous cell therapy production.
- Microfluidics:Chip-based laminar flow separation achieves single-cell resolution with nanoliter reagent volumes and eliminates centrifugation steps. Academic laboratories in Germany and the United States are adopting disposable cartridge systems at twice the pace of traditional sorters, compressing footprint requirements in resource-constrained settings.
- Fluorescence-Activated Cell Sorting:High-speed electrostatic droplet deflection enables multi-parameter analysis with 99%+ purity for rare population enrichment.
- Density Gradient Centrifugation:Differential sedimentation through viscous media separates cell types by buoyant density without antibody dependence.
- Immunoaffinity Chromatography:Column-based antibody capture scales from analytical to preparative volumes with continuous processing capability.
Leading the category by volume: Magnetic-Activated Cell Sorting. Expanding most quickly: Microfluidics.
Application:
Cost tiers separate commodity diagnostic workflows from premium therapeutic manufacturing, with regenerative medicine commanding 3-5x reagent spending per isolation versus research applications.
- Regenerative Medicine:Clinical-grade isolation of mesenchymal stem cells, induced pluripotent stem cells, and progenitor populations requires documented traceability, donor screening, and GMP-compliant reagent certification. Manufacturing sites in the United States, Germany, and China are installing qualified magnetic separation platforms to meet EMA and FDA chemistry-manufacturing-controls requirements for commercial cell therapy approval.
- Cancer Diagnostics:Circulating tumor cell enrichment from peripheral blood enables liquid biopsy applications with minimal invasiveness. Hospital laboratories in the United States are deploying microfluidic isolation systems to reduce sample-to-result time for oncology staging decisions.
- Stem Cell Research:Exploratory isolation of neural, hematopoietic, and embryonic stem cell populations for mechanism studies and differentiation protocols.
- Drug Discovery:High-throughput primary cell isolation for target validation, toxicity screening, and patient-derived model generation.
- Immunology Studies:T-cell, B-cell, and dendritic cell subset purification for mechanistic investigation of immune response pathways.
Steepest expansion trajectory: Regenerative Medicine. Largest current volume: Cancer Diagnostics.
Product Type:
Margin structures diverge sharply between capital equipment with 5-7 year replacement cycles and consumables generating 60-70% gross margins through recurring pull-through.
- Cell Isolation Kits:Pre-validated antibody cocktails, magnetic beads, and buffers packaged for specific cell type targets reduce protocol development burden. Biotechnology firms in the United States and Germany are locking in multi-year supply agreements for GMP-grade kits to secure batch consistency across clinical trial phases.
- Automation Systems:Closed-cassette instruments integrate sample preparation, labeling, separation, and collection with electronic batch records for regulatory submission. Contract research organizations in China are deploying automated platforms to compress technician training timelines and reduce operator-dependent variability.
- Cell Separation Instruments:Standalone magnetic columns, flow cytometers, and centrifuges requiring manual sample handling and protocol optimization.
- Reagents:Antibodies, fluorescent dyes, density gradient media, and blocking buffers sold separately from bundled kits.
- Consumables:Disposable columns, cartridges, tubing sets, and collection vessels with single-use regulatory status.
Highest margin capture: Cell Isolation Kits. Fastest installed base growth: Automation Systems.
End User:
Customer maturity separates quality-system-mandated procurement in commercial manufacturing from price-sensitive academic purchasing with discretionary protocol modification.
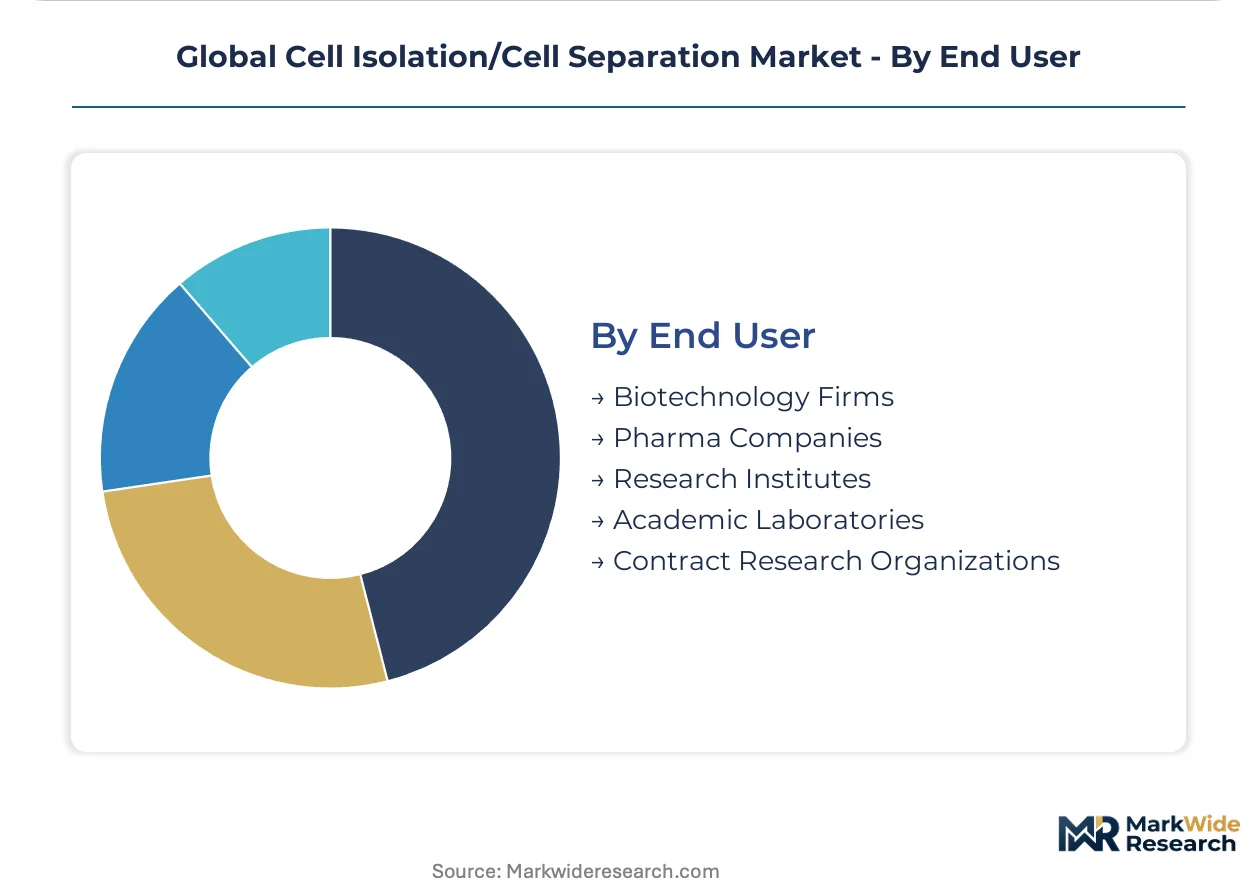
- Contract Research Organizations:CDMOs and CROs serving cell therapy developers require dual capability in GMP-compliant manufacturing and exploratory process development. CMOs in the United States and Germany are pre-qualifying separation platforms against FDA draft contamination control standards, creating vendor lock-in for approved instrument-consumable combinations.
- Pharma Companies:Internal cell therapy pipelines and partnered autologous product manufacturing drive demand for scalable, validated separation infrastructure. Large pharma manufacturers in Germany are consolidating magnetic bead procurement through single-source tenders to simplify supplier qualification overhead.
- Biotechnology Firms:Venture-funded developers of novel cell therapies with outsourced manufacturing and in-house process analytics.
- Research Institutes:National laboratories and disease-focused foundations with exploratory cell biology programs and limited GMP exposure.
- Academic Laboratories:University-based principal investigator groups with flexible protocols, trainee-operated equipment, and grant-dependent capital budgets.
Dominant procurement volume: Contract Research Organizations. Fastest budget growth: Pharma Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Kendall Square corridor anchors the densest concentration of cell therapy manufacturing infrastructure, with academic medical centers and contract manufacturers co-locating separation platforms within FDA inspection zones.
United States
CAR-T manufacturing scale-up and autologous cell therapy commercialization drive platform installation across Massachusetts, California, and Maryland manufacturing corridors. FDA draft guidance on contamination control mandates closed-system separation for commercial production, locking in demand for validated instruments. The Boston-Cambridge cluster hosts the highest density of GMP-grade magnetic sorting installations serving approved therapies.
Germany
Academic laboratories and CMOs in Heidelberg, Munich, and Berlin are deploying microfluidic cartridge systems at accelerated rates to compress reagent volumes and footprint requirements. EMA cell therapy manufacturing guidance tightens quality documentation standards for clinical-grade separation devices across European manufacturing sites. The Rhine-Main biotech corridor concentrates automated platform procurement for regenerative medicine applications.
China
Domestic cell therapy developers in Shanghai, Suzhou, and Beijing are building manufacturing capacity to serve NMPA approval pathways for novel autologous products. The country's central pharmaceutical regulator intensifies GMP inspection protocols for cell-based therapy production facilities. The Suzhou Industrial Park hosts dedicated cell therapy manufacturing clusters requiring magnetic separation infrastructure at commercial scale.
India
CDSCO streamlining of cell therapy trial approvals attracts CMO investment in Bangalore and Hyderabad, creating demand for GMP-compatible separation platforms. The national pharmaceutical regulator accelerates review timelines for regenerative medicine manufacturing facilities. Hyderabad's Genome Valley cluster emerges as a focal point for contract manufacturing infrastructure serving domestic and export markets.
Japan
PMDA oversight of cell therapy commercial manufacturing elevates qualification requirements for separation device validation and biocompatibility testing. Tokyo and Osaka metropolitan areas concentrate regenerative medicine manufacturing investments requiring documented traceability systems. The Kansai biomedical corridor integrates magnetic sorting platforms into induced pluripotent stem cell therapy production workflows.
Global Cell Isolation/Cell Separation Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across instrument and consumable categories, creating a tiered structure where integrated bioproduction portfolios command premium positioning while specialized component suppliers capture niche workflows. The market consolidates around three strategic archetypes: end-to-end bioproduction conglomerates, magnetic separation specialists with proprietary consumable lock-in, and microfluidic technology disruptors targeting miniaturization budgets. Competitive moves center on strategic partnerships with cell therapy CMOs for platform pre-qualification and geographic expansion into emerging biomanufacturing clusters in India and China.
Within the integrated bioproduction tier, Thermo Fisher Scientific anchors premium positioning through end-to-end portfolio breadth, while BD occupies a central position linking flow cytometry hardware with cell sorting workflows. Miltenyi Biotec exemplifies the magnetic separation specialist archetype, sustaining researcher loyalty through proprietary column technology and consumable recurring revenue models. These three entities represent distinct competitive vectors: portfolio integration, hardware-software convergence, and consumable-driven platform stickiness.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| BD |
| Danaher |
| Merck KGaA |
| STEMCELL Technologies Inc. |
| Bio-Rad Laboratories, Inc. |
| Agilent Technologies, Inc. |
| Terumo Corp. |
| Miltenyi Biotec |
| Others |
Supply & Pricing Matrix
Neodymium oxide price volatility cascades through magnetic bead manufacturing costs, compressing margins for reagent suppliers while forcing cell therapy CMOs to renegotiate long-term kit contracts or absorb input cost spikes through tiered pricing adjustments.
Pricing Analysis
Yield-guaranteed throughput contracts anchor pricing for automated separation platforms, with CMOs paying premium rates for validated instruments meeting FDA draft contamination standards. Three-tier pricing structure across GMP-certified, research-grade, and unvalidated equipment levels separates procurement budgets. Cost compression in research-grade consumables is intensifying because third-party magnetic bead alternatives have achieved regulatory equivalence in Europe. Academic laboratories exhibit highest price sensitivity, while commercial cell therapy manufacturers prioritize batch consistency over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from German and United States cell therapy manufacturers require qualified backup suppliers for magnetic beads and GMP-certified buffers, extending qualification timelines but reducing single-source exposure. Rare earth processing concentrates in China, with secondary refining capacity in the United States and Germany. Magnetic bead production draws from neodymium, iron oxide nanoparticles, and recombinant antibody stocks. Tariff exposure on Chinese rare earth exports threatens reagent cost stability. Distribution runs through authorized distributors serving CMO clusters in Massachusetts, Heidelberg, and Suzhou.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around GMP-compliant platform providers as ISO 13485 certification timelines freeze out capital-constrained innovators unable to sustain validation costs.
For Market Incumbents: Lock in CMO relationships through multi-year consumable supply agreements tied to instrument pre-qualification against FDA draft guidance. Defend magnetic bead margins by accelerating proprietary column technology refreshes before third-party alternatives achieve broader regulatory equivalence. Threat substitution from high-parameter spectral flow cytometers demands hardware-software convergence investments. For New Entrants and Emerging Players: Enter via point-of-care microfluidic devices for military field hospitals and rural oncology clinics lacking central lab infrastructure. Target India's Bangalore and Hyderabad CMO buildout where CDSCO streamlining has compressed trial approval timelines but GMP-grade separation infrastructure remains undersupplied. Lead with disposable cartridge systems that eliminate legacy LIMS integration friction. For Investors and Strategic Acquirers: The window for entry favors consumable-specialist firms with validated antibody libraries and established CMO procurement relationships. Long-term viability hinges on recurring revenue models with 60-70% gross margin profiles rather than capital equipment cycles. Watch for EMA guidance finalization on cell therapy manufacturing standards as the inflection signal for European platform replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Platform Pre-Qualification | CMOs in Massachusetts and Heidelberg lock in validated instrument-consumable combinations ahead of FDA and EMA final guidance. |
| Microfluidic Cartridge Development | Disposable systems from German and United States academic labs compress footprint requirements while expanding consumable pull-through. |
| Dual-Sourcing Supply Agreements | Magnetic bead manufacturers qualify secondary rare earth refiners in Germany to mitigate Chinese export quota volatility. |
| AI-Guided Sort Optimization | Machine learning integration with flow cytometry hardware reduces operator-dependent variability in rare cell enrichment workflows. |
| India Manufacturing Infrastructure | CMOs in Hyderabad's Genome Valley cluster install GMP-compatible separation platforms to serve CDSCO-accelerated trial pathways. |
Research Methodology
Independent corroboration across cell therapy manufacturing executives, regulatory affairs leads at CMOs, GMP compliance officers, and laboratory procurement managers underwrites the qualitative findings. Primary interviews with platform engineers and consumable R&D directors combined with secondary validation from FDA 510(k) filings, EMA qualification databases, ISO 13485 certification records, and hospital GPO contracts. Bottom-up instrument installation counts and top-down bioproduction capacity estimates triangulate market sizing.
Rate-of-change decomposition separates volume expansion from price trajectory across the analysis window. Segmentation dimensions modeled include technology type, application tier, product category, and end-user regulatory complexity. CAGRs derive from fitted growth curves applied to validated base-year estimates. Industry-specific inputs incorporate CAR-T manufacturing scale-up timelines, NMPA approval pathway acceleration in China, and microfluidic cartridge adoption rates in German academic laboratories.
Revisions become necessary when rare earth export restrictions tighten, EMA or FDA guidance finalization accelerates platform obsolescence, or spectral flow cytometry substitution exceeds projected rates. Forecasts reflect documented assumptions on certification timeline stability and CMO capital expenditure continuity. A model refresh is warranted upon material change in cell therapy commercial approval volumes or neodymium supply concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Biobanking Market
Biotechnology Services
Biobank Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Biomarker Research Services Market