
 Biobetters Market | 2026-2036
Biobetters Market Size, Share, and Industry Trends Forecast 2026-2036
Biobetters Market Intelligence
FDA biosimilar interchangeability qualification is unwinding competitive barriers for developers with advanced platform technologies. Amgen leverages decades of biologics manufacturing scale to sustain cost advantages across its biobetter portfolio. Regeneron Pharmaceuticals differentiates through proprietary VelocImmune antibody discovery platforms that accelerate candidate selection. Samsung Biologics anchors contract development capacity for biobetter programs across Asia-Pacific and Western markets.
Biobetters represent engineered therapeutic proteins with modified amino acid sequences, glycosylation patterns, or conjugation chemistries that improve pharmacokinetic profiles, immunogenicity, or target specificity beyond originator biologics. These molecules typically employ PEGylation, Fc-fusion, or site-directed mutagenesis to extend half-life or enhance receptor binding, serving primarily to maintain efficacy while reducing dosing frequency or adverse events in chronic disease management. Monoclonal antibodies occupy the largest value pool given their dominance in oncology and autoimmune indications, though growth factors are gaining traction in rare disease applications where modified potency profiles justify premium positioning. Injectable delivery modes command the majority of administered doses, yet transdermal formulations represent an emerging structural opportunity for patient adherence improvement in diabetes and hormone replacement segments.
FDA, EMA, and Japan's PMDA collectively govern biobetter approval pathways through distinct but converging standards for immunogenicity assessment, comparability protocols, and post-market surveillance requirements. These regulatory frameworks shape development timelines, manufacturing investment thresholds, and market access conditions across jurisdictions. Stakeholders must monitor evolving interchangeability designations and real-world evidence requirements as determinants of competitive positioning and reimbursement negotiation leverage.
Market Dynamics
FDA's interchangeability guidelines and EMA's evolving biologics pathways are compressing development timelines while simultaneously raising the bar for immunogenicity evidence, forcing developers to choose between accelerated entry and premium positioning strategies.
Growth Catalysts
- Interchangeability Designation:FDA's biosimilar interchangeability guidelines enable pharmacy-level substitution without prescriber intervention, expanding patient access for qualifying biobetter candidates in chronic disease management.
- PEGylation Platform Maturation:Advanced polyethylene glycol conjugation chemistries now deliver predictable pharmacokinetic extensions across multiple protein classes, reducing dosing frequency for oncology and autoimmune patients.
- Japan Premium Reimbursement:PMDA's favorable pricing framework for next-generation biologics sustains developer margins while accelerating patient access to half-life extended therapeutics in Tokyo and Osaka hospital networks.
Market Restraints
- Cell Line Development Costs:Proprietary CHO cell line optimization requires capital-intensive stable expression engineering, concentrating viable manufacturing among established biologics producers with captive platform technologies.
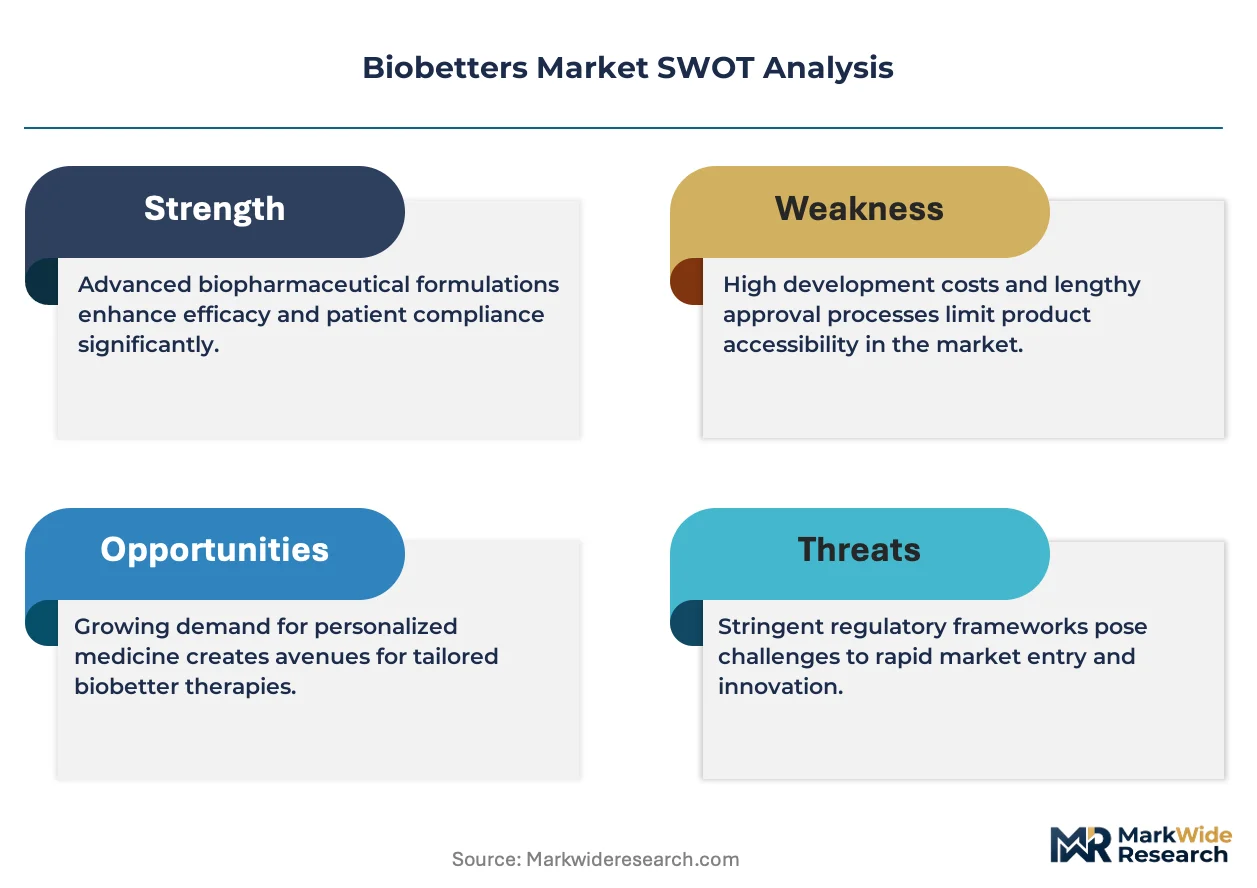
- Immunogenicity Assessment Burden:EMA's stringent comparability protocols for glycosylation pattern analysis extend preclinical timelines and require specialized analytical capabilities unavailable to emerging developers.
- Originator Patent Thickets:Dense Fc-fusion and site-directed mutagenesis patent estates in the United States create freedom-to-operate barriers that delay biosimilar entry even after composition-of-matter expiration.
Strategic Opportunities
- Rare Disease Glycoengineering:Modified potency growth factors for orphan indications command premium positioning in Germany's statutory reimbursement system where clinical differentiation justifies elevated price bands.
- Transdermal Formulation Gap:Microneedle array delivery technologies for peptide biobetters address unmet adherence needs in diabetes management, with development activity concentrating in Boston and Basel innovation clusters.
- Real-World Evidence Pathways:FDA's expanding acceptance of post-market effectiveness data creates accelerated label expansion opportunities for biobetters with established safety profiles in comparable indications.
Industry Challenges
- Analytical Biosimilarity Talent:Shortage of mass spectrometry specialists capable of higher-order structure characterization creates bottlenecks in comparability protocol execution across contract development organizations.
- Multi-Site Manufacturing Consistency:Maintaining glycosylation uniformity across geographically distributed production facilities requires harmonized cell culture parameters that strain quality assurance systems.
- Legacy Purification Retrofit:Existing protein A chromatography infrastructure at many contract manufacturers lacks the resolution needed for novel Fc-engineered variants, demanding capital-intensive downstream reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biobetters Market |
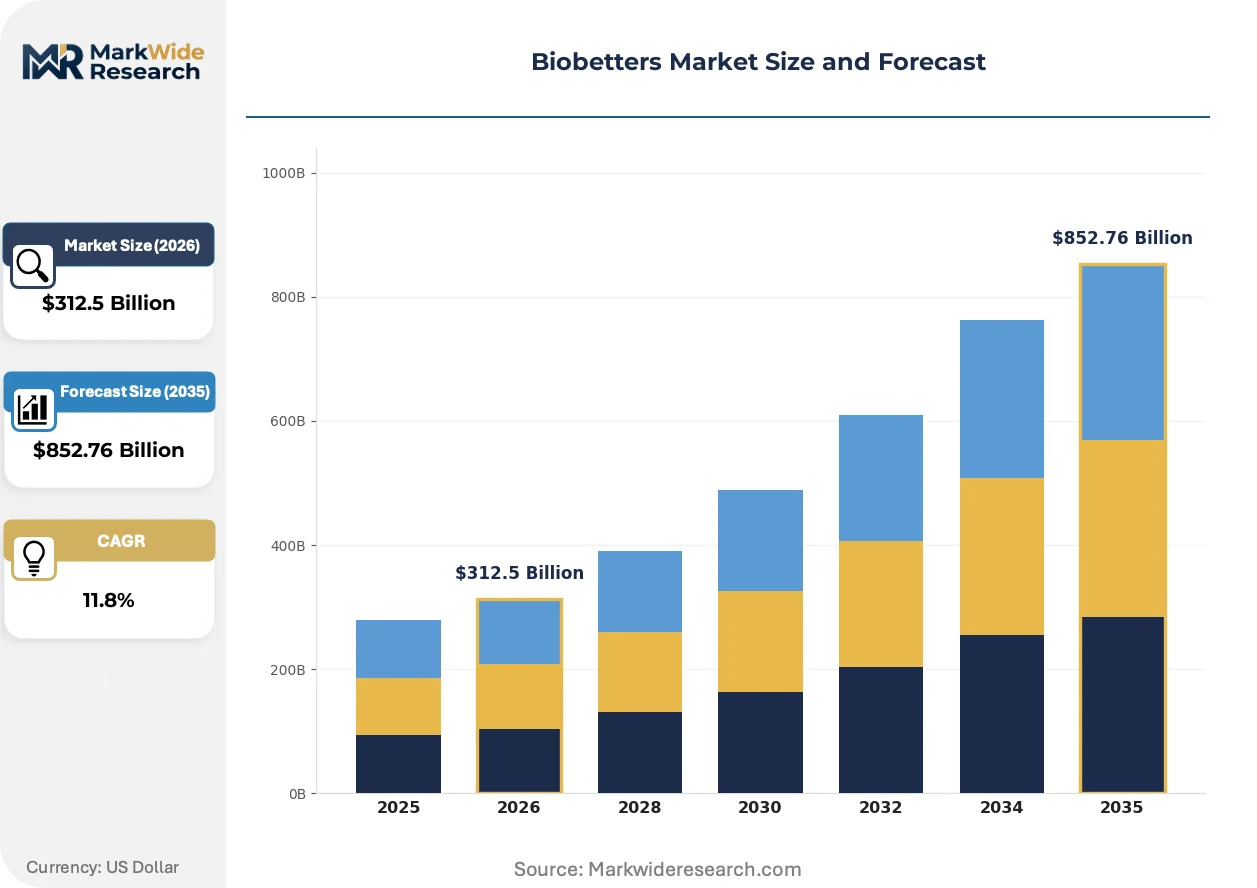
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $852.76 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Insulin, Growth Factors, Enzymes Application: Oncology, Autoimmune Disorders, Chronic Diseases, Infectious Diseases Delivery Mode: Injectable, Oral, Transdermal, Inhalable End User: Hospitals, Clinics, Research Laboratories, Home Care |
| Companies Covered | Gilead Sciences, Alnylam Pharmaceuticals, Amgen, UCB, Argenx, Regeneron Pharmaceuticals, Chugai Pharmaceutical, Samsung Biologics, Vertex Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biobetters Market Strategic Shifts & Innovations
Platform engineering capabilities are separating developers into distinct competitive tiers based on their ability to generate novel intellectual property versus execute on established modalities. This technological stratification is reshaping partnership structures and valuation multiples across the therapeutic protein landscape.
Site-specific conjugation technologies using non-natural amino acid incorporation are bifurcating the antibody-drug conjugate adjacent space. Oncology-focused biobetter developers in San Diego and Cambridge are adopting these chemistries to achieve homogeneous payload loading. The structural consequence is compressing traditional stochastic conjugation approaches into commodity manufacturing while premium positioning accrues to developers with orthogonal tRNA synthetase platforms.
EMA's revised comparability guidelines for post-approval manufacturing changes are tightening immunogenicity surveillance requirements across the European Union. Developers must now submit extended patient exposure data for glycosylation profile modifications. Biobetter programs targeting autoimmune indications face the steepest compliance burden, with several sponsors restructuring their CMC filing strategies to front-load analytical characterization.
Hospital formulary committees in the United States are consolidating purchasing authority for infused biologics into centralized pharmacy and therapeutics boards. This concentration is displacing individual physician prescribing autonomy in favor of protocol-driven biobetter selection. The shift is most visible in integrated delivery networks across Texas and Florida, where oncology pathway standardization now mandates specific half-life extended products for first-line regimens.
Biobetters Market Segmentation
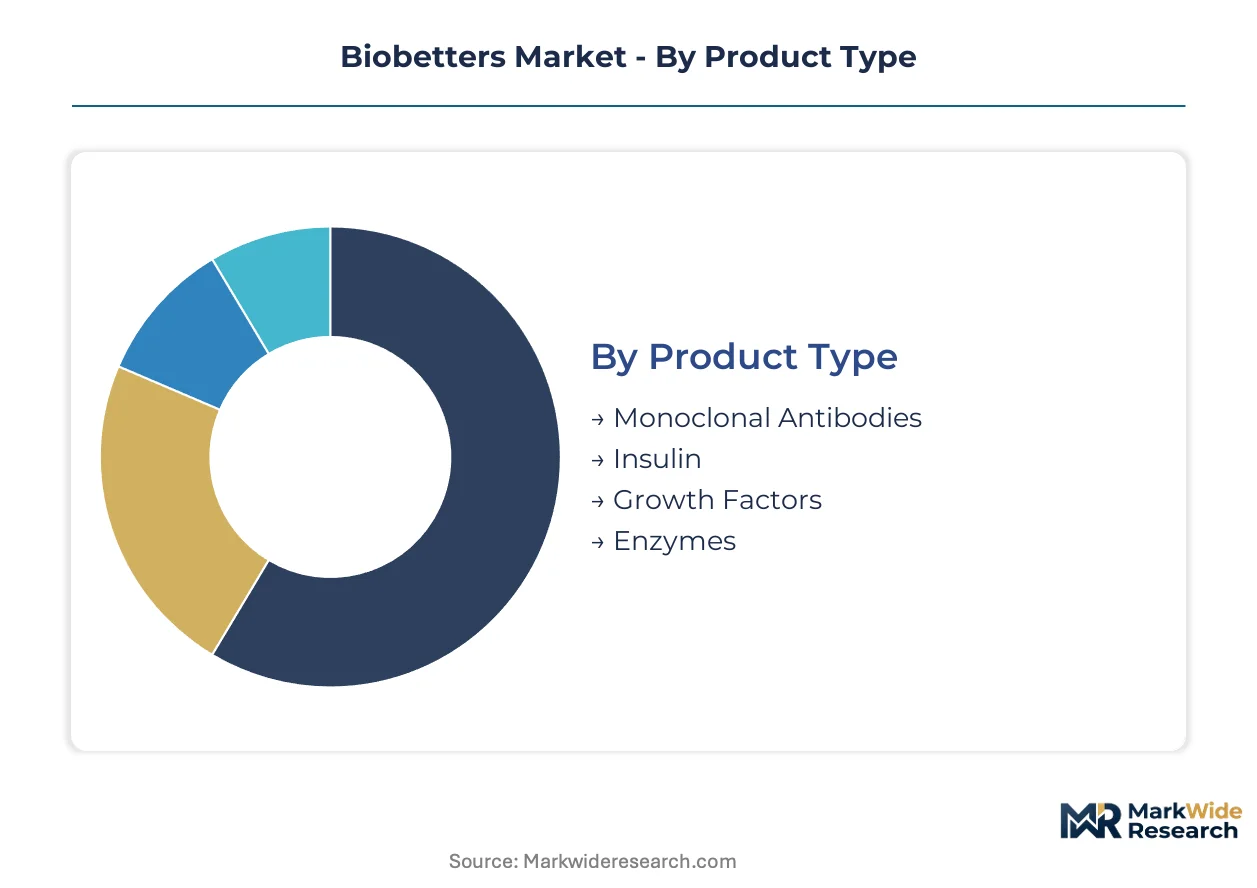
Segmentation reveals how biobetter developers allocate R&D resources across molecular platforms and therapeutic domains. Product engineering decisions, route of administration investments, and channel strategies diverge sharply based on which segments a company targets.
Product Type:
Monoclonal antibodies dominate domestic manufacturing footprints in the United States and Germany, while growth factors and insulin variants drive export-oriented production from contract manufacturers in South Korea and Singapore.
- Monoclonal Antibodies:Engineered immunoglobulins with Fc-modified half-life extensions or enhanced effector functions. Demand concentrates in tertiary oncology centers across Boston, Heidelberg, and Tokyo where infusion protocols favor extended-interval dosing. PEGylation and glycoengineering platforms differentiate competitive offerings.
- Insulin:Site-directed mutagenesis creates rapid-acting or ultra-long-acting analogs with modified hexamer dissociation kinetics. German and Japanese reimbursement systems sustain premium positioning for basal insulin biobetters with demonstrated hypoglycemia reduction.
- Growth Factors:Modified erythropoietins and G-CSF variants serve rare disease and oncology supportive care indications.
- Enzymes:PEGylated or fusion-tagged replacements for lysosomal storage disorders and metabolic deficiencies.
Monoclonal antibodies command the established base. The steepest expansion runs through growth factors.
Application:
Oncology applications absorb the highest per-patient pricing premiums, while chronic disease segments reward volume scale and pharmacy-level substitution economics.
- Oncology:Half-life extended checkpoint inhibitors and cytotoxic antibody conjugates reduce infusion center burden. Leading cancer institutes in Houston, Manchester, and Osaka prioritize biobetters enabling three-week versus two-week dosing intervals.
- Autoimmune Disorders:TNF-alpha and interleukin pathway biobetters compete on immunogenicity profiles and subcutaneous self-administration convenience. Rheumatology practices in Berlin and Chicago drive adoption of citrate-free formulations.
- Chronic Diseases:Diabetes, anemia, and growth hormone deficiency represent recurring revenue pools where dosing frequency reductions improve adherence metrics.
- Infectious Diseases:Extended-half-life monoclonal antibodies for RSV and HIV prophylaxis emerge as prevention-focused alternatives to small-molecule regimens.
Oncology absorbs the dominant revenue share. Autoimmune disorders are climbing the fastest as interchangeability designations expand pharmacy substitution.
Delivery Mode:
Injectable formats retain manufacturing concentration among established biologics producers, while transdermal and oral platforms attract venture investment for patient adherence breakthroughs.
- Injectable:Intravenous and subcutaneous administration remains standard for monoclonal antibodies and fusion proteins. Prefilled syringe and autoinjector device compatibility shapes formulation development at Cambridge and Basel innovation clusters.
- Transdermal:Microneedle arrays and iontophoretic systems enable peptide delivery without first-pass metabolism. Development activity concentrates in Boston-area startups targeting diabetes and hormone replacement segments.
- Oral:Encapsulation and permeation enhancement technologies address small protein and peptide biobetters, though bioavailability constraints limit applicability.
- Inhalable:Dry powder and nebulized formulations serve pulmonary enzyme replacement and localized immunomodulation indications.
Injectable modes anchor current revenue. Transdermal platforms are gaining share fastest as microneedle manufacturing scales.
End User:
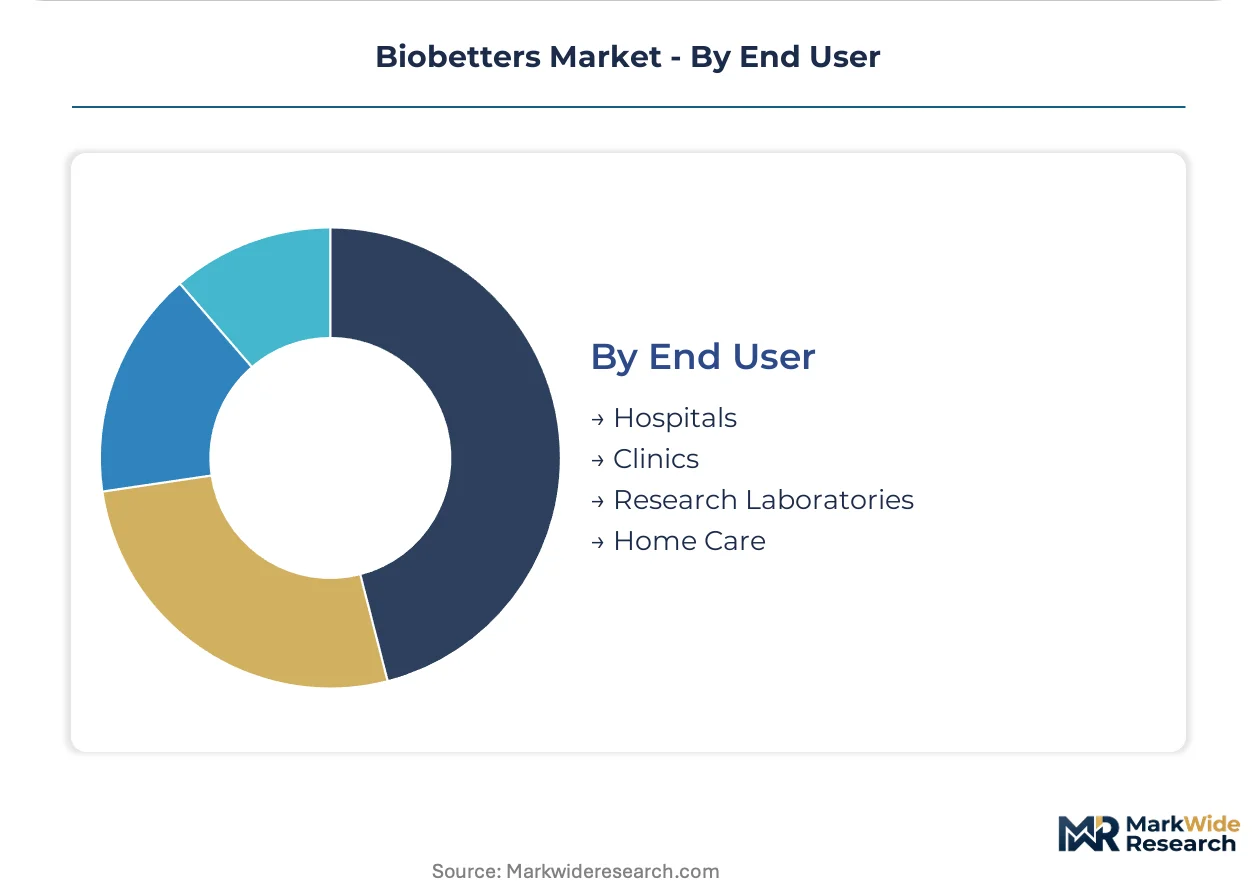
Hospital purchasing consolidation in the United States and Germany shifts volume toward centralized procurement, while home care channels expand in Japan's aging patient population.
- Hospitals:Integrated delivery networks and university medical centers command infusion-based biobetter volumes. Formulary committees in Texas and Florida health systems now mandate specific half-life extended products for oncology pathways.
- Home Care:Self-administered subcutaneous biobetters reduce clinic dependency for chronic disease patients. Japanese government reimbursement incentives accelerate home infusion nursing support in Tokyo and Osaka metropolitan areas.
- Clinics:Specialist outpatient settings manage rheumatology, endocrinology, and gastroenterology biobetter prescribing.
- Research Laboratories:Academic and contract research organizations utilize biobetters as reference standards and investigational comparators.
Hospitals command the established base. Home care channels are expanding most quickly as self-administration technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA's favorable pricing framework for next-generation biologics sustains developer margins in Japan while accelerating patient access. FDA's interchangeability guidelines and EMA's evolving biologics pathways reshape competitive entry conditions across developed markets. Demand concentrates in the United States, Germany, and Japan as these markets sustain premium reimbursement for half-life extended therapeutics.
United States
Integrated delivery networks in Texas and Florida consolidate purchasing authority for infused biologics into centralized pharmacy and therapeutics boards. FDA's biosimilar interchangeability guidelines enable pharmacy-level substitution without prescriber intervention, expanding patient access. Boston and San Diego anchor innovation clusters where site-specific conjugation technologies accelerate candidate selection.
Germany
Statutory reimbursement systems sustain premium positioning for clinical differentiation in rare disease glycoengineering applications. EMA's stringent comparability protocols for glycosylation pattern analysis extend preclinical timelines. Heidelberg's tertiary oncology centers prioritize biobetters enabling extended-interval dosing protocols.
Japan
Tokyo and Osaka hospital networks drive adoption of half-life extended therapeutics in aging patient populations. PMDA's favorable pricing framework accelerates patient access while sustaining developer margins. Government reimbursement incentives expand home infusion nursing support in metropolitan areas.
South Korea
Contract manufacturing capacity anchors export-oriented production for insulin variants and growth factors. The national pharmaceutical regulator harmonizes immunogenicity assessment standards with FDA and EMA convergence trends. Seoul-based biologics producers leverage captive platform technologies to serve Asia-Pacific and Western markets.
Switzerland
Basel's innovation clusters concentrate formulation development for prefilled syringe and autoinjector device compatibility. Swissmedic maintains distinct but converging standards for post-market surveillance requirements. The region's quality assurance systems support multi-site manufacturing consistency across European distribution networks.
Biobetters Market Key Industry Players
Player mix skews toward established biologics producers with captive manufacturing platforms and emerging specialists in site-specific conjugation technologies. The vendor base separates into scale-driven manufacturers, platform-technology licensors, and rare-disease-focused developers. Three archetypes dominate: integrated pharmaceutical conglomerates with decades of manufacturing scale, antibody-discovery platform specialists, and contract development organizations anchoring regional capacity. Competitive moves concentrate on strategic partnerships for technology access and geographic expansion of manufacturing footprints.
Within the integrated pharmaceutical tier, Amgen exemplifies manufacturing scale advantages across biobetter portfolios, while Regeneron Pharmaceuticals occupies a position defined by proprietary discovery platforms. Samsung Biologics anchors contract development capacity spanning Asia-Pacific and Western markets. These three entities represent distinct competitive vectors: manufacturing scale, platform technology, and regional capacity aggregation.
| Leading Market Players |
|---|
| Gilead Sciences |
| Alnylam Pharmaceuticals |
| Amgen |
| UCB |
| Argenx |
| Regeneron Pharmaceuticals |
| Chugai Pharmaceutical |
| Samsung Biologics |
| Vertex Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
PEGylated protein substitution for conventional biologics simultaneously shifts manufacturing gravity toward South Korean contract producers and compresses pricing premiums for half-life extension technologies. FDA interchangeability designations amplify this geographic reconfiguration by enabling pharmacy-level substitution that erodes originator pricing power.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate biobetter procurement between contract manufacturers and pharmaceutical sponsors. Three-tier pricing structure across premium glycoengineered variants, standard PEGylated formats, and economy biosimilar-adjacent products reflects analytical complexity and regulatory pathway differentiation. Pricing pressure stems from EMA's tightening comparability requirements that extend preclinical investment timelines. Hospital formulary committees exhibit highest price sensitivity, while rare disease specialists accept premium positioning for modified potency growth factors.
Supply Chain Analysis
United States, Germany, and South Korea anchor biobetter manufacturing through distinct specializations: Massachusetts and California concentrate Fc-engineering innovation, Heidelberg sustains tertiary oncology production, and Seoul anchors export-oriented insulin and growth factor supply. Chinese hamster ovary cell lines, specialized protein A chromatography resins, and PEGylation reagents constitute critical input dependencies. Single-source vulnerability concentrates in proprietary CHO cell line platforms held by established biologics producers. Distribution runs through cold-chain logistics networks serving hospital infusion centers and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biobetter markets increasingly reward service-attach revenue streams, with real-world evidence generation and post-market immunogenicity surveillance expanding faster than molecule licensing fees alone.
For Market Incumbents: Consolidate manufacturing scale advantages through captive CHO platform optimization and multi-site glycosylation harmonization. Samsung Biologics and Amgen demonstrate how regional capacity aggregation defends against emerging platform-technology specialists. EMA's evolving comparability protocols threaten margin compression for developers lacking integrated analytical capabilities.
For New Entrants and Emerging Players: FDA's biosimilar interchangeability fast-track offers entry acceleration for developers with advanced site-specific conjugation platforms. Transdermal microneedle delivery for diabetes biobetters represents the most penetrable white space, with Boston and Basel innovation clusters showing concentrated venture activity. Partner with established contract manufacturers to bypass capital-intensive cell line development barriers.
For Investors and Strategic Acquirers: FDA's interchangeability designation reshapes the acquisition landscape by elevating platform-technology specialists above commodity biosimilar developers. Long-term viability favors entities with orthogonal intellectual property in glycoengineering or half-life extension modalities. Watch PMDA pricing framework adjustments as the signal indicating Japan's sustained premium reimbursement appetite.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Multi-site CHO platform harmonization enables EMA comparability compliance across European distribution networks. |
| Regulatory Approval Pathway | FDA interchangeability designation unlocks pharmacy substitution without prescriber intervention in chronic disease segments. |
| Licensing Agreement | Site-specific conjugation technology access accelerates homogeneous antibody-drug conjugate development timelines. |
| Pipeline Diversification | Rare disease glycoengineering expansion captures Germany's statutory reimbursement premium for clinical differentiation. |
| Strategic Partnership | Real-world evidence collaborations with integrated delivery networks support accelerated label expansion opportunities. |
Research Approach
The analysis maps monoclonal antibody, insulin, growth factor, and enzyme biobetter segments, each validated through primary interviews with regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up molecule-level revenue modeling triangulates against top-down therapeutic category spending estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions include molecular platform, therapeutic application, administration route, and regional regulatory cluster. CAGRs derive from patent expiry timing, biosimilar entry probability, and reimbursement trajectory modeling. Forecast inputs incorporate PMDA pricing framework stability and FDA interchangeability designation velocity.
Decision-makers should treat outputs as directional under assumptions of sustained premium reimbursement in United States, Germany, and Japan; material deviation in interchangeability adoption or glycosylation comparability stringency would warrant model refresh. Recalibration cycles align with material shifts in regulatory pathway convergence and contract manufacturing capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Global Flu Vaccine Market