
 Insulin Syringes Market | 2026-2036
Insulin Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Syringes Market Outlook
REACH compliance is pivoting the cost-of-entry calculus for European market access, forcing manufacturers to revalidate material compositions and supply chain documentation. Becton Dickinson and Company leverages its captive polymer compounding capacity to sustain margin structures under these regulatory burdens. Hindustan Syringes & Medical Devices anchors South Asian cost positioning through integrated needle-drawing and sterilization operations. Ypsomed Holding AG differentiates via pen needle interoperability standards that navigate fragmented reimbursement systems across multiple geographies.
Insulin syringes are precision injection devices, typically comprising a graduated barrel, elastomer plunger seal, and attached hypodermic needle with bevel angles optimized for subcutaneous tissue penetration; most disposable variants utilize polypropylene barrels and stainless-steel needles with silicone lubrication to minimize injection force and patient trauma. Their primary commercial purpose is accurate, sterile delivery of measured insulin doses in ambulatory diabetes care settings. Disposable syringes dominate volume due to infection control protocols, while safety syringes command premium positioning as OSHA needlestick prevention mandates expand enforcement scope. Prefilled syringes occupy the fastest-growing structural slot, driven by biologic insulin analog formulations requiring precise dosing and reduced handling errors in hospital and home settings.
The FDA enforces sharps injury prevention through OSHA Bloodborne Pathogens Standard alignment, while the EMA's Medical Device Regulation tightens clinical evidence requirements for needle-based delivery systems. India's CDSCO and BIS jointly govern domestic syringe quality certification, with PLI scheme incentives accelerating local production scale for export competitiveness. Stakeholders must monitor evolving reimbursement parity between pen devices and conventional syringes, as payer formulary decisions will reshape volume allocation across delivery modalities.
Market Dynamics
REACH compliance is forcing European manufacturers to revalidate material compositions and supply chain documentation, restructuring cost-of-entry calculus for polymer sourcing and sterilization validation protocols.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard alignment:FDA enforcement of sharps injury prevention is accelerating safety-engineered syringe replacement cycles across US ambulatory care networks.
- India PLI scheme incentives:Domestic production scale expansion under CDSCO-BIS joint certification is compressing export lead times for South Asian manufacturers.
- Biologic insulin analog formulations:Precision dosing requirements for temperature-sensitive biologics are pulling prefilled syringe adoption in hospital and home settings.
Market Restraints
- Medical-grade polypropylene concentration:Barrel polymer supply tightness among specialized compounders is transmitting cost volatility to disposable syringe producers.
- EMA MDR clinical evidence requirements:Tighter documentation burdens for needle-based delivery systems are extending time-to-market for European product registrations.
- Pen device substitution:Reusable insulin pen systems are capturing dosing convenience preference among type 1 diabetes patients with pharmacy benefit coverage.
Strategic Opportunities
- Retail pharmacy channel expansion:Home-based diabetes management growth is opening volume deployment through India's government procurement programs and private pharmacy chains.
- Safety syringe premium positioning:OSHA needlestick prevention mandate expansion is creating pricing power for integrated needle-retraction designs in US occupational health settings.
- Silicone lubrication process optimization:Advanced coating technologies are reducing injection force variance and enabling patient trauma minimization claims for subcutaneous delivery.
Industry Challenges
- Sterilization validation timeline compression:Ethylene oxide and gamma sterilization protocol updates are requiring extended biocompatibility testing cycles before regulatory submission.
- Bevel angle standardization gaps:Interoperability friction between hypodermic needle geometries and emerging pen needle systems is complicating portfolio rationalization for multi-platform manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Syringes Market |
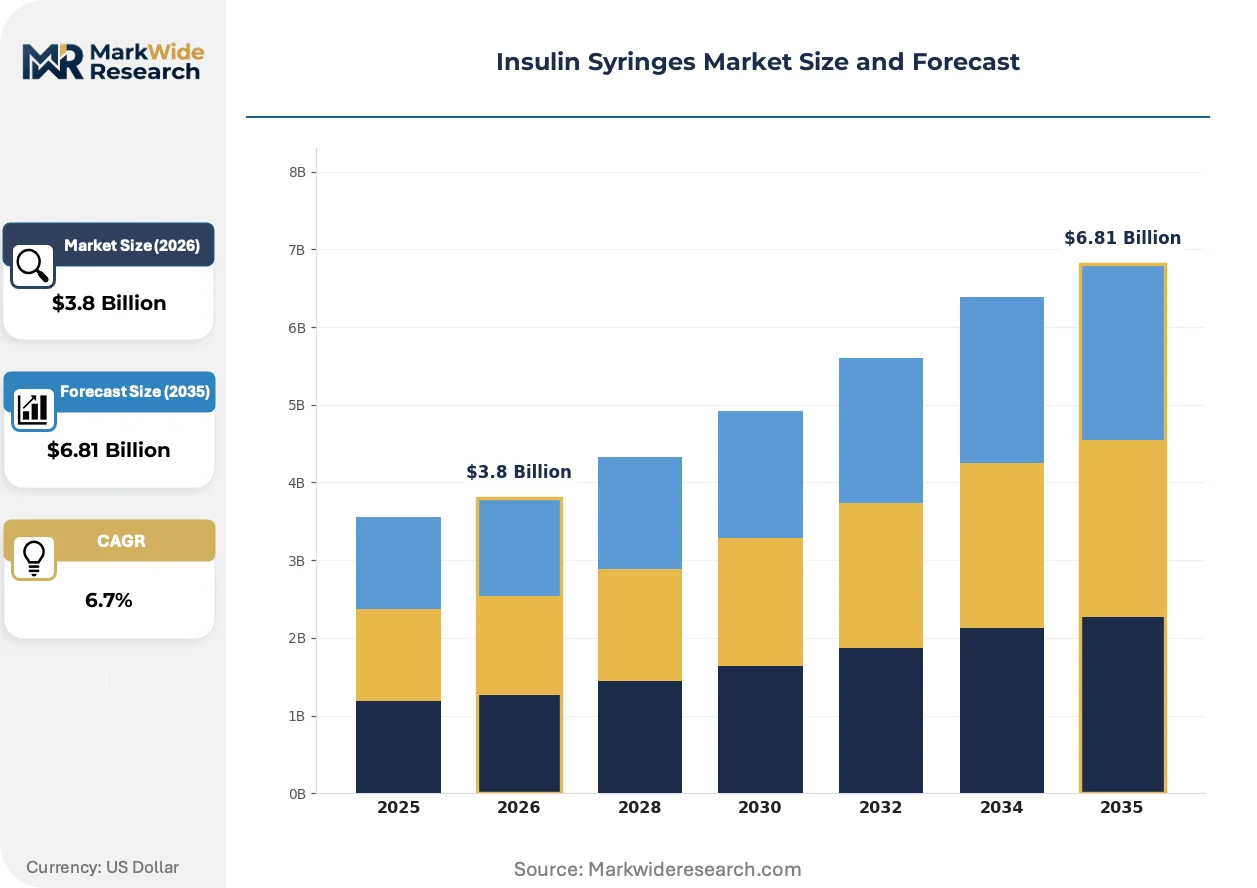
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
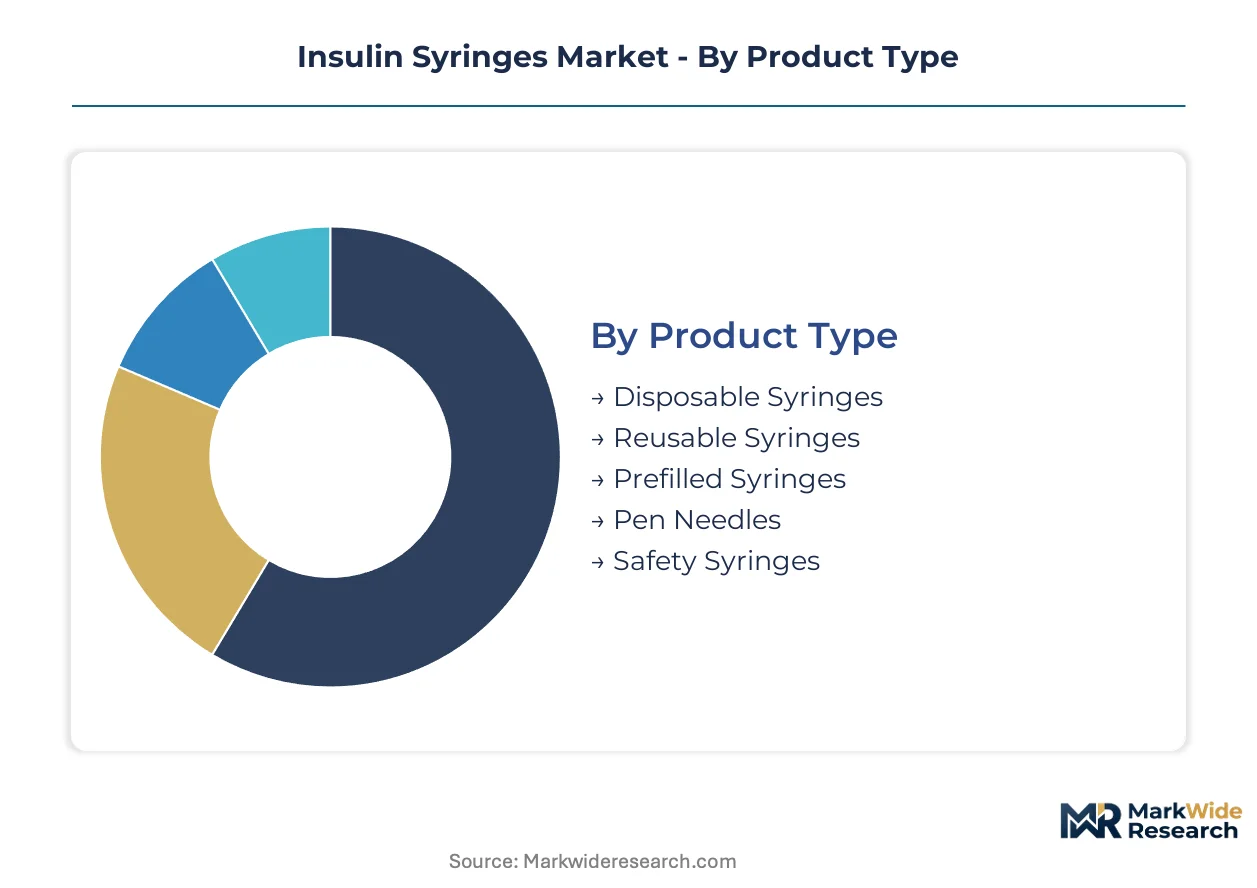
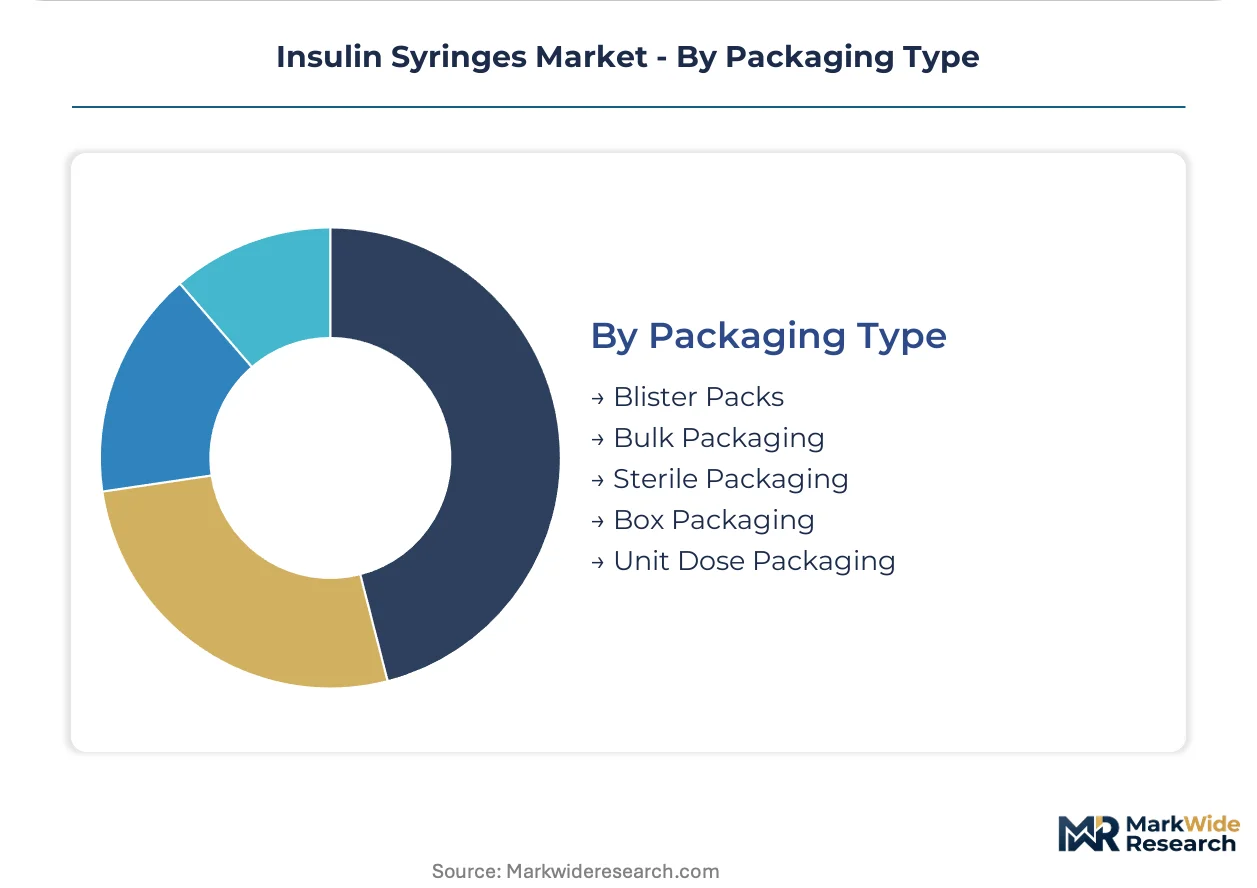
| Segmentation | Product Type: Disposable Syringes, Reusable Syringes, Prefilled Syringes, Pen Needles, Safety Syringes Application: Diabetes Management, Clinical Research, Veterinary Use, Hormone Therapy, Insulin Delivery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Diabetes Care Centers, Pharmacies Packaging Type: Blister Packs, Bulk Packaging, Sterile Packaging, Box Packaging, Unit Dose Packaging |
| Companies Covered | Hindustan Syringes & Medical Devices, B. Braun Melsungen AG, Becton Dickinson and Company, Owen Mumford, Ypsomed Holding AG, Nipro Corporation, Cardinal Health, UltiMed Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Syringes Market Strategic Shifts
Safety-engineered designs are integrating passive activation mechanisms that eliminate user-dependent needlestick protection, while polymer science advances and channel restructuring are compressing traditional procurement hierarchies.
Integrated needle-retraction systems are integrating spring-loaded barrel mechanisms that deploy automatically upon plunger completion, eliminating secondary handling steps. Hospital systems with occupational health liability exposure are specifying these designs in group purchasing organization contracts. The technology is integrating safety compliance into standard workflow without clinician training burden, displacing add-on safety devices that require separate activation.
REACH substance restriction updates are tightening permissible extractables thresholds for elastomer plunger seals and lubricant coatings used in European-market syringes. Manufacturers with captive polymer compounding operations are requalifying supply chains ahead of 2025 enforcement windows. Prefilled syringe segments with biologic drug co-development partnerships face accelerated reformulation timelines to maintain CE marking continuity.
Geriatric home-care patients are consolidating purchase decisions through retail pharmacy networks rather than durable medical equipment distributors, compressing traditional channel margins. India's domestic pharmacy chains with cold-chain capabilities are capturing insulin syringe volume previously routed through hospital discharge planning. This behavioral shift is most visible in Maharashtra and Karnataka states where government insurance portability enables retail substitution for chronic disease supplies.
Insulin Syringes Market Segmentation
Insulin syringe procurement patterns diverge sharply across delivery settings, with infection control protocols, reimbursement parity, and patient self-administration capabilities determining volume allocation. Manufacturers must align polymer sourcing and sterilization capacity to the technical specifications and regulatory burdens of each segment cluster.
Product Type:
Supply concentration tilts toward polymer compounding and needle-drawing operations that can absorb regulatory compliance costs across high-volume disposable output.
- Disposable Syringes:Polypropylene barrels with bonded stainless-steel needles and silicone lubrication dominate ambulatory care procurement. Hospital systems in the United States specify these for OSHA Bloodborne Pathogens Standard compliance, while India's retail pharmacy channels absorb volume through government insurance portability programs.
- Prefilled Syringes:Glass or cyclic olefin polymer barrels preloaded with biologic insulin analogs require cold-chain integrity and precise dosing mechanisms. Temperature-sensitive formulations are pulling adoption in Maharashtra and Karnataka states where diabetes care centers coordinate directly with pharmacy distribution.
- Safety Syringes:Integrated needle-retraction designs with passive activation mechanisms command premium positioning under expanding OSHA enforcement.
- Pen Needles:Threaded hub designs for reusable insulin pen systems capture dosing convenience preference among type 1 diabetes patients.
- Reusable Syringes:Metal or glass barrel constructions with detachable needles persist in limited veterinary and research applications.
Disposable Syringes absorb the bulk of installed capacity; Prefilled Syringes are expanding most quickly.
Application:
Cost tier differentiation separates acute care protocols with stringent sterility requirements from chronic disease management with price-sensitive repeat purchasing.
- Diabetes Management:Subcutaneous insulin delivery for type 1 and type 2 patients drives the preponderance of volume, with geriatric home-care patients consolidating purchases through retail pharmacy networks rather than durable medical equipment distributors.
- Clinical Research:Standardized dosing precision and batch traceability requirements govern investigational drug trials, with CDSCO-BIS joint certification enabling Indian manufacturers to supply contract research organizations.
- Insulin Delivery:Precision injection protocols in hospital and ambulatory settings emphasize bevel angle optimization and injection force consistency.
- Hormone Therapy:Off-label growth hormone and fertility treatment applications utilize similar subcutaneous delivery mechanisms with distinct dosing regimens.
- Veterinary Use:Companion animal diabetes care and livestock reproductive health applications operate outside human pharmaceutical reimbursement systems.
Diabetes Management commands the dominant revenue share; Clinical Research is gaining share fastest.
End User:
Volume concentration follows patient flow patterns, with procurement authority shifting from centralized hospital purchasing to decentralized pharmacy networks as home-based management expands.
- Hospitals:Group purchasing organization contracts specify safety-engineered designs for occupational health liability protection, with integrated needle-retraction systems displacing add-on safety devices.
- Pharmacies:India's domestic pharmacy chains with cold-chain capabilities are capturing insulin syringe volume previously routed through hospital discharge planning, particularly in government insurance portability states.
- Diabetes Care Centers:Specialized facilities coordinate patient education and supply distribution for complex insulin regimens.
- Clinics:Outpatient settings balance infection control protocols with cost containment pressures.
- Ambulatory Surgical Centers:Same-day procedure facilities prioritize disposable designs for throughput efficiency.
Pharmacies are absorbing the fastest volume growth; Hospitals retain the largest installed base.
Packaging Type:
Margin structure varies with sterilization validation burden and distribution channel requirements, from bulk institutional supply to unit-dose retail presentation.
- Sterile Packaging:Individual peel-pouch configurations with ethylene oxide or gamma sterilization validation support operating room and infusion center protocols.
- Blister Packs:Thermoformed plastic cavities with foil backing enable retail shelf presentation and patient portability for home-based diabetes management.
- Unit Dose Packaging:Single-syringe configurations with lot number traceability serve clinical research and hospital formulary requirements.
- Bulk Packaging:Multi-unit cartons for institutional procurement compress per-unit logistics costs.
- Box Packaging:Intermediate configurations balance inventory efficiency with dispensing convenience.
Sterile Packaging carries the highest compliance overhead; Blister Packs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones and production-linked incentive corridors are concentrating insulin syringe manufacturing capacity. Domestic manufacturers leverage integrated sterilization and polymer compounding operations to serve export markets. Regulatory harmonization across US, European, and Indian standards is reshaping facility certification requirements.
United States
Hospital group purchasing organizations specify safety-engineered syringes for OSHA Bloodborne Pathogens Standard compliance. FDA enforcement of sharps injury prevention mandates accelerates replacement cycles across ambulatory care networks. New Jersey and North Carolina manufacturing clusters host integrated needle-retraction system production for occupational health liability protection.
Germany
REACH substance restrictions tighten permissible extractables thresholds for elastomer plunger seals and lubricant coatings. EMA Medical Device Regulation extends time-to-market for needle-based delivery system registrations. Baden-Württemberg polymer compounding facilities revalidate supply chains ahead of enforcement windows to maintain CE marking continuity.
India
CDSCO-BIS joint certification enables domestic manufacturers to supply contract research organizations and government procurement programs. PLI scheme incentives compress export lead times for South Asian producers. Maharashtra and Karnataka pharmacy chains with cold-chain capabilities capture insulin syringe volume previously routed through hospital discharge planning.
Japan
PMDA clinical evidence requirements govern biologic insulin analog delivery system approvals. METI standards coordination supports pen needle interoperability for fragmented reimbursement navigation. Osaka and Tokyo medical device clusters specialize in precision dosing mechanisms for temperature-sensitive formulations.
Switzerland
Swissmedic quality certification supports prefilled syringe co-development partnerships with biologic drug manufacturers. Alpine pharmaceutical packaging specialists maintain cold-chain integrity for temperature-sensitive insulin formulations. Basel-area polymer science facilities optimize silicone lubrication processes for injection force consistency.
Insulin Syringes Market Competitive Environment
North American producers anchor one tier; European specialists hold differentiated positioning through regulatory compliance capabilities. The vendor base separates across integrated safety-engineered system manufacturers, polymer compounding-integrated fabricators, and pen needle interoperability specialists. Three archetypes dominate: captive polymer producers absorbing REACH compliance costs, integrated sterilization operators serving government procurement, and biologic drug co-development partners. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure polymer supply and sterilization validation timelines.
Among the named participants, Hindustan Syringes & Medical Devices exemplifies integrated sterilization and needle-drawing operations for South Asian cost positioning. Becton Dickinson and Company occupies a position representing captive polymer compounding capacity sustaining margin structures under regulatory burdens. Ypsomed Holding AG sits within the pen needle interoperability tier, navigating fragmented reimbursement systems across multiple geographies.
| Leading Market Players |
|---|
| Hindustan Syringes & Medical Devices |
| B. Braun Melsungen AG |
| Becton Dickinson and Company |
| Owen Mumford |
| Ypsomed Holding AG |
| Nipro Corporation |
| Cardinal Health |
| UltiMed Inc. |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH substance restriction enforcement gates qualified supply access for European-market syringes and separates premium-tier pricing from commodity positioning. Manufacturers lacking captive polymer compounding capacity face margin compression as revalidation costs for elastomer seals and silicone lubricants transmit through procurement hierarchies.
Pricing Analysis
Lead-time-driven pricing stratification rewards domestic Indian manufacturers with government procurement contracts while penalizing spot-market inventory from non-integrated suppliers. Three-tier pricing structure across premium safety-engineered, standard disposable, and economy bulk configurations reflects certification grade differentiation and volume scale. Pricing pressure stems from pen device substitution among type 1 diabetes patients with pharmacy benefit coverage. Hospital group purchasing organizations exhibit lowest price sensitivity due to OSHA-mandated safety specifications; retail pharmacy channels in Maharashtra and Karnataka states absorb highest price elasticity.
Supply Chain Analysis
Freight cost volatility from specialized medical-grade polypropylene compounders in Germany, the United States, and Japan transmits cost instability to barrel producers without backward integration. Raw material dependencies center on polypropylene resin, stainless-steel needle stock, and medical-grade silicone lubricants. Single-source vulnerability concentrates in European elastomer seal suppliers facing REACH requalification timelines. Distribution runs through hospital group purchasing organizations in North America, government procurement programs in India, and retail pharmacy chains with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated needle-retraction mechanisms are displacing add-on safety devices across US hospital systems, compressing legacy disposable syringe margins and forcing technology-transition investment decisions.
For Market Incumbents: To counter pen device substitution among type 1 diabetes patients with comprehensive pharmacy coverage, Becton Dickinson and Company should deepen backward integration into polymer compounding to absorb REACH compliance costs, while Hindustan Syringes & Medical Devices expands sterilization capacity under CDSCO-BIS joint certification to defend government procurement positioning. For New Entrants and Emerging Players: Launch via retail pharmacy channel partnerships in Maharashtra and Karnataka states where government insurance portability enables cold-chain substitution for hospital discharge planning. Target prefilled syringe co-development with biologic insulin analog manufacturers requiring precise dosing mechanisms. Penetrate through pen needle interoperability standards that navigate fragmented reimbursement systems across multiple geographies. For Investors and Strategic Acquirers: OSHA enforcement expansion for sharps injury prevention is the leading indicator that integrated safety-engineered designs will command sustained pricing power over the next decade. Acquisition targets should display captive polymer compounding operations or sterilization validation capabilities under FDA-EMA-CDSCO harmonized standards. Monitor PLI scheme incentive allocations as volume inflection signal for South Asian manufacturing scale.| Strategic Initiative | Industry Significance |
|---|---|
| Safety Syringe Platform Standardization | OSHA Bloodborne Pathogens Standard alignment accelerates replacement cycles across ambulatory care networks. |
| Backward Integration into Polymer Compounding | REACH substance restriction compliance absorbs margin pressure from elastomer plunger seal revalidation. |
| Prefilled Syringe Co-Development Partnership | Biologic insulin analog formulations require cold-chain integrity and precise dosing mechanisms. |
| Retail Pharmacy Channel Expansion | Government insurance portability in Maharashtra and Karnataka enables volume capture from hospital discharge planning. |
| CDSCO-BIS Joint Certification Investment | PLI scheme incentives compress export lead times for contract research organization supply. |
Study Parameters
FDA 510(k) filings, EMA Medical Device Regulation submissions, and CDSCO manufacturing facility inspections formed the secondary backbone for regulatory pathway validation. Primary interviews with hospital GPO contracts managers, retail pharmacy procurement leads, biomedical engineers, and biologic drug manufacturing executives combined with secondary sources to enable bottom-up and top-down triangulation across the analysis window.
Historical trendline analysis of disposable syringe shipment volumes, prefilled syringe adoption curves, and safety-engineered replacement cycles established baseline growth patterns. Segmentation modeling across product type, application, end user, and packaging format dimensions generated volume and value outputs. CAGRs were derived from regression analysis of polymer supply constraints, reimbursement parity shifts, and regulatory enforcement intensity.
OSHA mandate expansion timelines, REACH substance restriction enforcement windows, and PLI scheme incentive allocation delays are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect assumptions about regulatory harmonization continuity and polymer supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Bioactive Protein and Peptides Market