
 Discovery Bioanalysis Market | 2026-2036
Discovery Bioanalysis Market Size, Share, and Industry Trends Forecast 2026-2036
Discovery Bioanalysis Market Analytics
Platform-as-a-service bioanalytical offerings is restructuring how discovery programs procure analytical capabilities, shifting capital expenditure into operational spending models. Charles River Laboratories leverages its integrated drug discovery infrastructure to anchor large-molecule bioanalysis workflows across North America and Europe. WuXi AppTec sustains cost-competitive operations through extensive laboratory networks in China and the United States. Eurofins Scientific differentiates with specialized immunogenicity testing capabilities that support complex biologic development pipelines.
Discovery bioanalysis encompasses quantitative and qualitative analytical methods applied to drug candidates during preclinical and early clinical phases, utilizing techniques such as ligand-binding assays with sensitivity thresholds reaching picogram-per-milliliter detection and mass spectrometry platforms operating at high-resolution accurate-mass settings. Its primary purpose is to generate pharmacokinetic, toxicokinetic, and biomarker data that enables go-no-go decisions on compound advancement. Mass spectrometry-based workflows command premium pricing due to their universality across small-molecule and biologic modalities, while ELISA retains dominance in immunogenicity assessment where antibody specificity determines regulatory acceptability. High-throughput screening configurations within automated systems are expanding fastest as pharmaceutical sponsors compress discovery timelines.
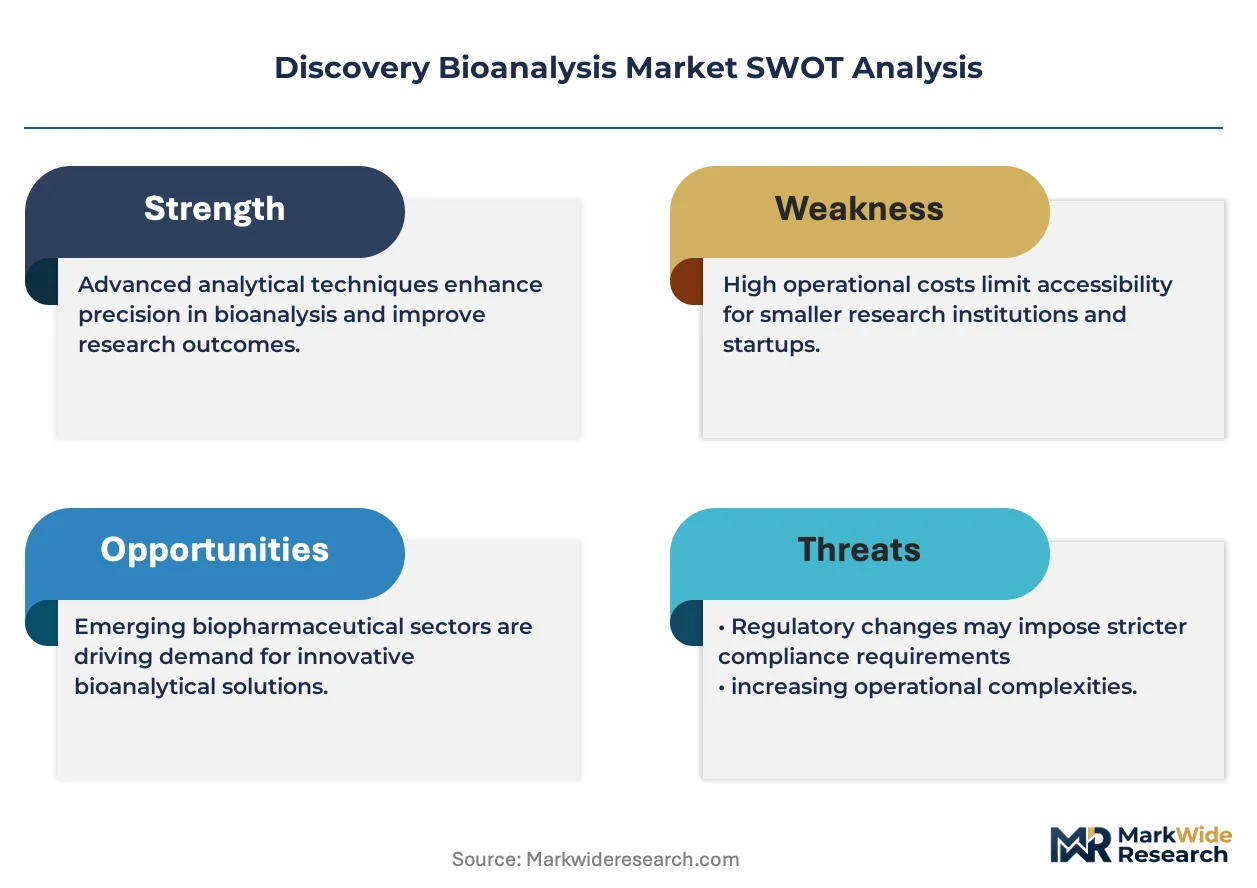
FDA bioanalytical method validation guidelines, EMA immunogenicity guidance, and OECD Good Laboratory Practice standards collectively dictate data package requirements that determine regulatory submission acceptability across jurisdictions. These frameworks elevate compliance costs for service providers while simultaneously creating barriers that protect established operators with mature quality systems. Stakeholders must monitor evolving regulatory expectations around cell and gene therapy bioanalytical strategies, as these modalities lack standardized guidance and present the highest technical complexity in method development.
Market Dynamics
Pharmaceutical sponsors are compressing preclinical timelines while simultaneously demanding more complex bioanalytical characterization for novel modalities, forcing contract research organizations to reconfigure capacity investments around speed-to-data rather than throughput volume alone.
Growth Catalysts
- Platform-as-a-service adoption:Sponsors are converting fixed capital expenditures into operational spending models, accelerating procurement cycles for bioanalytical capabilities without long-term infrastructure commitments.
- FDA bioanalytical method validation guidelines:Evolving compliance requirements for pharmacokinetic studies are expanding the addressable market for specialized method development services across small-molecule and biologic pipelines.
- Cell and gene therapy pipelines:Complex biologic modalities lacking standardized bioanalytical frameworks are creating demand for bespoke assay development that incumbent platforms cannot fulfill.
Market Restraints
- Specialized talent scarcity:Method development for high-resolution accurate-mass mass spectrometry requires hybrid skill sets combining analytical chemistry and biologic knowledge that training pipelines have not scaled.
- Reference material supply concentration:Certified reference standards for novel biologic modalities originate from a limited base of suppliers, creating single-source vulnerabilities for validation packages.
- OECD Good Laboratory Practice compliance costs:Data integrity and audit trail requirements for regulatory submission packages elevate fixed operational costs that disadvantage smaller service providers.
Strategic Opportunities
- India's contract research expansion:CDSCO-aligned quality systems and cost-competitive scientific talent are attracting bioanalytical outsourcing for early-phase pharmacokinetic studies previously concentrated in Western markets.
- High-throughput screening automation:Integration of robotic liquid handling with mass spectrometry platforms is compressing sample-to-data intervals for discovery-stage decision support.
- EMA immunogenicity guidance evolution:Anticipated updates to biologic safety assessment frameworks will expand method validation requirements for anti-drug antibody detection.
Industry Challenges
- Ligand-binding assay transfer complexity:Method migration between development and regulated bioanalysis phases requires extensive revalidation that delays program timelines and consumes technical resources.
- Legacy data system integration:Sponsor electronic laboratory notebooks and service provider laboratory information management systems often lack interoperability, forcing manual data reconciliation that introduces compliance risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Discovery Bioanalysis Market |
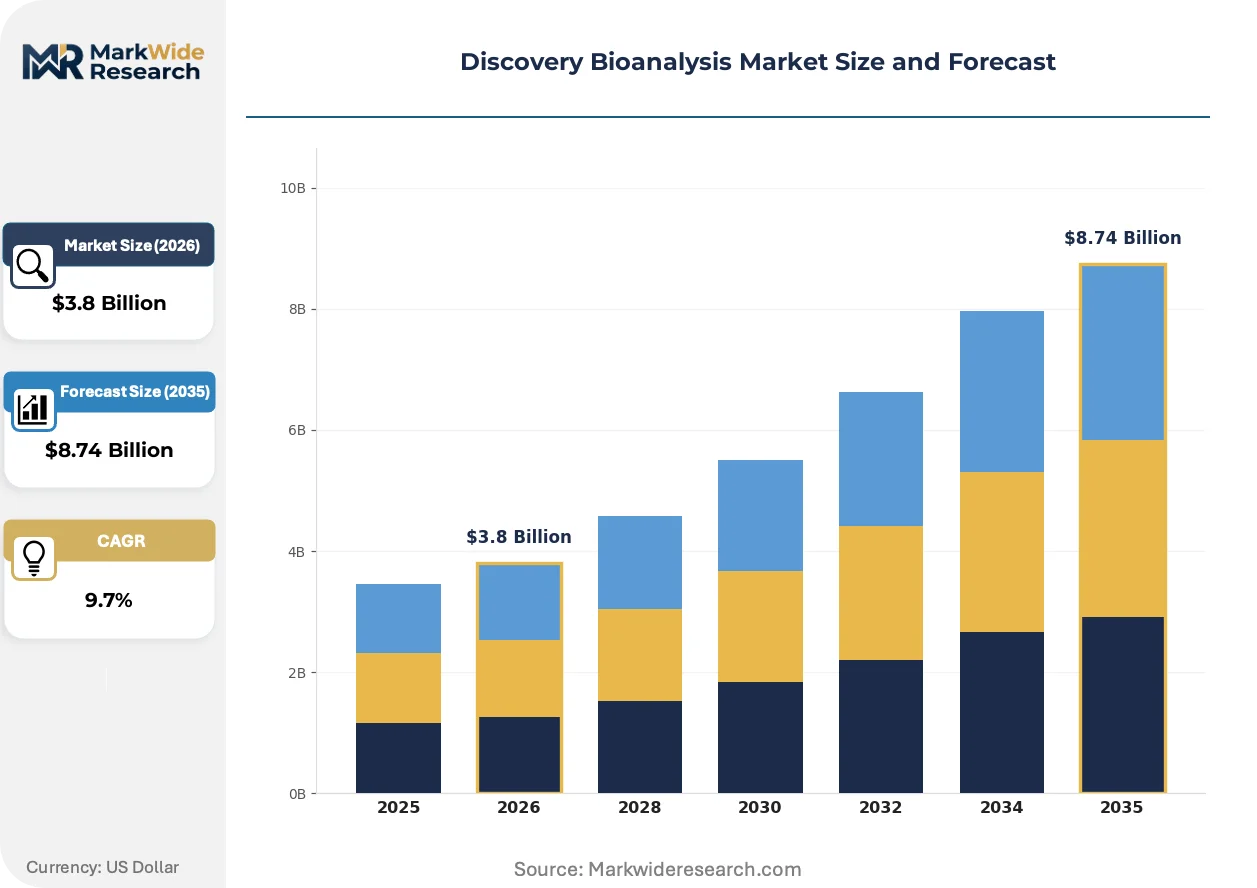
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Mass Spectrometry, Chromatography, Western Blotting Application: Pharmacokinetics, Toxicology, Biomarker Discovery, Drug Development End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations Technology: High-Throughput Screening, Label-Free Detection, Microfluidics, Automated Systems |
| Companies Covered | WuXi AppTec, Charles River Laboratories, Eurofins Scientific, ICON plc, Labcorp, SGS SA, BioAgilytix Labs, Intertek Group, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Discovery Bioanalysis Market Evolving Landscape
Automation architectures and regulatory guidance evolution are converging to redefine how bioanalytical capabilities are procured, delivered, and validated across the drug development continuum.
Microflow liquid chromatography coupled to mass spectrometry is decentralizing sample preparation workflows previously confined to centralized high-capacity facilities. Mid-tier contract research organizations are adopting these platforms to compete on turnaround time rather than scale. The technology is decentralizing analytical capacity toward distributed laboratory networks that reduce sample logistics burdens for sponsors with geographically dispersed research sites.
EMA immunogenicity guidance revisions are elevating requirements for anti-drug antibody assay sensitivity and drug tolerance. European biologic developers are revalidating existing methods or outsourcing to specialists with validated platform technologies. Cell and gene therapy developers in Switzerland and the United Kingdom are most affected, accelerating partnerships with immunogenicity-focused service providers ahead of formal guidance finalization.
Pharmaceutical procurement functions are unbundling discovery bioanalysis from integrated drug discovery contracts. Large sponsors are establishing preferred provider panels for specific modalities rather than single-source relationships. This pattern is most visible among Boston-Cambridge cluster biotechnology companies seeking competitive bidding for pharmacokinetic study execution.
Discovery Bioanalysis Market Segmentation
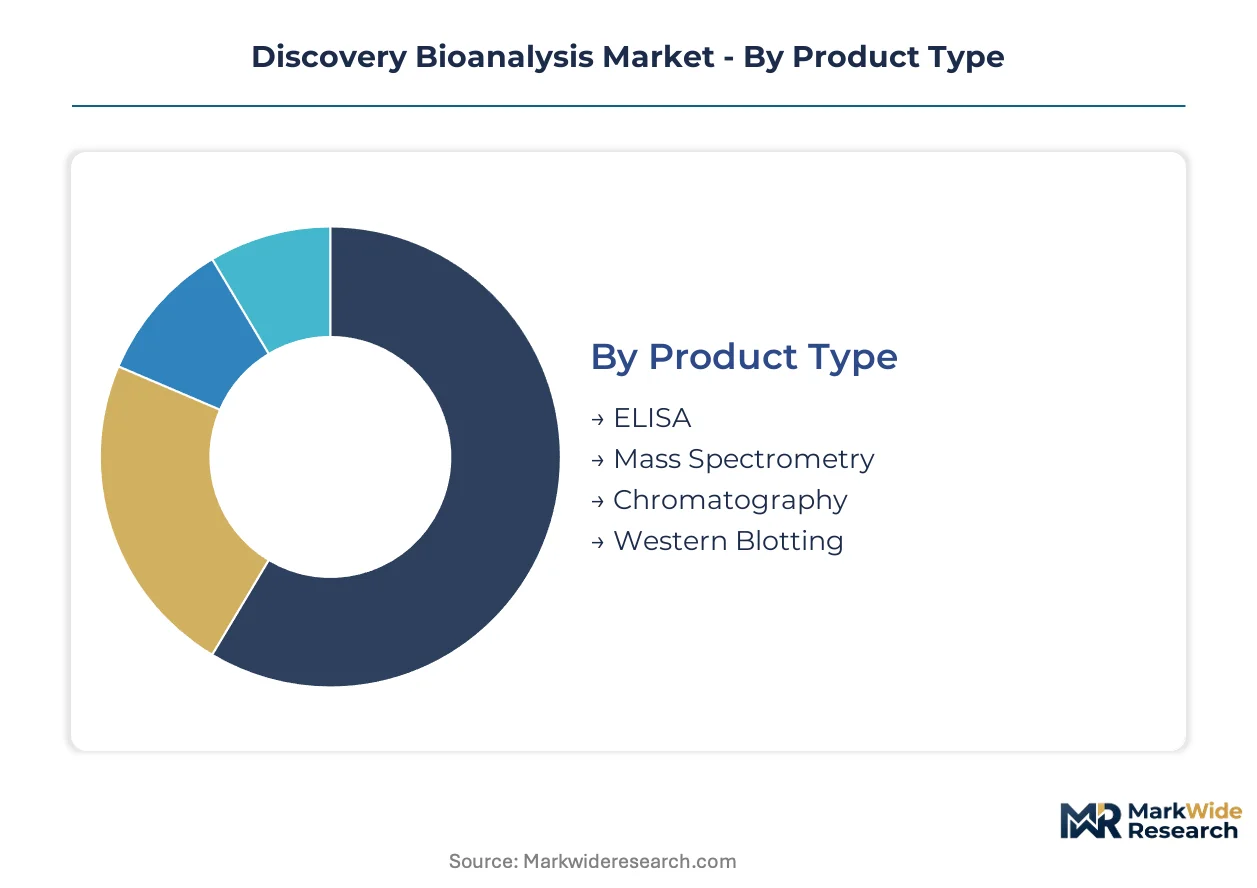
Segmentation in discovery bioanalysis reveals how capital allocation and technical specialization determine competitive positioning across service providers and technology vendors. Each dimension—product type, application, end user, and technology—carries distinct margin profiles and capacity requirements that shape procurement decisions.
Product Type:
Capital intensity varies sharply across analytical platforms, with mass spectrometry requiring seven-figure instrument investments versus lower-barrier immunoassay infrastructure.
- Mass Spectrometry:High-resolution accurate-mass platforms operate at sub-parts-per-billion detection thresholds for small-molecule quantification. Demand concentrates among Boston-Cambridge biotechnology sponsors developing complex biologics, where universal applicability across chemical classes justifies premium service pricing despite extended method development timelines.
- ELISA:Enzyme-linked immunosorbent assays dominate immunogenicity assessment through antibody-antigen specificity with picogram-per-milliliter sensitivity. Pharmaceutical sponsors in the United States outsource anti-drug antibody detection to specialists with validated platform technologies, driven by FDA bioanalytical method validation guidelines that elevate documentation requirements.
- Chromatography:Liquid and gas chromatography systems separate complex biological matrices prior to detection, forming the analytical backbone for pharmacokinetic studies across small-molecule pipelines.
- Western Blotting:Protein detection methodology serves qualitative biomarker verification with lower throughput but essential specificity for target engagement confirmation.
Most installed capacity flows through Mass Spectrometry. Expansion is steepest in ELISA as immunogenicity testing demands accelerate for biologic pipelines.
Application:
Revenue concentration tracks pharmaceutical sponsor decision points, with pharmacokinetic studies commanding the largest contract values due to regulatory submission requirements.
- Pharmacokinetics:Quantitative determination of drug concentration-time profiles enables dose selection and safety margin establishment. United States-based contract research organizations capture the majority of outsourcing as FDA bioanalytical method validation guidelines reshape compliance requirements for IND-enabling studies.
- Biomarker Discovery:Exploratory and validated biomarker quantification supports patient stratification and mechanism-of-action understanding. Academic institutions in Switzerland and the United Kingdom drive method innovation for cell and gene therapy applications where standardized frameworks remain under development.
- Toxicology:Toxicokinetic assessment establishes exposure-safety relationships for regulatory risk evaluation across preclinical species.
- Drug Development:Integrated analytical support spans lead optimization through candidate nomination, with timing pressures compressing study execution windows.
Pharmacokinetics anchors current revenue. Biomarker Discovery is climbing the fastest as precision medicine pipelines expand.
End User:
Procurement sophistication separates large pharmaceutical sponsors with dedicated outsourcing functions from emerging biotechnology companies seeking flexible capacity arrangements.
- Pharmaceutical Companies:Large sponsors maintain internal bioanalytical capabilities for early discovery while outsourcing regulated studies to contract research organizations with established quality systems. Platform-as-a-service adoption is converting fixed capital expenditures into operational spending models, accelerating procurement cycles without long-term infrastructure commitments.
- Contract Research Organizations:Service providers themselves constitute a demand segment as tier-one operators subcontract specialized assays or overflow capacity to mid-tier partners with complementary geographic presence or modality expertise.
- Biotechnology Firms:Venture-backed companies in the Boston-Cambridge cluster unbundle discovery bioanalysis from integrated drug discovery contracts, establishing preferred provider panels for competitive bidding.
- Academic Institutions:University laboratories contribute method innovation and reference standard development, though commercial scale-up typically transfers to contract research organizations.
Pharmaceutical Companies deploy the most capital. Biotechnology Firms are gaining share fastest through outsourcing expansion.
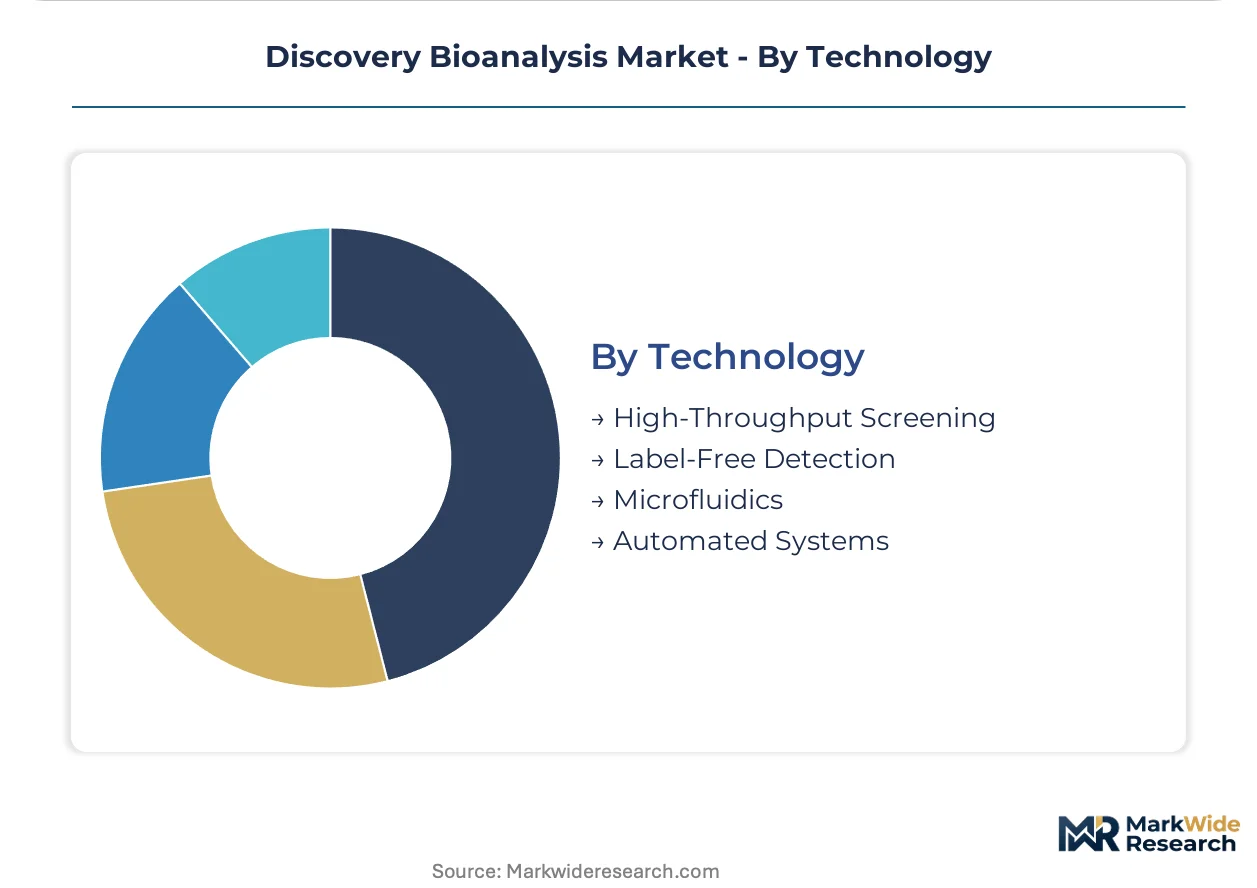
Technology:
Automation intensity determines labor cost exposure and turnaround time competitiveness across service provider business models.
- High-Throughput Screening:Robotic liquid handling integrated with mass spectrometry platforms compresses sample-to-data intervals for discovery-stage decision support. Mid-tier contract research organizations in India are adopting these configurations to compete on speed rather than scale, attracting early-phase pharmacokinetic studies previously concentrated in Western markets.
- Automated Systems:End-to-end workflow automation reduces manual intervention in sample preparation, analysis, and data reporting, addressing data integrity requirements under OECD Good Laboratory Practice standards.
- Label-Free Detection:Surface plasmon resonance and bio-layer interferometry enable real-time binding kinetics without reporter molecule requirements.
- Microfluidics:Microflow liquid chromatography decentralizes sample preparation toward distributed laboratory networks, reducing logistics burdens for sponsors with geographically dispersed research sites.
Automated Systems represent the largest installed base. High-Throughput Screening shows the steepest expansion trajectory as timeline compression intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium pricing for discovery bioanalysis services, while China competes through cost-efficient capacity networks that attract early-phase pharmacokinetic outsourcing from Western sponsors.
United States
FDA bioanalytical method validation guidelines drive compliance-intensive procurement decisions among pharmaceutical sponsors. The agency's evolving expectations for pharmacokinetic study documentation expand addressable demand for specialized method development services. Boston-Cambridge biotechnology cluster firms unbundle discovery bioanalysis from integrated contracts, establishing competitive bidding panels for IND-enabling studies.
Germany
EMA immunogenicity guidance revisions elevate anti-drug antibody assay requirements for biologic developers. The country's national pharmaceutical regulator enforces OECD Good Laboratory Practice standards that protect established operators with mature quality systems. Frankfurt and Munich host contract research organizations specializing in high-resolution accurate-mass mass spectrometry for complex biologic characterization.
Switzerland
Cell and gene therapy pipelines concentrate demand for bespoke bioanalytical strategies lacking standardized frameworks. Swissmedic oversight of advanced therapy medicinal products shapes method validation expectations for novel modalities. Basel and Zurich biotech clusters accelerate partnerships with immunogenicity-focused service providers ahead of formal EMA guidance finalization.
China
NMPA alignment with international bioanalytical standards expands domestic contract research organization capabilities for global sponsor acceptance. The national medical products administration's evolving pharmacokinetic study requirements reshape compliance investments. Shanghai and Suzhou laboratory networks sustain cost-competitive operations through extensive automation and scientific talent scale.
India
CDSCO-aligned quality systems attract bioanalytical outsourcing for early-phase pharmacokinetic studies previously concentrated in Western markets. The central drugs standard control organization's pharmacovigilance framework elevates data integrity expectations for regulatory submission packages. Hyderabad and Bengaluru service providers adopt high-throughput screening configurations to compete on turnaround time rather than scale alone.
Discovery Bioanalysis Market Competitive Landscape
Top-tier vendors anchor integrated drug discovery infrastructure, while mid-tier specialists compete through modality-specific expertise or geographic cost advantages. The vendor base stratifies across three tiers: global full-service organizations with multi-continent laboratory networks, regional specialists with validated platform technologies, and emerging entrants automating high-throughput workflows. Strategic archetypes include integrated discovery-to-GLP providers, immunogenicity-focused boutiques, and platform-as-a-service enablers. Dominant competitive moves encompass M&A for geographic expansion and strategic partnerships for cell and gene therapy capability gaps.
Within the integrated infrastructure tier, Charles River Laboratories exemplifies North American and European anchor positioning through captive laboratory networks. WuXi AppTec occupies a cost-competitive archetype spanning China and United States operations. Eurofins Scientific represents the specialized immunogenicity testing vector that complex biologic developers prioritize for anti-drug antibody method validation.
| Leading Market Players |
|---|
| WuXi AppTec |
| Charles River Laboratories |
| Eurofins Scientific |
| ICON plc |
| Labcorp |
| SGS SA |
| BioAgilytix Labs |
| Intertek Group |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
Microflow liquid chromatography decentralization compresses sample preparation costs while redistributing analytical capacity across distributed laboratory networks, simultaneously lowering per-test economics and fragmenting supply concentration away from centralized high-capacity facilities.
Pricing Analysis
Capacity additions in India are reshaping price floors for early-phase pharmacokinetic studies, forcing mid-tier Western providers toward premium positioning. Project-based pricing dominates, with differentiation driven by FDA compliance tier and automation intensity. Cost compression in standard-tier ELISA services is intensifying because Hyderabad and Bengaluru laboratories compete on turnaround time. Biotechnology firms in the Boston-Cambridge cluster show highest price sensitivity, while large pharmaceutical sponsors prioritize quality system maturity over unit cost.
Supply Chain Analysis
Freight costs for temperature-sensitive reference materials elevate total cost of ownership for immunogenicity assay validation packages. Supply concentrates in the United States, Germany, and China for high-resolution accurate-mass mass spectrometry platforms. Certified reference standards for novel biologic modalities draw from a limited supplier base concentrated in Switzerland and the United Kingdom. Single-source vulnerability for cell and gene therapy reference materials creates structural risk. Distribution runs through direct contractual relationships between sponsors and contract research organizations with validated platform technologies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-as-a-service adoption converts fixed capital expenditures into operational spending models, expanding margin capture for providers with automated high-throughput configurations while compressing returns for asset-heavy incumbents.
For Market Incumbents: Anticipate margin pressure from Indian high-throughput screening automation by accelerating microflow liquid chromatography deployment across European laboratory networks. Defend positioning through OECD Good Laboratory Practice certification investments that create compliance barriers for emerging entrants. Prioritize cell and gene therapy method development capabilities ahead of EMA immunogenicity guidance finalization.
For New Entrants and Emerging Players: CDSCO-aligned quality systems in India open a window for cost-competitive pharmacokinetic study execution previously concentrated in Western markets. Target early-phase outsourcing from Boston-Cambridge biotechnology firms seeking competitive bidding panels. Penetrate through high-throughput screening automation that compresses sample-to-data intervals below incumbent turnaround benchmarks.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier contract research organizations with validated immunogenicity platforms but limited geographic reach. Long-term viability centers on cell and gene therapy bioanalytical capabilities where standardized frameworks remain under development. Monitor EMA immunogenicity guidance revision timing as inflection indicator for anti-drug antibody assay demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Throughput Screening Automation | Robotic liquid handling integration compresses discovery-stage decision timelines for Boston-Cambridge sponsors. |
| Cell and Gene Therapy Capability Buildout | Bespoke assay development for advanced therapy medicinal products addresses Swissmedic validation expectations. |
| Microflow Liquid Chromatography Deployment | Distributed laboratory networks reduce sample logistics burdens for geographically dispersed research sites. |
| CDSCO-Aligned Quality System Investment | Indian regulatory compliance attracts early-phase pharmacokinetic outsourcing from Western pharmaceutical sponsors. |
| Immunogenicity Platform Partnership | Anti-drug antibody method validation expertise supports EMA guidance-aligned biologic safety assessment. |
Research Methodology
Bottom-up biotechnology firm procurement modeling reconciled against top-down contract research organization capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, bioanalytical laboratory directors, and CRO procurement officers combined with secondary validation against FDA bioanalytical method validation guideline documents, EMA immunogenicity guidance publications, ClinicalTrials.gov protocol registries, and OECD Good Laboratory Practice inspection databases. Triangulation across sponsor-reported outsourcing expenditures and service provider disclosed capacity metrics ensures dimensional consistency.
Input-output matrices connect analytical platform installations, scientific headcount, and automation intensity to pharmacokinetic study throughput estimates across the projection horizon. Segmentation dimensions encompass product type, application, end user, and technology, with regional regulatory cluster and modality complexity as cross-cutting variables. CAGRs derive from compound growth trajectory fitting against historical outsourcing pattern analysis. Forecast inputs include pharmaceutical sponsor pipeline composition by modality and FDA IND submission volume trends.
Revisions become necessary when EMA immunogenicity guidance finalization timelines shift, cell and gene therapy reference material supply disruptions materialize, or NMPA bioanalytical standard alignment accelerates. Forecasts reflect documented assumptions regarding regulatory evolution pace and sponsor outsourcing propensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Global Tick-Borne Encephalitis Inactivated Vaccine Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market