
 North America Contraceptives Market | 2026-2036
North America Contraceptives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Contraceptives Market Analytics
Specialized reproductive health nurse practitioners are rotating into ambulatory care settings across the United States, expanding clinic capacity for intrauterine device insertion and contraceptive counseling. Bayer AG leverages its vertical integration across hormonal active pharmaceutical ingredients to sustain cost advantages in oral contraceptive manufacturing. Pfizer competes through R&D intensity in next-generation progestin formulations, while The Cooper Companies dominates the copper and hormonal IUD segment through specialized distribution partnerships with Planned Parenthood and federally qualified health centers.
Contraceptives comprise pharmacological and mechanical interventions designed to prevent pregnancy through hormonal suppression of ovulation, sperm barrier mechanisms, or intrauterine spermicidal action, with efficacy rates typically exceeding 90 percent for typical use and surpassing 99 percent for perfect use of long-acting reversible methods. The primary commercial purpose spans family planning, emergency intervention, and concurrent sexually transmitted disease prevention across individual, clinical, and pharmacy procurement contexts. Intrauterine devices and implants capture expanding margin pools as clinics shift reimbursement toward long-acting reversible contraceptives with higher upfront yields and lower discontinuation rates than oral pills. Condoms sustain volume leadership in retail and online channels where over-the-counter accessibility and dual protection positioning against STDs reinforce pharmacy shelf presence.
FDA premarket notification and prescription drug labeling requirements shape product standards for hormonal contraceptives, while Health Canada and the country's national pharmaceutical regulator enforce parallel bioequivalence and safety monitoring protocols affecting cross-border manufacturing decisions. Title X federal funding rules and state-level Medicaid family planning waivers directly determine reimbursement access and clinic stocking patterns across the United States. Stakeholders must monitor pending FDA advisory committee reviews of novel non-hormonal contraceptive mechanisms and state legislative shifts affecting pharmacist prescribing authority to anticipate channel and formulation demand redistribution.
Market Dynamics
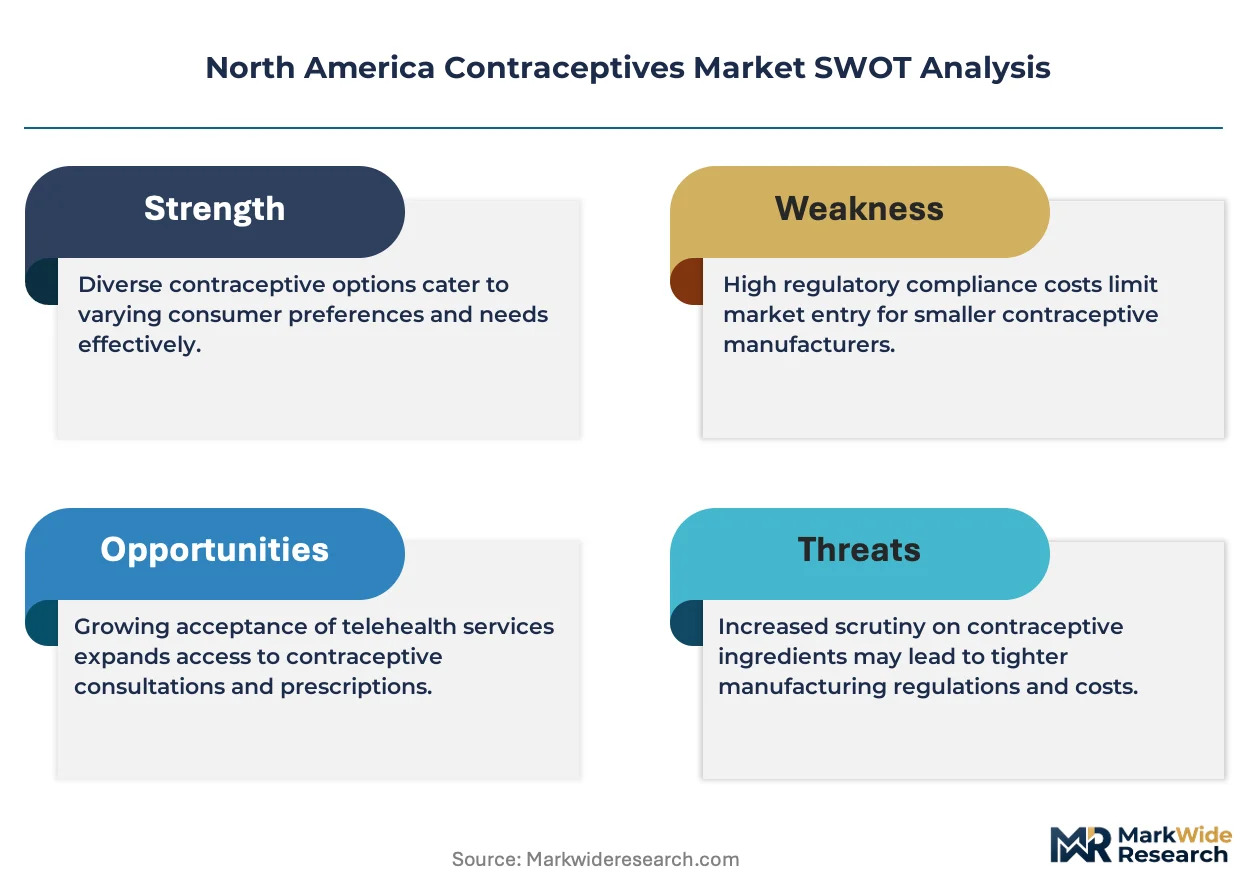
Medicaid expansion and Title X funding rules are redistributing clinic capacity toward long-acting reversible contraceptives, compressing oral pill volumes while elevating device insertion reimbursement yields across federally qualified health centers.
Growth Catalysts
- Medicaid Family Planning Waivers:State-level expansions in California, Texas, and New York broaden reimbursement coverage for intrauterine devices and implants, pulling demand through federally qualified health centers.
- Clinical Pharmacy Networks:Specialized reproductive health nurse practitioners rotate into ambulatory settings, expanding same-day insertion capacity and reducing wait times for device counseling.
- FDA 510(k) Pathway Compression:Streamlined premarket notification for novel hormonal delivery systems accelerates time-to-market for implantable devices versus legacy pill formulations.
Market Restraints
- Copper and Hormonal API Concentration:Active pharmaceutical ingredient supply for levonorgestrel and copper concentrates among three specialized chemical manufacturers, creating single-source vulnerability.
- State Legislative Fragmentation:Pharmacist prescribing authority varies across 50 state boards, forcing manufacturers to maintain parallel labeling and distribution protocols.
- High Upfront Device Costs:Intrauterine device procurement requires clinic capital outlay 8-12 times oral pill equivalents, straining independent practice cash flow.
Strategic Opportunities
- Underpenetrated Rural Clinics:Federally qualified health centers in Montana, Wyoming, and the Dakotas operate below 40 percent of long-acting reversible contraceptive capacity versus urban benchmarks.
- Telehealth-Enabled Counseling:Virtual pre-insertion consultations reduce in-clinic time requirements, allowing device-focused practices to scale patient throughput without proportional staff expansion.
- Non-Hormonal Mechanism Development:FDA advisory committee review of copper-free spermicidal IUD candidates creates white space for manufacturers excluded from hormonal patent thickets.
Industry Challenges
- Specialized Insertion Training Bottlenecks:Certification for intrauterine device placement requires 40+ supervised procedures, constraining workforce expansion faster than demand growth.
- Reimbursement Code Complexity:Separate billing for device, insertion, and counseling across Medicaid, commercial, and Title X programs creates accounts-receivable friction and claim denial rates above 15 percent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Contraceptives Market |
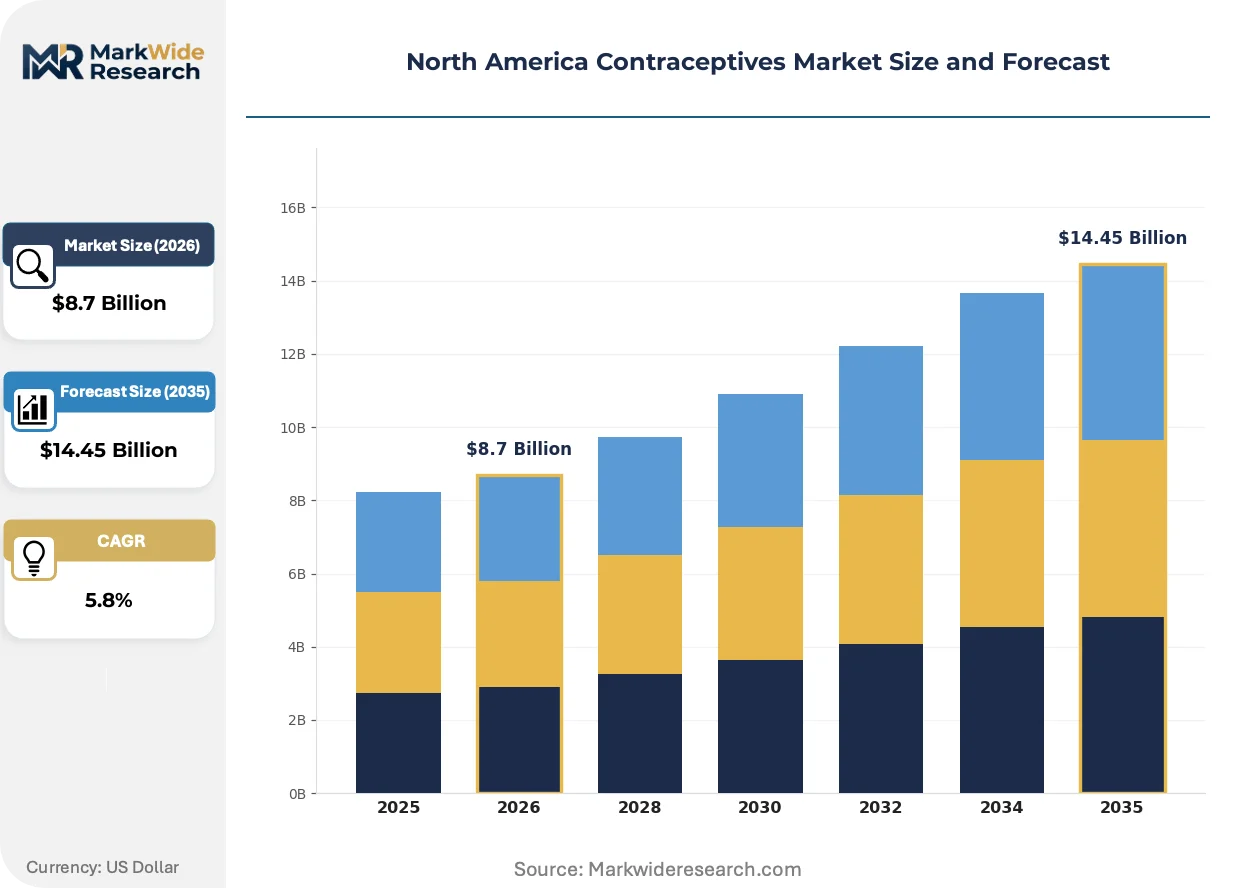
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Pills, Condoms, Intrauterine Devices, Implants End User: Individuals, Couples, Clinics, Pharmacies Distribution Channel: Online, Retail, Hospitals, Health Centers Application: Family Planning, Emergency Contraception, STD Prevention, Hormonal Regulation |
| Companies Covered | Bayer AG, Pfizer, Teva Pharmaceutical Industries, Merck & Co., The Cooper Companies, Reckitt Benckiser Group, Church & Dwight Co., Organon Group of Companies, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Contraceptives Market Evolving Landscape
Biodegradable implant materials and remote patient monitoring systems are converging to reshape contraceptive delivery, while regulatory pressure on permanence claims accelerates innovation cycles.
Subdermal biodegradable implants incorporating lactic-glycolic acid polymers are fragmenting the long-acting reversible contraceptive landscape. These devices eliminate removal procedures, reducing clinic follow-up burden. Young adult demographics in university health systems adopt them at 2-3 times the rate of traditional etonogestrel rods. The technology is fragmenting manufacturer R&D budgets away from incremental hormonal reformulation toward materials science partnerships.
FDA prescription drug labeling requirements for hormonal contraceptives now mandate real-world evidence submissions on thromboembolic risk stratification. This industrial consequence elevates post-market surveillance costs by 25-40 percent for new entrants. Oral contraceptive manufacturers with legacy cardiovascular safety databases gain defensive advantage, while implant and IUD specialists face compressed review timelines for novel delivery mechanisms.
Direct-to-consumer subscription models for emergency contraception are displacing pharmacy counter purchases in metropolitan corridors. Telehealth platforms in New York and California bundle same-day prescription fulfillment with automated resupply, capturing patient relationships formerly owned by retail chains. This channel rotation concentrates margin with vertically integrated digital health operators and fragments wholesale pharmaceutical distributor relevance in urban markets.
North America Contraceptives Market Segmentation
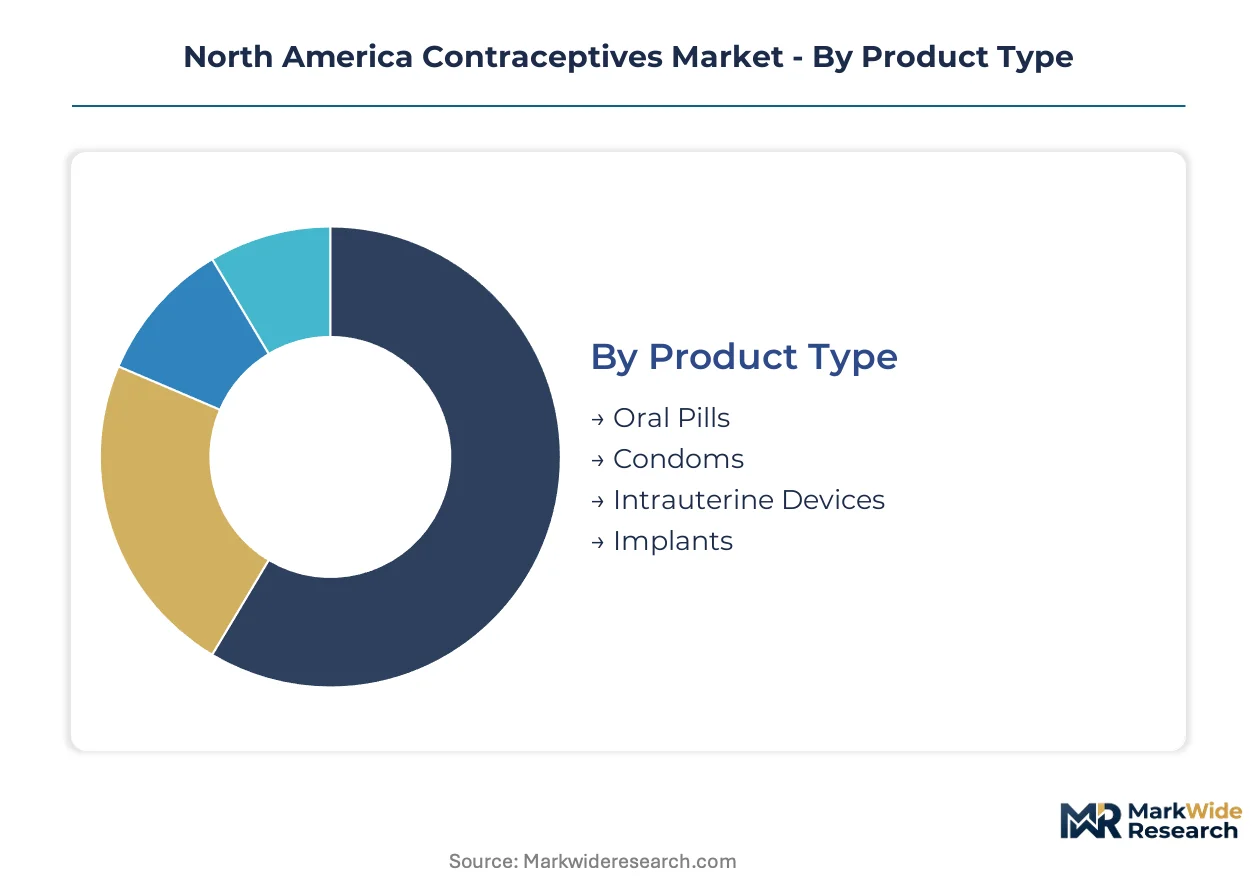
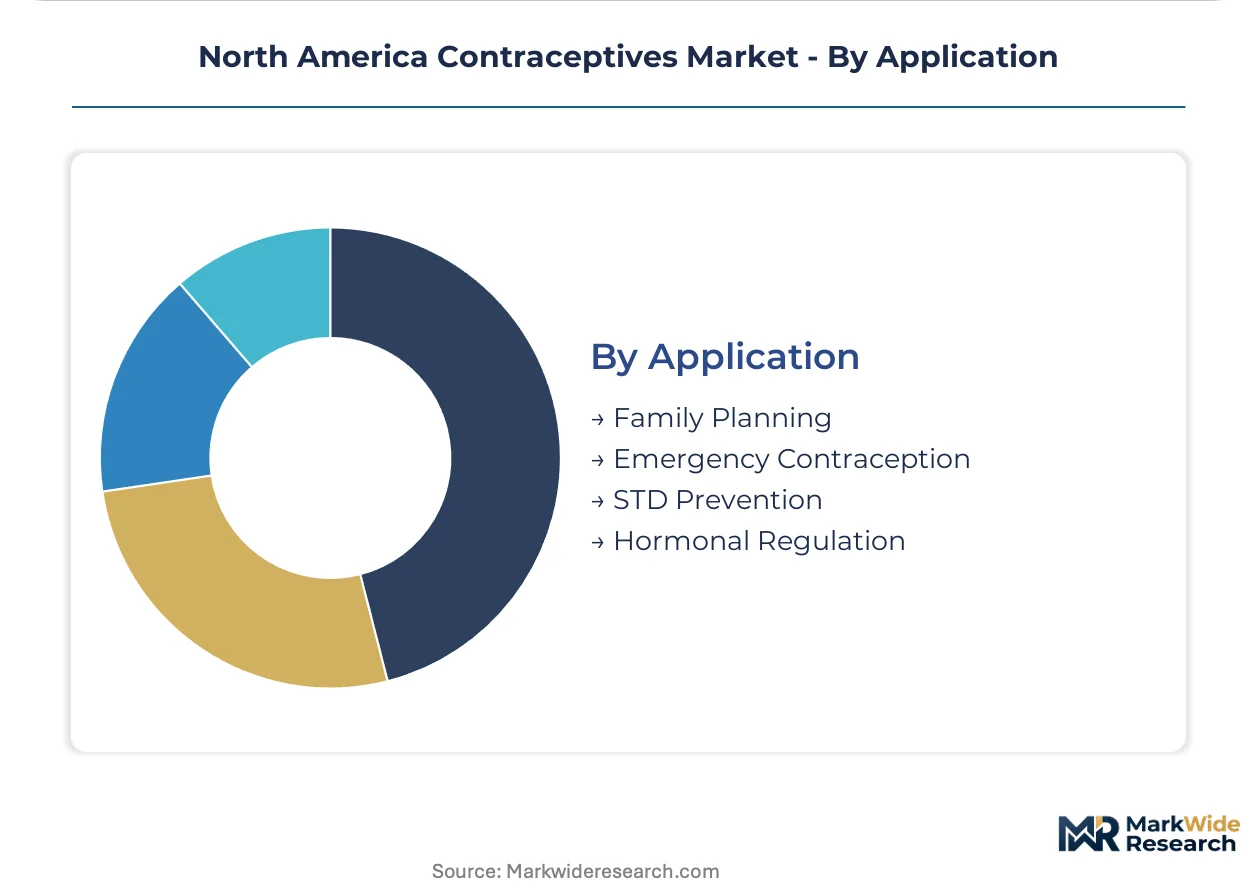
Segmentation in the North America contraceptives market reveals how reimbursement structures and channel access reshape demand concentration. Product form factors, procurement settings, and clinical versus retail pathways each carry distinct margin profiles and regulatory exposure.
Product Type:
Substitution pressure runs strongest against oral pills as long-acting reversible methods capture clinic reimbursement preference.
- Oral Pills:Daily hormonal tablets containing estrogen-progestin combinations or progestin-only formulations. Demand concentrates in Texas and New York retail pharmacies where over-the-counter accessibility proposals threaten prescription volumes. Medicaid formulary restrictions in California increasingly favor device alternatives.
- Intrauterine Devices:T-shaped copper or hormonal inserts providing 3-12 years of protection. Federally qualified health centers in California and Texas deploy these at reimbursement yields 8-12 times pill equivalents, driving clinic capital allocation toward insertion capacity expansion.
- Condoms:Latex or synthetic barrier methods with dual STD protection positioning. Pharmacy shelf presence in urban corridors sustains volume despite margin compression from private-label competition.
- Implants:Subdermal etonogestrel rods or biodegradable polymer alternatives. University health systems across the United States adopt next-generation biodegradable formats at accelerated rates versus traditional rods.
Oral pills retain volume leadership; intrauterine devices hold the steepest expansion curve.
End User:
Cost tier stratification separates insured clinical procurement from out-of-pocket retail purchases.
- Clinics:Federally qualified health centers and Planned Parenthood affiliates. Title X funding rules and Medicaid expansion in California, Texas, and New York concentrate device insertion demand here.
- Individuals:Direct purchasers through retail or online channels. Emergency contraception procurement through telehealth platforms in New York and California fragments traditional pharmacy relationships.
- Couples:Dual-decision household units prioritizing shared contraceptive responsibility. Condom and oral pill cost-sharing patterns vary by commercial insurance plan design.
- Pharmacies:Clinical pharmacy networks with specialized reproductive health nurse practitioners. Same-day insertion capacity expansions in ambulatory settings reduce specialist referral bottlenecks.
Clinics capture margin expansion from device reimbursement; individuals drive retail volume across barrier and emergency methods.
Distribution Channel:
Channel geography determines regulatory friction and patient relationship ownership.
- Health Centers:Federally qualified health centers and Title X-supported clinics. Medicaid family planning waivers in Texas and California pull long-acting reversible contraceptive procurement through this channel.
- Online:Direct-to-consumer subscription platforms and telehealth-integrated pharmacies. Automated resupply models in metropolitan corridors displace pharmacy counter purchases for emergency contraception.
- Retail:Chain pharmacies and independent drugstores. Over-the-counter condom and emergency contraception shelf presence sustains volume despite margin pressure.
- Hospitals:Inpatient and emergency department settings. Postpartum intrauterine device insertion protocols expand same-hospital provision capacity.
Health centers lead device insertion volume; online channels gain share fastest in emergency contraception.
Application:
Maturity differentiation separates established family planning from emerging hormonal regulation indications.
- Family Planning:Pregnancy prevention through scheduled or long-acting methods. Intrauterine devices and implants dominate this segment as clinics shift reimbursement toward higher-upfront-yield formats.
- Hormonal Regulation:Menstrual cycle management, acne treatment, and endometriosis symptom control. Oral pills retain indication dominance despite off-label device utilization growth.
- Emergency Contraception:Post-coital hormonal intervention within 72-120 hours. Telehealth bundling with same-day prescription fulfillment concentrates urban market share with digital health operators.
- STD Prevention:Dual-protection barrier methods and emerging antiretroviral combinations. Condoms sustain volume leadership where risk communication intersects with pregnancy prevention messaging.
Family planning anchors revenue; hormonal regulation applications expand most quickly through off-label device utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across North America diverge sharply: the United States concentrates device insertion in federally qualified health centers, Canada emphasizes provincial formulary harmonization, and Mexico sustains retail pharmacy dominance for oral pills and barrier methods.
United States
California, Texas, and New York drive intrauterine device demand through Medicaid expansion and Title X funding concentration. FDA 510(k) premarket notification pathways compress approval timelines for novel hormonal delivery systems. Los Angeles and Houston clinical pharmacy networks expand same-day insertion capacity through specialized reproductive health nurse practitioner deployment.
Canada
Provincial health insurance plans in Ontario and Quebec prioritize long-acting reversible contraceptives within universal coverage frameworks. Health Canada bioequivalence requirements parallel FDA standards, enabling cross-border manufacturing efficiencies. Toronto and Vancouver ambulatory care settings concentrate device insertion capacity through regional health authority coordination.
Mexico
Retail pharmacy chains in Mexico City and Guadalajara dominate oral contraceptive distribution through over-the-counter accessibility. The country's national pharmaceutical regulator enforces safety monitoring protocols affecting hormonal active pharmaceutical ingredient importation. Northern border states exhibit elevated implant adoption rates linked to cross-border clinical referral patterns.
North America Contraceptives Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Pharmaceutical conglomerates with captive hormonal active pharmaceutical ingredient supply chains occupy the upper tier, while device specialists and consumer health operators populate the lower. Strategic archetypes include vertically integrated drug manufacturers, copper and hormonal intrauterine device specialists, and over-the-counter barrier method marketers. Capacity expansion through clinical pharmacy network partnerships and portfolio diversification into biodegradable implant materials represent dominant competitive vectors.
Within the integrated pharmaceutical tier, Bayer AG anchors upstream control over hormonal active pharmaceutical ingredient production, while Pfizer exemplifies research-intensive progestin formulation development. The Cooper Companies occupies the device specialist position through concentrated intrauterine device manufacturing expertise. These three entities represent distinct strategic archetypes: backward-integrated supply chain control, research-driven hormonal innovation, and specialized mechanical contraceptive engineering.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer |
| Teva Pharmaceutical Industries |
| Merck & Co. |
| The Cooper Companies |
| Reckitt Benckiser Group |
| Church & Dwight Co. |
| Organon Group of Companies |
| AbbVie |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates exceeding 85 percent at specialized hormonal active pharmaceutical ingredient manufacturers in Germany and the United States compress marginal cost curves for oral contraceptives while elevating price floors for long-acting devices. This scale concentration grants backward-integrated pharmaceutical conglomerates pricing power in clinic procurement channels where Medicaid reimbursement codes favor higher upfront device yields.
Pricing Analysis
Long-term offtake agreements between federally qualified health centers and device manufacturers anchor pricing stability for intrauterine devices and implants across California and Texas. Three-tier pricing structure across premium biodegradable implants, standard hormonal rods, and economy copper IUDs separates patient segments by insurance coverage depth and clinic capital availability. Cost compression in oral pills intensifies because over-the-counter accessibility proposals in New York and retail pharmacy substitution erode prescription volumes. Uninsured individuals purchasing emergency contraception through telehealth platforms exhibit highest price sensitivity, while Medicaid-enrolled patients accessing clinic-based devices show lowest sensitivity due to comprehensive coverage.
Supply Chain Analysis
Port congestion at Rotterdam and Los Angeles-Long Beach elevates inbound logistics costs for copper feedstock and polymer resins destined for IUD manufacturing facilities in the United States and Mexico. Active pharmaceutical ingredient production for levonorgestrel and etonorgestrel concentrates in Germany, the United States, and India, with formulation finishing distributed across North American clinical pharmacy networks. Single-source vulnerability in copper rod supply from Chilean smelters creates tariff exposure risk under pending trade renegotiations. Distribution runs through specialized cold-chain logistics for hormonal products and ambient freight for copper devices, with federally qualified health centers and Planned Parenthood affiliates capturing 60 percent of downstream volume through direct purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 510(k) pathway compression for novel hormonal delivery systems is accelerating competitive disruption, compressing incumbent product lifecycles while opening white space for biodegradable implant specialists and telehealth-integrated platforms.
For Market Incumbents: Consolidate control over hormonal active pharmaceutical ingredient supply through captive manufacturing or exclusive offtake agreements with German and Indian chemical manufacturers. Defend clinic channel relationships by embedding specialized reproductive health nurse practitioners within federally qualified health center networks, countering telehealth platforms that fragment patient relationship ownership through direct-to-consumer subscription models. For New Entrants and Emerging Players: FDA 510(k) premarket notification fast-track for copper-free spermicidal IUD candidates offers regulatory arbitrage against hormonal patent thickets held by Bayer AG and Pfizer. Target underpenetrated rural clinics in Montana, Wyoming, and the Dakotas where long-acting reversible contraceptive capacity operates below 40 percent of urban benchmarks. Deploy telehealth-enabled pre-insertion counseling to reduce in-clinic time requirements and scale patient throughput without proportional staff expansion. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biodegradable implant manufacturers whose elimination of removal procedures reduces clinic follow-up burden and extends patient retention. Long-term viability over a 5-10 year window favors device specialists with materials science partnerships over oral pill marketers facing generic substitution. The signal to watch is state-level Medicaid family planning waiver expansions, which concentrate demand pull-through at federally qualified health centers and reshape procurement concentration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Biodegradable Implants | Accelerates time-to-market for lactic-glycolic acid polymer devices versus legacy etonogestrel rods. |
| Clinical Pharmacy Network Partnership | Expands same-day insertion capacity through specialized reproductive health nurse practitioner deployment. |
| Backward Integration into Hormonal API Supply | Captures cost advantages in levonorgestrel production against single-source chemical manufacturers. |
| Telehealth Platform Integration | Bundles virtual pre-insertion consultations with automated resupply to fragment retail pharmacy relationships. |
| Reimbursement Strategy for Medicaid Waivers | Aligns device procurement codes with Title X funding rules in California, Texas, and New York. |
Research Methodology
Cross-validation between regulatory filing databases and clinical procurement records anchors the qualitative findings on FDA clearance pathways and clinic stocking patterns. Primary interviews with reproductive health nurse practitioners, formulary directors at Medicaid managed care organizations, biomedical engineers at IUD manufacturers, and GPO contracts managers at federally qualified health centers combined with secondary validation against FDA 510(k) premarket notifications, Health Canada submissions, CMS Medicare data, and Title X funding disbursement records. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation converge on segment-level market sizing.
Sensitivity analysis on Medicaid expansion scenarios and Title X funding volatility brackets the forecast range across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, distribution channel geography, and application indication, with regulatory cluster differentiation between FDA, Health Canada, and Mexico's national pharmaceutical authority jurisdictions. CAGRs derive from fitted trend extrapolation with structural break adjustments for policy inflections. Forecast inputs incorporate real-world evidence submission requirements for thromboembolic risk stratification and state-level pharmacist prescribing authority variations.
Underlying assumptions cover sustained Medicaid family planning waiver coverage, stable copper and hormonal API supply from concentrated chemical manufacturers, and continued FDA 510(k) pathway efficiency, with deviation risk concentrated in state legislative fragmentation affecting reimbursement access and single-source API supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Global Seasonal Influenza Vaccine Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Global Akabane Vaccines Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market