
 Biologics Contract Development Market | 2026-2036
Biologics Contract Development Market Size, Share, and Industry Trends Forecast 2026-2036
Biologics Contract Development Market Intelligence
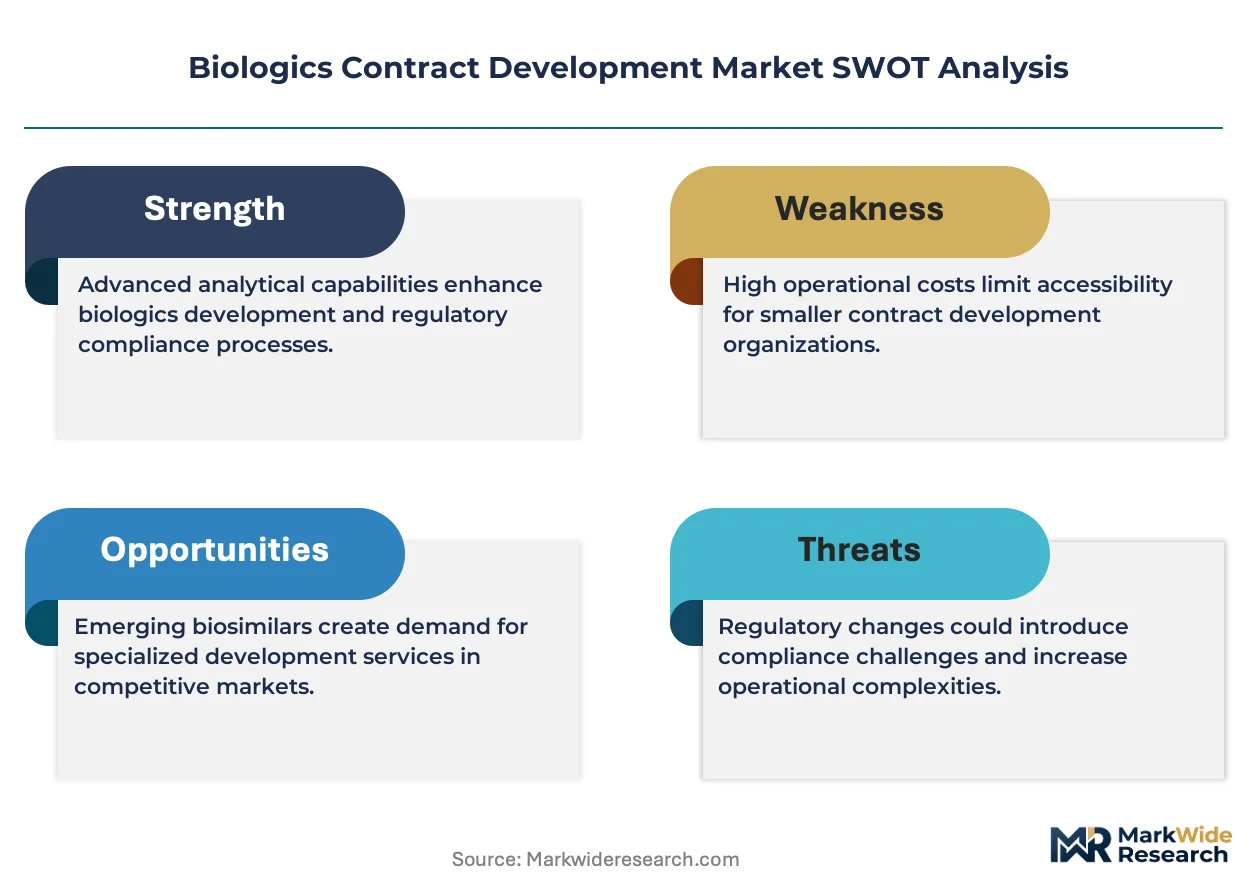
Oncology applications are repositioning the contract development landscape toward complex modalities. Lonza leverages its mammalian cell culture infrastructure to anchor high-value monoclonal antibody programs across North America and Europe. Samsung Biologics sustains massive single-use bioreactor capacity that competes aggressively on cost-per-gram for late-stage commercial manufacturing. WuXi Biologics differentiates through integrated discovery-to-commercial platforms that occupy a distinctive position in the Asia-Pacific supply chain.
Biologics contract development encompasses the outsourced design, optimization, and scale-up of living-cell-derived therapeutic proteins and nucleic acid products, typically requiring mammalian or microbial expression systems, aseptic processing, and cold-chain stability validation to meet pharmacopeial potency and purity specifications. The primary purpose is to transfer laboratory-scale bioprocesses into GMP-compliant manufacturing capable of supplying Phase I through commercial launch. Process development commands the largest share of current outsourcing spend as sponsors seek to de-risk tech transfer timelines, while gene therapies represent the fastest-growing product type due to viral vector manufacturing bottlenecks and specialized CDMO capacity scarcity. Clinical trial services remain fragmented across multiple providers, though integrated offerings that bundle analytical development with regulatory submission support capture disproportionate margin pools.
FDA's Chemistry, Manufacturing, and Controls guidance, EMA's Good Manufacturing Practice standards for advanced therapy medicinal products, and China's NMPA biologics registration requirements collectively elevate compliance costs and filter market access toward CDMOs with proven regulatory track records. These frameworks incentivize sponsor companies to consolidate outsourcing relationships with partners possessing multi-region inspection histories rather than dispersing programs across fragmented vendor bases. Stakeholders must monitor how emerging biosimilar competition and cell therapy autologous manufacturing complexity reshape capacity planning decisions and partnership structures.
Market Dynamics
Viral vector manufacturing capacity scarcity is compressing partnership timelines and forcing sponsors into exclusive capacity commitments years before commercial approval, fundamentally restructuring how biologics contract development relationships are negotiated and priced.
Growth Catalysts
- FDA Accelerated Approval:Compressed Phase I-to-approval timelines compress outsourcing decisions into earlier development stages, forcing sponsors to lock CDMO partnerships during preclinical optimization.
- Cell Therapy Autologous Manufacturing:Patient-specific production models require distributed manufacturing networks that multiply contract development touchpoints per therapy program.
- Switzerland:Concentrated regulatory excellence around Swissmedic inspection history attracts high-value monoclonal antibody programs seeking multi-region filing efficiency.
Market Restraints
- Plasmid DNA Supply Concentration:Limited qualified suppliers for GMP-grade plasmid DNA create single-source dependencies that amplify batch failure risk across gene therapy programs.
- EMA ATMP GMP Complexity:Advanced therapy medicinal product manufacturing standards impose facility redesign costs that filter market access toward capital-heavy incumbents.
- Stainless Steel Infrastructure Stranding:Legacy fixed-tank facilities face obsolescence as single-use systems dominate new capacity investments, creating stranded asset risk for mid-tier CDMOs.
Strategic Opportunities
- South Korea:MFDS regulatory convergence with FDA standards positions Korean CDMOs as bridge manufacturers for Asia-Pacific market entry by Western sponsors.
- Continuous Bioprocessing Convergence:Integration of perfusion cell culture with real-time quality monitoring enables smaller-footprint facilities that reduce capital barriers for regional market entry.
- US IRA Price Negotiation:Medicare price compression forces biopharma sponsors to seek manufacturing cost reductions through outsourced process intensification programs.
Industry Challenges
- Cell Line Development Talent Scarcity:Shortage of mammalian cell line engineers with CRISPR-editing experience extends early-phase timelines and inflates recruitment costs.
- Tech Transfer Standardization Delays:Absence of unified data exchange protocols between sponsor and CDMO quality systems creates documentation reconciliation bottlenecks.
- Multi-Product Facility Segregation:Viral vector and monoclonal antibody campaign switching requires extensive cleaning validation that compresses facility utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biologics Contract Development Market |
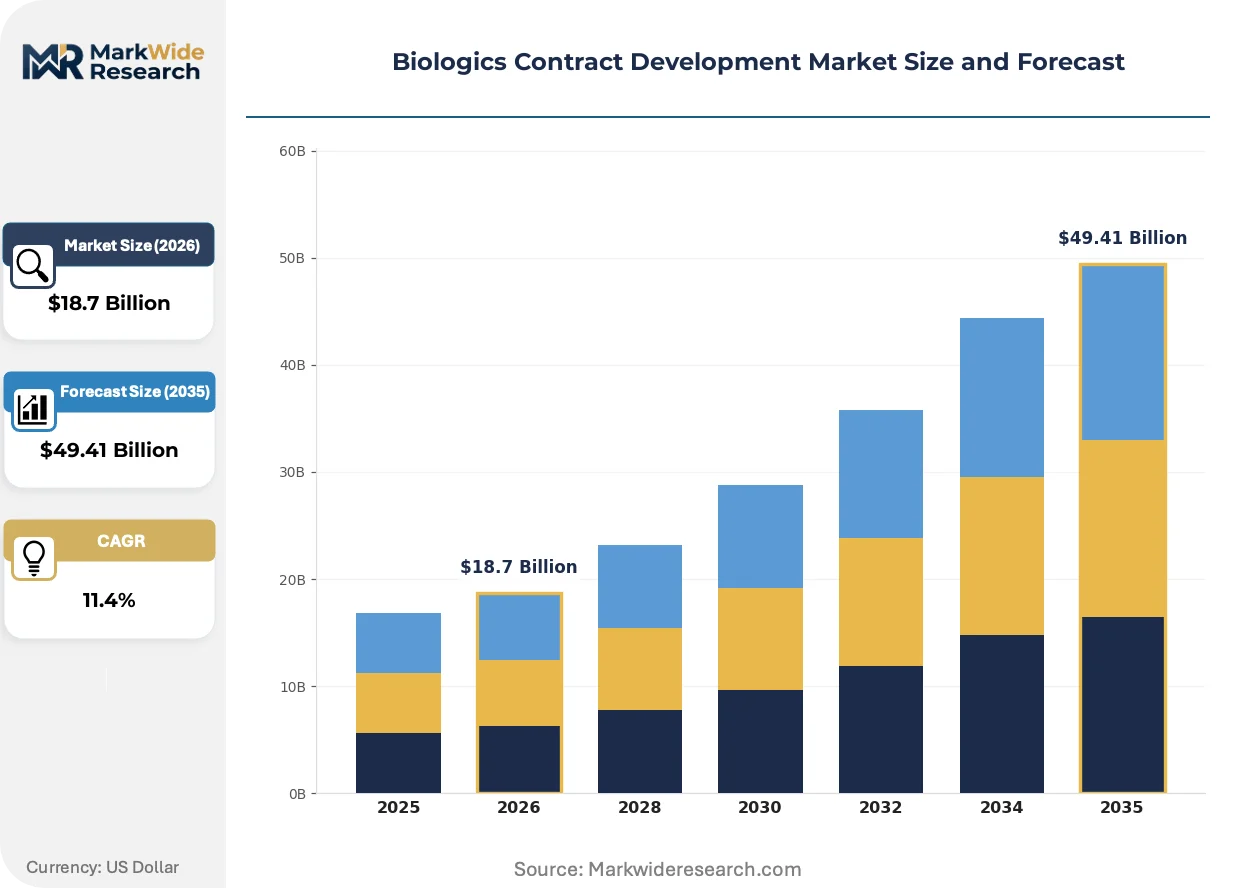
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Analytical Services, Clinical Trials, Commercial Manufacturing End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Product Type: Monoclonal Antibodies, Vaccines, Gene Therapies, Cell Therapies Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral |
| Companies Covered | Lonza, Thermo Fisher Scientific, Catalent, Samsung Biologics, WuXi Biologics, Boehringer Ingelheim BioXcellence, FUJIFILM Diosynth Biotechnologies, AGC Biologics, Curia Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biologics Contract Development Market Strategic Shifts & Innovations
Process analytical technology deployment is compressing batch release timelines and enabling real-time release testing, fundamentally altering how contract development organizations validate and transfer manufacturing processes to commercial scale.
Single-use bioreactor automation is automating seed train operations and in-process sampling across mammalian cell culture suites. Mid-size CDMOs in North America and Europe are adopting these platforms to compete with large-scale stainless steel facilities on flexibility and changeover speed. This compression of manual intervention is automating facility staffing models and reducing contamination risk profiles in multi-product environments.
EMA's revised Annex 1 sterile manufacturing guidelines mandate enhanced contamination control strategies and barrier technology adoption for aseptic processing. Facilities must upgrade isolator infrastructure and environmental monitoring systems to maintain GMP compliance. Cell therapy fill-finish operations face the steepest compliance costs, driving consolidation toward CDMOs with purpose-built advanced therapy infrastructure.
Sponsor procurement functions are consolidating vendor panels and demanding integrated discovery-through-commercial platforms rather than fragmented service procurement. Large biopharma companies now require CDMO partners to assume analytical development and regulatory submission bundling. This concentration of purchasing power is most visible in oncology pipeline outsourcing, where sponsors trade volume commitments for dedicated manufacturing slots and priority tech transfer scheduling.
Biologics Contract Development Market Segmentation
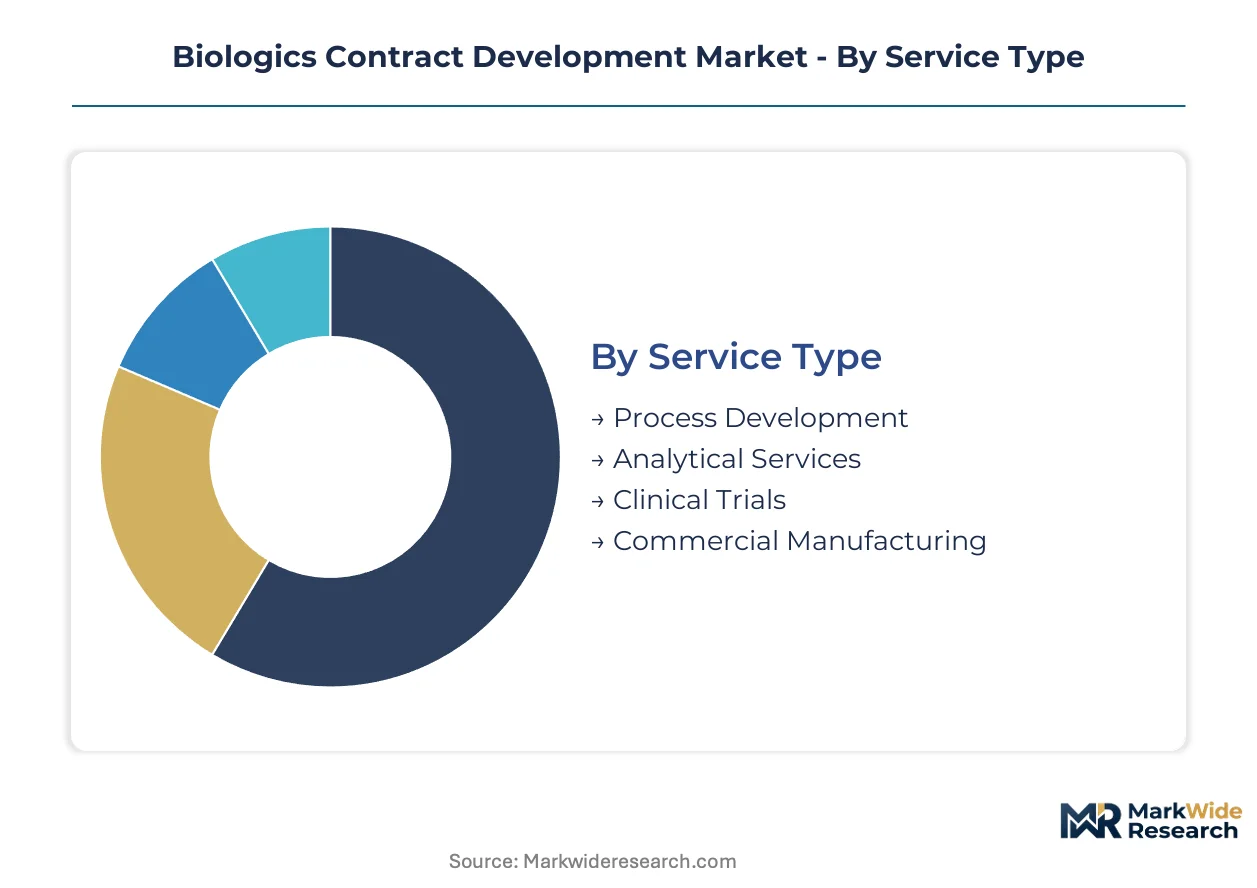
Biologics contract development segments diverge sharply in capital requirements, regulatory burden, and margin structure. Sponsors select CDMO partnerships based on modality complexity, manufacturing scale, and geographic filing strategy rather than commodity pricing.
Service Type:
Capital intensity peaks in commercial manufacturing, where GMP facility construction demands nine-figure investments and multi-year validation timelines. Process development and analytical services require specialized equipment but deploy across smaller footprints with faster capital cycles.
- Process Development:Cell line engineering, media optimization, and scale-up validation occupy the largest share of current outsourcing expenditure. Sponsors in the United States and Switzerland prioritize partners with platform technologies that compress tech transfer timelines for monoclonal antibody programs.
- Analytical Services:Method development, stability testing, and comparability studies require mass spectrometry and chromatography suites calibrated to ICH Q5E and Q6B guidelines. European sponsors concentrate demand here to support EMA multi-state filing packages.
- Clinical Trials:Phase-appropriate GMP manufacturing and investigational product release commands mid-tier capital investment. Korean CDMOs capture growing share through MFDS-aligned quality systems that satisfy Western sponsor due diligence.
- Commercial Manufacturing:Large-scale bioreactor operations and aseptic fill-finish represent the steepest facility investment category. Single-use infrastructure dominates new capacity additions, displacing legacy stainless steel trains.
Most installed capacity flows through Commercial Manufacturing. Expansion is steepest in Process Development.
End User:
Customer archetypes distribute risk tolerance and partnership duration differently. Large pharmaceutical sponsors consolidate vendor panels while emerging biotechnology firms seek integrated discovery-to-commercial platforms.
- Pharmaceutical Companies:Multinational sponsors with established regulatory affairs functions demand dedicated manufacturing slots and priority scheduling. Their procurement teams negotiate multi-product master service agreements that lock capacity years ahead of commercial launch.
- Biotechnology Firms:Venture-backed developers lack internal manufacturing infrastructure and represent the most price-sensitive customer segment. These sponsors concentrate in Cambridge, Massachusetts and South San Francisco, California, where proximity to CDMO technical teams accelerates troubleshooting cycles.
- Research Institutions:Academic medical centers and nonprofit research organizations contract for early-phase process development and non-GMP material supply. Their demand concentrates on viral vector production for investigator-initiated gene therapy trials.
- Contract Research Organizations:CROs that bundle clinical operations with manufacturing services create channel conflict for pure-play CDMOs. Their procurement leverage is rising as large CROs acquire biologics manufacturing assets.
Pharmaceutical Companies command the largest contract values. Biotechnology Firms are expanding most quickly.
Product Type:
Modality complexity determines facility design, workforce specialization, and regulatory pathway. Monoclonal antibodies leverage mature manufacturing platforms while cell and gene therapies require purpose-built infrastructure.
- Monoclonal Antibodies:Well-established mammalian cell culture platforms using Chinese hamster ovary lines dominate commercial output. Swiss and Irish manufacturing clusters specialize in high-titer fed-batch processes that supply multi-region markets.
- Vaccines:Viral and bacterial antigen production spans egg-based, cell culture, and recombinant protein platforms. Pandemic preparedness initiatives in the United States and South Korea have expanded surge capacity commitments for contract manufacturers.
- Gene Therapies:Adeno-associated viral vector manufacturing faces acute capacity scarcity. FDA's Chemistry, Manufacturing, and Controls guidance for gene therapy master files imposes documentation burdens that filter market access toward experienced CDMOs.
- Cell Therapies:Autologous chimeric antigen receptor T-cell production requires distributed manufacturing networks with cryogenic logistics chains. Patient-specific batch sizes and short shelf lives compress facility utilization metrics below traditional biologics benchmarks.
Monoclonal Antibodies anchor the revenue base. Cell Therapies are gaining share fastest.
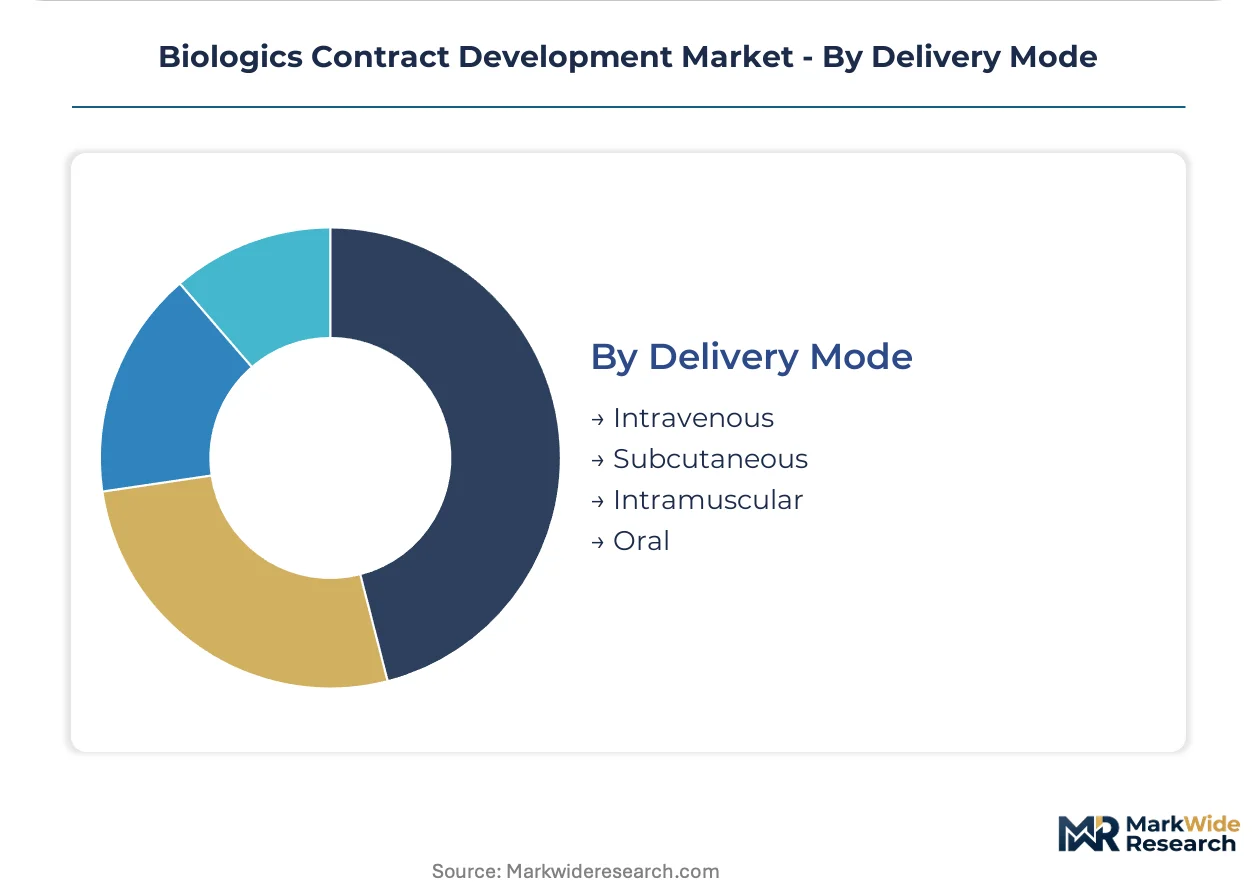
Delivery Mode:
Route of administration shapes formulation development requirements, stability testing protocols, and device compatibility validation. Parenteral formats dominate biologics due to molecular size and gastrointestinal degradation risk.
- Intravenous:Large-volume infusion concentrates demand in oncology and immunology indications. Hospital administration settings tolerate complex preparation requirements that subcutaneous formats seek to eliminate.
- Subcutaneous:Prefilled syringes and autoinjector devices require formulation viscosity optimization and siliconization studies. Patient self-administration preference is expanding demand for high-concentration protein formulations.
- Intramuscular:Vaccine delivery predominates, with adjuvant compatibility and local reactogenicity driving formulation development. Multi-dose vial presentations require preservative effectiveness validation per USP guidelines.
- Oral:Biologic oral delivery remains technically constrained by enzymatic degradation and epithelial permeability barriers. Contract development activity concentrates on permeation enhancers and nanoparticle encapsulation for peptide therapeutics.
Intravenous formats retain the largest installed base. Subcutaneous presentations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where biologics contract development concentrates, as sponsors migrate manufacturing toward jurisdictions with converged FDA-alignment and lower cost-of-compliance structures. Switzerland and South Korea capture disproportionate share through inspection-history premiums and MFDS regulatory convergence respectively.
United States
FDA accelerated approval pathways compress partnership timelines, forcing sponsors to lock CDMO relationships during preclinical stages. The agency's Chemistry, Manufacturing, and Controls guidance for gene therapies elevates documentation burdens that filter market access. Massachusetts and California biotech clusters concentrate demand for integrated discovery-to-commercial platforms.
Switzerland
Swissmedic inspection history attracts high-value monoclonal antibody programs seeking multi-region filing efficiency. The country's regulatory excellence commands premium pricing for GMP compliance services. Basel and Zurich manufacturing clusters specialize in high-titer fed-batch processes supplying European and North American markets.
South Korea
MFDS regulatory convergence with FDA standards positions Korean CDMOs as bridge manufacturers for Asia-Pacific market entry. Pandemic preparedness initiatives expanded surge capacity commitments for contract manufacturers. Songdo and Incheon bioclusters sustain massive single-use bioreactor installations competing on cost-per-gram metrics.
Germany
EMA Good Manufacturing Practice standards for advanced therapy medicinal products impose facility redesign costs that filter market access. The country's central European location supports multi-state EMA filing logistics for commercial distribution. Bavaria and Baden-Württemberg host mammalian cell culture infrastructure serving oncology pipeline demand.
China
NMPA biologics registration requirements elevate compliance costs and favor CDMOs with proven domestic inspection track records. Dual carbon goals incentivize process intensification investments that reduce facility energy footprints. Shanghai and Suzhou bioclusters anchor integrated platforms occupying distinctive positions in Asia-Pacific supply chains.
Biologics Contract Development Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing disproportionate margin pools in oncology outsourcing. The vendor base concentrates around three strategic archetypes: mammalian cell culture specialists with regulatory track records, viral vector capacity-constrained gene therapy players, and flexible single-use operators serving mid-tier biotechnology sponsors. M&A activity targets analytical development capabilities, while capacity expansion focuses on purpose-built advanced therapy infrastructure.
Among Swiss and German manufacturing specialists, Lonza and Boehringer Ingelheim BioXcellence exemplify the regulatory-history archetype that anchors high-value monoclonal antibody programs. Samsung Biologics occupies a position at the scale-driven end of the spectrum, representing Korean CDMOs competing aggressively on late-stage commercial manufacturing economics. These three entities illustrate how geographic regulatory convergence and capital intensity stratify competitive positioning across the contract development landscape.
| Leading Market Players |
|---|
| Lonza |
| Thermo Fisher Scientific |
| Catalent |
| Samsung Biologics |
| WuXi Biologics |
| Boehringer Ingelheim BioXcellence |
| FUJIFILM Diosynth Biotechnologies |
| AGC Biologics |
| Curia Global |
| Others |
Cost & Logistics Intelligence
Mammalian cell line engineers with CRISPR-editing experience concentrate in Massachusetts and Swiss bioclusters, and their scarcity spreads labor-cost differentials across three-tier pricing structures that separate regulatory-history premiums from cost-per-gram commodity tiers.
Pricing Analysis
Direct-to-biotech-sponsor contracts bypass distributor markups entirely. Pricing stratifies across premium, standard, and economy tiers where Swissmedic inspection history and dedicated manufacturing slots command premiums, while Korean CDMOs compete on late-stage commercial economics. Cost compression in the economy tier intensifies as Samsung Biologics expands single-use capacity. Emerging biotechnology firms exhibit highest price sensitivity; large pharmaceutical sponsors trade volume commitments for priority scheduling.
Supply Chain Analysis
Single-source vulnerability sits with GMP-grade plasmid DNA suppliers concentrated in the United States and Germany. Viral vector manufacturing feeds from specialized facility networks in Switzerland, South Korea, and the United States. Tariff exposure runs through cold-chain logistics dependencies for autologous cell therapies. Distribution runs through sponsor-directed point-to-point arrangements rather than wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biologics contract development market reads as a late-cycle quality story where FDA accelerated approval pathways and EMA adaptive licensing frameworks compress timelines toward partners with proven regulatory track records and integrated discovery-to-commercial platforms.
For Market Incumbents: To counter viral vector capacity scarcity forcing exclusive multi-year commitments, anchor high-value monoclonal antibody programs through Swissmedic-aligned facility investments and backward integration into analytical development capabilities that bundle regulatory submission support. For New Entrants and Emerging Players: Launch via distributed autologous cell therapy manufacturing networks targeting South Korean bridge-manufacturer positioning for Western sponsors seeking MFDS-converged quality systems and Asia-Pacific market entry efficiency. For Investors and Strategic Acquirers: Large CROs acquiring biologics manufacturing assets are the most active acquirer in this space, signaling consolidation toward integrated clinical-operations-manufacturing bundles. Target purpose-built advanced therapy infrastructure with EMA ATMP GMP compliance histories. Watch gene therapy viral vector capacity utilization rates as inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Convergence Certification | MFDS-FDA alignment enables Korean CDMOs to capture Western sponsor bridge-manufacturing contracts. |
| Single-Use Bioreactor Automation | Perfusion cell culture integration reduces capital barriers for regional market entry. |
| Plasmid DNA Supply Diversification | Multi-source GMP-grade plasmid reduces batch failure risk across gene therapy programs. |
| Continuous Bioprocessing Adoption | Real-time quality monitoring compresses batch release timelines for commercial manufacturing. |
| Advanced Therapy Infrastructure Buildout | Purpose-built isolator facilities satisfy EMA Annex 1 sterile manufacturing guideline mandates. |
Research Approach
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and CDMO procurement managers; secondary validation against FDA Chemistry Manufacturing and Controls guidance documents, EMA Good Manufacturing Practice standards, and ClinicalTrials.gov pipeline data; plus customs records and SEC 10-K facility investment disclosures — were reconciled through bottom-up service-type segmentation and top-down regional demand triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented modeling of service type, product modality, end-user archetype, and geographic regulatory cluster. CAGRs were derived from fitted growth curves calibrated to capacity expansion announcements, inspection history premiums, and sponsor outsourcing survey patterns. Industry-specific forecast inputs included viral vector manufacturing utilization rates and autologous cell therapy distributed network scaling assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under plasmid DNA supply disruption or EMA ATMP GMP facility redesign cost escalation scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Compounded Bioidentical Hormone Therapy Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Global Seasonal Influenza Vaccine Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market