
 Rivaroxaban Market | 2026-2036
Rivaroxaban Market Size, Share, and Industry Trends Forecast 2026-2036
Rivaroxaban Market Outlook
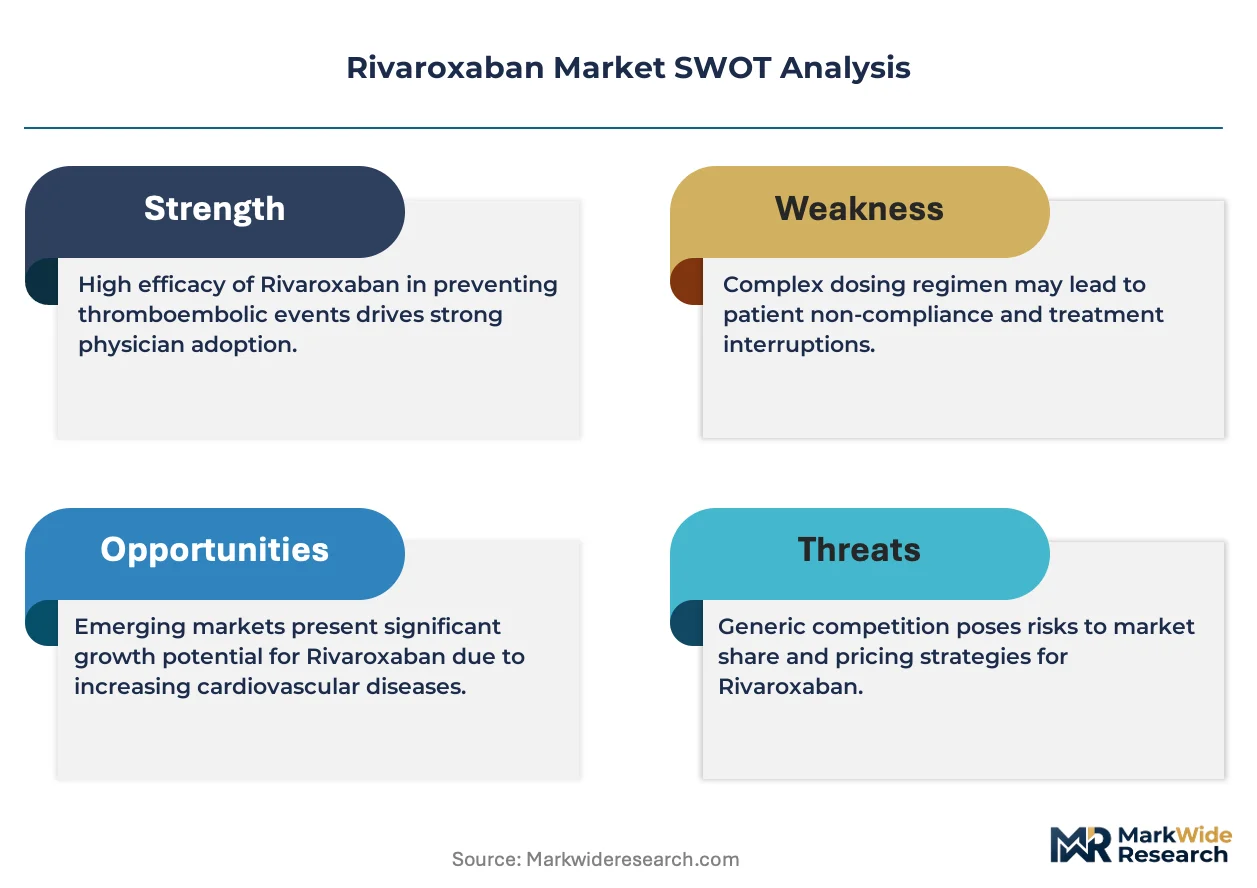
CE marking under the EU MDR is rotating competitive eligibility among manufacturers seeking European market access. Bayer AG leverages its original formulation expertise to sustain brand loyalty in cardiology. Janssen Pharmaceuticals anchors North American hospital formulary presence through established clinical trial data. Dr. Reddy's Laboratories competes on cost positioning in emerging markets with validated bioequivalence profiles.
Rivaroxaban is a direct factor Xa inhibitor anticoagulant with molecular formula C19H18ClN3O5S, synthesized through multi-step organic chemistry involving substituted thiophene and chlorothiophene intermediates, primarily indicated for stroke prevention in non-valvular atrial fibrillation and venous thromboembolism treatment. Tablet formulations dominate commercial volume due to established dosing convenience and storage stability, while extended-release development targets improved patient adherence in chronic therapy. Intravenous delivery modes serve perioperative bridging protocols in hospital settings, whereas oral administration captures the majority of outpatient maintenance prescriptions across cardiology and orthopedics therapy areas.
The FDA maintains stringent bioequivalence standards for generic rivaroxaban submissions through its Office of Generic Drugs, while the EMA's Committee for Medicinal Products for Human Use evaluates variations in European manufacturing sites. India's CDSCO aligns with ICH stability guidelines for domestic generic approvals, creating a multi-jurisdictional compliance burden. Stakeholders must monitor evolving pharmacovigilance requirements and biosimilar substitution policies across prescribing markets to anticipate revenue trajectory shifts.
Market Dynamics
Generic ANDA approvals through the FDA's Office of Generic Drugs are compressing brand pricing power while fragmenting hospital formulary control across North American cardiology networks.
Growth Catalysts
- Aging demographics in developed economies:Rising incidence of non-valvular atrial fibrillation among populations over 65 drives chronic anticoagulation demand in cardiology departments.
- EMA's EU MDR framework:Streamlined CE marking pathways for established active substances accelerate generic manufacturer entry into European hospital procurement channels.
- Factor Xa inhibitor class expansion:Clinical guideline updates favoring direct oral anticoagulants over warfarin reshape prescribing patterns in venous thromboembolism prophylaxis.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of chlorothiophene intermediates relies on concentrated Chinese chemical manufacturing clusters, exposing supply chains to geopolitical friction.
- Bleeding risk liability:Lack of widely available reversal agents for factor Xa inhibition constrains emergency department adoption in trauma-prone patient populations.
- CDSCO import dependency:Indian generic manufacturers face extended timeline variability for ICH stability guideline compliance, delaying domestic market penetration.
Strategic Opportunities
- Extended-release formulation development:Once-daily dosing improvements target medication adherence gaps in chronic atrial fibrillation management.
- Perioperative bridging protocols:Intravenous delivery modes capture surgical ward volume previously served by low-molecular-weight heparin.
- Japan's PMDA Sakigake designation:Expedited review pathways for novel anticoagulant combinations open premium positioning in geriatric stroke prevention.
Industry Challenges
- Bioequivalence study complexity:FDA requirements for food-effect and multiple-strength bridging trials extend generic development timelines and inflate clinical program costs.
- Pharmacovigilance integration:Post-market bleeding event reporting systems must reconcile disparate national databases, complicating signal detection for rare adverse events.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rivaroxaban Market |
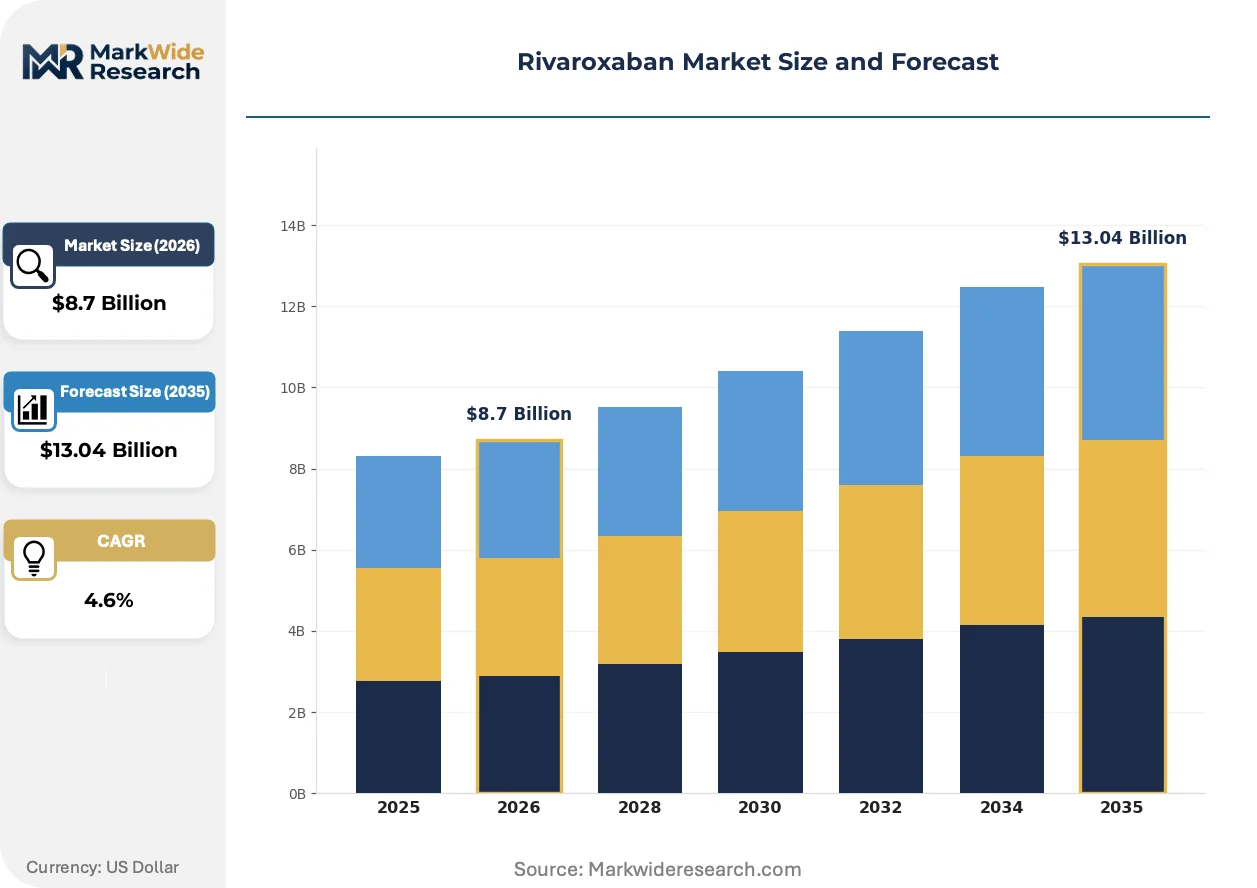
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injection, Oral Solution, Extended Release Therapy Area: Cardiology, Orthopedics, Pulmonology, Neurology Delivery Mode: Intravenous, Subcutaneous, Oral, Transdermal End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Dr. Reddy's Laboratories, Sun Pharmaceutical Industries Ltd., Bayer AG, Natco Pharma, Aurobindo Pharma, Janssen Pharmaceuticals, Inc., Sandoz International GmbH, Lupin Limited, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rivaroxaban Market Strategic Shifts
Formulation science and regulatory science are converging to reshape competitive entry patterns, with delivery technology and compliance automation emerging as distinct battlegrounds for market access.
Extended-release tablet platforms are miniaturizing dosing frequency from twice-daily to once-daily regimens. Cardiology practices in German hospital networks are adopting these formulations at accelerated rates to reduce nursing burden. The technology is miniaturizing patient pill burden while compressing competitive differentiation around convenience metrics rather than efficacy alone.
REACH registration requirements for thiophene derivative intermediates are tightening environmental compliance obligations for European manufacturing sites. Chemical producers must now submit full substance dossiers for chlorinated aromatic inputs previously exempt under grandfathered provisions. German and Belgian synthesis facilities are responding by relocating intermediate production to toll manufacturers with established MEE clearance in China.
Hospital procurement consortia are consolidating anticoagulant purchasing decisions at the integrated delivery network level rather than individual facility pharmacy committees. Regional buying groups in the United States are displacing traditional wholesaler relationships with direct manufacturer contracts tied to clinical outcome guarantees. This concentration is most visible in Florida and Texas cardiology networks where Catholic Health Initiatives and HCA Healthcare anchor multi-state formularies.
Rivaroxaban Market Segmentation
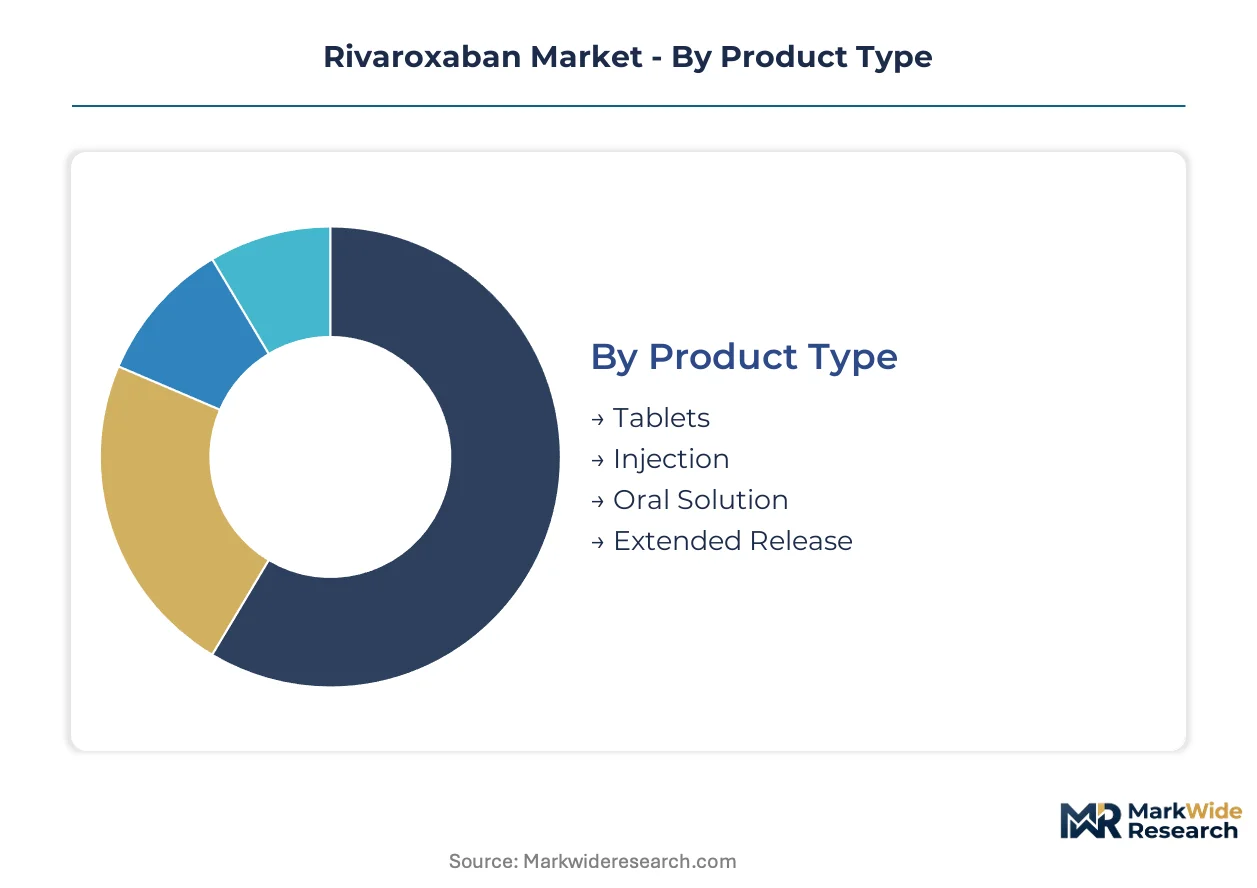
Segmentation in the rivaroxaban market reflects divergent regulatory pathways across delivery technologies and therapy areas. Product format and administration route determine compliance burden, reimbursement tier, and competitive entry barriers in hospital procurement channels.
Product Type:
FDA bioequivalence standards and EMA stability requirements create tiered compliance costs across formulation technologies.
- Tablets:Film-coated solid dosage forms containing 2.5mg, 10mg, 15mg, or 20mg active pharmaceutical ingredient with established dissolution profiles. Hospital formularies in the United States concentrate tablet procurement through integrated delivery networks seeking standardized inventory management. The format dominates commercial volume due to ambient storage stability and established clinical trial data packages.
- Extended Release:Modified-release matrix formulations targeting once-daily dosing regimens through polymeric excipient systems. German cardiology networks are adopting extended-release platforms at accelerated rates to reduce nursing administration burden in chronic atrial fibrillation management. The technology compresses competitive differentiation around adherence metrics rather than efficacy endpoints alone.
- Injection:Sterile parenteral formulations for perioperative bridging protocols in surgical wards.
- Oral Solution:Liquid formulations targeting geriatric and dysphagic patient populations with swallowing difficulties.
Established volume favors tablets; emerging adoption favors extended release.
Therapy Area:
Clinical guideline updates from cardiology societies reshape prescribing concentration across medical specialties.
- Cardiology:Stroke prevention in non-valvular atrial fibrillation and venous thromboembolism treatment represent primary approved indications with the deepest clinical evidence base. Hospital systems in Florida and Texas anchor multi-state formularies around cardiology department demand through Catholic Health Initiatives and HCA Healthcare procurement consortia. The specialty captures the majority of chronic maintenance prescriptions.
- Orthopedics:Venous thromboembolism prophylaxis following hip and knee replacement surgery drives perioperative dosing protocols. European orthopedic centers in Belgium and the Netherlands favor factor Xa inhibitors over low-molecular-weight heparin for post-surgical anticoagulation based on updated society guidelines.
- Pulmonology:Pulmonary embolism treatment in hospitalized patients with concomitant respiratory compromise.
- Neurology:Secondary stroke prevention in patients with concurrent cerebrovascular disease.
Cardiology anchors revenue concentration; orthopedics offers the steepest expansion trajectory for perioperative protocols.
Delivery Mode:
Route of administration determines site-of-care economics and emergency reversal accessibility.
- Oral:Immediate and modified-release tablet and solution formats for outpatient maintenance therapy. Outpatient prescriptions across United States cardiology practices capture the majority of volume due to patient self-administration convenience and pharmacy benefit coverage structures.
- Intravenous:Hospital-administered parenteral formulations for surgical bridging and acute venous thromboembolism treatment. Surgical wards in North American hospital networks are displacing low-molecular-weight heparin with intravenous factor Xa inhibitors for perioperative protocols.
- Subcutaneous:Depot injection formats for extended anticoagulation coverage in non-compliant patient populations.
- Transdermal:Patch-based delivery systems in early development for chronic therapy adherence improvement.
Oral administration dominates outpatient economics; intravenous formats capture inpatient surgical volume.
End User:
Procurement concentration at the integrated delivery network level fragments traditional wholesaler relationships.
- Hospitals:Inpatient pharmacy departments and emergency departments administer acute and perioperative anticoagulation through centralized formulary committees. Regional buying groups in the United States are consolidating purchasing decisions at the network level rather than individual facility committees.
- Clinics:Outpatient cardiology and anticoagulation clinics manage chronic therapy initiation and monitoring.
- Homecare:Infusion services and visiting nurse programs for post-discharge anticoagulation management.
- Pharmacies:Retail and specialty pharmacy channels dispense maintenance prescriptions with prior authorization requirements.
Hospital networks concentrate acute volume; clinic and pharmacy channels fragment chronic prescription fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia in North America and European cardiology centers concentrate the majority of rivaroxaban demand. Generic manufacturers compete through bioequivalence validation while brand-originators defend formulary position with clinical data packages. Regulatory pathways at the FDA and EMA determine competitive entry sequencing across these buyer clusters.
United States
Integrated delivery networks in Florida and Texas anchor multi-state anticoagulant procurement through Catholic Health Initiatives and HCA Healthcare systems. The FDA's ANDA approval pathway for generic anticoagulants compresses brand pricing power while fragmenting hospital formulary control. Boston and New York Metro cardiology departments drive chronic prescription volume through outpatient clinic networks.
Germany
German hospital networks adopt extended-release formulations at accelerated rates to reduce nursing administration burden in chronic atrial fibrillation management. REACH registration requirements for thiophene derivative intermediates tighten environmental compliance obligations for European manufacturing sites. Belgian and German synthesis facilities relocate intermediate production to toll manufacturers with established MEE clearance in China.
India
Domestic generic manufacturers compete on cost positioning in emerging markets with validated bioequivalence profiles. CDSCO aligns with ICH stability guidelines for domestic generic approvals, creating extended timeline variability for import-dependent manufacturers. Hyderabad and Mumbai pharmaceutical clusters concentrate API synthesis and finished dosage form production for export markets.
Japan
PMDA Sakigake designation expedites review pathways for novel anticoagulant combinations in geriatric stroke prevention. Tokyo and Osaka cardiology centers drive adoption of direct oral anticoagulants over warfarin based on updated society guidelines. The Kanto region anchors hospital procurement decisions for perioperative bridging protocols.
United Kingdom
NHS England procurement frameworks consolidate anticoagulant purchasing at the integrated care system level rather than individual trust pharmacy committees. London and Southeast England cardiology networks concentrate stroke prevention prescriptions for non-valvular atrial fibrillation patients. NICE guideline updates favoring factor Xa inhibitors reshape prescribing patterns in venous thromboembolism prophylaxis.
Rivaroxaban Market Competitive Environment
Player mix skews toward originator-multinational and generic-specialist archetypes with limited mid-tier presence. The competitive structure consolidates around patent-expiry transitions and bioequivalence validation capabilities. Two strategic archetypes dominate: brand-originators defending cardiology formulary position through clinical trial data, and cost-positioned generics competing on validated bioequivalence profiles. Competitive moves concentrate on ANDA filing velocity and extended-release formulation development.
Within the originator-multinational tier, Bayer AG and Janssen Pharmaceuticals occupy positions anchored by original formulation expertise and North American hospital formulary presence respectively. Among generic-specialist manufacturers, Dr. Reddy's Laboratories exemplifies cost-positioned competition in emerging markets. These three companies represent the dominant competitive archetypes: brand-originator defense, established market formulary anchoring, and emerging market generic penetration.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories |
| Sun Pharmaceutical Industries Ltd. |
| Bayer AG |
| Natco Pharma |
| Aurobindo Pharma |
| Janssen Pharmaceuticals, Inc. |
| Sandoz International GmbH |
| Lupin Limited |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Ninety-to-one-hundred-twenty-day API inventory buffers at European formulation sites now determine how generic manufacturers calibrate contract bids against brand-originator price floors. This lead-time band compresses margin recovery windows when chlorothiophene intermediate costs spike, forcing procurement teams to index long-term supply agreements to Chinese chemical export pricing rather than spot market exposure.
Pricing Analysis
Cost-plus contracts with quarterly API price indexation dominate hospital procurement agreements for generic rivaroxaban. Price differentiation hinges on FDA bioequivalence certification tier and volume scale commitments to integrated delivery networks. Pricing pressure stems from ANDA filing velocity as multiple generic manufacturers simultaneously target Catholic Health Initiatives and HCA Healthcare formularies. Hospital pharmacy committees exhibit highest price sensitivity, while outpatient cardiology clinics prioritize clinical trial data continuity over unit cost.
Supply Chain Analysis
China and India anchor global production of chlorothiophene intermediates and finished API synthesis respectively. Manufacturing draws from concentrated chemical clusters in Shandong Province and Hyderabad pharmaceutical corridors. Single-source vulnerability concentrates in thiophene derivative intermediates subject to REACH registration delays. Distribution runs through regional wholesaler networks serving hospital procurement consortia with direct manufacturer contracting displacing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as direct oral anticoagulant class penetration displaces warfarin maintenance prescriptions across aging populations. Extended-release formulation adoption in German and Japanese hospital networks signals adherence-driven volume acceleration ahead of therapeutic saturation.
For Market Incumbents: Fortify cardiology formulary anchoring through extended-release clinical data packages that generic competitors cannot rapidly replicate. Deepen backward integration into chlorothiophene intermediate production to buffer margin compression from Chinese environmental compliance cost inflation. Prioritize FDA bioequivalence study partnerships that delay ANDA approval timelines for emerging generic filers.
For New Entrants and Emerging Players: Differentiate on perioperative bridging protocol indications where intravenous delivery modes retain premium positioning against commoditized oral tablets. Target Japan's PMDA Sakigake pathway for novel anticoagulant combinations in geriatric stroke prevention. Pursue hospital system partnership models tied to clinical outcome guarantees rather than price-undercutting alone.
For Investors and Strategic Acquirers: Long-term, this sits as a formulation-science play because delivery technology patents outlast API exclusivity in sustaining margin structures. Acquisition candidates with validated extended-release platforms and established European CE marking under EU MDR command scarcity premia. Monitor FDA ANDA approval velocity as the signal for when generic price erosion accelerates beyond formulation innovation recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Once-daily dosing platforms reduce nursing burden in German hospital networks while compressing generic substitution threat. |
| FDA ANDA Filing Acceleration | Generic manufacturers compress brand pricing power through bioequivalence validation in North American cardiology networks. |
| REACH Registration Compliance | Thiophene derivative dossiers determine European manufacturing eligibility for chlorinated aromatic intermediate sourcing. |
| Hospital Procurement Consortium Partnership | Direct contracts with Catholic Health Initiatives and HCA Healthcare displace traditional wholesaler relationships. |
| PMDA Sakigake Designation Pursuit | Expedited Japanese review pathways open premium positioning in geriatric stroke prevention therapy lines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital formulary directors, cardiology department heads, generic regulatory affairs leads, and API procurement managers at European synthesis facilities. Secondary validation drew from FDA ANDA filings, EMA CHMP assessment reports, ClinicalTrials.gov protocol registries, and Indian CDSCO approval databases. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical expenditure tracking across the analysis window.
Across the projection horizon, segmentation modeling incorporated dosage form technology, therapy area concentration, regional regulatory cluster, and end-user procurement channel. CAGRs were derived from patient population epidemiology, guideline update velocity, and generic penetration curve analysis. Forecast inputs included aging demographic trajectories, REACH registration timeline assumptions, and hospital consolidation patterns in United States integrated delivery networks.
Decision-makers should treat outputs as directional under stable FDA bioequivalence standards and continued EMA MDR enforcement; material deviation in chlorothiophene intermediate supply availability or reversal agent development would warrant model refresh. Recalibration cycles align with material shifts in ANDA approval velocity and European environmental compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Generic Drugs Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Global Akabane Vaccines Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Global Immuno Oncology Assays Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
HIV Drugs Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Global Bioengineered Protein Drugs Market