
 Chemotherapy Market | 2026-2036
Chemotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy Market Analysis
Market Context
Good Manufacturing Practice certification for cytotoxic drug production is redrawing competitive boundaries in chemotherapy supply. Novartis leverages its integrated manufacturing network across multiple continents to sustain consistent output of high-potency compounds. Pfizer anchors its position through deep R&D investment in targeted cytotoxic agents. Bristol-Myers Squibb differentiates via specialization in immuno-oncology combination regimens that incorporate traditional chemotherapeutic backbones.
Technical Definition and Segments
Chemotherapy comprises systemic antineoplastic agents that disrupt cell division through DNA alkylation, metabolic interference, or microtubule inhibition, typically synthesized under containment-grade conditions with potency below 1 microgram per cubic meter occupational exposure limits. Alkylating agents occupy the largest revenue pool due to decades of clinical validation across solid and hematologic malignancies. Plant alkaloids represent the fastest-expanding category as paclitaxel and docetaxel derivatives penetrate adjuvant settings. Intravenous delivery dominates hospital procurement, though oral formulations are capturing share in maintenance therapy where bioequivalence has been established.
Regulatory Environment
FDA's Center for Drug Evaluation and Research, EMA's Committee for Medicinal Products for Human Use, and WHO prequalification standards collectively govern chemotherapy approval, manufacturing, and distribution across major markets. These frameworks mandate sterile processing validation, stability testing under ICH guidelines, and post-market pharmacovigilance that shapes both development costs and market access timelines. Stakeholders must monitor evolving biosimilar substitution policies and reference pricing mechanisms that will determine margin sustainability for originator molecules.
Market Dynamics
FDA's accelerated approval pathway for oncology drugs is compressing development timelines and redrawing competitive boundaries, while tertiary hospitals expand adjuvant chemotherapy protocols across major markets.
Growth Catalysts
- EMA's PRIME Designation:The European Medicines Agency's priority medicines scheme grants enhanced regulatory support to promising cytotoxic agents, shortening time-to-market for breakthrough therapies in hematologic malignancies.
- Adjuvant Protocol Expansion:Oncology departments in tertiary hospitals are systematically extending chemotherapy into post-surgical settings, creating sustained demand for taxane and platinum-based regimens.
- Containment Manufacturing Scale-Up:Contract manufacturers with isolator technology and potency-handling capabilities below 1 microgram per cubic meter are expanding capacity to serve both originator and biosimilar pipelines.
Market Restraints
- Potent Compound Handling Costs:Specialized engineering controls, closed-system transfer devices, and operator training for high-potency active pharmaceutical ingredients inflate manufacturing overhead by 40-60% versus standard pharmaceuticals.
- API Supply Concentration:China dominates the production of paclitaxel precursors and platinum salts, creating geographic vulnerability for formulators dependent on just-in-time raw material flows.
- Substitution Ceiling:Biosimilar penetration in oncology remains constrained by prescriber conservatism and institutional formulary inertia, limiting cost relief from generic competition.
Strategic Opportunities
- Oral Formulation Growth:Maintenance therapy settings in the United States are absorbing bioequivalent oral cytotoxics, displacing infusion center visits and capturing patient convenience premium.
- India's CDSCO Streamlining:The Central Drugs Standard Control Organization's phased manufacturing and clinical trial reforms are attracting contract research and manufacturing investment for export-oriented cytotoxic production.
- Antibody-Drug Conjugate Convergence:Linker chemistry advances are fusing monoclonal antibodies with traditional chemotherapeutic payloads, opening new therapeutic indices for cytotoxic moieties.
Industry Challenges
- Containment Engineering Talent Scarcity:Qualified professionals with combined pharmaceutical process and industrial hygiene expertise for high-potency compound handling remain critically undersupplied across manufacturing networks.
- Post-Market Pharmacovigilance Burden:FDA's Risk Evaluation and Mitigation Strategies and EMA's additional monitoring requirements impose persistent compliance costs and data infrastructure demands on commercialized oncology portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy Market |
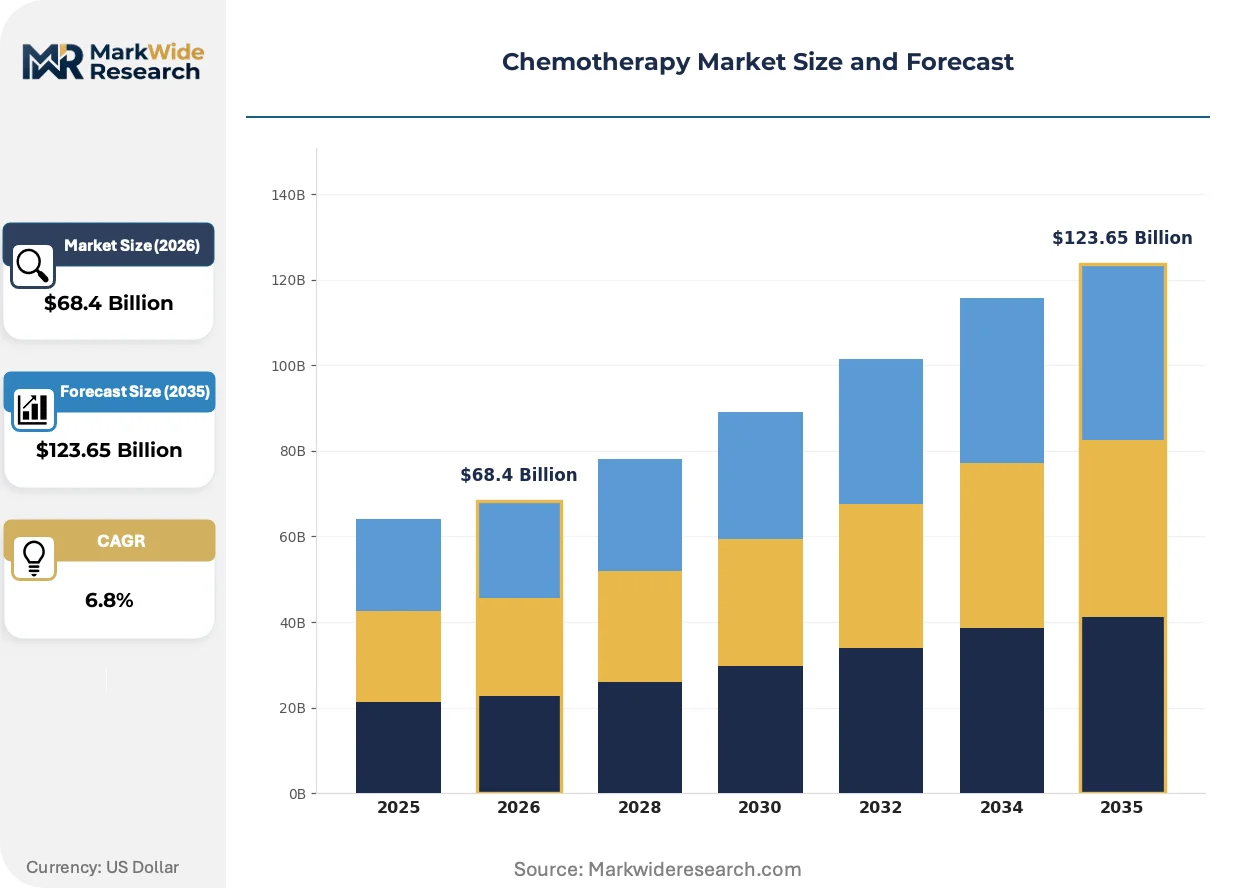
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylating Agents, Antimetabolites, Antibiotics, Plant Alkaloids Application: Breast Cancer, Lung Cancer, Colorectal Cancer, Leukaemia Delivery Mode: Intravenous, Oral, Intramuscular, Subcutaneous End User: Hospitals, Clinics, Home Healthcare, Research Centers |
| Companies Covered | Novartis, Pfizer, Roche, Bristol-Myers Squibb, AstraZeneca, Merck & Co., Sanofi, GSK, Eli Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy Market Emerging Trajectories
Continuous manufacturing technologies and digital batch records are displacing conventional batch processing in cytotoxic drug production, while regulatory frameworks accelerate adaptive trial designs.
Continuous flow chemistry for highly potent active pharmaceutical ingredients is miniaturizing production footprints and enabling distributed manufacturing closer to point-of-care. Contract development and manufacturing organizations with isolator-integrated flow reactors are securing multi-year supply agreements with major oncology portfolios. This technology is compressing campaign changeover times and reducing solvent waste volumes by an order of magnitude versus traditional batch synthesis.
WHO prequalification standards for essential cytotoxic medicines are tightening stability testing and cold chain documentation requirements for suppliers to low- and middle-income country procurement programs. Manufacturers seeking inclusion in national essential medicine lists must now demonstrate ICH Q1A-compliant photostability and accelerated degradation data. African and Southeast Asian tender markets are responding by consolidating supplier qualification around prequalified sources, raising barriers for non-compliant competitors.
Hospital purchasing consortia in Germany and the United States are unbundling chemotherapy acquisition from compounding and administration services, forcing price transparency on drug costs previously obscured in bundled payments. Specialty distributors with 503B compounding capabilities are capturing volume through direct-to-physician-office models that bypass traditional wholesale channels. This disintermediation is most pronounced in community oncology practices seeking to preserve in-office infusion revenue against hospital outpatient department competition.
Chemotherapy Market Segmentation
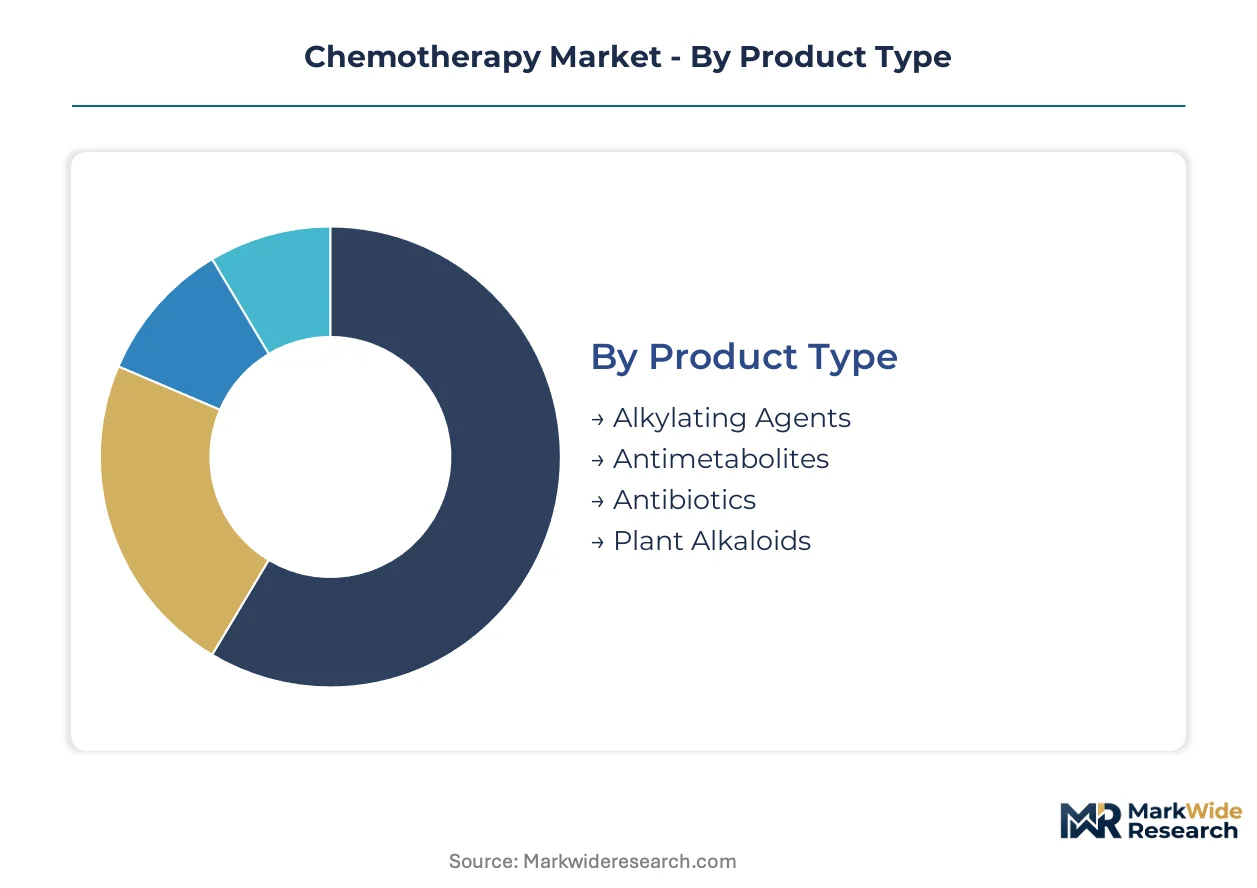
Segmentation in chemotherapy markets reveals divergent growth mechanics across molecular classes and care settings. Product type stratification exposes legacy alkylating dominance against plant alkaloid acceleration, while delivery mode shifts track patient preference evolution and reimbursement policy changes.
Product Type:
Alkylating agents command domestic hospital procurement volumes in the United States and Germany, while plant alkaloid demand concentrates in export-oriented manufacturing hubs serving Asia-Pacific markets.
- Alkylating Agents:These DNA-crosslinking compounds include cyclophosphamide and cisplatin derivatives synthesized under containment-grade conditions. United States tertiary hospitals anchor procurement for adjuvant protocols in solid tumors, though manufacturing cost inflation from platinum salt supply concentration constrains margin expansion.
- Plant Alkaloids:Taxane and vinca alkaloid derivatives disrupt microtubule dynamics during mitosis. Chinese API producers dominate paclitaxel precursor supply, positioning export-led formulators in India and South Korea to capture maintenance therapy demand as oral bioequivalence expands.
- Antimetabolites:Folate and purine antagonists like 5-fluorouracil interfere with nucleotide synthesis pathways.
- Antibiotics:Anthracycline compounds such as doxorubicin intercalate DNA and generate free radicals.
Alkylating agents hold the largest share; momentum sits with plant alkaloids.
Application:
Cost tier stratification separates premium biologics-adjacent regimens from standard cytotoxic backbones across oncology indications.
- Breast Cancer:Adjuvant taxane-platinum combinations drive hospital procurement in Germany and the United States. CDK inhibitor co-administration is compressing traditional cytotoxic share in first-line metastatic settings.
- Lung Cancer:Platinum-doublet protocols retain standard-of-care status despite immunotherapy displacement in non-small cell histologies. Chinese tertiary hospitals concentrate demand for pemetrexed-based regimens in adenocarcinoma.
- Colorectal Cancer:FOLFOX and FOLFIRI backbones sustain oxaliplatin and irinotecan consumption.
- Leukaemia:Cytarabine-anthracycline induction regimens dominate acute myeloid protocols.
Breast cancer applications generate the highest revenue concentration; lung cancer exhibits the steepest expansion trajectory from screening program expansion.
Delivery Mode:
Volume concentration favors infusion center infrastructure, though patient convenience preferences are redistributing share toward self-administered formats.
- Intravenous:Hospital outpatient departments and community oncology practices administer cytotoxics through central line or peripheral access. United States 340B program participation shapes procurement concentration among covered entities.
- Oral:Capecitabine and temozolomide formulations enable home-based maintenance therapy. German sickness funds are expanding reimbursement for bioequivalent oral cytotoxics to reduce infusion center utilization costs.
- Intramuscular:Depot formulations extend dosing intervals for select hormonal cytotoxic combinations.
- Subcutaneous:Trastuzumab biosimilars and supportive care adjuncts utilize this route for patient convenience.
Intravenous delivery commands institutional procurement volumes; oral formulations are gaining share fastest from reimbursement alignment and patient preference shifts.
End User:
Customer type fragmentation separates acute care infrastructure from distributed care models with divergent supply chain requirements.
- Hospitals:Tertiary oncology centers in the United States, China, and Germany consolidate adjuvant protocol administration. FDA Risk Evaluation and Mitigation Strategies compliance and closed-system transfer device mandates elevate procurement qualification barriers.
- Clinics:Community oncology practices in the United States preserve infusion revenue through 503B compounding relationships and direct physician office models.
- Home Healthcare:Oral cytotoxic dispensing and nursing administration for palliative regimens.
- Research Centers:Academic medical centers conduct early-phase cytotoxic combination trials under IND protocols.
Hospitals retain the dominant procurement position; home healthcare is climbing the fastest from oral formulation expansion and payer cost-containment incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital purchasing consortia and tertiary oncology centers concentrate procurement authority across the United States, Germany, China, India, and Japan, with each market exhibiting distinct regulatory and reimbursement architectures that reshape competitive access.
United States
Tertiary hospital systems in Boston, Houston, and New York Metro consolidate adjuvant protocol administration through 340B program participation. FDA's Risk Evaluation and Mitigation Strategies mandate closed-system transfer device compliance, elevating procurement qualification barriers for cytotoxic suppliers. Community oncology practices in Florida and Texas preserve infusion revenue through direct-to-physician-office distribution models that bypass traditional wholesale channels.
Germany
Sickness funds in Bavaria and North Rhine-Westphalia expand reimbursement for bioequivalent oral cytotoxics to reduce infusion center utilization costs. EMA's Committee for Medicinal Products for Human Use governs marketing authorization under centralized procedures. Hospital purchasing consortia in Baden-Württemberg unbundle chemotherapy acquisition from compounding services, forcing price transparency on drug costs previously obscured in bundled payments.
China
NMPA's accelerated review pathway for breakthrough oncology therapies compresses registration timelines for imported cytotoxic agents. Tertiary hospitals in Beijing, Shanghai, and Guangzhou concentrate demand for pemetrexed-based regimens in lung adenocarcinoma. Domestic API producers in Jiangsu and Zhejiang provinces dominate paclitaxel precursor supply, positioning local formulators to capture maintenance therapy demand.
India
CDSCO's phased manufacturing and clinical trial reforms attract contract research investment for export-oriented cytotoxic production. Maharashtra and Gujarat-based formulators leverage cost advantages in containment-grade synthesis to serve African and Southeast Asian tender markets. WHO prequalification requirements for essential cytotoxic medicines tighten stability documentation, consolidating supplier qualification around prequalified sources.
Japan
PMDA's Sakigake designation grants priority review to innovative oncology agents, shortening time-to-market for novel cytotoxic mechanisms. Metropolitan Tokyo and Osaka hospital networks anchor procurement for platinum-doublet protocols in gastric and lung malignancies. Domestic manufacturers with isolator-integrated continuous flow capabilities secure multi-year supply agreements with regional oncology portfolios.
Chemotherapy Market Vendor Landscape
Player mix skews toward integrated pharmaceutical conglomerates with captive manufacturing networks and specialized oncology divisions. Tiered competition separates originator molecule holders from biosimilar entrants and contract manufacturing organizations with containment-grade capabilities. Dominant competitive moves include geographic manufacturing diversification to reduce API supply concentration risk and strategic partnerships with antibody-drug conjugate developers seeking chemotherapeutic payload sourcing.
Among Swiss-based pharmaceutical conglomerates, Novartis and Roche occupy positions exemplifying integrated manufacturing network strategies across multiple continents. Bristol-Myers Squibb represents the immuno-oncology combination archetype, anchoring competitive positioning through specialization in regimens that incorporate traditional chemotherapeutic backbones. Pfizer exemplifies deep R&D investment archetypes in targeted cytotoxic agents.
| Leading Market Players |
|---|
| Novartis |
| Pfizer |
| Roche |
| Bristol-Myers Squibb |
| AstraZeneca |
| Merck & Co. |
| Sanofi |
| GSK |
| Eli Lilly |
| Others |
Supply Flow & Price Mechanics
Isolator-integrated manufacturing scale at contract development organizations shapes both supply concentration and minimum viable pricing for high-potency cytotoxic compounds. Capacity utilization rates above 80% at containment-grade facilities in India and China establish floor prices that originators must match to retain hospital formulary access.
Pricing Analysis
Cost-plus contracts with platinum salt and paclitaxel precursor indexation dominate API procurement between Chinese suppliers and Western formulators. Three-tier pricing structure across originator, authorized generic, and biosimilar levels reflects FDA Risk Evaluation and Mitigation Strategies compliance costs and closed-system transfer device bundling. Pricing pressure stems from German sickness fund reference pricing mechanisms and United States 340B ceiling price calculations. Community oncology practices exhibit highest price sensitivity due to infusion revenue preservation needs, while tertiary hospital systems absorb premium tiers through bundled payment structures.
Supply Chain Analysis
Jiangsu and Zhejiang province port congestion underwrites API delivery risk for paclitaxel precursor-dependent formulators. China, India, and Switzerland anchor cytotoxic drug supply through distinct specializations: Chinese API production, Indian containment formulation, and Swiss originator innovation. Platinum salts, taxane precursors, and anthracycline fermentation feedstocks feed from geographically concentrated extraction and synthesis nodes. Single-source vulnerability concentrates in Chinese platinum salt refining. Distribution runs through specialty distributors with 503B compounding capabilities and direct-to-physician-office channels that bypass traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against immuno-oncology and targeted therapy displacement of traditional cytotoxic backbones in first-line settings.
For Market Incumbents: Secure antibody-drug conjugate payload supply agreements to embed cytotoxic moieties within biologic growth vectors. Anchor manufacturing diversification across Swiss, Indian, and Japanese containment facilities to reduce Jiangsu province concentration exposure. Reinforce hospital formulary position through Risk Evaluation and Mitigation Strategies program administration services that lock in procurement relationships. For New Entrants and Emerging Players: Differentiate on oral bioequivalence capabilities for maintenance therapy segments where German sickness funds and United States Medicare Advantage plans prioritize home administration cost savings. Target Indian CDSCO streamlined pathways for export-oriented production serving African and Southeast Asian WHO prequalification tenders. Pursue 503B compounding partnerships with United States community oncology practices seeking to preserve in-office infusion revenue. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract manufacturers with multi-year supply agreements and isolator-integrated continuous flow capabilities. Five-to-ten year viability hinges on ADC payload diversification and biosimilar substitution ceiling persistence. Monitor CDSCO manufacturing reform implementation velocity and FDA accelerated approval pathway expansion as inflection signals for contract research and manufacturing organization valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Antibody-Drug Conjugate Partnership | Linker chemistry advances fuse monoclonal antibodies with cytotoxic payloads, opening new therapeutic indices. |
| Continuous Flow Manufacturing Scale-Up | Isolator-integrated flow reactors compress campaign changeover times and reduce solvent waste volumes. |
| CDSCO Regulatory Pathway Utilization | Phased manufacturing reforms attract export-oriented cytotoxic production investment for emerging market tenders. |
| Oral Formulation Bioequivalence Development | Capecitabine and temozolomide equivalents enable home-based maintenance therapy reimbursement expansion. |
| Containment Engineering Talent Acquisition | Combined pharmaceutical process and industrial hygiene expertise remains critically undersupplied across manufacturing networks. |
Methodological Framework
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up demand modeling at the indication-protocol level triangulated against top-down manufacturer revenue segmentation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions included molecular class, delivery mode, treatment line, administration setting, and regional regulatory cluster. CAGRs were derived from protocol expansion trajectories, biosimilar penetration assumptions, and oral formulation adoption curves specific to maintenance therapy settings.
Material uncertainties — regulatory pathway delays, API supply disruptions, and immuno-oncology substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about prescriber conservatism and formulary inertia persistence. Practitioners should keep alternative scenarios live as WHO prequalification standard tightening and hospital purchasing consortia unbundling evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market