
 Global Incretin-Based Drugs Market | 2026-2036
Global Incretin-Based Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Incretin-Based Drugs Market Analysis
Obesity management is expanding as the fastest-rising end-use vertical for incretin-based therapies, overtaking traditional type 2 diabetes positioning in prescriber mindshare. Novo Nordisk dominates the weekly injectable segment through manufacturing scale and channel control across North American and European distribution networks. Eli Lilly differentiates via dual GIP/GLP-1 receptor agonist technology leadership, while Sanofi competes through sustained investment in oral formulation R&D pipelines.
Incretin-based drugs comprise peptide and small-molecule therapeutics that potentiate glucose-dependent insulin secretion through GLP-1 receptor activation or DPP-4 enzyme inhibition, typically requiring cold-chain distribution at 2-8°C for biologic formulations. GLP-1 receptor agonists anchor the largest revenue pool due to superior HbA1c reduction and weight loss outcomes, while DPP-4 inhibitors occupy a mature, price-compressed tier with generic erosion in major markets. The injectable delivery mode leads in value terms, though oral formulations represent the fastest-growing development frontier as patient adherence data reshapes payer preference.
The FDA mandates cardiovascular outcome trials for novel incretin therapies, while the EMA requires periodic safety signal monitoring through its pharmacovigilance framework, and the WHO inclusion of GLP-1 agonists on its essential medicines watchlist shapes procurement standards in lower-income markets. These regulatory layers elevate clinical evidence thresholds and compress development timelines for follow-on entrants. Stakeholders must monitor how FDA label expansions for cardiovascular risk reduction and EMA pediatric investigation plans reshape competitive positioning and reimbursement dynamics.
Market Dynamics
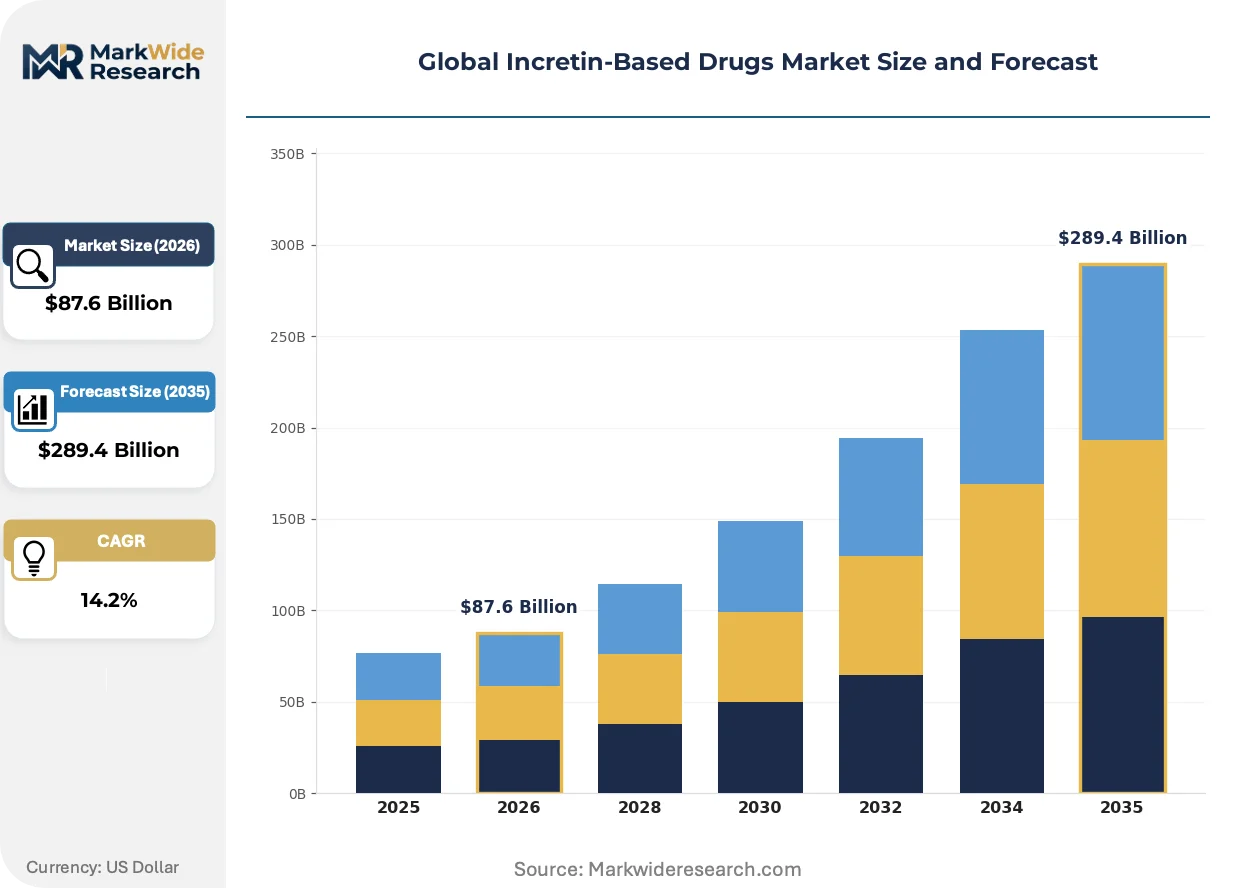
The central structural force reshaping the incretin-based drugs market is the regulatory mandate for cardiovascular outcome trials, which compresses development timelines and elevates clinical evidence thresholds for new molecular entities entering the GLP-1 receptor agonist class.
Growth Catalysts
- EMA Pharmacovigilance Framework:The European Medicines Agency's periodic safety signal monitoring requirements accelerate post-market surveillance capabilities, strengthening prescriber confidence in long-acting formulations and expanding formulary access across European Union member states.
- Obesity Management Clinics:Specialized weight-loss treatment centers in the United States are recalibrating their therapeutic protocols to prioritize weekly injectable GLP-1 agonists, creating concentrated demand pull from employer-sponsored health plan networks.
- Cold-Chain Distribution Infrastructure:Advances in temperature-controlled logistics at 2-8°C are reducing biologic degradation rates during transit, enabling market expansion into secondary and tertiary care settings previously excluded from peptide therapy access.
Market Restraints
- FDA Cardiovascular Outcome Study Requirements:The Food and Drug Administration's tightened trial mandates for novel incretin therapies impose substantial capital requirements and extend pre-approval timelines, creating barriers for mid-cap developers lacking Phase III infrastructure.
- Active Pharmaceutical Ingredient Concentration:Peptide synthesis capacity concentrates among a limited network of contract manufacturing organizations in Switzerland and Denmark, exposing supply continuity to single-source dependencies and geopolitical disruption risks.
- DPP-4 Inhibitor Generic Erosion:Patent expiration across major markets has triggered price compression in the oral small-molecule segment, compressing margins and redirecting R&D investment away from enzyme inhibition toward receptor agonist platforms.
Strategic Opportunities
- WHO Essential Medicines Watchlist Inclusion:The World Health Organization's provisional listing of GLP-1 agonists creates procurement pathway standardization for lower-income markets, opening volume opportunities through multilateral health financing mechanisms and national essential medicine programs.
- Oral Formulation Development:Small-molecule GLP-1 receptor agonists with enhanced bioavailability are advancing through clinical pipelines, targeting patient adherence gaps in the United States and European Union where injection frequency drives discontinuation.
- Dual GIP/GLP-1 Receptor Agonist Technology:Convergent incretin pathway activation is demonstrating superior metabolic outcomes in Phase II studies, creating white space for differentiated positioning against single-mechanism competitors in prescriber preference hierarchies.
Industry Challenges
- Peptide Manufacturing Talent Scarcity:The specialized skill set required for large-scale recombinant protein production and purification is concentrated among a limited cohort of process engineers, constraining capacity expansion timelines for biologic formulation scale-up.
- Multi-Jurisdictional Label Harmonization:Divergent cardiovascular risk reduction claims across FDA, EMA, and PMDA labeling requirements complicate global launch sequencing and medical affairs resource allocation for developers pursuing simultaneous market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Incretin-Based Drugs Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GLP-1 Receptor Agonists, DPP-4 Inhibitors, Combinations, Others Delivery Mode: Injectable, Oral, Combination, Others End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Type 2 Diabetes, Obesity, Cardiovascular Diseases, Others |
| Companies Covered | Novo Nordisk, Eli Lilly, AstraZeneca, Merck & Co., Sanofi, Boehringer Ingelheim, Novartis AG, Takeda Pharmaceutical Company, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Incretin-Based Drugs Market Emerging Trajectories
Three interconnected developments are restructuring competitive positioning in the incretin-based drugs market: convergence toward multi-receptor agonist platforms, intensifying regulatory scrutiny of cardiovascular safety endpoints, and the emergence of oral peptide delivery as a viable alternative to parenteral administration.
Dual GIP/GLP-1 receptor agonist technology is absorbing the highest share of late-stage R&D investment in the metabolic disease space. Endocrinology practices in the United States and Germany are adopting these agents at twice the rate of single-mechanism predecessors based on superior HbA1c and body weight composite outcomes. The technology is absorbing market share from established GLP-1 monotherapies by collapsing the efficacy gap that previously justified separate diabetes and obesity treatment protocols.
REACH authorization requirements for novel biologic substances in the European Union are extending chemical safety dossier preparation timelines for peptide-based therapeutics. Industrial consequence includes delayed market access for developers lacking existing European chemical registration infrastructure. Small-cap entrants with limited regulatory affairs capacity are most affected, responding through partnership structures with established European marketing authorization holders.
Employer-sponsored health plans in the United States are consolidating pharmacy benefit management under single-vendor arrangements to negotiate volume-based rebates for weekly injectable therapies. The channel shift displaces traditional fee-for-service reimbursement models with outcomes-linked contracting structures. This behavioral pivot is most visible in the self-insured employer segment, where pharmacy spend concentration has elevated GLP-1 agonists to top-three therapeutic category status.
Global Incretin-Based Drugs Market Segmentation
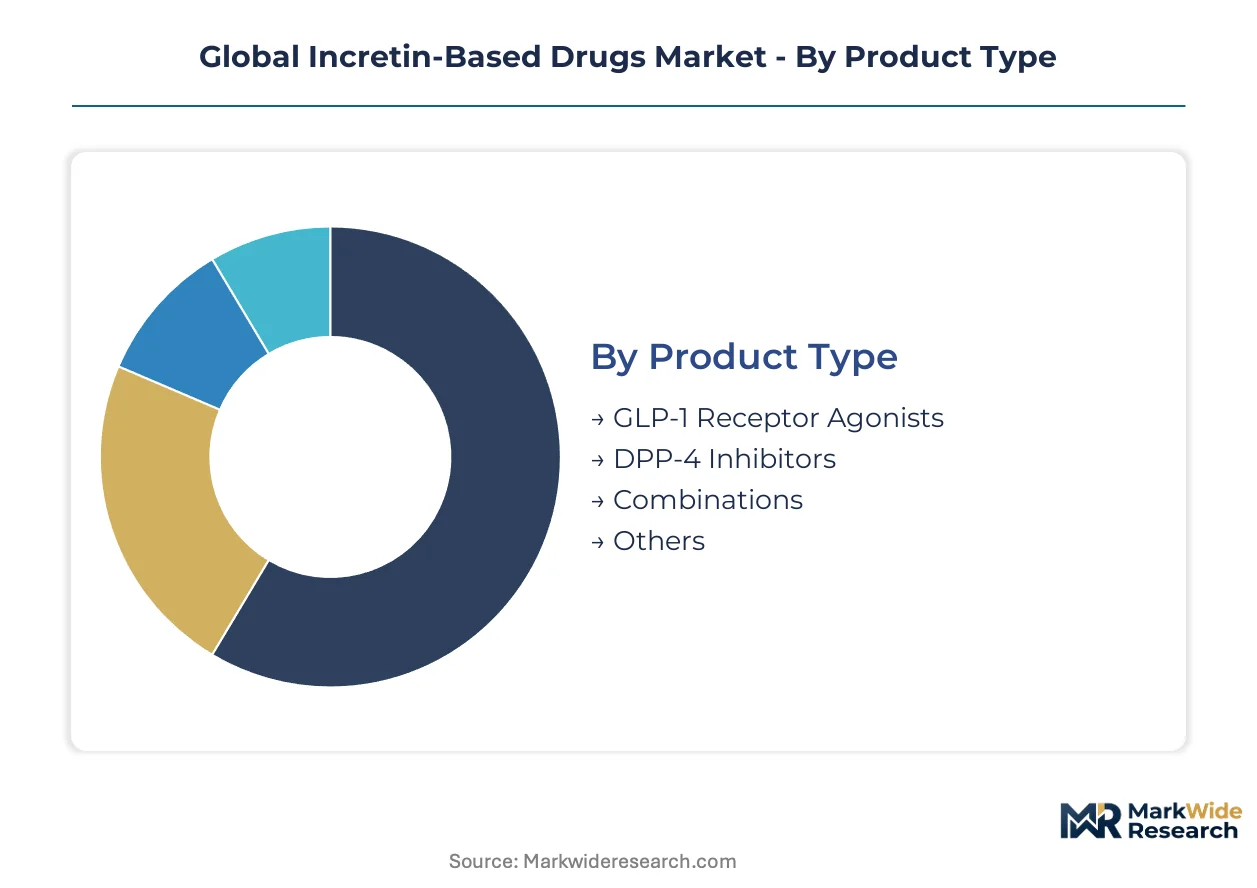
Incretin-based therapeutics fragment across four critical dimensions that determine pricing power, distribution infrastructure, and prescriber access protocols. Product mechanism and delivery mode together dictate cold-chain requirements and manufacturing complexity, while end-user channel and therapy area shape reimbursement negotiation leverage.
Product Type:
Prescriber preference hierarchies concentrate revenue around mechanism-of-action differentiation and cardiovascular outcome data.
- GLP-1 Receptor Agonists:Peptide therapeutics activating glucagon-like peptide-1 receptors deliver superior HbA1c reduction and weight loss profiles. Demand clusters in United States employer-sponsored health plans where weekly injectable formulations command preferred formulary tier placement.
- DPP-4 Inhibitors:Small-molecule enzyme inhibitors blocking dipeptidyl peptidase-4 degradation of endogenous incretin hormones occupy a mature, generic-eroded tier. Price compression across Germany, Japan, and the United Kingdom has redirected R&D investment toward receptor agonist platforms.
- Combinations:Fixed-dose pairings of incretin agents with metformin or SGLT2 inhibitors target polypharmacy reduction in complex type 2 diabetes populations.
- Others:Emerging dual and triple incretin receptor agonists in clinical development represent next-generation metabolic disease targeting.
Volume sits with GLP-1 Receptor Agonists; growth tilts toward Combinations as prescriber protocols favor streamlined therapeutic regimens.
Delivery Mode:
Patient adherence data and cold-chain infrastructure requirements determine channel economics and geographic expansion feasibility.
- Injectable:Subcutaneous peptide formulations requiring 2-8°C distribution anchor current revenue pools. Weekly dosing frequency drives United States volume through reduced discontinuation versus daily alternatives.
- Oral:Small-molecule and peptide-based oral formulations with enhanced bioavailability address injection aversion in Japan and European Union markets where patient preference studies reshape payer coverage criteria.
- Combination:Hybrid delivery systems pairing injectable and oral components target step-therapy protocols in managed care environments.
- Others:Transdermal patches and implantable depot formulations in early-stage development target long-acting delivery without injection burden.
Injectable delivery commands installed revenue base; oral formulations are gaining share fastest as pharmaceutical sponsors prioritize adherence-linked outcomes contracting.
End User:
Channel structure determines rebate negotiation dynamics and patient support program deployment intensity.
- Hospitals:Inpatient and outpatient acute care settings initiate therapy for decompensated diabetes and obesity-related comorbidities. United States health systems concentrate purchasing through group purchasing organizations for GLP-1 agonist procurement.
- Clinics:Specialized endocrinology and obesity management centers in Germany and the United States drive protocol-setting influence through key opinion leader networks.
- Homecare:Self-administered injection training and remote monitoring services expand access beyond traditional clinical settings.
- Pharmacies:Retail and specialty pharmacy channels manage prior authorization workflows and copay assistance program distribution.
Hospital systems anchor procurement volume; clinics are expanding most quickly as obesity management verticals fragment from traditional diabetes care pathways.
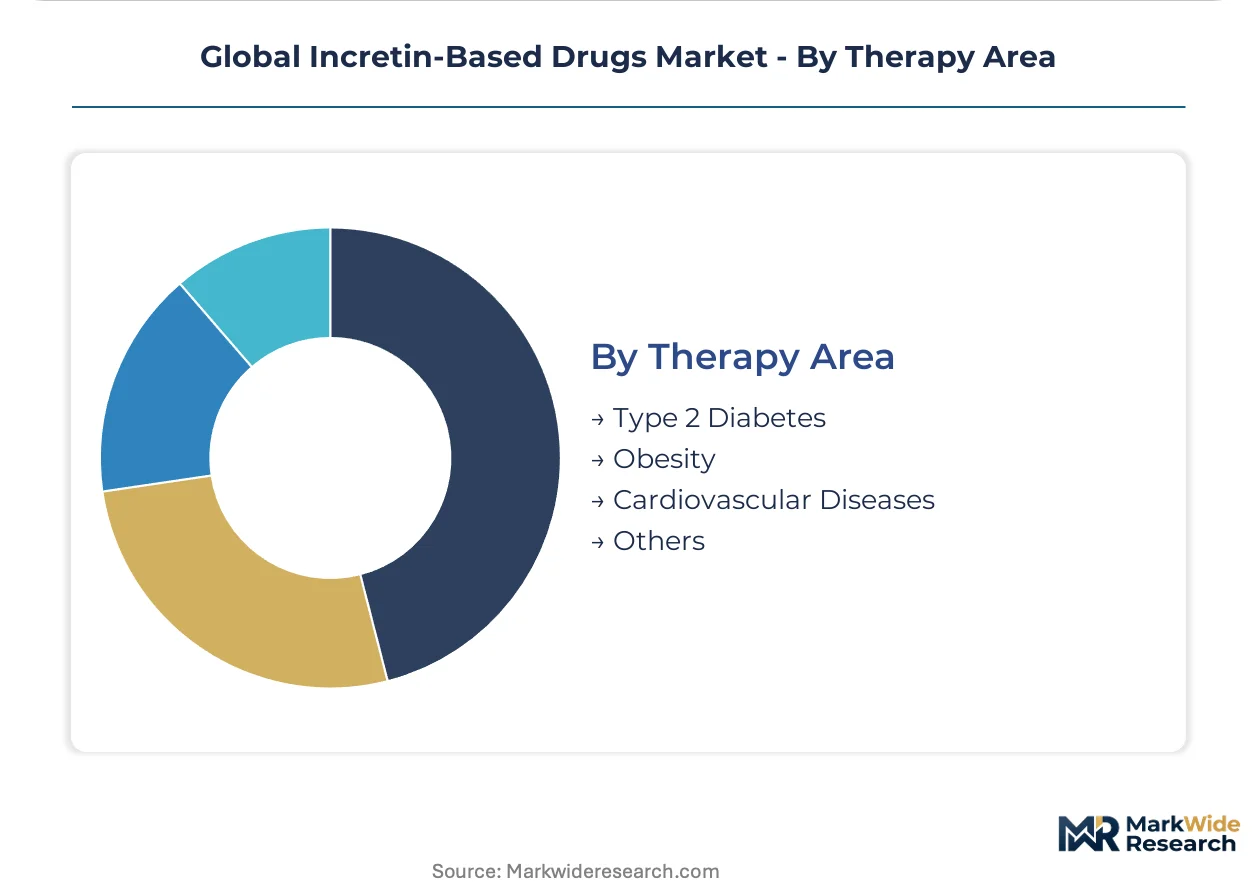
Therapy Area:
Label expansion trajectories and cardiovascular outcome trial results determine addressable population sizing and payer willingness-to-pay thresholds.
- Type 2 Diabetes:Established regulatory pathway with extensive long-term safety data supports broad formulary inclusion across United States, European Union, and Japanese reimbursement systems.
- Obesity:FDA and EMA label expansions for weight management indications have shifted prescriber mindshare and employer pharmacy benefit spend allocation in North American markets.
- Cardiovascular Diseases:Secondary prevention indications based on cardiovascular outcome trial data open risk-based contracting opportunities with integrated delivery networks.
- Others:Non-alcoholic steatohepatitis, chronic kidney disease, and neurodegenerative disorder investigations represent pipeline expansion frontiers.
Type 2 Diabetes retains installed patient base; obesity applications show steepest expansion trajectory as regulatory approvals accumulate across major markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Basel-Stadt, Copenhagen, and Indianapolis concentrate peptide manufacturing capacity through tax-advantaged research facilities and streamlined regulatory pathways. These jurisdictions anchor global supply networks for cold-chain biologics.
United States
Employer-sponsored health plans drive volume for weekly injectable therapies through consolidated pharmacy benefit management contracts. The FDA mandates cardiovascular outcome trials for novel incretin molecular entities, extending pre-approval timelines. Indianapolis hosts concentrated manufacturing infrastructure for large-scale peptide production serving North American distribution networks.
Germany
Specialized obesity management clinics in Munich and Berlin recalibrate therapeutic protocols toward GLP-1 receptor agonists. The EMA pharmacovigilance framework requires periodic safety signal monitoring for long-acting formulations. The Rhine-Ruhr corridor anchors cold-chain logistics hubs distributing temperature-controlled biologics across European Union member states.
Switzerland
Contract manufacturing organizations in Basel-Stadt concentrate active pharmaceutical ingredient synthesis capacity for peptide therapeutics. Swissmedic maintains alignment with EMA cardiovascular safety requirements while offering accelerated assessment pathways for innovative medicines. The Basel biotech cluster houses specialized process engineering talent for recombinant protein purification at scale.
Japan
Patient preference studies in Tokyo and Osaka reshape payer coverage criteria toward oral formulation alternatives. The PMDA requires pediatric investigation plans for metabolic disease therapies entering the Japanese market. The Kansai region hosts clinical trial infrastructure evaluating enhanced bioavailability small-molecules for injection-averse patient populations.
Denmark
Recombinant protein production facilities in Copenhagen leverage specialized fermentation capacity for GLP-1 receptor agonist manufacturing. Danish regulatory authorities coordinate with EMA on REACH authorization requirements for novel biologic substances. The Øresund Region integrates upstream peptide synthesis with downstream purification operations serving European and North American markets.
Global Incretin-Based Drugs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical companies commanding weekly injectable volumes while mid-cap developers compete for oral formulation niches. The vendor base concentrates around three strategic archetypes: large-cap innovators with cardiovascular outcome trial infrastructure, regional generic houses capturing DPP-4 inhibitor erosion value, and specialized biologics contractors with captive peptide synthesis capacity. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and strategic partnerships for multi-jurisdictional label harmonization.
Within the large-cap innovator tier, Novo Nordisk and Eli Lilly occupy positions defined by manufacturing scale and dual-receptor technology leadership respectively. Novo Nordisk anchors the weekly injectable segment through Danish production infrastructure and North American channel control. Eli Lilly represents the convergent incretin pathway activation archetype with GIP/GLP-1 receptor agonist platforms. Sanofi exemplifies sustained commitment to oral formulation research pipelines, competing through differentiated delivery mode strategies rather than mechanism-of-action novelty.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly |
| AstraZeneca |
| Merck & Co. |
| Sanofi |
| Boehringer Ingelheim |
| Novartis AG |
| Takeda Pharmaceutical Company |
| GlaxoSmithKline |
| Others |
Supply Flow & Price Mechanics
Peptide synthesis automation and single-use bioreactor adoption are compressing unit production costs while simultaneously concentrating manufacturing capacity among contract development organizations with validated cold-chain infrastructure. This technological transition elevates capital barriers for new entrants and anchors pricing power with incumbent producers possessing integrated fermentation and purification assets.
Pricing Analysis
Short lead-time premiums for cold-chain biologics command substantial markups over standard distribution schedules, while spot inventory availability in the United States and Germany enables tactical purchasing for hospital systems facing formulary deadlines. Three-tier pricing structure across innovator biologics, biosimilar candidates, and generic DPP-4 inhibitors stratifies the market by cardiovascular outcome data and delivery mode complexity. Cost compression in the oral small-molecule tier is intensifying because of patent cliff dynamics across European markets. Employer-sponsored health plans demonstrate lowest price sensitivity due to outcomes-linked contracting structures, while retail pharmacy channels face highest sensitivity from copay accumulator program expansion.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on specialized fermentation capacity concentrated in Denmark, Switzerland, and the United States, with recombinant protein purification operations tethered to Basel-Stadt and Copenhagen industrial clusters. Critical inputs include recombinant yeast strains, chromatography resins, and single-use bioreactor bags. Single-source vulnerability in peptide synthesis capacity exposes continuity to geopolitical disruption risks. Distribution runs through temperature-controlled logistics networks with 2-8°C validation requirements, anchored by Rhine-Ruhr and Indianapolis cold-chain hubs serving hospital systems and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capacity scarcity for large-scale recombinant protein production is propping pricing power across the weekly injectable segment, constraining volume expansion despite employer plan demand acceleration.
For Market Incumbents: Deploy backward integration into active pharmaceutical ingredient production to secure peptide synthesis capacity against contract manufacturing organization bottlenecks. Consolidate channel control through direct distribution partnerships with obesity management clinics, defending formulary position against dual GIP/GLP-1 receptor agonist entrants. Prioritize cardiovascular outcome trial infrastructure investments to maintain regulatory moats as FDA tightens evidence requirements. For New Entrants and Emerging Players: Digital therapeutics integration platforms represent the most penetrable white-space target, enabling remote patient monitoring and adherence tracking for self-injected therapies. Oral formulation development in Japan and European Union markets offers regulatory differentiation from injectable incumbents. Pursue partnership structures with established European marketing authorization holders to bypass REACH authorization timeline delays. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of specialized biologics contractors with captive peptide synthesis capacity and validated cold-chain infrastructure. Long-term viability in this market hinges on manufacturing scale rather than molecule novelty, favoring asset-heavy positions over pure-play development stories. Watch FDA label expansion decisions for cardiovascular risk reduction indications as the critical inflection signal for reimbursement tier mobility.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive fermentation capacity in Copenhagen and Basel-Stadt secures supply continuity against CMO bottlenecks. |
| Regulatory Approval Pathway | FDA cardiovascular outcome trial completion unlocks employer-sponsored health plan preferred formulary placement. |
| Licensing Agreement | European marketing authorization holder partnerships accelerate REACH compliance for novel biologic substances. |
| Pipeline Diversification | Dual GIP/GLP-1 receptor agonist platforms differentiate from single-mechanism competitors in prescriber protocols. |
| Clinical Trial Advancement | Oral formulation bioavailability studies in Japanese patient populations address injection aversion barriers. |
Methodological Framework
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings in this study. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population sizing and top-down revenue triangulation were reconciled across the analysis window.
Comparable-period anchoring to historical cardiovascular outcome trial completion timelines and regulatory approval cycles structured the forecast framework. Segmentation dimensions modeled include product mechanism, delivery mode, end-user channel, and therapy area across the projection horizon. CAGRs were derived from volume-demand elasticity functions and pricing trajectory assumptions. Forecast inputs incorporated employer pharmacy benefit spend allocation patterns and cold-chain distribution capacity expansion schedules.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time formulary placement data and confidential rebate contracting terms introduce uncertainty bands around volume projections. Forecasts reflect documented assumptions regarding FDA label expansion timing and EMA pharmacovigilance framework evolution. Regulatory approval delays, manufacturing capacity constraints, and payer coverage criteria shifts warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Lupus Nephritis Market
Biopharmaceuticals
Terbinafine Tablet Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
A - Estradiol Market