
 Chemotherapy Drugs Market | 2026-2036
Chemotherapy Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy Drugs Market Outlook
Oncology clinics as an end-user vertical is repositioning procurement patterns toward outpatient-administered oral antimetabolites and subcutaneous formulations. Pfizer Inc. leverages its manufacturing scale across North American and European production networks. F. Hoffmann-La Roche Ltd. anchors its competitive stance through sustained R&D intensity in plant alkaloid derivatives. Bristol-Myers Squibb Company differentiates via specialized immuno-oncology combination protocols that integrate traditional chemotherapy backbones.
Chemotherapy drugs comprise cytotoxic and cytostatic pharmaceutical agents designed to destroy or inhibit rapidly dividing malignant cells, typically synthesized through complex organic chemistry processes involving platinum coordination, nucleoside analog modification, or natural product semi-synthesis, with potency measured by IC50 values against specific cancer cell lines. Alkylating agents and antimetabolites occupy the largest revenue pools due to decades of clinical validation and broad-spectrum applicability across solid tumors and hematologic malignancies. Plant alkaloids represent the fastest-expanding structural category as taxane and vinca alkaloid derivatives gain traction in combination regimens for lung and breast cancer indications. Intravenous delivery mode retains dominant volume share, though oral formulations are capturing margin expansion in homecare and research institution settings where patient convenience drives protocol design.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks compress development timelines while intensifying post-market surveillance obligations for novel cytotoxic agents. REACH and RoHS compliance requirements in Europe constrain excipient sourcing and packaging material selection, directly impacting formulation economics for manufacturers serving multiple geographies. China's NMPA priority review channels for oncology therapies are reshaping launch sequencing decisions among multinational sponsors. Stakeholders must monitor evolving pharmacovigilance mandates and biosimilar substitution policies that threaten branded chemotherapy margins in key reimbursement markets.
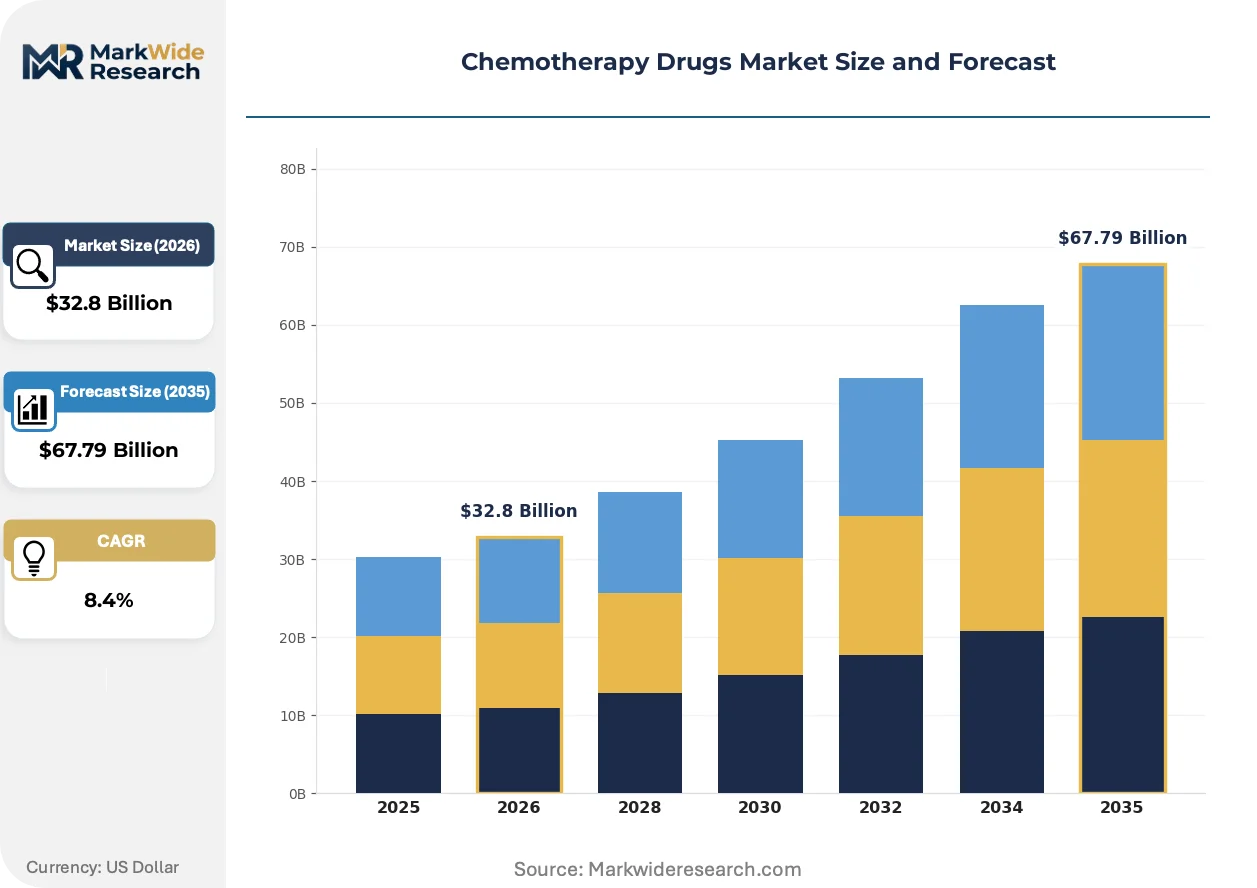
Market Dynamics
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks are compressing development timelines for novel cytotoxic agents while intensifying post-market surveillance obligations across all major jurisdictions.
Growth Catalysts
- Accelerated regulatory pathways:FDA breakthrough therapy designations and EMA priority medicines status compress Phase II-to-approval timelines for first-in-class alkylating agents, enabling faster commercialization of novel mechanisms.
- Outpatient administration shift:Oncology clinics are expanding procurement of oral antimetabolites and subcutaneous formulations that reduce hospital bed utilization while maintaining therapeutic efficacy.
- China's NMPA priority review:Priority review channels for oncology therapies are reshaping launch sequencing decisions among multinational sponsors targeting the world's second-largest pharmaceutical market.
Market Restraints
- Platinum supply concentration:Over 70% of platinum group metal refining occurs in South Africa and Russia, creating input cost volatility for cisplatin and carboplatin manufacturers.
- REACH and RoHS compliance:European chemical safety regulations constrain excipient sourcing and packaging material selection, directly impacting formulation economics for multi-territory manufacturers.
- Biosimilar substitution policies:Mandatory substitution frameworks in Germany and France threaten branded chemotherapy margins as payers prioritize cost containment over originator loyalty.
Strategic Opportunities
- Homecare administration models:Oral chemotherapy protocols are penetrating the United States and United Kingdom homecare segments where reimbursement frameworks now cover remote patient monitoring.
- Antibody-drug conjugate convergence:Cytotoxic payloads are integrating with monoclonal antibody delivery systems, opening new indication spaces in HER2-positive and TROP2-expressing malignancies.
- India's PLI scheme for APIs:Production-linked incentive schemes for active pharmaceutical ingredients are attracting contract manufacturing investment for oncology intermediates.
Industry Challenges
- Good Manufacturing Practice certification timelines:FDA pre-approval inspections and EMA manufacturing authorization reviews are extending launch readiness by 12-18 months for new production facilities.
- Cold chain reconfiguration:Temperature-sensitive biologic-chemotherapy combinations require validated distribution networks that legacy logistics providers cannot support without capital-intensive infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy Drugs Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkylating Agents, Antimetabolites, Plant Alkaloids, Antitumor Antibiotics Indication: Breast Cancer, Lung Cancer, Leukemia, Lymphoma Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Oncology Clinics, Homecare, Research Institutions |
| Companies Covered | Johnson & Johnson Services Inc., Pfizer Inc., F. Hoffmann-La Roche Ltd., Novartis AG, Merck & Co., Inc., Bristol-Myers Squibb Company, AstraZeneca PLC, AbbVie Inc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy Drugs Market Strategic Shifts
Combination immuno-oncology protocols are displacing single-agent chemotherapy as the standard of care across multiple tumor types, forcing reformulation strategies and new clinical trial designs.
Antibody-drug conjugate technology is integrating cytotoxic payloads with tumor-targeting delivery mechanisms to expand the therapeutic index of established agents. Academic medical centers in the United States and Germany are adopting ADC protocols at twice the rate of community oncology practices. This convergence is compressing development timelines for novel payloads while demanding specialized manufacturing capabilities.
EMA's revised pharmacovigilance guidelines and FDA's Project Optimus dose-optimization mandate are reshaping post-market study obligations for cytotoxic agents. Manufacturers must now generate real-world evidence on patient-reported outcomes and quality-of-life metrics beyond traditional efficacy endpoints. Oral chemotherapy formulations face the steepest compliance burden under these frameworks.
Hospital procurement consortia are consolidating purchasing power through centralized tendering mechanisms that unbundle drug acquisition from infusion services. Group purchasing organizations in the United States now control over half of intravenous chemotherapy volume. This concentration is squeezing manufacturer margins while favoring suppliers with integrated distribution networks.
Chemotherapy Drugs Market Segmentation
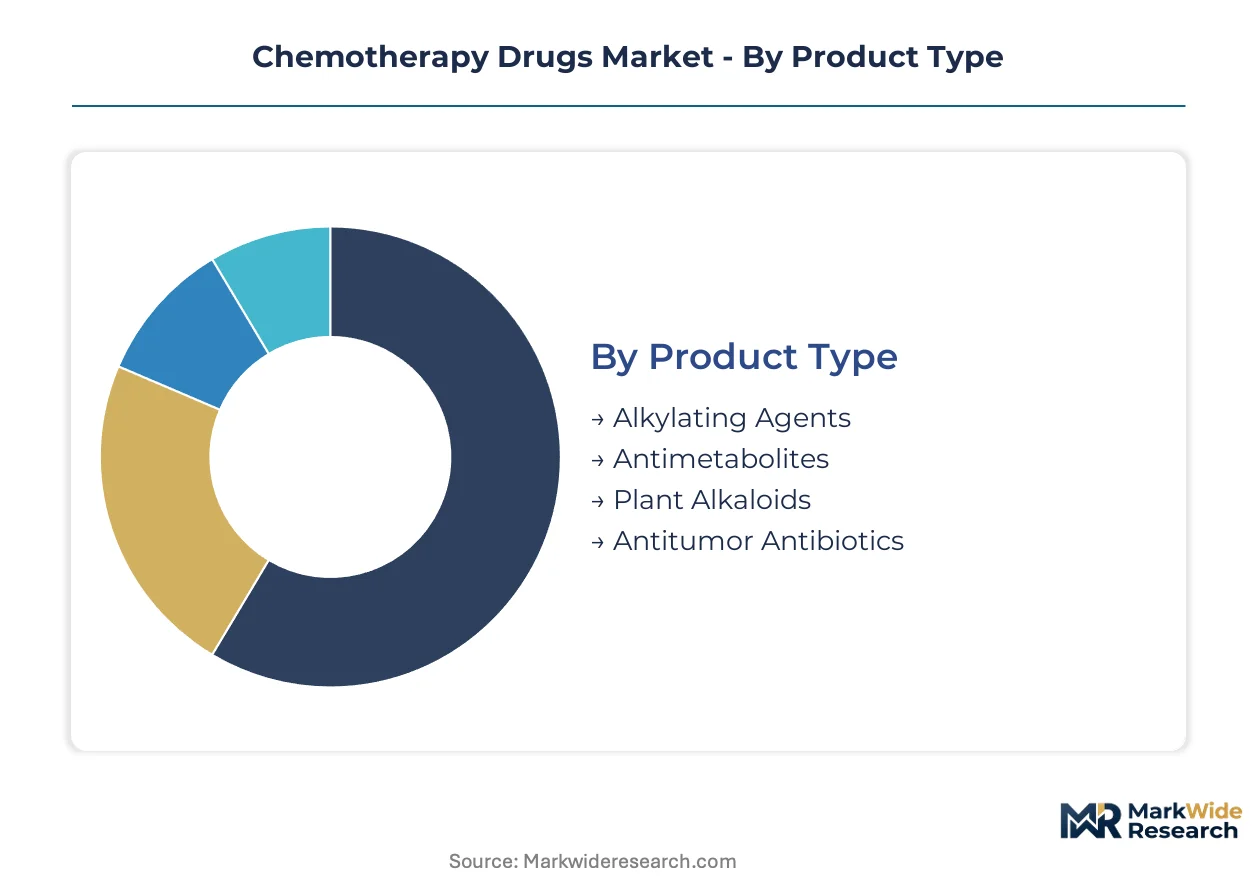
Chemotherapy market segmentation reveals how therapeutic mechanisms, administration logistics, and care settings create distinct procurement ecosystems with divergent margin profiles and regulatory burdens.
Product Type:
Structural chemistry differentiates manufacturing complexity, patent longevity, and combination therapy compatibility across cytotoxic classes.
- Alkylating Agents:Platinum-coordination and nitrogen mustard compounds form DNA crosslinks that arrest cell division. Hospital-based oncology units in the United States and Germany concentrate procurement here for first-line solid tumor protocols, though platinum supply concentration in South Africa and Russia injects raw material volatility.
- Antimetabolites:Nucleoside analogs and folic acid antagonists disrupt DNA synthesis through false substrate incorporation. FDA and EMA accelerated approval pathways compress development timelines for novel antimetabolites, with oral formulations capturing outpatient expansion in oncology clinics.
- Plant Alkaloids:Taxane and vinca derivatives extracted or semi-synthesized from natural sources. Demand climbs fastest in combination regimens for lung and breast cancer indications.
- Antitumor Antibiotics:Anthracyclines and related glycoside compounds intercalate DNA and generate free radicals. Manufacturing depends on fermentation capacity and specialized containment infrastructure.
Volume sits with alkylating agents; growth tilts toward plant alkaloids.
Indication:
Tumor biology drives dosing intensity, combination complexity, and reimbursement tier placement.
- Breast Cancer:Taxane-anthracycline sequential protocols dominate adjuvant settings, with HER2-directed ADC combinations expanding cytotoxic payload demand. United States and China reimbursement frameworks favor high-efficacy neoadjuvant regimens.
- Lung Cancer:Platinum-doublet backbones persist in non-small cell indications despite immunotherapy displacement pressure. Germany and France biosimilar substitution policies threaten branded platinum margins.
- Leukemia:Cytarabine and anthracycline induction regimens concentrate in academic medical centers with specialized supportive care infrastructure.
- Lymphoma:CHOP-variant protocols and novel alkylating agent combinations drive infusion center utilization rates.
Procurement scale favors breast cancer; pipeline investment flows toward lung cancer combination strategies.
Delivery Mode:
Administration route determines site-of-care economics, patient compliance architecture, and cold chain requirements.
- Intravenous:Infusion-dependent formulations requiring clinical supervision and vascular access. Hospital procurement consortia and United States group purchasing organizations control dominant volume share through centralized tendering.
- Oral:Capecitabine and other antimetabolite formulations enabling home administration. United Kingdom and United States reimbursement frameworks now cover remote patient monitoring for oral chemotherapy protocols.
- Subcutaneous:Reduced infusion time and lower healthcare utilization versus intravenous equivalents. Oncology clinics expanding procurement for margin-efficient outpatient administration.
- Intramuscular:Limited applications for depot formulations and specific hormonal adjuvant therapies.
Intravenous retains volume dominance; oral formulations gain share fastest in homecare segments.
End User:
Care setting dictates formulary control, purchasing consortium membership, and protocol standardization depth.
- Hospitals:Comprehensive cancer centers with integrated surgery, radiation, and medical oncology. China's NMPA priority review channels reshape launch sequencing for hospital formulary access.
- Oncology Clinics:Outpatient-focused practices repositioning toward oral antimetabolites and subcutaneous formulations that reduce hospital bed dependency.
- Homecare:Emerging administration model for stable patients on oral protocols. REACH and RoHS compliance requirements in Europe constrain packaging material selection for direct-to-patient distribution.
- Research Institutions:Academic medical centers in the United States and Germany adopting ADC protocols at elevated rates versus community practice.
Hospital systems anchor current volume; oncology clinics and homecare represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones attract contract manufacturing investment for oncology APIs through production-linked incentive schemes that reduce landed costs for multinational sponsors.
United States
Hospital procurement consortia and group purchasing organizations control dominant intravenous chemotherapy volume through centralized tendering mechanisms. FDA accelerated approval pathways compress Phase II-to-approval timelines for novel alkylating agents. Academic medical centers in Boston and Houston adopt antibody-drug conjugate protocols at elevated rates versus community oncology practices.
Germany
Biosimilar substitution policies in statutory health insurance frameworks threaten branded chemotherapy margins as payers prioritize cost containment. EMA conditional marketing authorization frameworks intensify post-market surveillance obligations for cytotoxic agents. The Rhine-Ruhr metropolitan region concentrates manufacturing authorization reviews and GMP certification timelines that extend launch readiness.
China
NMPA priority review channels for oncology therapies reshape launch sequencing decisions among multinational sponsors targeting the world's second-largest pharmaceutical market. Dual carbon goals and environmental compliance standards constrain fermentation capacity expansion for antitumor antibiotics. Shanghai and Suzhou industrial clusters anchor domestic production of platinum-coordination compounds.
India
Production-linked incentive schemes for active pharmaceutical ingredients attract contract manufacturing investment for oncology intermediates and reduce import dependency. CDSCO accelerated approval pathways for oncology therapies compress regulatory timelines for domestic sponsors. Hyderabad and Ahmedabad pharmaceutical corridors concentrate fermentation capacity and specialized containment infrastructure for cytotoxic manufacturing.
United Kingdom
Reimbursement frameworks now cover remote patient monitoring for oral chemotherapy protocols, enabling homecare administration expansion. MHRA post-Brexit regulatory autonomy permits streamlined recognition of EMA marketing authorizations for oncology therapies. The Cambridge-London corridor anchors ADC research institutions and early-phase clinical trial infrastructure.
Chemotherapy Drugs Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with consolidated control over patented cytotoxic agents contrasting fragmented supply for mature generic alkylating agents. Three archetypes dominate: multinational pharmaceutical conglomerates with integrated oncology portfolios, mid-cap biotech specialists focused on novel mechanisms, and emerging-market API-to-formulation integrators. Competitive dynamics center on manufacturing scale defense and regulatory pathway speed rather than price alone.
Within the multinational tier, Pfizer Inc. and F. Hoffmann-La Roche Ltd. occupy positions that exemplify divergent strategic postures toward combination therapy integration. Bristol-Myers Squibb Company represents the immuno-oncology convergence archetype, anchoring competitive commentary on how traditional chemotherapy backbones integrate with biologic protocols. These three entities collectively illustrate the spectrum from manufacturing-scale defense to specialized R&D intensity in cytotoxic agent development.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| AbbVie Inc. |
| Amgen Inc. |
| Others |
Value Chain & Pricing Dynamics
Platinum group metal spot indices cascade through cisplatin and carboplatin manufacturing economics, compressing margin structures for alkylating agent producers while amplifying price volatility premiums for hospital procurement consortia negotiating multi-year supply agreements. Contract manufacturers in India and China absorb input cost swings through volume-tiered pricing structures that reward committed offtake over spot purchasing.
Pricing Analysis
Lead-time compression commands premium positioning, with oncology clinics paying elevated rates for guaranteed delivery windows under six weeks while spot inventory trades at discounted clearing levels. Three-tier pricing structure across premium, standard, and economy levels segments by GMP certification tier and cold chain validation depth. Price differentiation hinges on FDA pre-approval inspection status and REACH compliance documentation completeness. Cost compression in standard-tier oral antimetabolites is intensifying because India's PLI scheme expands API manufacturing capacity. Hospital group purchasing organizations exhibit highest price sensitivity; academic medical centers with ADC protocols demonstrate lowest sensitivity due to payload specialization requirements.
Supply Chain Analysis
Dual-sourcing mandates from United States hospital procurement consortia and European GPOs require qualified backup suppliers for platinum-coordination compounds and fermentation-derived anthracyclines, extending vendor qualification timelines. Manufacturing gravity centers on China for platinum refining and fermentation capacity, India for API intermediates and contract synthesis, and Germany for GMP-certified finishing and packaging. Raw material dependencies encompass platinum group metals from South African and Russian refineries, specialized fermentation substrates for antitumor antibiotics, and nucleoside precursors for antimetabolite synthesis. Single-source vulnerability concentrates in platinum supply given South African electricity grid instability and Russian export restrictions. Distribution runs through cold chain-validated logistics networks serving hospital systems and oncology clinics with temperature-monitored last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EMA pharmacovigilance mandates and FDA Project Optimus dose-optimization requirements erect regulatory moats that favor incumbents with established post-market surveillance infrastructure and specialized manufacturing authorization.
For Market Incumbents: Hedge platinum input volatility through long-term offtake agreements with South African refiners and backward integration into fermentation capacity for antitumor antibiotics. Defensive consolidation should prioritize GMP-certified facilities in Germany's Rhine-Ruhr corridor to compress EMA manufacturing authorization review timelines. Biosimilar substitution policies in France and Germany threaten branded margin structures; counter through ADC payload specialization that escapes commoditization pressure. For New Entrants and Emerging Players: Contract research organizations present the most penetrable channel for initial revenue traction, offering formulation development services to multinational sponsors seeking India's CDSCO accelerated approval pathways. White-space targets include oral chemotherapy homecare protocols in the United Kingdom where MHRA post-Brexit regulatory autonomy streamlines marketing authorization recognition, and subcutaneous formulation manufacturing for United States oncology clinics reducing hospital bed dependency. Go-to-market positioning should emphasize integrated regulatory affairs capabilities spanning FDA, EMA, and NMPA submission requirements. For Investors and Strategic Acquirers: The window for entry favors mid-cap biotech specialists with novel alkylating agent mechanisms and existing FDA breakthrough therapy designations. Long-term viability hinges on manufacturing scale defense rather than pipeline depth alone, given consolidation pressure from group purchasing organization concentration. Acquisition targets should demonstrate captive fermentation capacity or platinum coordination chemistry expertise. The inflection signal to monitor is NMPA priority review channel utilization rates among multinational sponsors, indicating China market access commitment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy and EMA priority medicines status compress Phase II-to-approval timelines for novel cytotoxic mechanisms. |
| Manufacturing Scale-Up | GMP-certified capacity expansion in Germany's Rhine-Ruhr corridor addresses EMA manufacturing authorization bottlenecks. |
| Backward Integration | Captive platinum refining partnerships with South African suppliers mitigate raw material volatility for alkylating agent production. |
| Clinical Trial Advancement | ADC payload combination protocols in United States academic medical centers expand therapeutic index for established cytotoxic agents. |
| Licensing Agreement | India's PLI scheme attracts contract manufacturing investment for oncology API intermediates through production-linked incentives. |
Study Parameters
Multi-period observation of FDA accelerated approval decisions, EMA conditional marketing authorizations, and NMPA priority review grants anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov protocol registries, and formulary database audits. Bottom-up segment sizing triangulated against top-down market aggregation across therapeutic class, administration route, and regional regulatory cluster dimensions.
Segment-weighting approaches assigned differential growth coefficients to oral antimetabolites versus intravenous alkylating agents based on outpatient administration shift velocity and homecare reimbursement expansion trajectories. Modeled dimensions encompassed product type, indication, delivery mode, and end-user care setting across the projection horizon. CAGRs derived from regression analysis of historical approval timelines, pricing trend vectors, and procurement volume shifts. Industry-specific forecast inputs incorporated platinum price index volatility bands and GMP certification queue depth estimates.
Caveats apply where platinum supply disruption from South African electricity instability or Russian export policy shifts could materially shift the outlook for alkylating agent manufacturing economics. Forecasts reflect assumptions regarding sustained reimbursement favorability for high-efficacy protocols in United States and China statutory frameworks. A model refresh is warranted upon material change in biosimilar substitution policy enforcement intensity across Germany and France statutory health insurance systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Fenbendazole Market