
 Global High Purity Quartz Glass Market | 2026-2036
Global High Purity Quartz Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Purity Quartz Glass Market Foresight
Direct supply agreements between quartz refiners and semiconductor foundries are reshaping procurement patterns across the high purity quartz glass value chain. Sibelco leverages its vertically integrated mining-to-refining footprint to secure long-term feedstock commitments. The Quartz Corp anchors North Atlantic supply through its Spruce Pine operations, while Jiangsu Pacific Quartz Co., Ltd dominates domestic distribution across East Asian electronics corridors.
High purity quartz glass consists of silicon dioxide refined to impurity levels below 50 parts per million, typically manufactured through electric fusion of carefully selected crystal feedstock or synthetic chemical vapor deposition to achieve thermal stability up to 1,100 degrees Celsius. Its primary purpose is to contain, transport, or shape materials during high-temperature precision processes where metal contamination would destroy product yield. Fused silica commands the dominant share of semiconductor chamber components due to its superior thermal shock resistance, while synthetic quartz leads growth in photomask substrates where absolute purity dictates lithographic precision. Powder and granule forms capture the bulk volume in crucible manufacturing, whereas quartz tubing margins concentrate in specialty lamp and fiber draw applications.
REACH registration requirements in Europe, RoHS substance restrictions, and China's GB standards for electronic materials collectively elevate compliance costs for producers serving cross-border equipment makers. FDA oversight of laboratory-grade quartzware adds another certification layer for scientific instrument suppliers. Stakeholders must monitor how dual-use export controls on advanced semiconductor equipment redirect quartz glass demand toward alternative fabrication geographies.
Market Dynamics
Semiconductor equipment manufacturers are consolidating their quartz glass supplier bases to secure crucible volumes for advanced node wafer production, compressing qualification timelines and locking in multi-year procurement commitments ahead of capacity ramps.
Growth Catalysts
- GB Standards Compliance:China's mandatory electronic materials certification is accelerating domestic substitution of imported quartzware in wafer fabs across Jiangsu and Zhejiang provinces.
- Synthetic CVD Deposition:Chemical vapor deposition methods for ultra-high purity substrates are capturing photomask applications where natural crystal impurities compromise lithographic yield.
- Dual-Use Export Controls:US Department of Commerce restrictions on advanced lithography equipment are redirecting quartz glass demand toward mature-node fabrication clusters in Southeast Asia and Eastern Europe.
Market Restraints
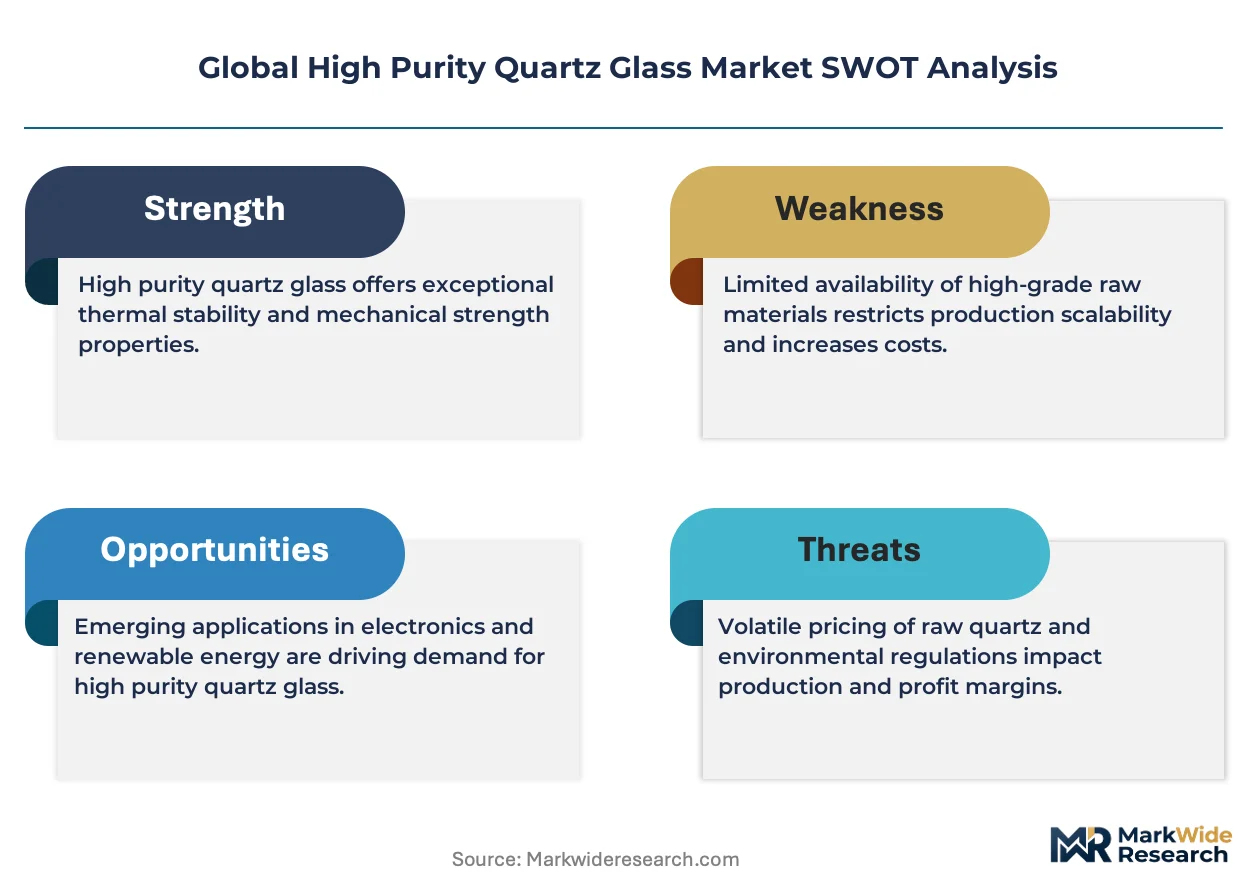
- Spruce Pine Concentration:Overreliance on Appalachian ultra-high purity crystal deposits creates single-source vulnerability for semiconductor-grade feedstock.
- Helium Cost Volatility:Fusion furnace operations depend on helium cooling systems exposed to supply disruptions from Qatar and US federal reserve auctions.
- REACH Registration Burden:ECHA substance data requirements for imported quartzware add twelve-to-eighteen month pre-market compliance timelines for Asian exporters.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor packaging are creating first-mover quartzware demand in Gujarat and Tamil Nadu greenfield sites.
- Recycled Fused Silica:Crucible reclamation streams from decommissioned solar ingot operations are emerging as certified feedstock for secondary semiconductor applications.
- CE Marking Fast-Track:Harmonized European conformity assessment routes for pre-qualified medical device quartz components are compressing time-to-revenue for laboratory instrument suppliers.
Industry Challenges
- High-Temperature Metrology Talent:Scarce expertise in thermal expansion characterization for 1,100°C+ applications is extending R&D cycles at specialty glass houses.
- Multi-Jurisdiction Certification:Simultaneous FDA, REACH, and GB standard compliance is forcing redundant testing protocols that consume eighteen-to-twenty-four months per product line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Purity Quartz Glass Market |
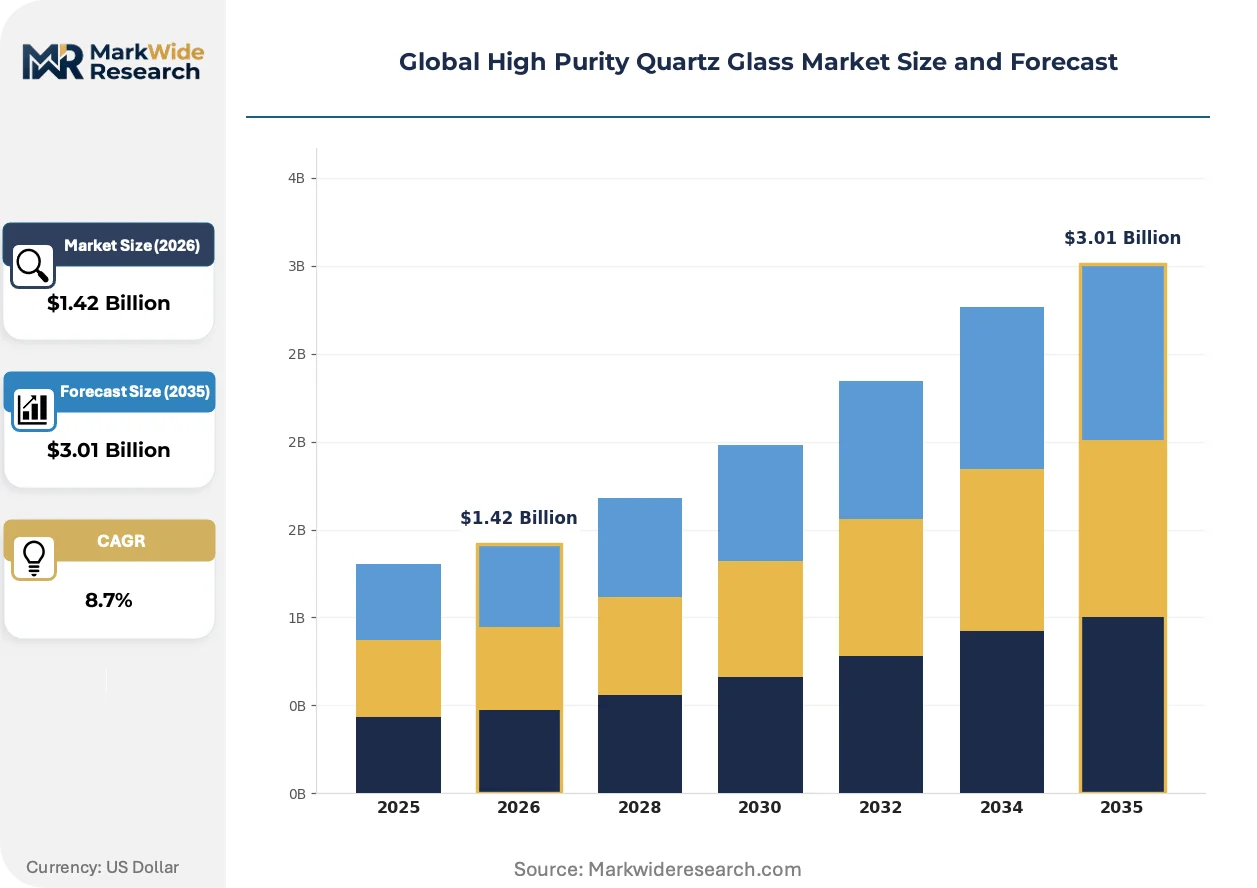
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Quartz, Fused Silica, Synthetic Quartz, Quartz Tubing, Quartz Plates Form: Powder, Granules, Blocks, Rods, Films Application: Semiconductor Manufacturing, Optical Fibers, Solar Panels, Laboratory Equipment, Lighting Solutions End User Industry: Electronics Fabricators, Photonics Specialists, Renewable Energy Producers, Scientific Institutions, Illumination Technology Providers |
| Companies Covered | Sibelco, The Quartz Corp, Jiangsu Pacific Quartz Co., Ltd, Momentive Technologies, Russian Quartz LLC, Australian Silica Quartz Group Ltd, Nordic Mining ASA, Imerys, Heraeus Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Purity Quartz Glass Market Shifts & Advancements
Synthetic manufacturing routes and regulatory traceability mandates are restructuring how quartz glass moves from raw crystal to semiconductor chamber components.
Plasma-enhanced chemical vapor deposition of silicon dioxide is collapsing the purity gap between synthetic and natural quartz for photomask substrates. Leading lithography equipment buyers in Japan and the Netherlands are qualifying synthetic blanks at 10 parts per billion metal impurity levels. This synthetic route is collapsing premium pricing tiers that historically separated natural crystal premiums from standard fused silica grades.
REACH Article 33 disclosure obligations now mandate supply chain communication of Substances of Very High Concern above 0.1% weight concentration in finished quartzware. European semiconductor equipment OEMs are forcing upstream crystal refiners to implement batch-level chemical fingerprinting. Photovoltaic crucible manufacturers serving European module assemblers face the steepest documentation burden under this expanded due diligence framework.
Direct mill-to-fab contracting is displacing distributor intermediaries for high-volume crucible procurement. Tier-one foundries in Taiwan and South Korea are negotiating five-year take-or-pay agreements that guarantee furnace-ready blank supply. This channel compression is most visible in 300mm silicon ingot operations where crucible failure costs exceed $50,000 per thermal cycle interruption.
Global High Purity Quartz Glass Market Segmentation
Segmentation in high purity quartz glass reveals divergent replacement cycles and margin structures across material grades and end-use applications. Semiconductor chamber components turn over in months while photonics substrates operate for years, creating distinct inventory and pricing dynamics for suppliers.
Product Type:
Cycle times vary dramatically by material purity and thermal duty, with synthetic deposition routes commanding longest qualification periods while fused silica crucibles rotate fastest in volume production.
- Fused Silica:Electrically fused natural crystal refined to sub-50 ppm impurity levels delivers superior thermal shock resistance for rapid thermal processing chambers. Demand concentrates in Taiwan and South Korea where 300mm wafer fabs prioritize crucible durability under repeated thermal cycling.
- Synthetic Quartz:Chemical vapor deposition achieves 10 ppb metal purity for photomask substrates where lithographic precision dictates absolute contamination control. Japanese and Dutch lithography equipment buyers are qualifying synthetic blanks fastest as natural crystal premiums erode.
- Fused Quartz:Lower-purity fused material serves lamp envelopes and industrial sight glasses with shorter qualification timelines.
- Quartz Tubing:Hollow cylindrical forms dominate fiber draw towers and specialty lamp architectures.
- Quartz Plates:Flat polished substrates anchor optical windows and diffusion furnace liners.
Fused silica anchors the volume base while synthetic quartz gains share at the steepest rate.
Form:
Physical configuration determines handling economics and downstream processing steps, with bulk powders moving through automated crucible lines while precision rods require diamond grinding.
- Powder:Fine particulate feedstock below 100 micron diameter feeds automated isostatic pressing for semiconductor crucible bodies. Chinese wafer fabs in Jiangsu province are scaling powder consumption fastest as domestic ingot capacity expands.
- Granules:Coarse crushed crystal between 1-10 mm enables rapid furnace loading and controlled fusion profiles for large-diameter tubing. European lamp manufacturers prefer Spruce Pine-sourced granules for UV transmission consistency.
- Blocks:Massive raw crystal sections await CNC machining into custom chamber components.
- Rods:Pulled cylindrical stock feeds precision grinding for optical fiber preform cores.
- Films:Thin deposited layers serve specialty optical coatings and MEMS substrates.
Powder and granules together dominate tonnage throughput while films exhibit the most rapid expansion trajectory.
Application:
End-use thermal environments create divergent purity thresholds, with diffusion furnaces tolerating higher alkali content than plasma etch chambers.
- Semiconductor Manufacturing:Wafer processing equipment demands the highest purity grades for epitaxial deposition, plasma etching, and thermal oxidation steps. Foundries in Hsinchu and Pyeongtaek are locking in five-year crucible supply agreements ahead of capacity ramps.
- Solar Panels:Photovoltaic ingot growth requires large-volume crucibles with moderate purity tolerance where cost efficiency outweighs extreme contamination control. Decommissioned solar crucibles are re-entering supply chains as certified secondary feedstock.
- Optical Fibers:Preform manufacturing depends on ultra-low hydroxyl content for infrared transmission.
- Laboratory Equipment:Analytical instruments and reaction vessels face FDA oversight for clinical diagnostics.
- Lighting Solutions:UV and halogen lamp envelopes prioritize thermal stability over semiconductor-grade purity.
Semiconductor manufacturing anchors revenue concentration while solar applications expand most quickly in absolute volume terms.
End User Industry:
Customer technical capabilities determine specification stringency, with photonics specialists imposing metrology requirements that illumination providers bypass.
- Electronics Fabricators:Integrated device manufacturers and pure-play foundries drive crucible qualification protocols and multi-year procurement commitments. Taiwan Semiconductor Manufacturing and Samsung Foundry are consolidating supplier bases to three approved quartzware vendors per furnace type.
- Photonics Specialists:Optical component houses demand batch-level chemical fingerprinting for laser cavity materials and fiber draw towers. Japanese coherent source manufacturers require 0.1 ppb iron certification for ultraviolet laser windows.
- Renewable Energy Producers:Solar ingot growers prioritize unit economics over trace element specification.
- Scientific Institutions:Research laboratories source certified analytical grade ware for trace element analysis.
- Illumination Technology Providers:Lamp manufacturers source standard fused quartz for thermal envelope applications.
Electronics fabricators command pricing power through volume consolidation while photonics specialists drive the steepest purity requirement escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo deepwater port corridor underwrites China's dominance in high purity quartz glass procurement, handling inbound Spruce Pine crystal feedstock and outbound finished crucibles for wafer fabs across East Asia.
China
Domestic wafer fabs in Jiangsu and Zhejiang provinces are scaling 300mm ingot capacity fastest. GB standards compliance for electronic materials is accelerating substitution of imported quartzware. The Yangtze River Delta cluster around Hsinchu-facing suppliers is locking in five-year take-or-pay crucible contracts.
United States
Appalachian ultra-high purity crystal deposits near Spruce Pine anchor Western semiconductor feedstock security. FDA oversight of laboratory-grade quartzware adds certification layers for scientific instrument suppliers. The Carolina-Virginia mining belt faces helium cost volatility from federal reserve auction disruptions.
Germany
Lithography equipment OEMs in Aachen and Oberkochen drive photomask substrate qualification timelines. REACH Article 33 disclosure obligations mandate batch-level chemical fingerprinting from upstream refiners. The Rhine-Ruhr industrial corridor concentrates specialty lamp and fiber draw tower demand.
Japan
Coherent source manufacturers require 0.1 ppb iron certification for ultraviolet laser windows. METI industrial policy supports synthetic quartz deposition R&D for next-generation lithography blanks. The Nagoya-Osaka manufacturing belt hosts the densest photonics specialist clustering outside Taiwan.
South Korea
Samsung Foundry and SK Hynix are consolidating approved quartzware vendors to three per furnace type. Dual-use export controls on advanced lithography equipment are redirecting procurement toward mature-node process tools. The Pyeongtaek semiconductor complex is negotiating direct mill-to-fab contracting for crucible supply security.
Global High Purity Quartz Glass Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The supplier base concentrates around vertically integrated mining-to-refining operations and synthetic deposition specialists. Three archetypes dominate: Appalachian crystal miners with captive refining assets, European synthetic substrate developers, and Chinese domestic distributors leveraging GB certification speed. Competitive moves center on backward integration into ultra-high purity feedstock and multi-year procurement lock-ins with foundry customers.
Within the integrated mining-refining tier, Sibelco and The Quartz Corp exemplify archetypes of geographically anchored supply security. Jiangsu Pacific Quartz Co., Ltd occupies a position representing domestic Chinese distribution scale. These three entities illustrate how competitive positioning stratifies between feedstock control, regional certification access, and foundry relationship depth.
| Leading Market Players |
|---|
| Sibelco |
| The Quartz Corp |
| Jiangsu Pacific Quartz Co., Ltd |
| Momentive Technologies |
| Russian Quartz LLC |
| Australian Silica Quartz Group Ltd |
| Nordic Mining ASA |
| Imerys |
| Heraeus Holding |
| Others |
Supply & Pricing Matrix
Helium cost volatility from Qatar supply disruptions and US federal reserve auction instability compresses margin spreads between synthetic deposition routes and electric fusion methods while simultaneously forcing foundries toward long-term procurement lock-ins that reshape inventory positioning across the value chain.
Pricing Analysis
Volume-discount tiering structures separate photomask-grade synthetic blanks from standard fused silica crucibles and economy-grade lamp tubing, with price differentiation driven by metal impurity certification thresholds and five-year take-or-pay contract scale. Cost compression in semiconductor-grade feedstock is intensifying because Appalachian crystal miners face helium cooling expense escalation. Solar ingot growers in Jiangsu province exhibit the highest price sensitivity, while Dutch lithography equipment OEMs show minimal elasticity for 10 ppb purity substrates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning as dual-use export controls on advanced lithography equipment redirect quartz glass flows toward Southeast Asian and Eastern European fabrication clusters. Raw material sourcing draws from Appalachian ultra-high purity crystal deposits, Qatari helium reserves, and synthetic deposition precursors from Japanese chemical suppliers. Single-source vulnerability at Spruce Pine creates systemic risk for semiconductor-grade feedstock security. Distribution runs through direct mill-to-fab contracting that displaces distributor intermediaries for high-volume crucible procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry consolidation to three approved quartzware vendors per furnace type across Taiwan and South Korea has shifted bargaining power decisively toward buyers, compressing supplier margins and accelerating qualification timeline pressures.
For Market Incumbents: Build captive feedstock moats through backward integration into ultra-high purity crystal mining assets or synthetic deposition R&D partnerships. Secure five-year take-or-pay agreements with Hsinchu and Pyeongtaek foundries before capacity ramps lock in competitor volumes. Counter synthetic quartz substitution threats by accelerating batch-level chemical fingerprinting capabilities for REACH Article 33 compliance.
For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Tamil Nadu greenfield packaging sites where Production-Linked Incentive schemes create first-mover quartzware demand without entrenched incumbent relationships. Target recycled fused silica certification from decommissioned solar ingot operations as secondary feedstock for mature-node semiconductor applications. Pursue CE marking fast-track pathways for pre-qualified medical device quartz components to compress time-to-revenue.
For Investors and Strategic Acquirers: REACH Article 33 disclosure obligations reshapes the acquisition landscape toward upstream refiners with implemented batch-level chemical fingerprinting systems. Five-to-ten year viability favors synthetic deposition specialists over natural crystal-dependent miners given purity convergence trends. Monitor qualification velocity at Japanese and Dutch lithography equipment buyers as the inflection indicator for synthetic quartz premium erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ultra-High Purity Feedstock | Sibelco's mining-to-refining footprint secures long-term supply commitments from semiconductor foundries. |
| Synthetic CVD Deposition Scale-Up | Momentive Technologies expands photomask substrate capacity as Japanese buyers qualify 10 ppb metal purity blanks. |
| Long-Term Take-or-Pay Contracting | Taiwan Semiconductor Manufacturing locks in five-year crucible supply ahead of 300mm capacity ramps. |
| Recycled Fused Silica Certification | Decommissioned solar ingot crucibles re-enter supply chains as certified secondary feedstock for mature-node applications. |
| CE Marking Fast-Track Pathway | Harmonized European conformity assessment compresses time-to-revenue for laboratory instrument quartzware suppliers. |
Research Methodology
A spread of perspectives from quartz refinery technical directors, semiconductor foundry procurement leads, lithography equipment OEM supply chain managers, and REACH compliance consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs trade data, SEC 10-K filings of listed mining companies, ECHA substance registration databases, and GB standards certification records. Bottom-up crucible volume estimates from Jiangsu and Zhejiang wafer fabs triangulated against top-down semiconductor capital expenditure disclosures.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning material purity grade, physical form factor, end-use thermal environment, and regional regulatory cluster. CAGRs were derived from installed base growth rates for 300mm wafer processing equipment and synthetic quartz qualification velocity at photomask substrate buyers. Forecast inputs incorporated helium auction price trajectories and dual-use export control redirection effects on fabrication geography.
Sensitivities concentrate around Spruce Pine supply disruption scenarios, synthetic deposition cost parity achievement, and India PLI scheme implementation pace. Forecasts reflect assumptions about qualification timeline compression and buyer consolidation sustainability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Fiber-Optic Filters Market
Optics
Optical Microscope Market
Optics
North America Optical Imaging Market
Optics
Sports Optics Market
Optics
Optical Imaging Market
Optics
Optical Sensing Market
Optics
Europe Laser Interferometer Market
Optics
Glass Scintillator Market
Optics
Global Enhanced Vision System Market
Optics
Smartphone Camera Lenses Market
Optics
MEMS Mirrors Market
Optics
Advanced Optics Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Global Fiber Optic Components Market
Optics
Fiber Optic Development Tools Market
Optics
Residential 1080P Laser Television Projector Market