
 Middle East and Africa Optical Imaging Market | 2026-2036
Middle East and Africa Optical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Optical Imaging Market Foresight
High-resolution spectral specification tiers is reorganizing procurement priorities across Middle East and Africa healthcare networks. Carl Zeiss Meditec AG leverages its established service infrastructure across Gulf hospital chains to sustain recurring revenue streams. Heidelberg Engineering GmbH anchors its position through specialized retinal imaging platforms that dominate academic medical centers. Topcon Corporation competes aggressively on ophthalmic diagnostic bundles, extending its footprint into North African markets through distributor partnerships.
Optical imaging encompasses systems that capture, process, and analyze electromagnetic radiation in the visible through near-infrared spectrum, typically employing charge-coupled device or complementary metal-oxide semiconductor sensors with spatial resolutions reaching sub-micron scales. These instruments serve primarily to enable non-invasive visualization of biological tissues, material microstructures, and environmental samples for diagnostic, analytical, or quality assurance purposes. Microscopes and endoscopes command the largest installed base across the region's healthcare infrastructure, though fluorescence imaging technology generates disproportionate margin pools due to its specialized reagent and service attach rates. The industrial sector application segment exhibits the steepest trajectory as Gulf petrochemical and semiconductor fabrication facilities adopt automated optical inspection protocols.
Saudi Food and Drug Authority and South African Health Products Regulatory Authority device registration requirements shape market entry timelines and clinical evidence standards for optical imaging equipment across their respective jurisdictions. The African Medicines Agency's emerging harmonization framework will consolidate technical documentation demands for manufacturers seeking multi-country distribution. Stakeholders must monitor divergent reimbursement pathways between Gulf state insurance mandates and South Africa's public procurement mechanisms to optimize market access investments.
Market Dynamics
High-resolution spectral specification tiers are reorganizing procurement priorities across Middle East and Africa healthcare networks, forcing distributors to restructure service attach rates and clinical training bundles around performance-based contracts rather than capital equipment sales alone.
Growth Catalysts
- Gulf hospital chain expansion:Healthcare providers across Saudi Arabia and the United Arab Emirates are building specialized diagnostic infrastructure, creating concentrated demand for ophthalmology and retinal imaging platforms.
- SFDA registration streamlining:Saudi Food and Drug Authority device approval pathways are accelerating market entry timelines for manufacturers with established clinical evidence packages.
- Fluorescence imaging reagent pull-through:Specialized consumable and service attach rates on fluorescence platforms generate recurring revenue streams that offset capital equipment margin compression.
Market Restraints
- Import duty volatility on optical sensors:Charge-coupled device and complementary metal-oxide semiconductor component costs fluctuate with currency exposure across Egyptian and Nigerian procurement channels.
- Technical limitation in ambient light interference:Near-infrared imaging systems face performance degradation in uncontrolled clinical environments prevalent in secondary care facilities.
- Substitution threat from portable ultrasound:Point-of-care diagnostic devices capture share in resource-constrained settings where optical infrastructure investment is deferred.
Strategic Opportunities
- Underpenetrated North African markets:Morocco and Algeria present white space for distributor partnership models replicating Topcon Corporation's regional expansion playbook.
- African Medicines Agency harmonization:Emerging technical documentation consolidation reduces multi-country registration burdens for manufacturers seeking pan-African distribution.
- Industrial semiconductor fabrication adoption:Gulf petrochemical facilities are deploying automated optical inspection protocols, opening non-healthcare revenue verticals.
Industry Challenges
- Biomedical optics specialist scarcity:Retinal imaging platform maintenance and clinical application training face talent gaps in South Africa's public health system.
- Legacy PACS integration complexity:New spectral imaging systems require middleware development to interface with existing picture archiving infrastructure in academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Optical Imaging Market |
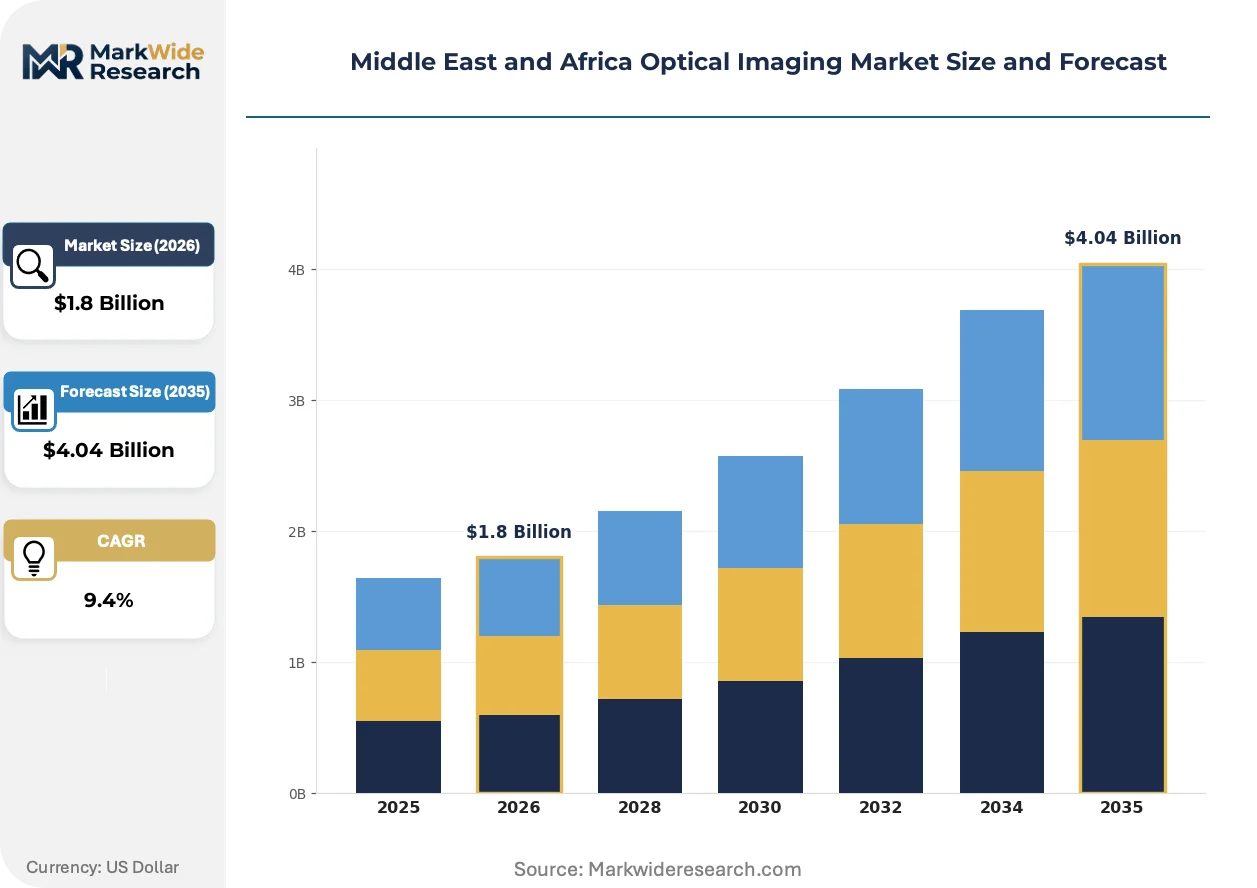
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Cameras, Spectrometers, Microscopes, Endoscopes Technology: Fluorescence Imaging, Light Field Technology, 3D Imaging, Multispectral Imaging End User: Healthcare, Research Laboratories, Industrial Sector, Education Application: Biological Imaging, Material Analysis, Quality Control, Environmental Monitoring |
| Companies Covered | Carl Zeiss Meditec AG, Heidelberg Engineering GmbH, Topcon Corporation, Abbott Laboratories, Nikon Corporation, Olympus Corporation, Hamamatsu Photonics, OPTO GmbH, Revenio Group Oyj, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Optical Imaging Market Shifts & Advancements
Spectral imaging architectures are compressing hardware footprints while expanding diagnostic utility, reshaping how Gulf healthcare networks deploy capital equipment across centralized and distributed care models.
Confocal laser scanning microscopy is supplanting conventional widefield imaging in retinal disease staging protocols. Saudi Arabian academic medical centers are adopting these platforms at accelerated procurement cycles compared to general hospitals. The technology is supplanting longitudinal follow-up visit frequencies by enabling single-session comprehensive microstructural assessment.
South African Health Products Regulatory Authority clinical evidence requirements are tightening equivalence demonstration standards for optical imaging device registrations. Manufacturers must now submit expanded biocompatibility and electromagnetic compatibility testing protocols. Ophthalmic diagnostic bundles face extended review timelines, compressing revenue recognition schedules for distributors.
Service unbundling from capital sales is restructuring buyer-supplier relationships across United Arab Emirates hospital chains. Procurement departments now negotiate preventive maintenance and software upgrade contracts separately from hardware acquisition. This pattern is most visible in Dubai's private healthcare sector, where asset-light operating models dominate capital planning.
Middle East and Africa Optical Imaging Market Segmentation
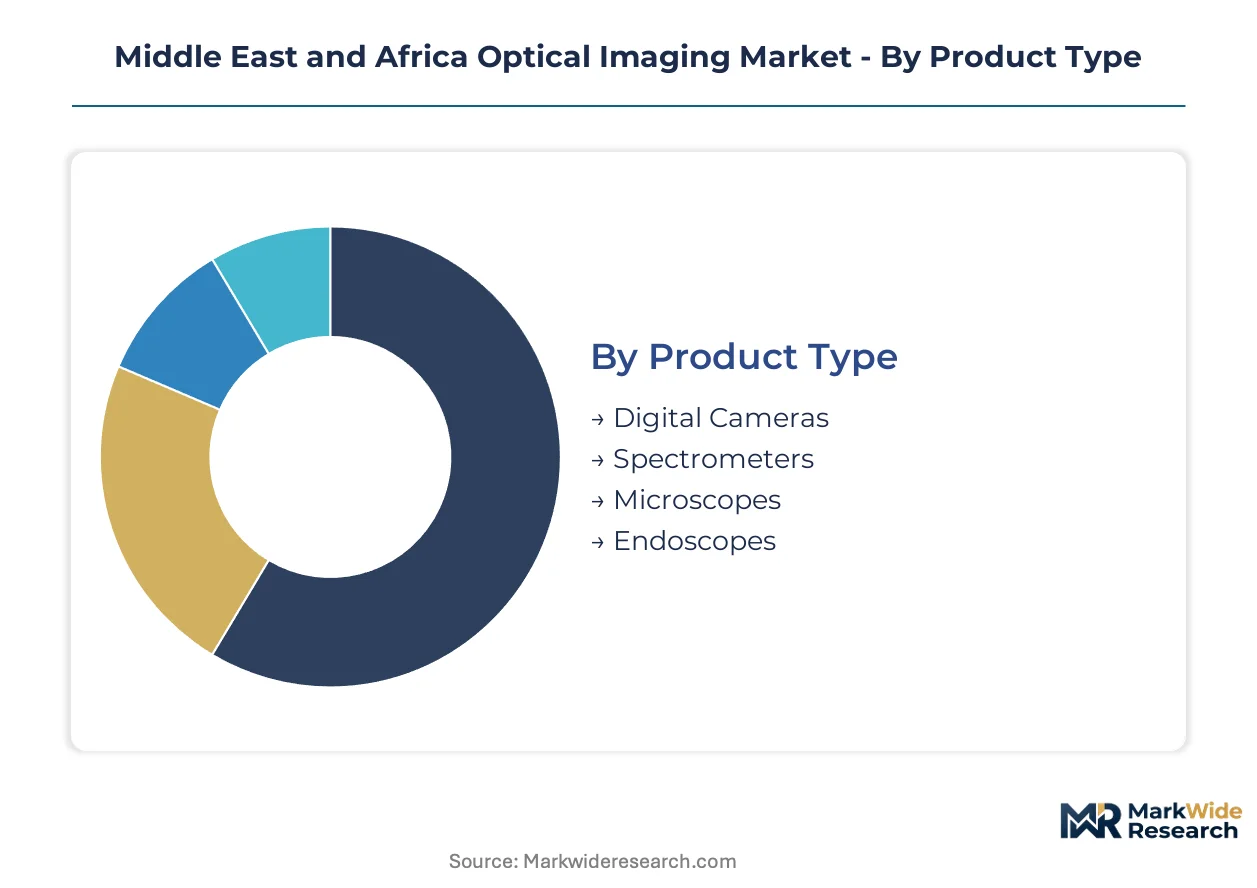
Optical imaging procurement across the Middle East and Africa fragments across distinct technical specifications, end-use requirements, and channel economics. Each segment category channels through different distribution pathways—from Gulf hospital chain tenders to South African academic procurement frameworks—shaping margin capture and service attach strategies for equipment vendors.
Product Type:
Hospital procurement departments in Saudi Arabia and the United Arab Emirates route capital equipment purchases through centralized tenders, while research laboratories in South Africa favor direct manufacturer relationships for specialized microscopy platforms.
- Microscopes:Compound and stereo configurations with sub-micron resolution capabilities dominate academic medical center installations across Gulf Cooperation Council states. Saudi Arabian ophthalmology departments concentrate demand for confocal variants that enable single-session retinal microstructural assessment, compressing longitudinal follow-up frequencies.
- Endoscopes:Flexible and rigid optical scopes with integrated charge-coupled device sensors command the largest installed base across the region's secondary care infrastructure. South African public health facilities face maintenance talent gaps that constrain utilization rates despite equipment availability.
- Digital Cameras:Industrial-grade machine vision cameras with near-infrared sensitivity serve automated optical inspection protocols in Gulf petrochemical fabrication facilities.
- Spectrometers:Benchtop and portable units for material composition analysis flow primarily through distributor networks into North African industrial quality control laboratories.
By volume, endoscopes lead procurement tallies across Middle East and Africa healthcare networks. By growth pace, microscopes are climbing the fastest as Saudi academic medical centers accelerate specialized diagnostic infrastructure buildouts.
Technology:
Margin structures vary sharply across technology tiers—capital-intensive hardware platforms compete against reagent-dependent systems with recurring revenue profiles that alter distributor investment priorities.
- Fluorescence Imaging:Excitation-emission systems utilizing specialized dye chemistry and filter architectures generate disproportionate margin pools through consumable pull-through and service attach rates. Dubai's private hospital chains now unbundle preventive maintenance contracts from hardware acquisition, restructuring supplier relationships around performance-based recurring revenue.
- 3D Imaging:Stereoscopic and computed tomography reconstruction platforms enable volumetric tissue assessment without invasive biopsy protocols. Research laboratories in South Africa concentrate adoption for biological specimen archiving, though legacy PACS integration complexity delays deployment timelines.
- Multispectral Imaging:Discrete wavelength capture systems serve environmental monitoring applications across North African agricultural research stations.
- Light Field Technology:Plenoptic camera arrays for post-capture focus adjustment remain concentrated in Gulf academic demonstration facilities with limited clinical translation.
By installed base, fluorescence platforms dominate retinal disease staging protocols across Saudi Arabian academic medical centers. By margin contribution per unit, 3D imaging systems are gaining share fastest as volumetric diagnostic protocols displace conventional planar assessment.
End User:
Customer-type concentration determines service infrastructure requirements—healthcare networks demand 24-hour technical response capabilities while industrial buyers prioritize throughput optimization consulting.
- Healthcare:Hospitals and specialty clinics across the Gulf Cooperation Council drive concentrated demand for ophthalmology and diagnostic imaging capacities. SFDA registration streamlining accelerates market entry timelines for manufacturers with established clinical evidence packages, though biomedical optics specialist scarcity constrains platform maintenance in South Africa's public system.
- Industrial Sector:Petrochemical and semiconductor fabrication facilities deploy automated optical inspection protocols, opening non-healthcare revenue verticals with distinct procurement cycles and technical specifications.
- Research Laboratories:Academic medical centers and agricultural institutes concentrate multispectral and fluorescence platform adoption for biological specimen analysis.
- Education:University teaching hospitals and technical training institutes represent price-sensitive volume demand for entry-level microscopy configurations.
By revenue concentration, healthcare anchors procurement value across Middle East and Africa optical imaging markets. By expansion trajectory, the industrial sector exhibits the steepest growth as Gulf fabrication facilities automate quality assurance protocols.
Application:
Use-case specificity shapes technical specification requirements—biological applications demand spectral precision while environmental monitoring prioritizes field portability and ambient light tolerance.
- Biological Imaging:Cellular and tissue visualization protocols in clinical diagnostics and life science research require sub-micron spatial resolution and specialized fluorescent probe compatibility. Confocal laser scanning architectures are supplanting conventional widefield systems in Saudi Arabian retinal disease staging, enabling comprehensive microstructural assessment within single clinical sessions.
- Quality Control:Automated defect detection in manufacturing processes drives machine vision camera deployment across Gulf industrial zones.
- Material Analysis:Spectroscopic composition verification serves petrochemical and semiconductor fabrication quality assurance.
- Environmental Monitoring:Field-deployable multispectral systems face performance degradation from ambient light interference in uncontrolled settings prevalent across secondary care facilities and agricultural stations.
By procedural volume, biological imaging leads application demand across Middle East and Africa healthcare infrastructure. By technology refresh rates, quality control applications are expanding most quickly as industrial automation protocols proliferate through Gulf manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese optical equipment manufacturers export precision imaging systems to Gulf hospital chains and South African academic medical centers, establishing trade corridors that shape procurement patterns across the Middle East and Africa.
Saudi Arabia
Riyadh and Jeddah hospital chains are expanding ophthalmology departments with confocal laser scanning platforms. The Saudi Food and Drug Authority has streamlined device registration pathways for manufacturers with established clinical evidence packages. King Faisal Specialist Hospital anchors demand concentration in the capital region.
United Arab Emirates
Dubai's private healthcare sector drives service unbundling trends, with procurement departments negotiating preventive maintenance contracts separately from hardware acquisition. The Ministry of Health and Prevention oversees device registration harmonization across emirates. Cleveland Clinic Abu Dhabi and Dubai Healthcare City concentrate specialized diagnostic infrastructure investment.
South Africa
Academic medical centers in Johannesburg and Cape Town favor direct manufacturer relationships for specialized microscopy platforms. The South African Health Products Regulatory Authority has tightened equivalence demonstration standards for optical imaging device registrations. The Western Cape biomedical research corridor faces biomedical optics specialist scarcity that constrains platform maintenance.
Israel
Medical technology clusters in Tel Aviv and Haifa develop advanced imaging components for export to Gulf markets. The national pharmaceutical regulator maintains stringent electromagnetic compatibility testing protocols for device approvals. Weizmann Institute research partnerships anchor innovation concentration in the central coastal region.
Egypt
Cairo-based distributors serve secondary care facilities with flexible endoscope systems featuring integrated charge-coupled device sensors. Import duty volatility on optical sensor components creates procurement cost fluctuations. The New Administrative Capital healthcare zone is emerging as a concentration point for hospital infrastructure modernization.
Middle East and Africa Optical Imaging Market Competitive Landscape
Listed leaders compete with private specialists across service infrastructure depth and clinical training capabilities. The vendor base clusters around three tiers: diversified conglomerates with broad imaging portfolios, pure-play ophthalmic specialists with regional service networks, and industrial automation providers crossing into healthcare applications. Competitive positioning hinges on distributor partnership density and preventive maintenance contract penetration. M&A activity targets service infrastructure assets, while organic expansion concentrates on training academy establishment.
Within the ophthalmic specialist tier, Carl Zeiss Meditec AG and Heidelberg Engineering GmbH exemplify divergent strategic positions. The German Meditec AG structure leverages established service infrastructure across Gulf hospital chains to sustain recurring revenue streams. Heidelberg Engineering GmbH anchors its position through specialized retinal imaging platforms that dominate academic medical centers. Topcon Corporation represents the Japanese cross-category approach, competing aggressively on ophthalmic diagnostic bundles and extending its footprint into North African markets through distributor partnerships.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Heidelberg Engineering GmbH |
| Topcon Corporation |
| Abbott Laboratories |
| Nikon Corporation |
| Olympus Corporation |
| Hamamatsu Photonics |
| OPTO GmbH |
| Revenio Group Oyj |
| Others |
Supply & Pricing Matrix
SFDA and SAHPRA device registration requirements gate both supply qualification and price differentiation simultaneously, compressing market entry timelines for uncertified vendors while enabling premium capture for manufacturers with established clinical evidence packages across Gulf and South African procurement channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Gulf petrochemical fabrication facilities. Pricing stratifies across premium, standard, and economy tiers based on spectral resolution specifications and ISO 13485 certification status. Cost compression in mid-tier fluorescence platforms is intensifying because Dubai hospital chains now unbundle preventive maintenance from hardware acquisition. Research laboratories in South Africa exhibit highest price sensitivity due to constrained public funding, while Saudi academic medical centers show lowest sensitivity given specialized diagnostic infrastructure mandates.
Supply Chain Analysis
Strategic stockpiling of charge-coupled device and complementary metal-oxide semiconductor sensor components dominates procurement behavior among Egyptian and Nigerian distributors facing import duty volatility. Manufacturing concentration centers on Germany and Japan for precision optical assemblies, with China supplying machine vision camera housings and power electronics. Raw material dependencies include rare-earth doped glass for laser sources, silicon wafers for sensor fabrication, and specialized optical coatings. Single-source vulnerability runs through Japanese sensor foundries. Distribution runs through authorized dealer networks serving Gulf hospital chains alongside direct manufacturer relationships for South African academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa optical imaging market is emerging from a capital expenditure trough as Gulf healthcare infrastructure modernization cycles inflect upward, with Saudi Vision 2030 hospital buildouts providing cyclical lift.
For Market Incumbents: Secure recurring revenue streams by expanding preventive maintenance contract penetration across Dubai's unbundling procurement environment. Deepen backward integration into sensor component sourcing to mitigate Egyptian and Nigerian import duty exposure. Anchor position against portable ultrasound substitution threats through clinical training academy investments that embed platform dependency among retinal imaging specialists. For New Entrants and Emerging Players: Biomedical optics specialist scarcity in South Africa's public health system presents immediate white-space opportunity for service-heavy entry models. Target Morocco and Algeria distributor partnerships replicating proven North African expansion playbooks. Lead with fluorescence reagent pull-through economics rather than capital equipment margins to align with Gulf hospital chain procurement preferences. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across industrial machine vision segments as Gulf petrochemical automation protocols standardize. Long-term viability favors asset-light service infrastructure plays over manufacturing capacity ownership. Monitor African Medicines Agency harmonization implementation pace as signal for pan-African distribution scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Fast-Track | Accelerated market entry timelines compress competitive response windows for Gulf hospital tenders. |
| Service Contract Unbundling | Dubai procurement departments now negotiate maintenance separately, restructuring supplier revenue recognition. |
| Confocal Platform Training Academy | Saudi academic medical center adoption creates captive specialist pools that lock in platform ecosystems. |
| North African Distributor Partnership | Morocco and Algeria white-space replication extends footprint without direct sales infrastructure investment. |
| Industrial AOI Protocol Deployment | Gulf petrochemical facility automation opens non-healthcare verticals with distinct procurement cycles. |
Research Methodology
A standing panel of biomedical engineers, hospital purchasing committee members, GPO contracts managers, and ophthalmology department heads provided ongoing calibration across primary interview rounds. Secondary validation drew from SFDA device registration databases, SAHPRA approval filings, Gulf hospital procurement tender records, and customs trade data for optical sensor component flows. Bottom-up installed base estimates triangulated against top-down healthcare capital expenditure projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, technology tier, end-user category, and application use-case, with additional dimensioning by regulatory jurisdiction cluster. CAGRs were derived from weighted average growth contributions across these segments. Forecast inputs incorporated SFDA streamlining implementation pace, African Medicines Agency harmonization rollout status, and Gulf petrochemical automation adoption curves.
Material uncertainties — regulatory approval delays, currency volatility in Egyptian and Nigerian procurement channels, and biomedical optics talent pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued Gulf healthcare infrastructure investment commitment and industrial automation protocol standardization. Revision becomes warranted when African Medicines Agency harmonization implementation crosses operational thresholds or when portable ultrasound diagnostic accuracy improvements accelerate substitution pressure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Collimating Lens Market
Optics
Optical Telephoto Lens Market
Optics
Smart Glass Market
Optics
Lasers Market
Optics
Laser Transmitter Market
Optics
Fiber-Optic Filters Market
Optics
Fiber Optic Development Tools Market
Optics
Middle East and Africa Tunable Laser Market
Optics
Fiber Optical Receivers Market
Optics
Single-Mode Optical Fiber Market
Optics
Optical Gratings Market
Optics
Optical Imaging Market
Optics
Photostimulation Lasers Market
Optics
EUV Pellicle Market
Optics
Glass Scintillator Market
Optics
Fiber Optic Preform Market