
 US Photonics Market | 2026-2036
US Photonics Market Size, Share, and Industry Trends Forecast 2026-2036
US Photonics Market Analytics
The shortage of photonics technicians with compound semiconductor fabrication skills is unwinding as community colleges in Arizona and New Mexico expand cleanroom training partnerships with national laboratories. Coherent Corp leverages vertical integration across laser crystal growth and diode fabrication to control supply security for defense prime contractors. IPG Photonics anchors high-power fiber laser production from its Massachusetts and California facilities, sustaining manufacturing scale that competitors struggle to replicate. Thorlabs Inc differentiates through catalog breadth and in-house optical coating capabilities, occupying a defensible position in research instrumentation.
Photonics encompasses the generation, manipulation, and detection of light across ultraviolet through infrared wavelengths, typically involving coherent sources with output powers ranging from milliwatts to multi-kilowatt in industrial systems, and relies on precision optical substrates with surface roughness below one nanometer for critical beam-shaping functions. Its primary commercial purpose spans optical communications infrastructure, precision manufacturing, biomedical diagnostics, and military sensor systems where electromagnetic alternatives fail. Lasers command the largest product category by installed value, though optical components capture disproportionate margin pools through specification-critical roles in telecom and semiconductor metrology. Fiber optics technology leads volume deployment in data center interconnects, while semiconductor photonics platforms are displacing legacy discrete assemblies in coherent transceivers. Manufacturing end users represent the fastest-growing demand vertical as ultrafast lasers replace mechanical tools in battery cell processing and medical device fabrication.
FDA device regulations govern laser-based surgical and diagnostic equipment, requiring 510(k) premarket notification for most photonic therapeutic systems and enforcing IEC 60825 safety classifications. NIST maintains traceable calibration standards for optical power and wavelength that underpin commercial measurement validity across defense and semiconductor applications. FCC spectrum management intersects with free-space optical communication developers seeking experimental licenses for atmospheric laser links. Stakeholders must monitor how CHIPS Act implementation redirects foundry capacity toward silicon photonics co-packaging versus discrete III-V compound semiconductor fabrication, as this allocation choice will determine which technology platforms achieve cost parity for next-generation optical interconnects.
Market Dynamics
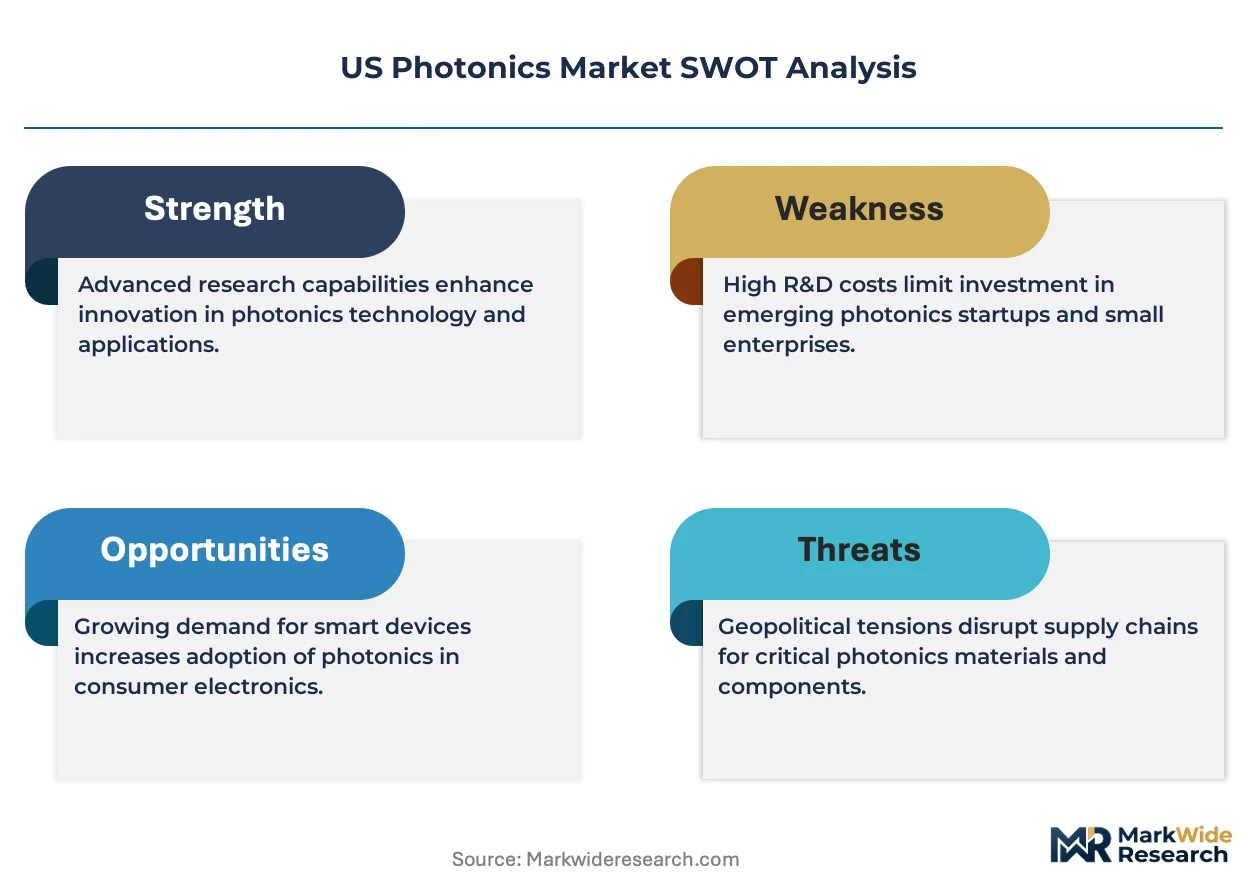
Silicon photonics integration with CMOS foundry processes is compressing unit costs for optical transceivers while redirecting capital away from legacy III-V compound semiconductor fabrication, fundamentally restructuring competitive positioning among domestic suppliers.
Growth Catalysts
- CHIPS Act Implementation:Federal foundry capacity allocation toward silicon photonics co-packaging is accelerating domestic optical interconnect production and reducing reliance on offshore III-V fabrication.
- Defense Modernization Mandates:Department of Defense procurement of directed-energy systems and laser rangefinders is pulling high-power fiber laser demand through prime contractor supply chains.
- Ultrafast Laser Adoption:Battery cell processing and medical device fabrication in Michigan and Ohio manufacturing corridors is replacing mechanical tooling with precision photonic systems.
Market Restraints
- Indium Phosphide Supply Concentration:Limited domestic sources for high-purity InP substrates creates vulnerability in telecom laser diode production chains.
- FDA 510(k) Timeline Friction:Premarket notification requirements for laser-based surgical equipment extend commercialization cycles for photonic therapeutic developers.
- Electron Beam Lithography Bottleneck:Cleanroom access constraints at national laboratories delay prototype-to-production scaling for advanced photonic integrated circuits.
Strategic Opportunities
- Arizona-New Mexico Technician Pipeline:Community college cleanroom training partnerships with Sandia and Los Alamos national laboratories are unwinding skilled labor shortages in compound semiconductor fabrication.
- Free-Space Optical Communication:FCC experimental licensing for atmospheric laser links is opening spectrum alternatives for rural broadband backhaul in mountainous western states.
- Silicon-III-V Heterogeneous Integration:Hybrid wafer bonding processes are enabling co-packaged optics that bridge cost-performance gaps in data center interconnects.
Industry Challenges
- Compound Semiconductor Skill Gap:MOCVD reactor operation and epitaxial growth expertise remains concentrated among retiring cohorts at legacy Bell Labs and Xerox PARC alumni networks.
- NIST Calibration Dependency:Traceable optical power and wavelength standards require federal laboratory access that creates scheduling bottlenecks for commercial metrology validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Photonics Market |
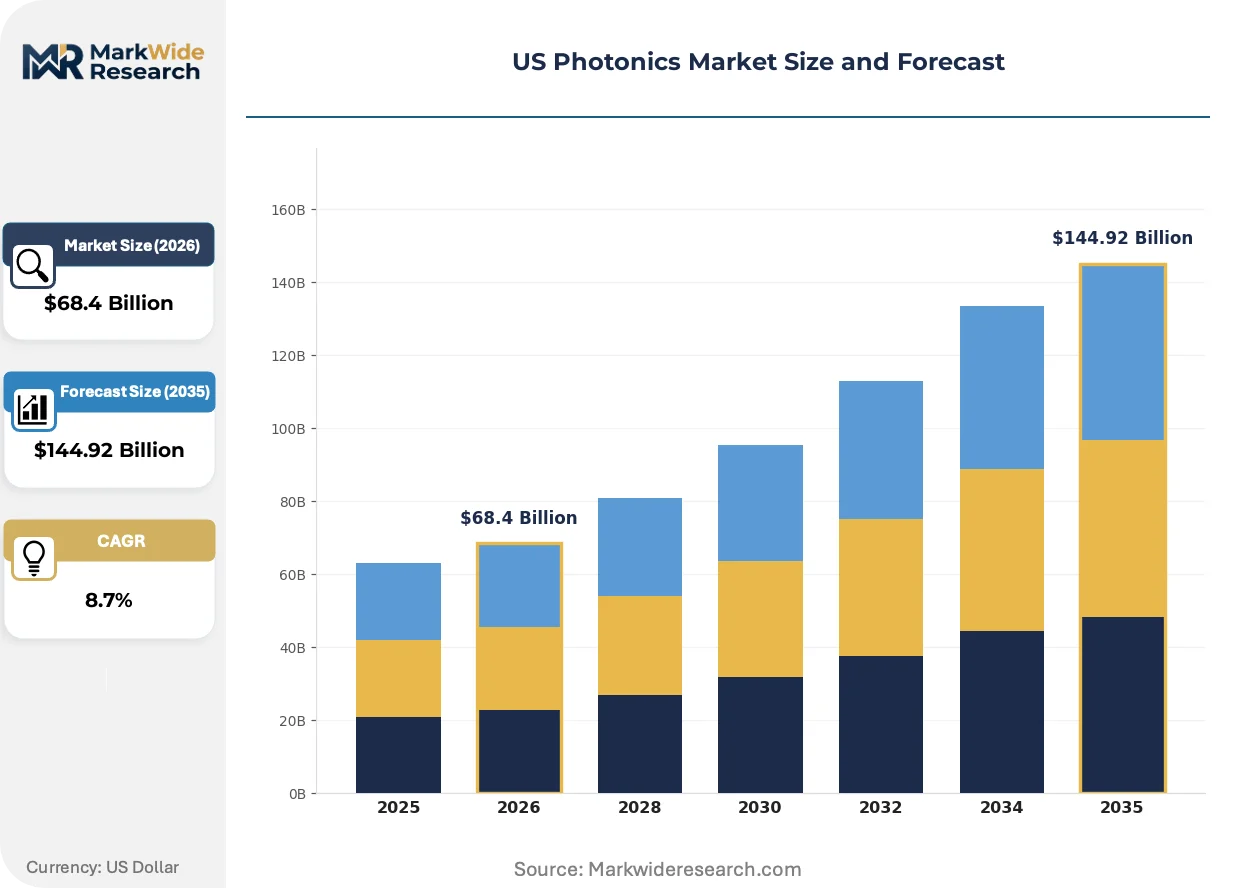
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lasers, Sensors, Optical Components, Imaging Systems Technology: Fiber Optics, Semiconductor, Laser Diodes, Waveguide End User: Telecommunications, Defense, Healthcare, Manufacturing Application: Display, Communication, Measurement, Medical Equipment |
| Companies Covered | Molex LLC, Coherent Corp, Intel Corporation, Thorlabs Inc, IPG Photonics, Lumentum Holdings Inc., Hamamatsu Photonics K.K., Corning Incorporated, Infinera Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Photonics Market Evolving Landscape
Photonic system architectures are splitting between commodity silicon photonics platforms and performance-optimized compound semiconductor solutions, with process convergence determining which applications migrate to volume manufacturing.
Coherent transceiver technology is bifurcating across two distinct manufacturing paths. Silicon photonics platforms leveraging CMOS foundry compatibility now dominate 400G and below data center interconnects. Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth facilities are standardizing on these lower-cost modules. Meanwhile, InP-based coherent engines retain pricing power in 800G+ long-haul applications where laser linewidth and modulation fidelity specifications remain stringent.
FDA enforcement of IEC 60825 safety classifications for laser-based surgical equipment is tightening documentation requirements for 510(k) submissions. Photonic therapeutic developers must now demonstrate comprehensive hazard analysis beyond prior substantial equivalence benchmarks. This regulatory compression most affects dermatology and ophthalmology device segments, where manufacturers are absorbing extended premarket review cycles into product planning timelines.
Defense prime contractors are consolidating supplier bases for directed-energy subsystems, compressing qualification cycles from traditional multi-year evaluations to 18-month technology readiness assessments. This buyer concentration is displacing fragmented vendor pools that historically served research-phase programs. The shift is most visible in Albuquerque and Huntsville defense corridors, where sole-source relationships with vertically integrated laser crystal growers are becoming standard procurement practice.
US Photonics Market Segmentation
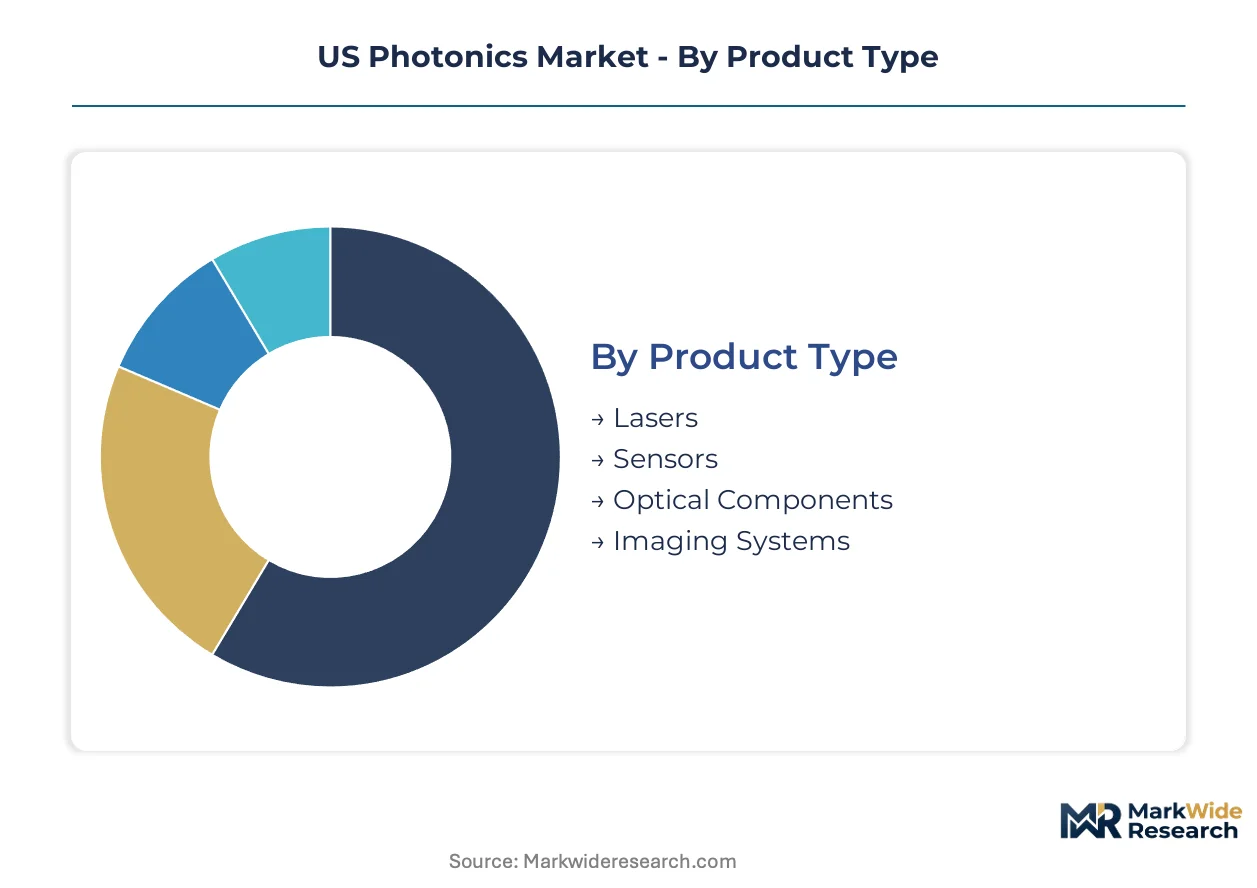
Photonics market segmentation reveals where substitution pressure from alternative technologies is reshaping procurement patterns. Defense and telecommunications buyers now evaluate photonic systems against electronic and acoustic alternatives based on performance thresholds rather than legacy specifications.
Product Type:
Laser systems face intensifying substitution pressure from ultrasonic and electron beam technologies in precision manufacturing, while optical components defend irreplaceable positions in telecom wavelength-division multiplexing.
- Lasers:Coherent light sources spanning milliwatt laboratory units to multi-kilowatt industrial fiber systems. Defense procurement in Albuquerque and Huntsville corridors is pulling high-power fiber laser demand through prime contractor supply chains constrained by sole-source qualification requirements.
- Sensors:Photodetectors and optical encoders converting light signals into measurable electrical outputs. Automotive lidar developers in Michigan are integrating solid-state photonic sensors as primary perception layers, displacing radar in premium vehicle platforms.
- Optical Components:Lenses, filters, polarizers, and beam splitters with surface roughness below one nanometer for critical functions. Precision substrate fabrication concentrates in California's Silicon Valley cleanroom corridors.
- Imaging Systems:Integrated camera modules and machine vision assemblies combining optics with computational processing. Medical device manufacturers in Minnesota deploy these for surgical navigation and diagnostic microscopy.
Lasers retain volume leadership; imaging systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates CMOS-compatible platforms from specialty compound semiconductor processes requiring dedicated fabrication infrastructure.
- Fiber Optics:Glass waveguides transmitting optical signals across ultraviolet through infrared wavelengths with minimal attenuation. Hyperscale data centers in Northern Virginia and Dallas-Fort Worth are standardizing fiber interconnects for 400G and below applications.
- Semiconductor:Silicon photonics platforms leveraging foundry compatibility for optical transceiver integration. CHIPS Act funding is redirecting domestic foundry capacity toward silicon photonics co-packaging versus discrete III-V fabrication.
- Laser Diodes:Edge-emitting and vertical-cavity surface-emitting sources fabricated from III-V compound semiconductors. Indium phosphide substrate limitations constrain telecom laser diode production chains.
- Waveguide:Structured optical paths in planar or channel configurations for photonic integrated circuits. Prototype-to-production scaling faces cleanroom access constraints at national laboratories.
Fiber optics commands the largest installed base; silicon photonics platforms are climbing the fastest.
End User:
Customer type determines specification rigidity, with defense and healthcare imposing qualification barriers that manufacturing and telecom segments relax for cost optimization.
- Telecommunications:Network operators and equipment manufacturers deploying optical infrastructure for backbone and access networks. Coherent transceiver demand splits between silicon photonics for data center interconnects and InP-based engines for 800G+ long-haul.
- Defense:Department of Defense and prime contractors acquiring directed-energy systems, laser rangefinders, and optical sensors. Modernization mandates are compressing supplier qualification cycles from multi-year evaluations to 18-month technology readiness assessments.
- Healthcare:Hospitals, clinics, and device manufacturers utilizing photonic systems for surgical and diagnostic applications. FDA 510(k) premarket notification requirements extend commercialization cycles for laser-based therapeutic equipment.
- Manufacturing:Industrial users replacing mechanical tooling with ultrafast laser systems for precision processing. Battery cell fabrication in Ohio and Michigan manufacturing corridors is adopting photonic cutting and welding systems.
Telecommunications retains volume leadership; manufacturing holds the steepest expansion curve.
Application:
Geography clusters application demand, with display manufacturing concentrating on the West Coast and medical equipment production anchoring in the Upper Midwest.
- Display:Backlighting, projection, and direct-emission systems for visual information presentation. MicroLED development in California's San Diego photonics corridor is driving advanced photonic integration requirements.
- Communication:Free-space optical links and fiber-based data transmission systems. FCC experimental licensing for atmospheric laser links is opening spectrum alternatives for rural broadband backhaul in mountainous western states.
- Measurement:Metrology and inspection systems requiring traceable optical power and wavelength standards. NIST calibration dependencies create scheduling bottlenecks for commercial validation across defense and semiconductor applications.
- Medical Equipment:Laser-based surgical and diagnostic devices governed by FDA device regulations. IEC 60825 safety classification enforcement is tightening documentation requirements for 510(k) submissions in dermatology and ophthalmology segments.
Communication retains volume leadership; medical equipment holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California's Silicon Valley photonics corridors while manufacturing cost advantages cluster in Arizona and New Mexico technician training zones. Defense procurement premiums flow through Albuquerque and Huntsville corridors, sustaining margin pools unavailable to commercial-only suppliers. Regional specialization is hardening as federal research funding co-locates with distinct cleanroom infrastructure capabilities.
California
Silicon Valley and San Diego photonics corridors anchor precision optical substrate fabrication with surface roughness below one nanometer. NIST traceable calibration standards underpin commercial measurement validity across defense and semiconductor applications concentrated in Bay Area national laboratory partnerships. Venture capital co-location with specialized cleanroom infrastructure accelerates prototype-to-production scaling for photonic integrated circuits.
Arizona
Community college cleanroom training partnerships with Sandia National Laboratories unwind skilled labor shortages in compound semiconductor fabrication. CHIPS Act implementation redirects foundry capacity toward silicon photonics co-packaging versus discrete III-V fabrication in Phoenix-area facilities. Technician pipeline expansion supports MOCVD reactor operation and epitaxial growth expertise transfer from retiring Bell Labs alumni networks.
New Mexico
Los Alamos National Laboratory collaborations extend cleanroom access for advanced photonic integrated circuit developers facing electron beam lithography bottlenecks. Directed-energy subsystem procurement from defense prime contractors compresses qualification cycles to 18-month technology readiness assessments. Albuquerque defense corridors consolidate sole-source relationships with laser crystal growers.
Massachusetts
High-power fiber laser production facilities sustain manufacturing scale through defense modernization mandates for directed-energy systems. FDA 510(k) premarket notification timelines for laser-based surgical equipment extend commercialization cycles for photonic therapeutic developers in Boston medical device clusters. Ultrafast laser adoption in battery cell processing pulls demand through Michigan and Ohio manufacturing corridor supply chains.
Texas
Hyperscale data center operators in Dallas-Fort Worth facilities standardize on silicon photonics optical transceivers for 400G and below interconnects. FCC experimental licensing for atmospheric laser links opens spectrum alternatives for rural broadband backhaul in mountainous western states. InP-based coherent engines retain pricing power in 800G+ long-haul applications where laser linewidth specifications remain stringent.
US Photonics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated laser crystal specialists commanding defense premiums while CMOS-compatible silicon photonics platforms capture hyperscale data center volume. The vendor base splits between compound semiconductor fabricators requiring dedicated MOCVD infrastructure and foundry-dependent integrators leveraging CHIPS Act capacity allocation. Strategic archetypes include defense-qualified sole-source suppliers, catalog-breadth research instrumentation providers, and telecom component scale manufacturers. Competitive moves center on supplier base consolidation for directed-energy subsystems and heterogeneous integration partnerships bridging silicon-III-V cost-performance gaps.
Within the defense-qualified tier, Coherent Corp and IPG Photonics exemplify archetypes of supply security control and manufacturing scale respectively. Thorlabs Inc occupies a position in research instrumentation through catalog breadth differentiation. Among telecom component specialists, Lumentum Holdings Inc and Infinera Corporation represent scale manufacturing approaches to coherent transceiver production. Intel Corporation and Molex LLC sit within the silicon photonics integration archetype leveraging CMOS foundry compatibility.
| Leading Market Players |
|---|
| Molex LLC |
| Coherent Corp |
| Intel Corporation |
| Thorlabs Inc |
| IPG Photonics |
| Lumentum Holdings Inc. |
| Hamamatsu Photonics K.K. |
| Corning Incorporated |
| Infinera Corporation |
| Others |
Value Network & Pricing Analysis
Silicon photonics substitution for legacy III-V compound semiconductor platforms is compressing unit costs while relocating fabrication gravity toward CMOS-compatible foundries, simultaneously eroding pricing premiums for discrete optical components and elevating procurement leverage for hyperscale data center operators.
Pricing Analysis
The customization-premium spread separates standard silicon photonics transceivers from configured-to-order coherent engines, with the former commanding commodity margins and the latter retaining specification-based premiums. Price differentiation hinges on laser linewidth certification tier and volume procurement scale, with hyperscale cloud operators extracting steepest discounts. Cost compression in sub-400G data center interconnects is intensifying because foundry standardization eliminates non-recurring engineering charges. Telecom backbone operators exhibit lowest price sensitivity due to 800G+ performance requirements that resist silicon substitution.
Supply Chain Analysis
Inventory lead-times for indium phosphide substrates stretch procurement cycles to six months, constraining telecom laser diode production schedules. Supply concentrates in Japan, the United States, and China for high-purity compound semiconductor wafers, with Taiwan anchoring silicon photonics foundry capacity. Raw material dependencies include rare earth elements for fiber laser dopants, high-purity silica for waveguide fabrication, and specialty gases for MOCVD epitaxial growth. Single-source vulnerability pervades electron beam lithography equipment, where Dutch and Japanese OEMs control global installed base. Distribution runs through defense prime contractor qualification channels and direct OEM procurement for commercial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US photonics market sits at early-cycle expansion driven by defense modernization mandates pulling directed-energy systems through prime contractor supply chains at compressed qualification intervals.
For Market Incumbents: Compound defensive moats by deepening backward integration into laser crystal growth and diode fabrication, securing sole-source positions against emerging silicon photonics entrants. Anchor capacity addition in Arizona and New Mexico technician training corridors to unwind compound semiconductor skill gaps. Prioritize FDA 510(k) certification investment to extend premarket review cycle advantages over therapeutic device challengers. For New Entrants and Emerging Players: FDA fast-track pathways for laser-based surgical equipment offer regulatory arbitrage against established dermatology and ophthalmology incumbents. Target free-space optical communication applications in mountainous western states, where FCC experimental licensing creates spectrum access without fiber trenching costs. Pursue hospital system partnerships as primary go-to-market channel for photonic therapeutic devices. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors vertically integrated laser crystal specialists with defense qualification credentials over foundry-dependent silicon photonics integrators. Long-term viability rests on heterogeneous integration capabilities bridging silicon-III-V cost-performance gaps. Acquisition target archetype: compound semiconductor fabricators with captive MOCVD infrastructure and national laboratory partnerships. Watch CHIPS Act foundry capacity allocation announcements as inflection signal for platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-III-V Heterogeneous Integration Partnership | Hybrid wafer bonding bridges cost-performance gaps in data center interconnects. |
| Defense Prime Contractor Qualification | Sole-source relationships compress procurement cycles to 18-month technology readiness assessments. |
| Community College Cleanroom Training Expansion | Arizona and New Mexico partnerships unwind MOCVD reactor operation skill shortages. |
| FCC Experimental Licensing Pursuit | Atmospheric laser links open rural broadband backhaul spectrum alternatives in western states. |
| FDA 510(k) Premarket Notification Investment | IEC 60825 safety classification documentation tightens therapeutic device entry barriers. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with photonics manufacturing executives, defense procurement officers, and biomedical device regulatory leads; and secondary validation through SEC 10-K filings, CHIPS Act implementation disclosures, FDA 510(k) submission databases, and hyperscaler capital expenditure reports. Bottom-up and top-down triangulation cross-checked unit economics against aggregate market sizing.
Across the projection horizon, the analytical framework modeled demand across product type, technology platform, end-user vertical, and application segment dimensions. CAGRs were derived from segment-level volume trajectories and value-per-unit compression curves. Forecast inputs included defense modernization budget appropriations, foundry capacity allocation announcements, and technician pipeline graduation rates from national laboratory partnerships.
Underlying assumptions cover CHIPS Act funding continuity, defense procurement mandate persistence, and FDA regulatory pathway stability, with deviation risk concentrated in indium phosphide substrate supply disruptions and electron beam lithography equipment availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Optical Microscope Market
Optics
Stroboscope Market
Optics
Asia Pacific Smartphone Camera Lens Market
Optics
Beam Combining Optics Market
Optics
Residential 1080P Laser Television Projector Market
Optics
Lasers Market
Optics
Excimer Lasers for DUV Lithography Market
Optics
Optical Telephoto Lens Market
Optics
Fiber-Optic Couplers Market
Optics
Smart Vision Systems Market
Optics
Electro Optics Market
Optics
Optical Fiber Raw Material Market
Optics
Optical Profilometer Market
Optics
Global Semiconductor Lasers Market
Optics
Optical Imaging Market
Optics
Optical Wavelength Service Market