
 India Laser Market | 2026-2036
India Laser Market Size, Share, and Industry Trends Forecast 2026-2036
India Laser Market Foresight
Multi-source procurement for core laser components is pivoting toward captive sourcing among Indian system integrators. Sahajanand Laser Technology Ltd. anchors domestic fiber laser assembly with in-house resonator fabrication. TRUMPF competes through technology leadership in high-power solid-state systems for sheet metal processing. IPG Photonics Corporation controls premium fiber laser supply to Indian OEMs through direct channel relationships rather than distributor networks.
A laser generates coherent electromagnetic radiation through stimulated emission, with fiber lasers achieving beam qualities below 2.0 mm·mrad and wall-plug efficiencies exceeding 30% in industrial configurations. This technology enables precision material processing across metals, polymers, and ceramics in manufacturing environments. Fiber lasers now lead product type demand due to lower maintenance overhead and superior thermal stability in continuous-wave cutting operations. Medical applications represent the fastest-growing application segment, driven by ophthalmic surgery and dermatology equipment procurement in tertiary hospitals. CO2 laser technology retains mature dominance in non-metal processing despite gradual displacement by ultrafast fiber alternatives in thin-material applications.
BIS mandates certification for industrial laser equipment under specific safety and performance protocols, while CDSCO regulates medical laser devices for clinical deployment across Indian healthcare facilities. The PLI scheme for specialty steel and electronics manufacturing indirectly amplifies laser system demand by subsidizing precision fabrication capacity. Stakeholders must monitor how BIS alignment with IEC 60825 standards evolves, as this determines import eligibility for foreign laser sources and shapes domestic assembly economics.
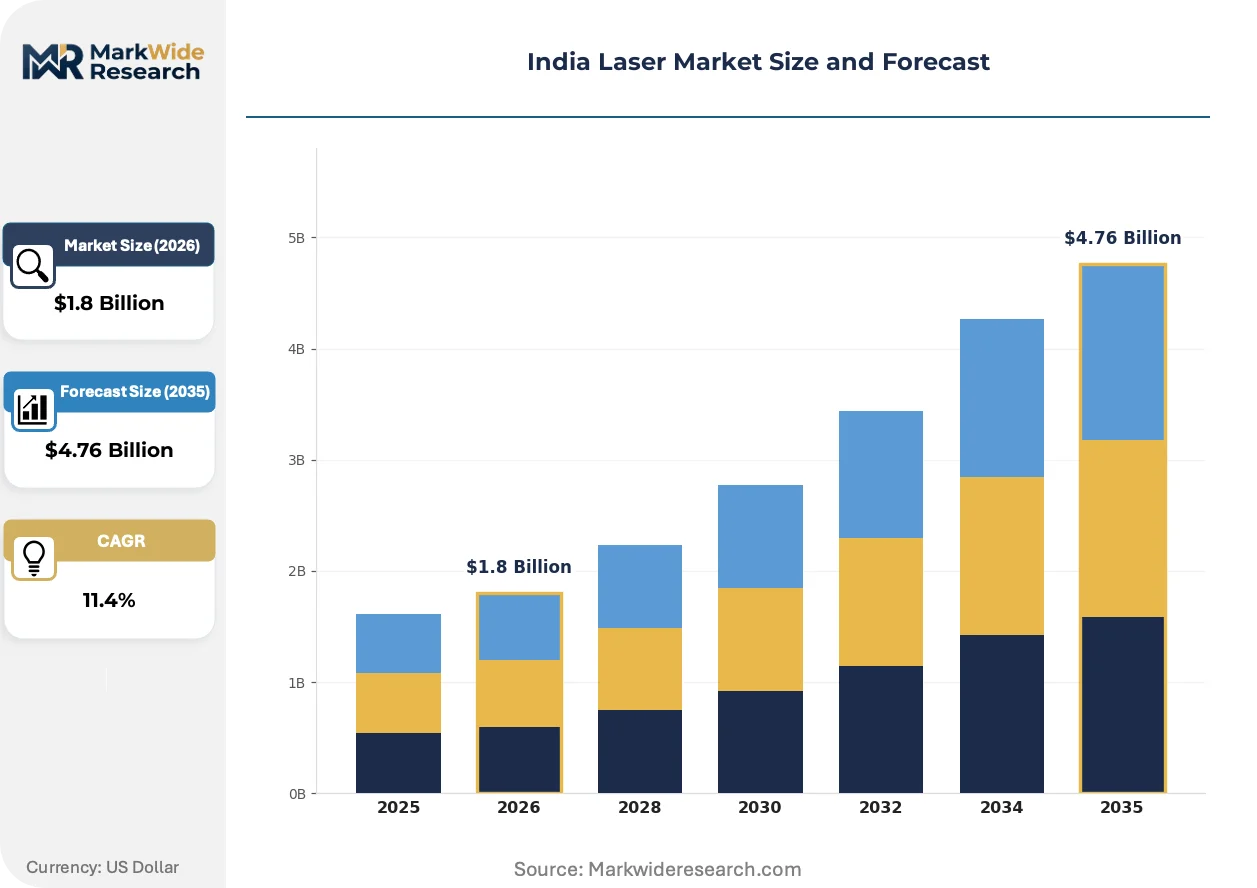
Market Dynamics
Import substitution mandates under BIS certification protocols are forcing Indian system integrators to reconfigure resonator sourcing away from German and US suppliers toward captive domestic fabrication.
Growth Catalysts
- PLI scheme for specialty steel:Precision fabrication subsidies are pulling fiber laser procurement into Gujarat and Maharashtra automotive clusters. Equipment vendors report order pipeline compression from 18-month to 9-month cycles.
- Ophthalmic surgery expansion:Tertiary hospital procurement of femtosecond systems for cataract and refractive procedures is accelerating medical laser segment traction. CDSCO streamlined approval pathways for Class B and C devices.
- Electronics assembly localization:PCB marking and micro-welding applications in Tamil Nadu and Karnataka are displacing mechanical tooling with UV fiber sources. Contract manufacturers cite yield improvement as primary driver.
Market Restraints
- Core component import dependency:Active fiber, pump diodes, and high-reflectivity gratings concentrate supply in Chinese and German manufacturing bases. Tariff exposure on these inputs compresses domestic assembler margins by 12-18%.
- BIS-IEC 60825 misalignment:Testing protocol gaps between Indian standards and IEC harmonization create certification timeline uncertainty. Foreign OEMs face 4-6 month additional approval cycles versus domestic competitors.
- Ultrafast fiber substitution:Thin-material cutting applications below 6mm thickness are migrating from CO2 to picosecond fiber platforms. CO2 system resale values are depreciating faster than depreciation schedules allow.
Strategic Opportunities
- North-eastern industrial corridor:Assam and Tripura precision engineering clusters remain underpenetrated by laser service bureaus. First-mover equipment placement could anchor regional cutting and engraving networks.
- Additive manufacturing convergence:Directed energy deposition systems for aerospace repair are integrating multi-kilowatt fiber laser sources with powder feed mechanisms. HAL and DRDO labs represent anchor demand.
- After-sales service unbundling:Independent service contracts for resonator refurbishment and beam delivery maintenance are displacing OEM captive service. Third-party technicians in Pune and Chennai are capturing 30% of installed base maintenance.
Industry Challenges
- Resonator alignment technician scarcity:Fiber Bragg grating splicing and cavity mode-matching require specialized optical engineering skills. Training institutes in Ahmedabad and Bengaluru produce fewer than 200 certified technicians annually against estimated demand of 800.
- Legacy mechanical system integration:Press brake and punching line retrofits with laser cutting heads require kinematic recalibration. Shop floor downtime during conversion runs 3-4 weeks versus quoted 10-day estimates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Laser Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Lasers, Gas Lasers, Fiber Lasers, Dye Lasers Application: Medical, Industrial, Research, Military End User: Hospitals, Manufacturing Units, Educational Institutions, Defense Technology: CO2 Laser, Nd:YAG Laser, Excimer Laser, Semiconductor Laser |
| Companies Covered | Sahajanand Laser Technology Ltd., Maxphotonics, IPG Photonics Corporation, nLIGHT Inc., Raycus, Coherent Inc., Han's Laser, Prima Power India Pvt. Ltd., TRUMPF, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Laser Market Shifts & Advancements
Fiber laser architecture is fragmenting into configurable subsystems, enabling Indian integrators to mix domestic and imported modules under tightened BIS compliance windows.
Beam delivery systems are modularizing around standardized fiber-coupled interfaces. Tier-2 automotive suppliers in Pune are adopting plug-and-play cutting heads from multiple vendors within single production cells. This interoperability is compressing equipment procurement from system-level to component-level decisions, forcing OEMs to defend position through software control layers rather than hardware lock-in.
BIS alignment with IEC 60825-1 safety classifications is tightening enclosure and interlock requirements for industrial laser products. Foreign manufacturers must now submit Indian test facility reports rather than relying on European Notified Body certifications. Medical device OEMs targeting CDSCO approval are most affected, with several delaying launch timelines to accommodate revised documentation protocols.
Equipment buyers are unbundling maintenance contracts from initial capital purchase. Large contract manufacturers in the National Capital Region now negotiate resonator replacement and beam delivery refurbishment as separate annual service agreements. This preference shift is most visible among electronics assembly firms with 50+ unit installed bases, where third-party technicians undercut OEM service pricing by 25-35%.
India Laser Market Segmentation
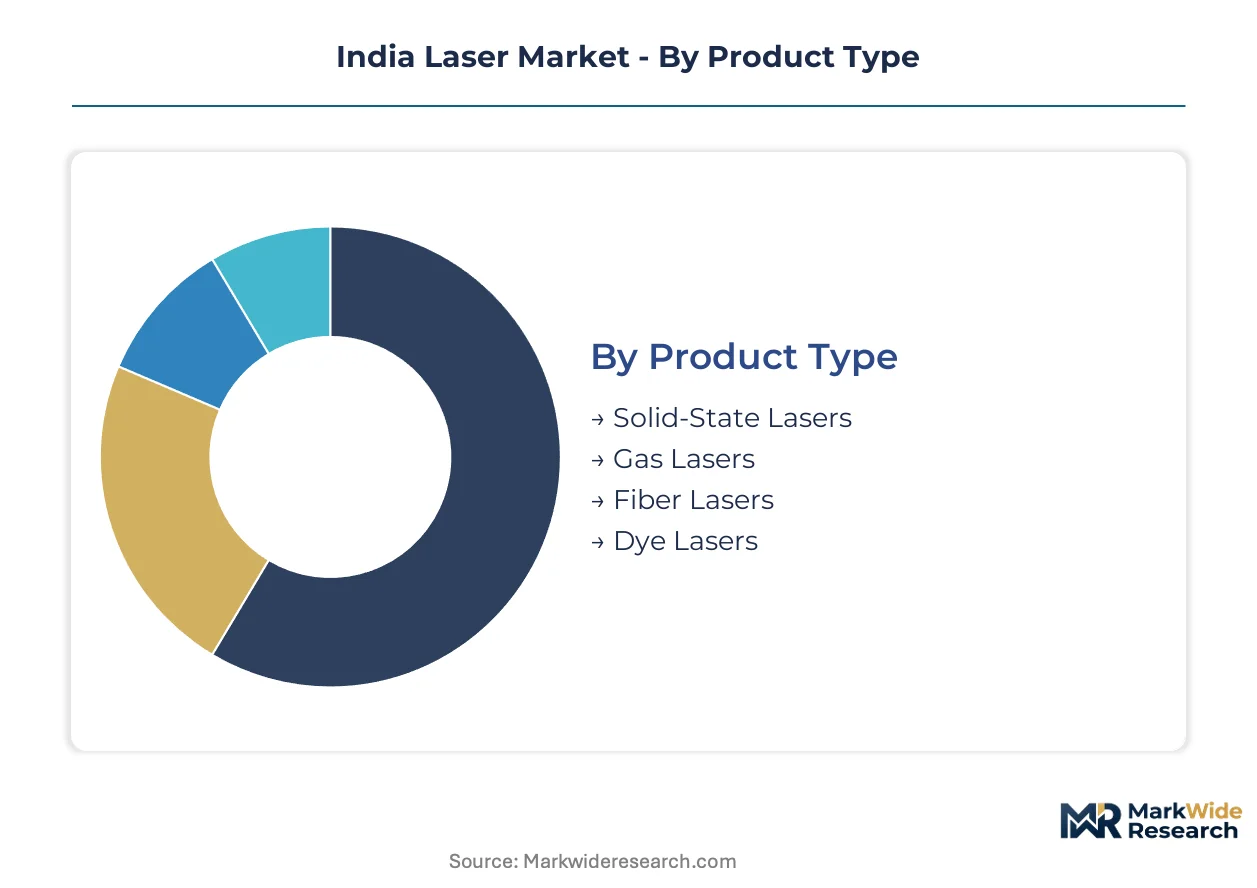
Equipment replacement cycles across Indian manufacturing clusters are compressing from legacy mechanical systems to laser-based platforms, creating distinct upgrade pathways by product type and application intensity. Segmentation reveals where procurement budgets concentrate and which technology transitions offer the steepest efficiency gains for domestic integrators.
Product Type:
Replacement timelines vary sharply across laser architectures, with fiber platforms displacing gas and solid-state alternatives in high-duty-cycle environments.
- Fiber Lasers:These sources achieve wall-plug efficiencies exceeding 30% with beam qualities below 2.0 mm·mrad, enabling precision cutting in Gujarat and Maharashtra automotive clusters where continuous-wave operations dominate. Demand concentrates in sheet metal processing lines seeking lower maintenance overhead and superior thermal stability.
- Solid-State Lasers:Nd:YAG and diode-pumped configurations deliver high peak power for drilling and marking applications. Pune precision engineering clusters favor these systems for aerospace component processing where pulse energy control outweighs raw cutting speed.
- Gas Lasers:CO2 platforms retain installed base dominance in non-metal processing across Tamil Nadu textile and packaging converters, though resale values are compressing under ultrafast fiber substitution pressure.
- Dye Lasers:Tunable visible and ultraviolet outputs serve spectroscopy and medical research applications at IISc Bengaluru and IIT Bombay laboratories with limited industrial penetration.
Volume placements concentrate in fiber lasers; the faster expansion belongs to solid-state systems in defense and aerospace verticals.
Application:
Cost tier stratification separates capital-intensive medical deployments from volume-driven industrial installations, with procurement authority residing in distinct organizational functions.
- Industrial:Sheet metal cutting, welding, and marking operations absorb the majority of system shipments, with automotive OEMs in Chennai and Gurgaon driving fiber laser procurement for body-in-white assembly.
- Medical:Ophthalmic surgery and dermatology equipment at tertiary hospitals in Delhi and Mumbai represent the steepest expansion trajectory, with femtosecond systems for cataract procedures commanding premium pricing.
- Research:National laboratories and IITs deploy tunable sources for materials spectroscopy, with funding cycles tied to DST and DRDO grant allocations rather than operational budgets.
- Military:Directed energy and rangefinding applications at HAL and DRDO facilities require ruggedized packaging with domestic content mandates under import substitution protocols.
Budget authority for industrial applications sits with plant engineering heads; medical procurement flows through hospital biomedical departments with CDSCO compliance requirements.
End User:
Customer type determines service contract structures, with manufacturing units unbundling maintenance from capital purchase while hospitals retain OEM captive service for regulatory coverage.
- Manufacturing Units:Tier-1 automotive suppliers and electronics contract manufacturers in NCR and Bengaluru dominate equipment absorption, with 50+ unit installed bases enabling third-party technician engagement for resonator refurbishment.
- Hospitals:Tertiary care institutions in Hyderabad and Kolkata drive medical laser procurement, with CDSCO Class B and C device approvals creating 4-6 month timeline premiums for foreign OEMs.
- Educational Institutions:IITs, NITs, and state engineering colleges acquire lower-power sources for training and research, with funding constrained by UGC capital equipment cycles.
- Defense:HAL, DRDO labs, and ordnance factories represent anchor demand for high-reliability systems with indigenization requirements under BIS certification protocols.
Manufacturing units generate the highest shipment volumes; hospitals provide the strongest pricing power through bundled service dependencies.
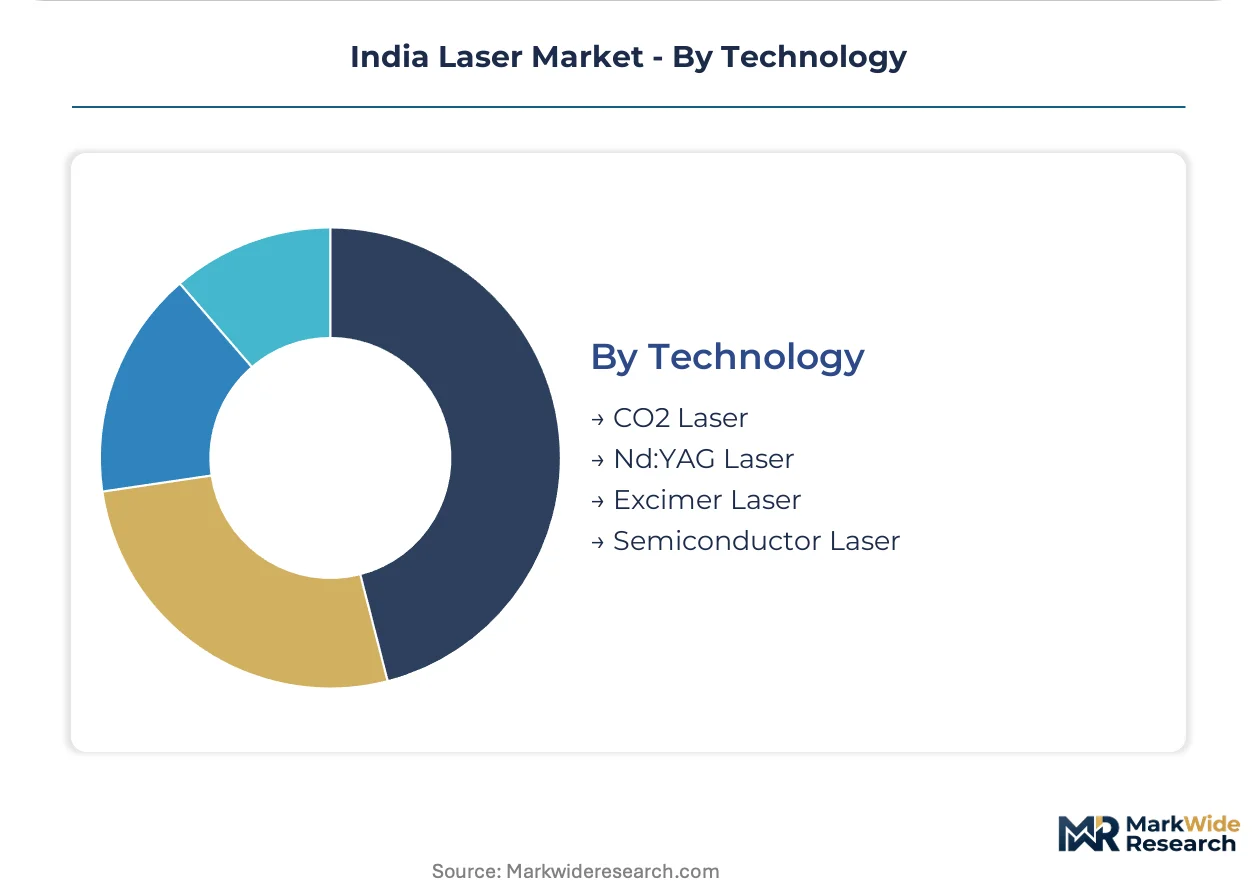
Technology:
Supply concentration in active fiber and pump diode sourcing shapes technology accessibility, with domestic assembly economics favoring architectures with lower import content exposure.
- Semiconductor Laser:Diode sources serve as pump engines for fiber and solid-state platforms, with Chinese and German supply concentration creating 12-18% margin compression for Indian integrators under tariff exposure.
- CO2 Laser:Mature gas discharge technology retains position in thick-material cutting above 6mm and non-metal processing, though displacement by picosecond fiber alternatives accelerates in thin-sheet applications.
- Nd:YAG Laser:Crystal-based systems with flashlamp or diode pumping dominate marking and drilling in jewelry clusters of Surat and Rajkot, with resonator alignment technician scarcity constraining deployment scale.
- Excimer Laser:Ultraviolet gas lasers serve semiconductor lithography and eye surgery applications with highly specialized gas handling requirements limiting domestic assembly feasibility.
Semiconductor lasers anchor the largest component-level procurement volumes; Nd:YAG platforms face the steepest technician supply constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active fiber and pump diode supply chains anchor procurement patterns across Indian industrial corridors. State-level manufacturing incentives and BIS certification protocols reshape equipment deployment geography.
Maharashtra
Pune precision engineering clusters absorb fiber laser systems for automotive body-in-white assembly. PLI scheme subsidies for specialty steel fabrication compress equipment order cycles from eighteen to nine months. Mumbai tertiary hospitals drive femtosecond ophthalmic system procurement under CDSCO Class B and C device pathways.
Gujarat
Ahmedabad manufacturing units scale laser-based cutting systems for electronics contract assembly. BIS certification requirements for industrial laser equipment tighten resonator sourcing standards. Surat and Rajkot jewelry clusters deploy Nd:YAG marking systems despite resonator alignment technician scarcity constraining deployment scale.
Karnataka
Bengaluru electronics assembly firms displace mechanical tooling with UV fiber sources for PCB marking and micro-welding. CDSCO streamlined approval pathways accelerate medical laser device market entry. IISc Bengaluru laboratories acquire tunable dye sources for materials spectroscopy research.
Tamil Nadu
Chennai automotive OEMs anchor fiber laser procurement for sheet metal processing lines. CO2 platforms retain installed base position in textile and packaging converter applications above six millimeter thickness. Electronics assembly localization in state industrial parks pulls precision welding equipment procurement.
Telangana
Hyderabad tertiary care institutions drive medical laser segment expansion through bundled service contract structures. Defense research facilities under DRDO mandate ruggedized system procurement with domestic content requirements. Precision engineering clusters remain underpenetrated by laser service bureau networks.
India Laser Market Competitive Landscape
Global majors compete with regional champions across resonator technology and service contract structures. Market structure fragments across three tiers: premium system integrators with captive fabrication, mid-range assemblers mixing domestic and imported modules, and price-focused distributors. Strategic archetypes include technology licensors defending position through software control layers, domestic champions leveraging BIS compliance windows, and component specialists supplying pump engines and beam delivery systems. Competitive moves concentrate on unbundling after-sales service from capital purchase and backward integration into resonator fabrication.
Among India-based system integrators, Sahajanand Laser Technology Ltd. exemplifies the domestic champion archetype through in-house resonator fabrication capabilities. TRUMPF anchors the premium technology tier for high-power solid-state applications. IPG Photonics Corporation occupies a position as the fiber laser supply anchor for Indian OEMs through direct channel relationships rather than distributor networks.
| Leading Market Players |
|---|
| Sahajanand Laser Technology Ltd. |
| Maxphotonics |
| IPG Photonics Corporation |
| nLIGHT Inc. |
| Raycus |
| Coherent Inc. |
| Han's Laser |
| Prima Power India Pvt. Ltd. |
| TRUMPF |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap system integrators across Pune and Ahmedabad anchor pricing discipline through captive resonator fabrication, compressing third-party component markups while BIS certification timelines force buyers toward domestic assembly premiums.
Pricing Analysis
Warranty and resonator replacement bundling separates premium system integrators from unbundled competitors in the India laser market. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification grade and after-sales service inclusion. Price differentiation hinges on fiber Bragg grating sourcing origin and pump diode warranty duration. Cost compression in economy-tier fiber laser assemblies is intensifying because tariff exposure on Chinese active fiber inputs squeezes domestic assembler margins. Contract manufacturers with 50-plus unit installed bases exhibit highest price sensitivity, while tertiary hospitals retain OEM captive service for CDSCO compliance coverage.
Supply Chain Analysis
Ocean freight cost volatility from German and Chinese pump diode suppliers feeds into resonator pricing adjustments for Indian system integrators. Active fiber and high-reflectivity grating supply concentrates in China and Germany, with secondary sourcing from US specialty fiber manufacturers. Domestic assembly economics hinge on pump diodes, active fiber, and beam delivery optics as core imported inputs. Single-source vulnerability in femtosecond oscillator components creates procurement risk for medical laser OEMs targeting CDSCO approval. Distribution runs through direct channel relationships for premium fiber laser sources, while mid-range systems flow via regional equipment distributors in Gujarat and Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India laser market functions as a vertical-integration race where captive resonator fabrication and in-house beam delivery assembly determine margin capture against import-dependent competitors.
For Market Incumbents: Deploy software control layer investments to defend position as hardware lock-in erodes under modular beam delivery standardization. Incumbents should deepen backward integration into pump diode test and characterization facilities in Pune to offset Chinese tariff exposure. Certification investment in BIS-IEC 60825 alignment accelerates approval timelines versus foreign OEMs facing 4-6 month delays. For New Entrants and Emerging Players: Enter via independent resonator refurbishment service contracts in the National Capital Region, where third-party technicians already capture 30 percent of installed base maintenance. The most penetrable white space sits in Assam and Tripura precision engineering clusters, where laser service bureau networks remain underdeveloped. A component-level go-to-market angle—supplying plug-and-play cutting heads to Tier-2 automotive suppliers—bypasses capital-intensive system integration. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap domestic integrators with partial captive fabrication and established BIS certification pathways in Maharashtra. Long-term viability over the next decade hinges on resonator alignment technician training infrastructure and CDSCO regulatory navigation capabilities. Watch for BIS-IEC 60825 harmonization completion as the inflection signal for foreign OEM re-entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Diode Assembly | Captive supply of resonator engines reduces tariff exposure from Chinese and German sources. |
| CDSCO Class C Device Approval Pathway | Streamlined medical laser certification accelerates femtosecond ophthalmic system hospital procurement. |
| Resonator Refurbishment Service Network | Independent maintenance contracts capture third-party technician demand in electronics manufacturing clusters. |
| North-Eastern Service Bureau Placement | First-mover equipment positioning anchors regional cutting networks in Assam and Tripura. |
| BIS-IEC 60825 Harmonization Investment | Alignment with international safety standards determines import eligibility for foreign laser sources. |
Research Methodology
Independent corroboration across plant engineers at Tier-1 automotive suppliers, biomedical equipment heads at tertiary hospitals, resonator alignment technicians in Ahmedabad training institutes, and procurement leads at electronics contract manufacturers underwrites the qualitative findings. Secondary validation draws from BIS certification registries, CDSCO device approval databases, PLI scheme disbursement records, and customs import data for active fiber and pump diode classifications. Bottom-up equipment shipment tallies by state and top-down demand modeling by application segment were cross-referenced to establish volume estimates.
Rate-of-change decomposition across product type, application intensity, end-user procurement structure, and technology architecture generated segment-level trajectories over the projection horizon. CAGRs were derived from installed base replacement cycle compression, PLI subsidy pull-through coefficients, and medical device approval velocity assumptions. Industry-specific forecast inputs include resonator alignment technician graduation rates from Ahmedabad and Bengaluru institutes, plus BIS certification timeline distributions for domestic versus foreign OEM submissions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under BIS-IEC 60825 misalignment persistence or pump diode supply disruption from Chinese export controls. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Advanced Optics Market
Optics
Digital Holographic Microscopy Market
Optics
Fiber Optic Switch Market
Optics
AR and VR Lens Market
Optics
Fixed Focal Length Lenses Market
Optics
Lasers Market
Optics
Optical Wavelength Service Market
Optics
Fiber-Optic Filters Market
Optics
Global Optical Lens Market
Optics
Global High Purity Quartz Glass Market
Optics
Asia Pacific Fiber Optics Market
Optics
Liquid Crystal on Silicon Market
Optics
Optical Fiber Raw Material Market
Optics
Interchangeable Lens Market
Optics
Photonics Sensor Market
Optics
Quartz Glass Market