
 Optical Telescope Market | 2026-2036
Optical Telescope Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Telescope Market Analysis
Buyer concentration among research institutions is rebalancing as national observatories consolidate purchasing power while educational institutions fragment into smaller, grant-funded acquisitions. Celestron leverages its mass-market distribution to sustain volume leadership in the enthusiast segment. Takahashi anchors the premium apochromatic refractor niche through Japanese precision manufacturing. Astro-Physics competes on custom-built platforms for professional observatories with exacting tracking specifications.
An optical telescope collects and focuses electromagnetic radiation using curved mirrors or glass lenses to magnify distant celestial objects, with aperture diameter determining light-gathering capacity and resolution limits. Primary industrial purposes span astronomical research, satellite tracking, and terrestrial surveillance where angular resolution below one arcsecond proves critical. Refractor configurations occupy the high-margin amateur astrophotography segment where color correction commands premium pricing. Reflector designs dominate institutional procurement due to superior cost-per-aperture economics. Digital technology integration represents the fastest-growing structural shift as CMOS sensors displace traditional eyepiece observation.
FDA oversight applies to medical-grade optical components while FCC regulates radio-frequency emissions from motorized tracking systems in the US market. ISO 10110 surface quality standards govern international trade in precision optics, with non-compliant manufacturers facing exclusion from European Space Agency supply chains. Stakeholders must monitor how emerging national space programs in the Middle East and Southeast Asia reshape procurement qualification requirements.
Market Dynamics
CMOS sensor adoption is decentralizing observational astronomy from centralized institutional facilities toward distributed amateur networks, compressing the addressable market for traditional eyepiece manufacturers while expanding data-sharing platform economics.
Growth Catalysts
- Adaptive Optics Mandate:ESA's tightening optical payload standards force manufacturers toward wavefront correction integration, opening retrofit markets for existing ground-based installations.
- Exoplanet Characterization:Research institutions expand procurement of large-aperture instruments for atmospheric analysis, sustaining demand for meter-class primary mirrors.
- Germany:The Max Planck Institute network maintains steady orders for precision instruments, anchoring European manufacturing capacity.
Market Restraints
- Optical Glass Supply Concentration:Schott AG and Ohara Corporation control specialty low-dispersion glass production, creating single-source vulnerability for apochromatic refractor manufacturers.
- ISO 10110 Compliance Costs:Surface quality certification for ESA supply chain access requires capital-intensive metrology equipment that excludes smaller optical shops.
- Computational Imaging Substitution:Synthetic aperture algorithms and post-processing stacking software reduce hardware resolution requirements for astrophotography applications.
Strategic Opportunities
- Space Situational Awareness:Satellite constellation tracking contracts from defense agencies create demand for rapid-slew robotic mounts with sub-arcsecond pointing accuracy.
- Educational Grant Fragmentation:Smaller institutional purchases under NSF and EU Horizon programs favor modular, transportable telescope systems over permanent installations.
- CMOS-AO Convergence:Integration of low-noise sensors with real-time atmospheric correction enables portable systems to achieve previously facility-bound resolution.
Industry Challenges
- Adaptive Optics Talent Scarcity:Wavefront engineering expertise concentrates at a handful of academic centers, constraining manufacturer hiring pipelines.
- Mirror Polishing Timeline Compression:Large-aperture primary fabrication requires 12-18 month lead times that conflict with grant-funded procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Telescope Market |
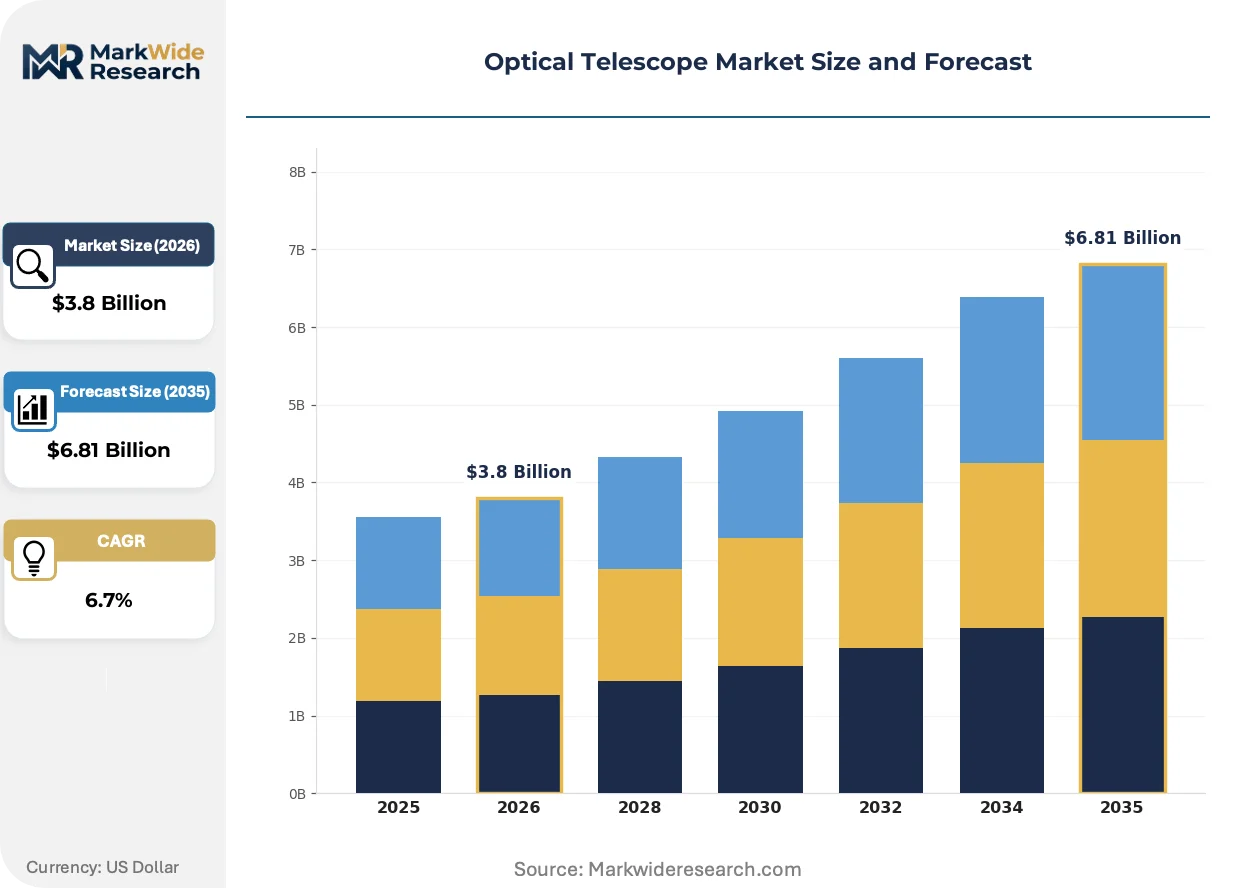
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Astronomical, Terrestrial, Refractor, Reflector End User: Astronomy Enthusiasts, Research Institutions, Educational Institutions, Professional Astronomers Technology: Optical, Digital, Infrared, Radio Application: Astrophotography, Research, Educative Purposes, Observational Studies |
| Companies Covered | Celestron, Meade Instruments, Sky-Watcher, Orion Telescopes & Binoculars, Vixen Optics, Takahashi, Bushnell, Bresser, Astro-Physics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Telescope Market Emerging Trajectories
Digital sensor integration and automated observation platforms are restructuring how telescopes capture, process, and distribute astronomical data across professional and enthusiast segments.
CMOS sensor technology is decentralizing data acquisition from dedicated observatory nights toward continuous automated sky monitoring. Amateur astronomers now operate remote robotic facilities through subscription-based telescope networks, compressing demand for personal instrument ownership while expanding aggregate observation hours. This distributed architecture is decentralizing scientific contribution authority from credentialed institutions toward verified citizen-science platforms.
REACH chemical restrictions on lead-containing optical glasses are forcing reformulation of traditional crown-flint achromat designs. European manufacturers face reformulation costs for heritage product lines while Asian suppliers gain temporary advantage from regulatory lag. The refractor segment is responding with increased fluorite-crystal adoption despite material cost premiums.
Consolidated national observatory purchasing is fragmenting into consortium-based shared-risk instruments. Large research facilities now pool capital through multi-institution governance structures rather than single-entity procurement, extending sales cycles while expanding contract values. This behavioral shift is most visible in US and Australian radio-optical hybrid facility planning where optical telescope contracts attach to larger array projects.
Optical Telescope Market Segmentation
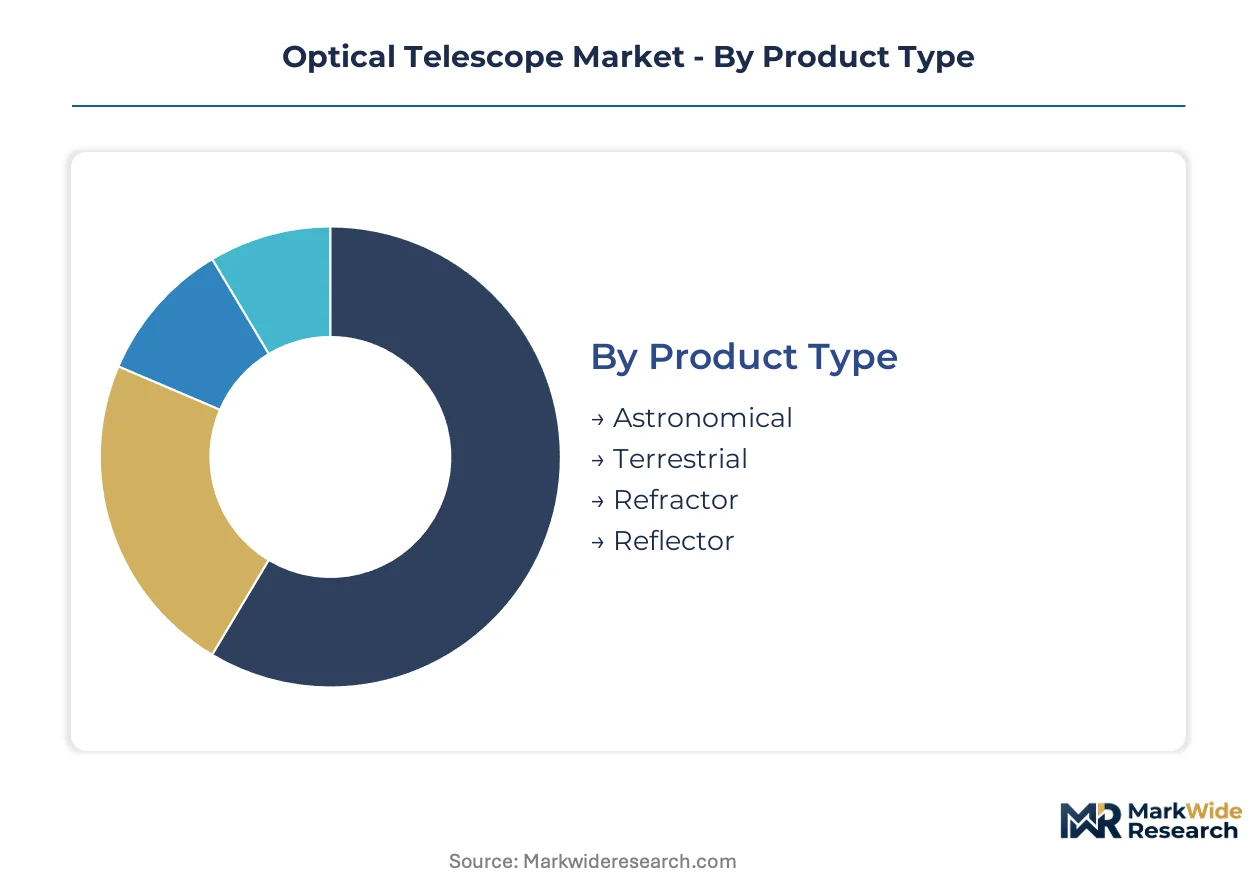
Segmentation in the optical telescope market tracks how procurement authority fragments across institutional hierarchies and how sensor technology restructures product architecture. Manufacturers must align production capacity with diverging specification requirements between grant-funded educational buyers and precision-demanding research consortia.
Product Type:
Supply concentration in large-aperture mirror fabrication favors reflector economics, while specialty glass monopolies constrain refractor expansion.
- Reflector:Curved primary mirrors collect and focus light through cost-efficient aluminum or silver coatings on glass substrates. Research institutions in Germany and the United States dominate procurement of meter-class instruments for exoplanet atmospheric characterization, constrained by 12-18 month polishing timelines that conflict with grant cycles.
- Refractor:Crown-flint or fluorite-crystal lens systems deliver superior color correction for high-resolution astrophotography. Ohara Corporation and Schott AG control specialty low-dispersion glass supply, creating single-source vulnerability for apochromatic manufacturers serving the premium amateur segment.
- Astronomical:Purpose-built instruments optimized for celestial observation with equatorial or alt-azimuth tracking mounts. Demand concentrates in university observatories and national facilities.
- Terrestrial:Erect-image optical systems for surveillance and spotting applications with weatherproofing requirements. Defense agencies and border security services drive specification standards.
Reflector configurations absorb the bulk of installed capacity; refractor systems are expanding most quickly in the premium astrophotography niche.
End User:
Customer concentration has inverted as national observatories consolidate purchasing power while educational institutions fragment into smaller grant-funded acquisitions.
- Research Institutions:National observatories and university consortia procure large-aperture systems with adaptive optics integration. The Max Planck Institute network in Germany sustains steady orders for precision instruments, anchoring European manufacturing capacity.
- Professional Astronomers:Individual credentialed researchers accessing shared-risk consortium instruments or dedicated facility time. Multi-institution governance structures now govern capital allocation, extending sales cycles while expanding contract values.
- Astronomy Enthusiasts:Individual consumers purchasing through mass-market distribution channels. CMOS sensor adoption is compressing demand for personal instrument ownership while expanding subscription-based remote telescope network participation.
- Educational Institutions:Schools and universities acquiring modular, transportable systems under NSF and EU Horizon program grants. Smaller procurement sizes favor standardized over custom specifications.
Research institutions command the largest contract values; educational institutions are climbing the fastest as grant programs democratize access.
Technology:
Digital sensor integration is restructuring competitive boundaries as CMOS technology displaces traditional eyepiece observation across all price tiers.
- Digital:Integrated CMOS sensor arrays enabling automated sky monitoring and data stacking algorithms. Amateur networks now operate continuous observation platforms, decentralizing scientific contribution authority from credentialed institutions.
- Optical:Traditional visible-light systems relying on glass optics and eyepiece observation. Heritage product lines face reformulation costs from REACH chemical restrictions on lead-containing optical glasses.
- Infrared:Thermal detection systems for satellite tracking and space situational awareness applications. Defense agencies specify rapid-slew robotic mounts with sub-arcsecond pointing accuracy.
- Radio:Non-optical frequency detection often hybridized with optical arrays in multi-wavelength facilities. Australian and US radio-optical hybrid planning attaches optical contracts to larger array projects.
Optical technology retains the largest installed base; digital systems are gaining share fastest through sensor-software convergence.
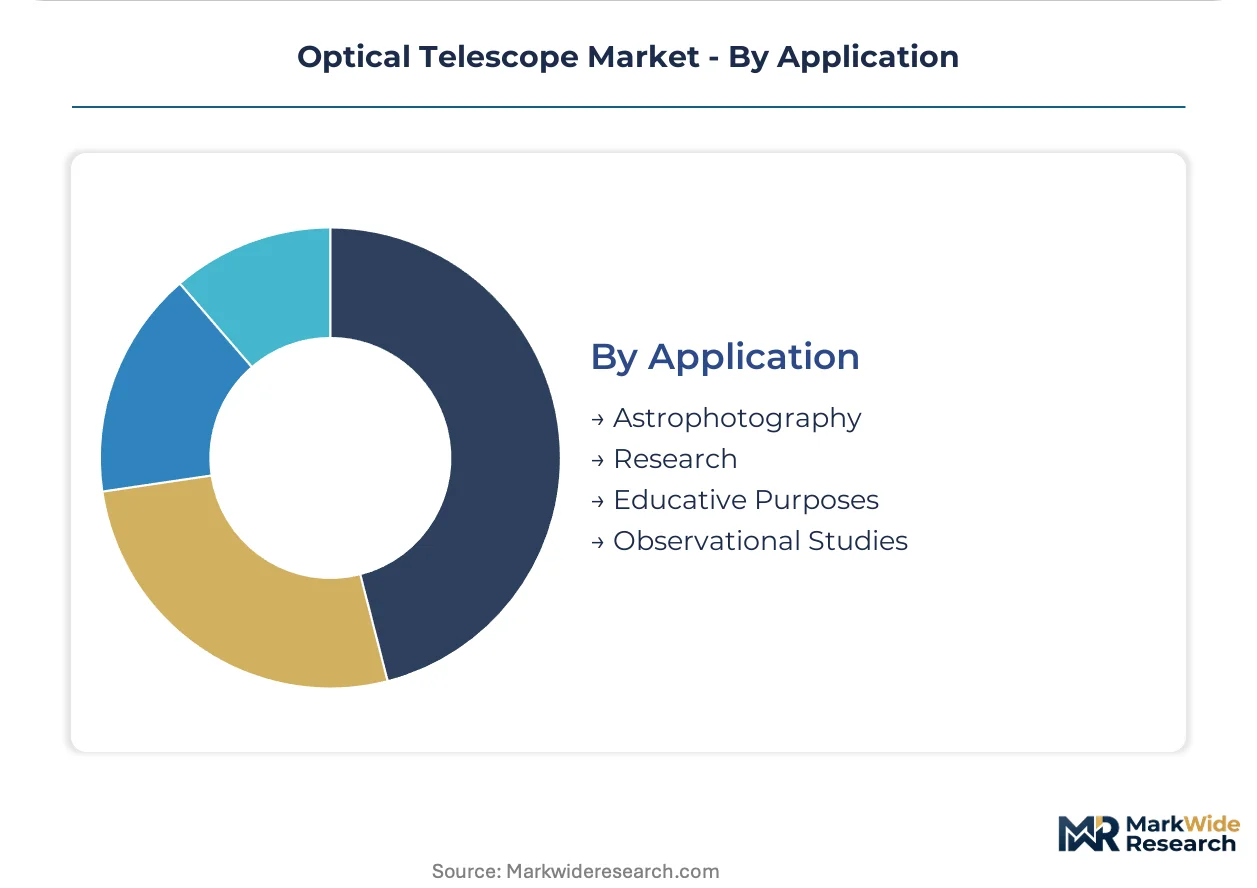
Application:
Application boundaries are blurring as computational imaging reduces hardware resolution requirements for astrophotography outputs.
- Research:Peer-reviewed scientific inquiry requiring calibrated photometric and spectroscopic data. ESA's tightening optical payload standards force wavefront correction integration, opening retrofit markets for existing ground-based installations.
- Astrophotography:Imaging-oriented observation prioritizing aesthetic and technical image quality. Synthetic aperture algorithms and post-processing stacking software reduce hardware investment thresholds.
- Observational Studies:Systematic monitoring programs for variable stars, asteroids, or satellite constellations. Citizen-science platforms verify distributed amateur contributions for scientific archive integration.
- Educative Purposes:Curriculum-supporting observation with simplified interfaces and durable construction. Modular transportable systems accommodate shared-resource scheduling across multiple institutions.
Research applications dominate capital deployment; astrophotography is expanding most quickly through consumer sensor accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty optical glass production concentrates in Germany and Japan, anchoring precision telescope manufacturing while research demand clusters around Max Planck Institute facilities and national observatory networks.
United States
National Science Foundation grant cycles drive procurement timing for university observatories, with meter-class mirror contracts often attaching to multi-wavelength array projects. FCC regulations govern motorized tracking system emissions for robotic telescope installations. Tucson, Arizona hosts concentrated optical fabrication capacity serving both institutional and defense satellite-tracking contracts.
Germany
The Max Planck Institute network sustains steady orders for precision instruments, anchoring European adaptive optics integration requirements. ESA tightening optical payload standards forces wavefront correction technology adoption across ground-based installations. Munich and Jena clusters concentrate specialty glass processing and large-aperture mirror polishing expertise.
Japan
Ohara Corporation controls low-dispersion optical glass supply for apochromatic refractor manufacturers serving premium astrophotography demand. METI industrial standards govern precision optics export certification. Osaka-Tokyo corridor hosts concentrated lens grinding and fluorite-crystal processing capacity for high-resolution instruments.
China
Domestic CMOS sensor manufacturing expansion reduces import dependency for digital telescope integration, compressing cost structures for automated observation platforms. MIIT standards regulate radio-frequency emissions from motorized mounts. Yangtze River Delta clusters concentrate mass-market telescope assembly for enthusiast distribution channels.
United Kingdom
Consortium-based shared-risk instrument procurement extends sales cycles while expanding contract values for multi-institution governance structures. Research Council funding frameworks prioritize modular transportable systems over permanent installations. Cambridge and Edinburgh clusters concentrate radio-optical hybrid facility planning expertise.
Optical Telescope Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-software convergence and subscription-based observation networks. The market structures around three tiers: mass-market distributors leveraging volume scale, precision manufacturers commanding premium positioning through specialty glass access, and custom builders serving exacting institutional specifications. Two dominant competitive moves define current positioning: strategic partnerships between glass suppliers and finished-goods manufacturers securing feedstock access, and portfolio diversification into automated remote observation platforms reducing customer acquisition costs.
Within the mass-market distribution tier, Celestron and Meade Instruments represent volume-driven positioning through broad retail channel penetration. Takahashi occupies a premium-manufacturing archetype anchored by Japanese precision optics heritage. Astro-Physics exemplifies the custom-build segment serving professional observatories with exacting tracking specifications. These three anchors illustrate how competitive positioning stratifies across price-performance vectors rather than geographic coverage alone.
| Leading Market Players |
|---|
| Celestron |
| Meade Instruments |
| Sky-Watcher |
| Orion Telescopes & Binoculars |
| Vixen Optics |
| Takahashi |
| Bushnell |
| Bresser |
| Astro-Physics |
| Others |
Supply Flow & Price Mechanics
Wavefront engineering expertise clustering around Munich and Tucson creates labor-cost differentials that stretch pricing-tier spreads between mass-market distributors and custom observatory builders. Mirror-polishing specialists command premium compensation that feeds directly into reflector pricing, while CMOS-sensor integration skills in Shenzhen compress digital-tier margins.
Pricing Analysis
Volume leadership concentrates in mass-market distribution where Celestron and Meade Instruments compete on scale, while margin capture sits with precision manufacturers like Takahashi and Astro-Physics. Three-tier pricing structure across premium, standard, and economy levels separates fluorite-crystal apochromats from aluminum-coated reflectors and entry-level refractors. Price differentiation hinges on ISO 10110 surface quality certification and adaptive optics integration depth. Cost compression in the enthusiast tier is intensifying because CMOS-sensor commoditization reduces hardware resolution thresholds for astrophotography outputs. Educational institutions exhibit highest price sensitivity due to grant-funded procurement constraints, whereas national observatories prioritize performance specifications over unit economics.
Supply Chain Analysis
Workforce availability for large-aperture mirror polishing concentrates in Germany, the United States, and Japan, constraining capacity expansion regardless of capital deployment. Raw material dependencies center on Schott AG and Ohara Corporation for low-dispersion optical glass, aluminum and silver coatings for mirror substrates, and fluorite crystal for apochromatic lens systems. Single-source vulnerability in specialty glass production creates supply chain risk that manufacturers mitigate through long-term offtake agreements. Distribution runs through mass-market retail channels for enthusiast products, direct institutional sales for research-grade instruments, and subscription-based remote telescope networks for data-service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Large-aperture primary mirror fabrication capacity acts as the binding constraint propping pricing power across institutional procurement tiers. Wavefront correction integration requirements from ESA tighten this bottleneck further.
For Market Incumbents: Cement feedstock security through captive partnerships with Schott AG or Ohara Corporation to defend against specialty glass supply disruption. Add polishing capacity in Jena or Tucson to compress 12-18 month lead times that currently conflict with grant cycles. Adaptive optics talent scarcity at academic centers threatens execution timelines for ESA-compliant retrofit contracts. For New Entrants and Emerging Players: CMOS-AO convergence technology offers entry into portable high-resolution systems previously restricted to facility-bound installations. Educational grant fragmentation under NSF and EU Horizon programs presents the most penetrable white space, favoring modular transportable designs over permanent observatory builds. Go-to-market positioning should emphasize subscription-based data-sharing platform economics rather than hardware ownership. For Investors and Strategic Acquirers: Re-rating potential sits with precision manufacturers possessing ISO 10110 certification and ESA supply chain access given tightening optical payload standards. Long-term viability favors entities with backward integration into specialty glass processing or captive mirror-polishing expertise. Watch ESA procurement qualification timeline acceleration as the inflection signal for capacity-constrained pricing power release.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Optics Integration | ESA payload standards force wavefront correction adoption across ground-based installations. |
| Specialty Glass Supply Agreement | Schott AG and Ohara Corporation partnerships secure low-dispersion feedstock for apochromatic refractors. |
| CMOS-Sensor Platform Convergence | Real-time atmospheric correction enables portable systems to achieve facility-grade resolution. |
| Remote Observation Network Launch | Subscription-based telescope access compresses personal ownership demand while expanding aggregate observation hours. |
| Educational Modular System Development | NSF and EU Horizon grant structures favor transportable designs over permanent installations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews across optical fabrication engineers, observatory procurement directors, adaptive optics researchers, and mass-market distribution managers. ESA technical standards documentation, ISO certification databases, and national research council grant award records provided secondary validation. Bottom-up telescope shipment aggregation and top-down research instrumentation budget analysis were triangulated against mirror-polishing capacity estimates.
Data-stream reconciliation across product type, end-user institution, sensor technology, and application purpose enabled segmentation-specific trajectory modeling. CAGRs were derived from installed base evolution and replacement cycle analysis across the projection horizon. Forecast inputs incorporated ESA optical payload standard implementation timelines, CMOS sensor cost curves, and specialty glass production capacity constraints from Schott AG and Ohara Corporation disclosures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH chemical restriction enforcement or sudden ESA qualification requirement shifts. Mirror-polishing specialist retirement rates and adaptive optics academic program graduation volumes represent critical assumption sensitivities. Material deviation in ESA procurement timeline acceleration or specialty glass supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Sports Optics Market
Optics
Fiber Optic Cable Market
Optics
Digital Holographic Microscopy Market
Optics
Quartz Glass Market
Optics
Fiber Optic Receiver Market
Optics
Fiber Optic Preform Market
Optics
Optical Sensing Market
Optics
India Laser Market
Optics
AR and VR Lens Market
Optics
Single-Mode Optical Fiber Market
Optics
Interchangeable Lens Market
Optics
Photostimulation Lasers Market
Optics
Europe Smart Glass Market
Optics
Beam Combining Optics Market
Optics
Stroboscope Market
Optics
Global High Purity Quartz Glass Market