
 Tunable Laser Market | 2026-2036
Tunable Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Tunable Laser Market Analysis
The EU Green Deal is hardening energy-efficiency requirements for optical components deployed in telecommunications and sensing networks. MKS Instruments leverages vertical integration across laser sources and photonic instruments to sustain margin control. Coherent anchors its position through R&D intensity in materials science for tunable gain media.
A tunable laser emits light at adjustable wavelengths across a defined spectral range, typically spanning tens to hundreds of nanometers depending on cavity design and gain medium composition. Engineers tune output through temperature adjustment, current modulation, or mechanical grating rotation to match precise wavelength requirements in fiber-optic communications and spectroscopic analysis. Semiconductor lasers dominate volume deployment in telecommunications backbones where dense wavelength-division multiplexing demands agile sources. Quantum cascade lasers represent the fastest-growing technology segment, driven by expanding adoption in infrared sensing and environmental monitoring applications.
FCC spectrum allocation rules in the United States, EU Green Deal efficiency mandates, and REACH chemical restrictions on laser dye formulations collectively shape product standards and market access conditions. FDA device classification requirements for medical laser systems further constrain design choices for healthcare applications. Stakeholders must monitor evolving regulatory convergence between electromagnetic spectrum policy and chemical safety frameworks to anticipate compliance costs.
Market Dynamics
Wavelength agility requirements in fiber-optic backbones are compressing product lifecycles and forcing simultaneous investments in semiconductor fabrication and external cavity designs.
Growth Catalysts
- DWDM Network Expansion:Dense wavelength-division multiplexing architectures in long-haul telecommunications require tunable sources for dynamic channel allocation.
- EU Green Deal Efficiency Mandates:Hardening energy-efficiency standards for optical components are accelerating replacement cycles of legacy fixed-wavelength equipment.
- Quantum Cascade Laser Materials:Advances in III-V semiconductor heterostructures are extending tunable range into mid-infrared bands for spectroscopic sensing.
Market Restraints
- Indium Phosphide Supply Concentration:Foundry capacity for InP substrates clusters in East Asian suppliers, exposing procurement to geopolitical friction.
- REACH Chemical Restrictions:ECHA limitations on laser dye formulations constrain organic dye laser architectures and force reformulation investments.
- Fixed-Wavelength Laser Substitution:Low-cost distributed feedback lasers satisfy price-sensitive applications where agility provides marginal value.
Strategic Opportunities
- Environmental Monitoring Applications:Quantum cascade lasers enable ppb-level detection of methane and NOx for climate compliance verification.
- India PLI Scheme Incentives:Production-linked incentives for telecom equipment manufacturing attract module assembly investments.
- Silicon Photonics Convergence:Hybrid integration of III-V gain chips with silicon nitride waveguides promises cost reduction at wafer scale.
Industry Challenges
- Packaging Engineering Talent Scarcity:Hermetic sealing and thermal management for butterfly packages require skills concentrated in aging workforce cohorts.
- ISO 10110 Optical Surface Certification:Extended qualification timelines for laser-grade polished surfaces delay new supplier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tunable Laser Market |
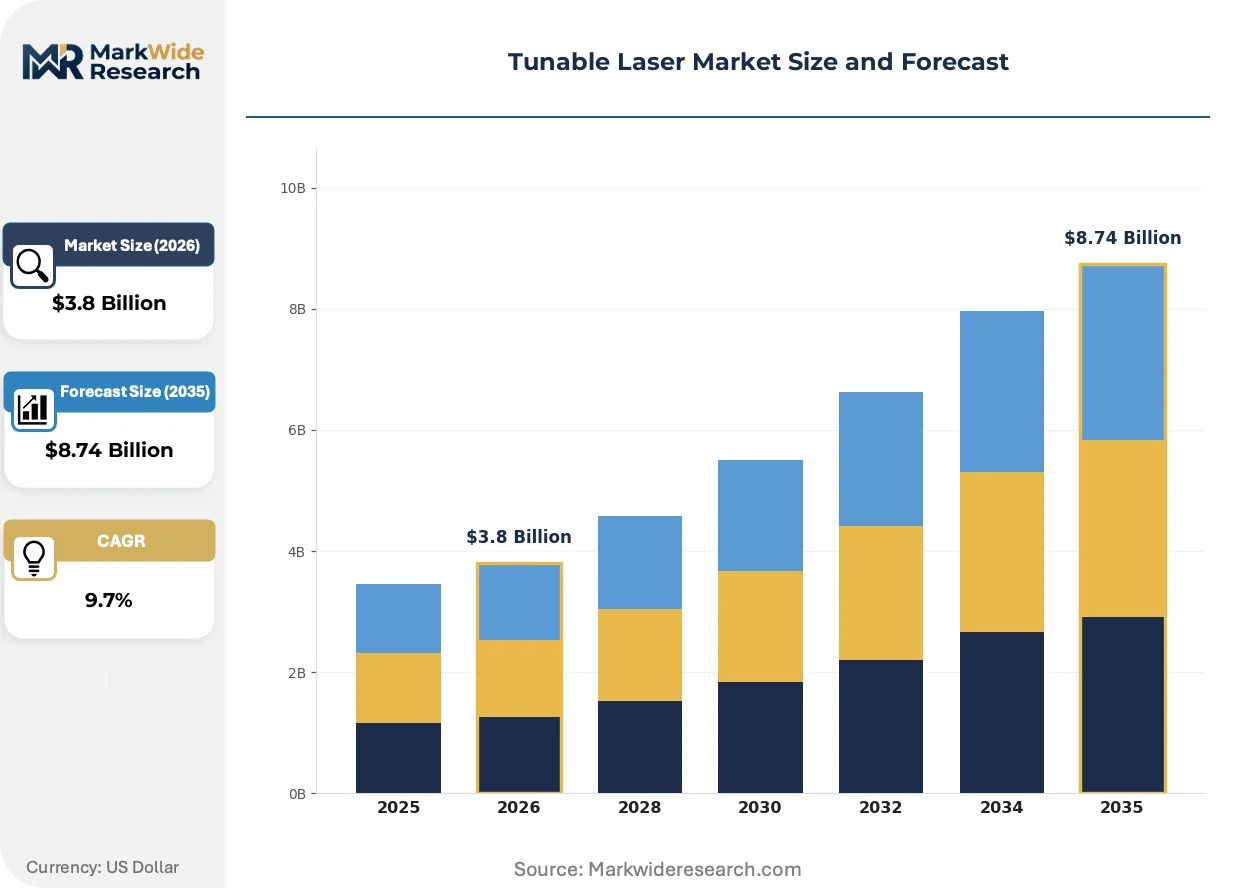
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Lasers, Dye Lasers, Fiber Lasers, Semiconductor Lasers Technology: DBR Laser, DFB Laser, Vertical-Cavity Laser, Quantum Cascade Laser Application: Telecommunications, Sensing, Material Processing, Medical End User: Aerospace, Defense, Healthcare, Research Institutions |
| Companies Covered | MKS Instruments, Toptica, Coherent, Hamamatsu Photonics, Thorlabs, IPG Photonics, Keysight Technologies, Santec, Lumentum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tunable Laser Market Emerging Trajectories
Photonic integration roadmaps are collapsing discrete component boundaries, while regulatory pressure on energy consumption and chemical safety accelerates design-rule revisions across gain medium categories.
External cavity diode lasers with Littman-Metcalf grating configurations are rewriting performance benchmarks for linewidth and tuning range. Metrology laboratories and coherent communication testbeds adopt these architectures for sub-100 kHz linewidth requirements. The technology is compressing addressable markets for traditional distributed Bragg reflector designs.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are reshaping cooling system designs in high-power laser installations. Manufacturers must qualify alternative refrigerants or transition to thermoelectric cooling for precision temperature control. Medical and industrial laser segments face the steepest redesign costs given FDA and MDR dual-certification requirements.
Telecom operators are consolidating supplier panels and demanding 15-year operational lifetime guarantees with predictive failure analytics. Equipment vendors respond with embedded photodiode monitoring and cloud-connected health diagnostics. Germany and Japan exhibit the most aggressive qualification timelines for these service-integrated procurement models.
Tunable Laser Market Segmentation
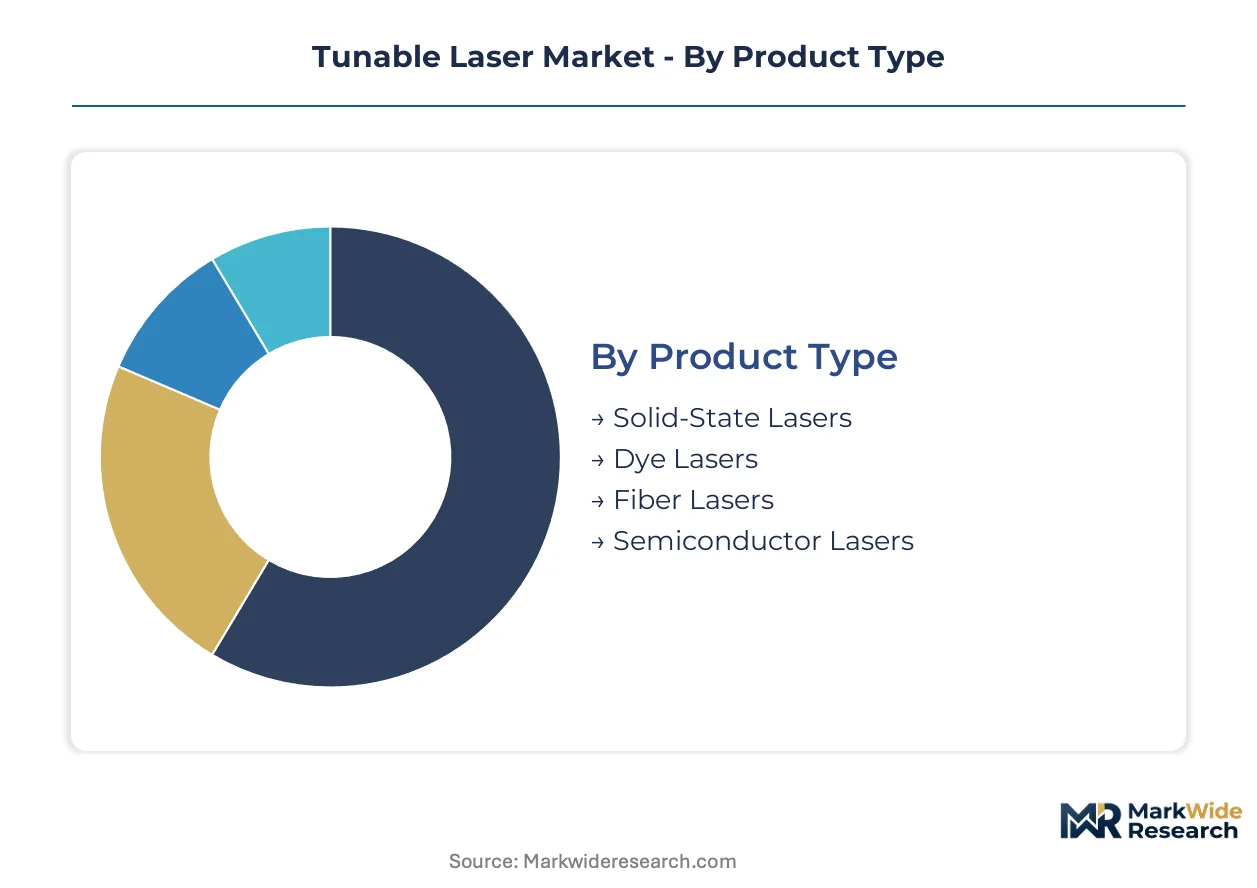
Wavelength agility requirements vary sharply across deployment contexts, from standalone laboratory instruments to embedded transceiver modules. Segmentation reveals where technical specifications diverge and where integration economics dominate procurement decisions.
Product Type:
Standalone benchtop systems serve metrology and research workflows, while chip-scale formats embed directly into telecommunications line cards and sensing nodes.
- Solid-State Lasers:Titanium-doped sapphire and Nd:YAG crystals deliver nanosecond pulse widths with thermal lensing managed through cryogenic or conductive cooling. Demand clusters in Germany's Berlin-Brandenburg photonics corridor for materials spectroscopy, constrained by EU F-Gas Regulation phase-downs affecting cooling system designs.
- Semiconductor Lasers:InGaAsP and AlGaAs heterostructures enable direct current modulation across C-band and L-band windows for dense wavelength-division multiplexing. Procurement from Deutsche Telekom and NTT accelerates as external cavity designs displace fixed-wavelength distributed feedback alternatives in long-haul routes.
- Fiber Lasers:Ytterbium-doped fiber architectures with integrated fiber Bragg gratings achieve kilowatt-class output for industrial micromachining.
- Dye Lasers:Organic rhodamine and coumarin solutions span visible spectra for biomedical fluorescence excitation, facing REACH chemical restrictions on solvent formulations.
Volume placements concentrate in Semiconductor Lasers; the faster expansion belongs to Solid-State Lasers.
Technology:
Cost tiers separate commodity telecom sources from precision scientific instruments, with foundry economics determining accessible performance thresholds.
- DFB Laser:Corrugated grating structures etched directly into the active region provide single-mode stability with 35 dB side-mode suppression. Deployment concentrates in Japan's metropolitan fiber rings where METI efficiency standards accelerate replacement of legacy fixed-wavelength equipment.
- Quantum Cascade Laser:Intersubband transitions in InGaAs/InAlAs superlattices extend emission into terahertz and mid-infrared bands for methane detection. Bavarian environmental monitoring networks and Alberta oil-sands operators drive procurement as climate verification mandates tighten.
- DBR Laser:Separate Bragg reflector sections enable wider tuning ranges than DFB architectures through current-controlled refractive index shifts.
- Vertical-Cavity Laser:Short cavity lengths perpendicular to the wafer surface support two-dimensional array fabrication for optical interconnects.
Premium pricing attaches to Quantum Cascade Laser architectures; DFB Laser volumes dominate telecommunications procurement.
Application:
Customer maturity separates price-sensitive volume buyers from specification-driven niche purchasers with extended qualification cycles.
- Telecommunications:Reconfigurable optical add-drop multiplexers demand sub-100 kHz linewidth for coherent 400G and 800G transmission. India's PLI scheme incentives attract module assembly investments from domestic and multinational vendors serving BSNL and Reliance Jio infrastructure builds.
- Sensing:Differential absorption lidar for atmospheric chemistry requires wavelength stability across temperature excursions for ppm-level gas discrimination. German TÜV certification requirements for industrial safety systems extend supplier qualification timelines.
- Medical:Ophthalmic photocoagulation and dermatological procedures demand FDA Class III device clearance with predictive failure analytics embedded.
- Material Processing:Selective laser melting and micromachining prioritize beam quality metrics over wavelength agility for metals and ceramics fabrication.
Telecommunications generates the highest shipment volumes; Sensing applications are climbing the fastest on environmental compliance spending.
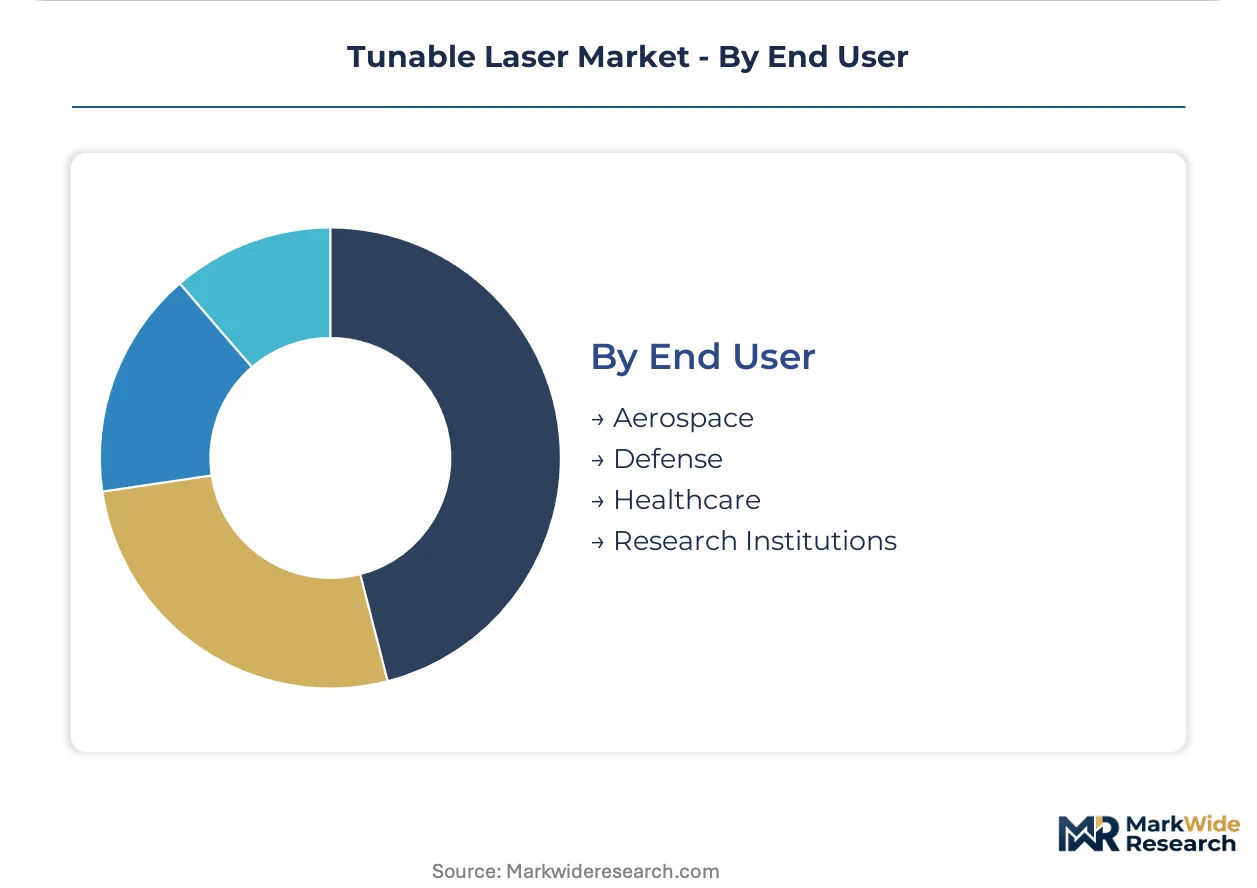
End User:
Supply concentration in defense-qualified foundries creates procurement bottlenecks distinct from commercial volume channels.
- Defense:MIL-STD-883 screening for hermetic butterfly packages with 15-year operational guarantees. Pentagon directed-energy and infrared countermeasure programs concentrate sourcing through cleared domestic suppliers with ITAR-controlled heterostructure epitaxy.
- Research Institutions:National laboratories and university consortia specify Littman-Metcalf external cavity configurations for sub-50 kHz linewidth in atomic physics and quantum information experiments. Max Planck Institute and RIKEN procurement cycles drive demand for customizable grating-motor assemblies.
- Aerospace:Satellite optical communication terminals require radiation-hardened pump diodes and thermoelectric cooling for geostationary orbit thermal environments.
- Healthcare:Hospital networks and ambulatory surgical centers prioritize disposable fiber delivery systems over capital equipment ownership for laser surgery platforms.
Defense procurement commands premium pricing tiers; Research Institutions are gaining share fastest on quantum technology funding expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian foundries for indium phosphide substrates, while consumption clusters in European and North American network infrastructure upgrades. The mismatch creates procurement vulnerabilities for wavelength-agile sources.
United States
Defense-directed energy programs and coherent 400G/800G telecommunications backbones drive procurement of external cavity designs. FCC spectrum allocation rules shape device certification timelines for commercial deployment. Pentagon sourcing concentrates through ITAR-controlled suppliers in California and Massachusetts corridors.
Germany
Deutsche Telekom infrastructure builds and Bavarian environmental monitoring networks accelerate quantum cascade laser adoption. EU Green Deal efficiency mandates compress replacement cycles for legacy fixed-wavelength equipment. Berlin-Brandenburg photonics clusters anchor metrology instrument manufacturing.
Japan
NTT metropolitan fiber ring expansions and RIKEN quantum research facilities sustain demand for sub-50 kHz linewidth sources. METI efficiency standards accelerate displacement of aging distributed feedback architectures. Kanto and Kansai industrial corridors concentrate butterfly package assembly capacity.
China
Domestic 5G backbone construction and dual carbon goals for methane monitoring expand quantum cascade deployment. MIIT standards for optical transceivers tighten wavelength stability requirements. Yangtze River Delta foundries concentrate InP epitaxy capacity for indigenous supply security.
India
BSNL and Reliance Jio infrastructure builds attract module assembly investments under PLI scheme incentives. TRAI spectrum policy shapes wavelength agility requirements for national fiber networks. Karnataka and Maharashtra telecom manufacturing zones concentrate packaging operations.
Tunable Laser Market Vendor Landscape
The competitive structure tilts toward vertically integrated instrument manufacturers with captive semiconductor fabrication. Three tiers separate premium scientific instrument houses from volume telecom component suppliers and specialized epitaxy foundries. Dominant competitive moves include backward integration into gain chip production and strategic partnerships with defense-qualified packaging houses.
Among diversified photonics conglomerates, MKS Instruments and Coherent exemplify the integrated archetype spanning laser sources through test instrumentation. Hamamatsu Photonics anchors the precision optoelectronics tier with Japanese manufacturing heritage. These three occupy positions where materials science R&D and hermetic packaging capabilities converge.
| Leading Market Players |
|---|
| MKS Instruments |
| Toptica |
| Coherent |
| Hamamatsu Photonics |
| Thorlabs |
| IPG Photonics |
| Keysight Technologies |
| Santec |
| Lumentum |
| Others |
Supply Flow & Price Mechanics
Hermetic sealing specialists concentrated in Japan's Kanto corridor command wage premiums that compress margins at the precision packaging tier while widening spreads between laboratory-grade and volume-telecom price points. Labor-cost differentials between German photonics clusters and East Asian assembly zones feed directly into tiered procurement economics for butterfly packages and external cavity assemblies.
Pricing Analysis
Margin tightening in mid-range semiconductor lasers reflects volume consolidation among Deutsche Telekom, NTT, and Reliance Jio procurement panels. Three-tier pricing structure across premium, standard, and economy levels separates sub-50 kHz linewidth external cavity instruments from fixed-wavelength DFB alternatives and commodity distributed feedback chips. Price differentiation hinges on ISO 10110 optical surface certification grade and embedded predictive analytics capability. Defense-qualified suppliers with ITAR-controlled epitaxy capture least price-sensitive demand; volume telecom module vendors face acute sensitivity to per-watt benchmarks.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from NTT and Deutsche Telekom, while distributor networks serve research institutions and medical device OEMs. InP substrate supply concentrates in Taiwan, China, and Japan; III-V epitaxy services cluster in California and Massachusetts defense corridors. Raw material dependencies include indium metal, high-purity phosphine gas, and laser-grade fused silica substrates. Single-source vulnerability around hermetic butterfly package sealing equipment exposes lead times to Japanese equipment builder queues. Distribution runs through cleared domestic channels for Pentagon-directed energy programs and open commercial lanes for telecom infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indium phosphide foundry capacity constraints prop pricing power for captive epitaxy owners while forcing module vendors into long-term offtake commitments. The supply-constrained structure favors incumbents with backward-integrated gain chip production.
For Market Incumbents: Deploy in-house InP epitaxy capacity additions in California and Massachusetts corridors to offset East Asian foundry concentration risk. Secure ITAR-qualified packaging partnerships before Pentagon directed-energy procurement accelerates. Fixed-wavelength DFB substitution threats from low-cost distributed feedback vendors demand linewidth performance differentiation in coherent 400G/800G segments. For New Entrants and Emerging Players: Regional environmental monitoring agencies in Bavaria and Alberta present underserved buyer archetypes with climate verification mandates tightening methane detection procurement. Quantum cascade laser module assembly for oil-sands operators and TÜV-certified industrial safety systems offers white-space penetration below tier-one defense and telecom concentration. A go-to-market angle through cloud-connected health diagnostics bundling addresses telecom operator demands for 15-year operational guarantees. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing captive III-V epitaxy and ISO 10110-certified optical polishing given EU Green Deal efficiency mandates accelerating replacement cycles. Long-term viability centers on dual-use technology positioning spanning defense infrared countermeasures and environmental sensing applications. The signal to watch is PLI scheme disbursement velocity in India attracting module assembly investments from multinational vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into InP Epitaxy | Captive substrate supply insulates margin from East Asian foundry concentration and geopolitical friction. |
| ISO 10110 Optical Surface Certification Investment | Extended qualification timelines create switching costs for metrology and coherent communication buyers. |
| Quantum Cascade Laser Platform Expansion | Mid-infrared band extension captures Bavarian environmental monitoring and Alberta oil-sands procurement. |
| Cloud-Connected Health Diagnostics Embedding | Predictive failure analytics satisfy Deutsche Telekom and NTT 15-year operational guarantee demands. |
| ITAR-Controlled Packaging Partnership | Cleared domestic supplier status unlocks Pentagon directed-energy and infrared countermeasure programs. |
Methodological Framework
SEC 10-K filings, ECHA REACH restriction notices, and ITAR supplier registry data formed the secondary backbone for supply chain mapping and regulatory constraint identification. Primary interviews with III-V epitaxy process engineers, hermetic packaging specialists, and telecom procurement managers at Deutsche Telekom and NTT supplemented secondary validation. Bottom-up and top-down triangulation cross-checked unit shipment estimates against foundry capacity disclosures and infrastructure build announcements.
Bottom-up modeling aggregated segment-level demand across telecommunications, sensing, medical, and material processing applications; top-down constraints checked aggregate against indium phosphide substrate supply estimates. Segmentation dimensions included product type, technology architecture, application vertical, and end-user category across the analysis window. CAGRs derived from fitted growth curves incorporating EU Green Deal mandate timelines, India PLI scheme incentive trajectories, and quantum cascade laser materials science advancement rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to InP foundry capacity expansion decisions and REACH chemical restriction amendments affecting laser dye formulations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Excimer Laser Market
Optics
Optical Profilometer Market
Optics
Global Nanophotonics Market
Optics
Picosecond Lasers Market
Optics
Beam Expanders Market
Optics
Fiber Optic Development Tools Market
Optics
Glass Scintillator Market
Optics
EUV Pellicle Market
Optics
Europe Smart Glass Market
Optics
North America Optical Imaging Market
Optics
3D Optical Microscope Market
Optics
Photostimulation Lasers Market
Optics
Interchangeable Lens Market
Optics
Quartz Glass Market
Optics
Optical Wavelength Service Market
Optics
Residential 1080P Laser Television Projector Market