
 Gaas Photodiode Market | 2026-2036
Gaas Photodiode Market Size, Share, and Industry Trends Forecast 2026-2036
Gaas Photodiode Market Foresight
Discrete packaging of GaAs photodiodes into chip-scale and wafer-level formats is fragmenting traditional module-level supply chains. Hamamatsu Photonics K.K. sustains dominance in high-sensitivity avalanche designs through captive crystal growth capabilities. Broadcom Inc. leverages vertical integration from epitaxy to packaged devices for fiber optic communication customers. II-VI Incorporated anchors North American supply with specialized foundry services for defense-qualified components.
A gallium arsenide photodiode is a semiconductor optoelectronic detector fabricated from III-V compound material, typically achieving responsivity above 0.5 A/W at 850 nm wavelength with rise times under 100 picoseconds for high-speed variants. Its primary purpose is converting optical signals into electrical current in wavelength regimes where silicon detectors exhibit poor quantum efficiency. P-i-N photodiodes occupy the largest volume share due to mature telecom infrastructure replacement cycles, while avalanche photodiodes command premium positioning in Lidar and aerospace applications where single-photon sensitivity justifies higher unit costs. Extended near-infrared technology is displacing legacy germanium alternatives in datacenter transceivers.
The FDA governs optical radiation safety and biocompatibility for medical imaging devices incorporating GaAs photodiodes, while the EPA restricts hazardous substance content through RoHS-aligned enforcement. FCC Part 15 emissions standards shape design constraints for photodiodes integrated into consumer-facing Lidar and communication hardware. Stakeholders must monitor pending amendments to defense procurement regulations that could mandate domestic epitaxial wafer sourcing for sensitive applications.
Market Dynamics
Defense procurement of avalanche photodiodes for Lidar systems is compressing development cycles and forcing foundries to qualify alternative epitaxial sources as domestic sourcing mandates tighten.
Growth Catalysts
- Automotive Lidar deployment:Autonomous vehicle programs in Germany require high-sensitivity GaAs photodiodes for precision ranging, pulling volume from telecom infrastructure into mobility sensing applications.
- FCC Part 15 emissions standards:Consumer-facing Lidar hardware must meet strict electromagnetic compatibility thresholds, creating certified-component demand that favors established GaAs suppliers with pre-qualified designs.
- Extended near-infrared sensitivity:Datacenter transceiver manufacturers are replacing germanium detectors with GaAs alternatives to improve quantum efficiency at 850 nm wavelength.
Market Restraints
- Epitaxial wafer supply concentration:Captive crystal growth capabilities at dominant Japanese suppliers limit second-source availability for defense-qualified components.
- RoHS-aligned hazardous substance restrictions:EPA enforcement of material purity standards raises compliance costs for industrial photodiode packaging.
- Silicon photonics substitution:Silicon-based detectors threaten cost-sensitive telecom applications where GaAs responsivity advantages do not justify unit premiums.
Strategic Opportunities
- Medical imaging device certification:FDA biocompatibility requirements for optical radiation safety create premium positioning for photodiodes meeting Class IIIa laser product standards.
- Chip-scale packaging convergence:Wafer-level integration with CMOS readout circuits enables new form factors in wearable health monitors.
- India PLI scheme incentives:Domestic manufacturing subsidies for compound semiconductors attract packaging investments serving Middle East and Southeast Asian defense contractors.
Industry Challenges
- III-V epitaxy skill scarcity:Foundry operators struggle to hire process engineers with MOCVD reactor experience for high-volume GaAs production.
- Defense qualification timelines:MIL-STD-883 testing cycles extend 18-24 months, freezing design iterations for sensitive aerospace applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaas Photodiode Market |
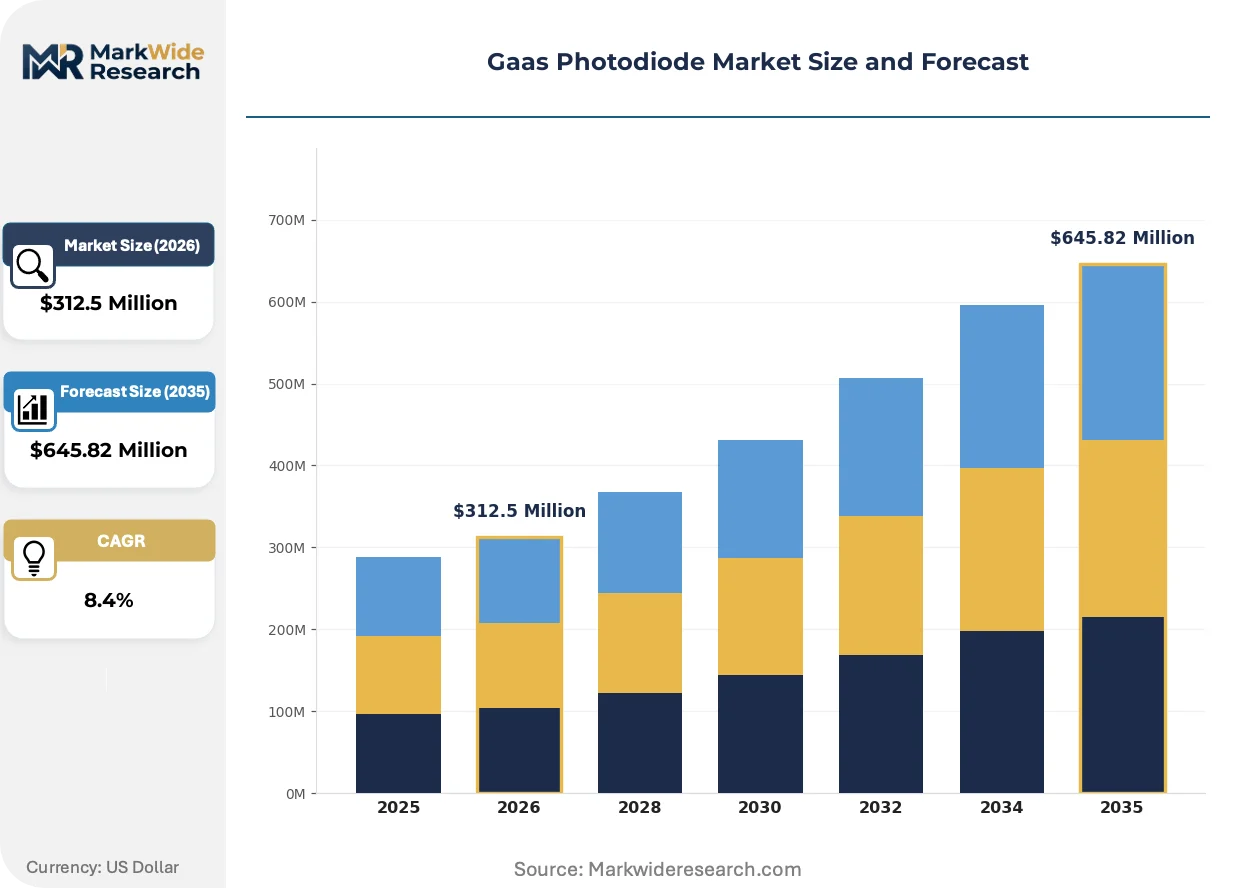
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: P-i-N Photodiodes, Avalanche Photodiodes, Metal-Semiconductor-Metal, Schottky Photodiodes, Phototransistors Technology: High-Speed, High-Sensitivity, Low-Noise, Wide Bandgap, Extended Near-Infrared, UV Detection Application: Fiber Optic Communication, Lidar Systems, Medical Imaging, Industrial Automation, Environmental Monitoring, Aerospace End User: Telecommunication Operators, OEM Manufacturers, Research Laboratories, Defense Agencies, Semiconductor Foundries |
| Companies Covered | Broadcom Inc., Hamamatsu Photonics K.K., II-VI Incorporated, Global Communication Semiconductors, LLC, KYOTO SEMICONDUCTOR Co., Ltd., OSI Optoelectronics Ltd., Electro-Optics Technology Inc., Albis Optoelectronics AG, Lumentum Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaas Photodiode Market Shifts & Advancements
Wafer-level packaging and heterogeneous integration are collapsing traditional module boundaries, while regulatory pressure on supply chain provenance accelerates captive manufacturing investments.
Single-photon avalanche diode arrays are digitizing Lidar receiver architectures by replacing analog signal chains with direct time-of-flight counting. Automotive OEMs in Germany and the United States are qualifying these devices for 2026 platform launches. The shift is digitizing distance measurement from continuous waveform analysis to discrete photon detection, compressing sensor fusion complexity.
REACH substance restrictions on gallium arsenide processing chemicals are forcing European foundries to retrofit waste handling systems or relocate epitaxial operations. The regulation affects primarily small-batch research contractors serving precision metrology laboratories. German suppliers are responding by consolidating processing at centralized facilities with advanced effluent treatment.
Specification-driven procurement now dominates defense and automotive verticals, with buyers mandating traceable epitaxial growth records rather than accepting standard commercial grades. Tier-1 Lidar integrators are disintermediating legacy distributors to secure direct foundry relationships. The pattern is most visible in United States defense procurement, where prime contractors now require documented wafer-level provenance for avalanche photodiode shipments.
Gaas Photodiode Market Segmentation
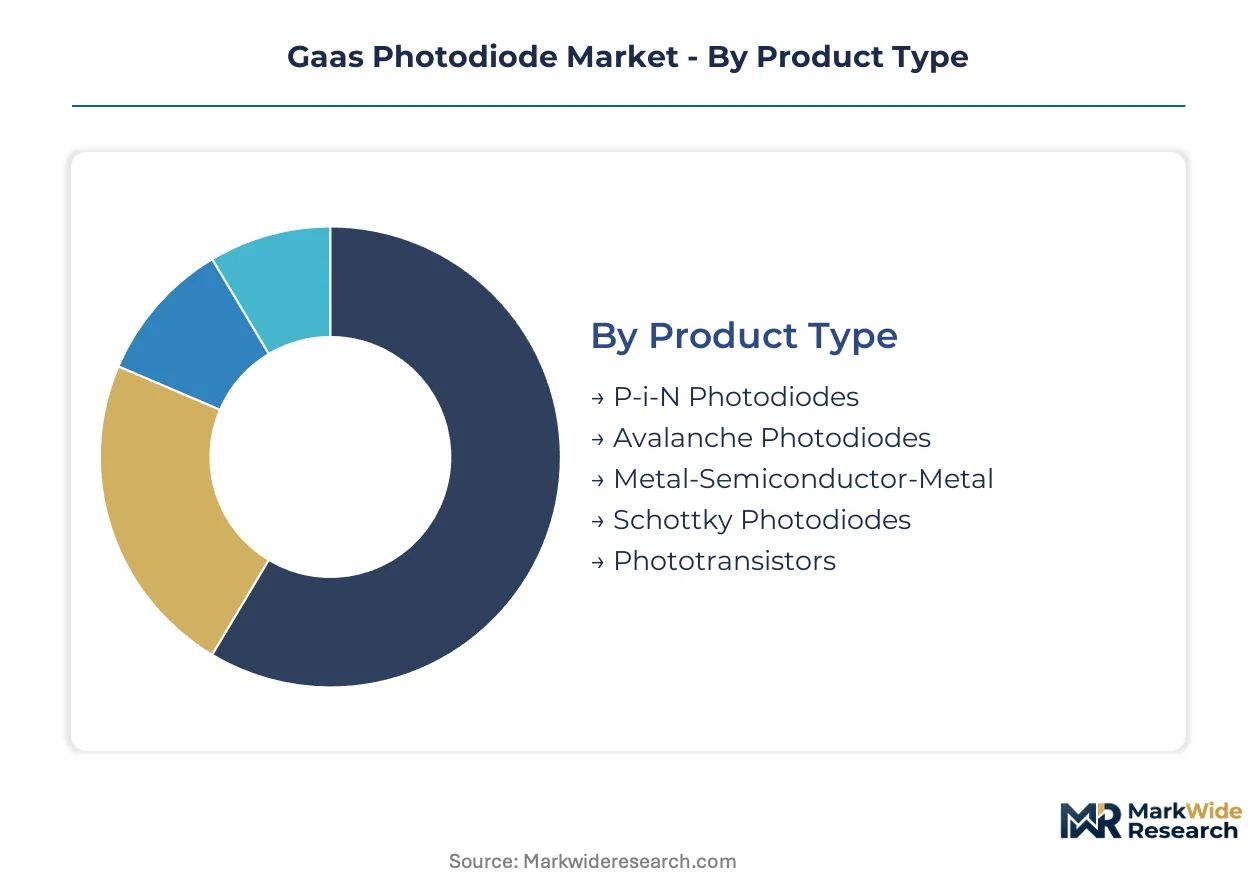
GaAs photodiode procurement patterns diverge sharply across technical specifications and end-use certifications, with defense-qualified components commanding fundamentally different supply chain relationships than commercial telecom volumes. Understanding these segment boundaries clarifies where captive manufacturing investments concentrate versus where merchant foundry competition operates.
Product Type:
After-sales service intensity varies dramatically by product type, with avalanche photodiodes requiring specialized calibration support while P-i-N variants run on standardized replacement cycles.
- Avalanche Photodiodes:These devices incorporate internal gain mechanisms through impact ionization, achieving single-photon sensitivity critical for long-range detection. United States defense agencies are compressing procurement timelines for these components in advanced Lidar systems, forcing foundries to qualify alternative epitaxial sources under tightening domestic sourcing mandates.
- P-i-N Photodiodes:A simple intrinsic layer sandwiched between p-type and n-type regions delivers fast response with low bias voltage requirements. Telecommunication infrastructure replacement cycles in Germany and Japan sustain the highest volume demand, though silicon photonics substitution threatens cost-sensitive applications where responsivity premiums cannot be justified.
- Metal-Semiconductor-Metal:Interdigitated electrode structures on undoped GaAs enable sub-picosecond response times for ultra-fast optical sampling systems in research laboratories.
- Schottky Photodiodes:Metal-semiconductor junctions eliminate diffusion capacitance limitations, serving high-frequency RF-over-fiber links in defense communication backbones.
- Phototransistors:Integrated transistor gain stages amplify photocurrent without external circuitry, finding niche deployment in industrial automation proximity sensors.
P-i-N Photodiodes hold the largest share; momentum sits with Avalanche Photodiodes.
Technology:
Cost tier separation between high-sensitivity designs for aerospace and standard-speed variants for datacenter transceivers determines foundry process development priorities.
- High-Sensitivity:Optimized quantum efficiency and minimal dark current support single-photon detection thresholds. Automotive OEMs in Germany are qualifying these designs for autonomous vehicle platforms, pulling process development investment away from legacy telecom specifications.
- Extended Near-Infrared:Modified bandgap engineering pushes responsivity beyond 900 nm wavelength regimes. Datacenter transceiver manufacturers in the United States and Ireland are displacing germanium detectors with these GaAs alternatives to improve coupling efficiency at 850 nm.
- High-Speed:Minimized carrier transit times achieve rise times under 100 picoseconds for 100 Gbps fiber optic communication receivers.
- Low-Noise:Suppressed dark current density serves medical imaging applications where FDA optical radiation safety classifications require predictable signal-to-noise performance.
- Wide Bandgap:Enhanced temperature stability supports aerospace applications under MIL-STD-883 qualification protocols.
- UV Detection:Surface-passivated structures extend sensitivity into ultraviolet regimes for environmental monitoring instrumentation.
Extended Near-Infrared is expanding most quickly; High-Sensitivity maintains premium positioning.
Application:
Customer type fragmentation separates specification-driven defense procurement from price-sensitive industrial automation volumes.
- Lidar Systems:Time-of-flight ranging architectures demand precise photon timing resolution. Tier-1 integrators in the United States are disintermediating legacy distributors to secure direct foundry relationships with documented wafer-level provenance requirements.
- Fiber Optic Communication:Massive installed base drives replacement volume, though silicon photonics integration threatens discrete GaAs component demand in next-generation coherent transceivers.
- Medical Imaging:FDA biocompatibility and optical radiation safety regulations create certification barriers that favor established suppliers with Class IIIa laser product compliance histories.
- Industrial Automation:Position sensing and machine vision applications prioritize unit cost over performance margins, exposing segments to Asian merchant foundry competition.
- Environmental Monitoring:Spectroscopic detection of atmospheric constituents requires stable responsivity across temperature extremes.
- Aerospace:MIL-STD-883 testing cycles extending 18-24 months freeze design iterations and concentrate procurement among qualified North American suppliers.
Fiber Optic Communication holds the largest share; Lidar Systems are gaining share fastest.
End User:
Supply concentration patterns map directly to end user qualification requirements, with defense agencies and semiconductor foundries driving divergent epitaxial sourcing strategies.
- Defense Agencies:United States procurement regulations mandate traceable epitaxial growth records and domestic wafer sourcing for sensitive applications, compressing available supplier pools.
- Telecommunication Operators:Infrastructure replacement cycles sustain volume demand for standardized P-i-N designs with minimal customization requirements.
- OEM Manufacturers:Automotive and industrial equipment builders specify performance tiers without dictating process technology, enabling merchant foundry competition.
- Research Laboratories:Small-batch precision metrology requirements in Germany favor suppliers with flexible MOCVD reactor scheduling.
- Semiconductor Foundries:Captive integration from epitaxy to packaged devices at leaders like Broadcom and Hamamatsu limits merchant market access for specialized avalanche designs.
Telecommunication Operators hold the largest share; Defense Agencies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German foundries export precision-matched avalanche photodiodes to United States defense integrators, while Japanese crystal growth specialists supply epitaxial wafers to Irish datacenter transceiver manufacturers.
United States
Defense procurement mandates from the Department of Defense compress qualification timelines for Lidar-grade avalanche photodiodes. FCC Part 15 emissions standards shape design constraints for consumer-facing hardware. Boston-area photonics clusters host prime contractors requiring documented wafer-level provenance for sensitive aerospace applications.
Germany
Automotive OEMs in Stuttgart and Munich pull high-sensitivity GaAs photodiodes into autonomous vehicle sensing platforms. REACH substance restrictions force foundries to retrofit waste handling systems for gallium arsenide processing chemicals. Bavarian research laboratories consolidate precision metrology procurement at centralized facilities with advanced effluent treatment.
Japan
Hamamatsu Photonics K.K. sustains dominance through captive crystal growth capabilities for high-sensitivity avalanche designs. METI industrial policy supports compound semiconductor foundry modernization. Hamamatsu City anchors domestic supply chains with integrated epitaxy-to-packaging operations serving telecom and medical imaging verticals.
Ireland
Datacenter transceiver manufacturers displace germanium detectors with extended near-infrared GaAs alternatives to improve quantum efficiency at 850 nm. EU Green Deal alignment pressures packaging subcontractors to reduce hazardous substance content. Dublin and Cork host hyperscale operator procurement teams specifying traceable epitaxial sourcing for 100 Gbps receiver modules.
India
PLI scheme incentives for compound semiconductor manufacturing attract packaging investments serving Middle East defense contractors. BIS standards harmonization with RoHS-aligned restrictions raises entry barriers for imported components. Telangana and Karnataka foundry clusters specialize in chip-scale formats for wearable health monitor integration.
Gaas Photodiode Market Competitive Landscape
On the supply side, the industry is bifurcated between captive-integrated conglomerates and specialized merchant foundries. Japanese and North American leaders control upstream crystal growth, constraining second-source availability for defense-qualified components. Three archetypes dominate: epitaxy-captive integrated device manufacturers, defense-specialized foundries, and telecom-focused merchant suppliers. Competitive moves concentrate on backward integration into MOCVD reactor capacity and qualification of alternative domestic wafer sources under tightening procurement regulations.
Among epitaxy-captive integrated device manufacturers, Broadcom Inc. and Hamamatsu Photonics K.K. exemplify the premium-tier positioning that limits merchant market access for specialized avalanche designs. II-VI Incorporated anchors North American defense-qualified supply with foundry services concentrated on MIL-STD-883 testing protocols. These three entities represent the structural concentration that compresses available supplier pools for traceable-provenance procurement.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Hamamatsu Photonics K.K. |
| II-VI Incorporated |
| Global Communication Semiconductors, LLC |
| KYOTO SEMICONDUCTOR Co., Ltd. |
| OSI Optoelectronics Ltd. |
| Electro-Optics Technology Inc. |
| Albis Optoelectronics AG |
| Lumentum Holdings Inc. |
| Others |
Supply & Pricing Matrix
The Yokohama-to-Long Beach maritime corridor carries epitaxial wafer shipments whose freight cost volatility amplifies pricing spreads between captive-integrated Japanese suppliers and merchant foundries in North America. Defense procurement mandates for traceable provenance compress available supplier pools, concentrating pricing power among qualified vendors while RoHS-aligned compliance costs widen spreads between industrial and aerospace-grade components.
Pricing Analysis
Generation-gap pricing separates extended near-infrared designs displacing germanium detectors from legacy P-i-N variants facing silicon photonics substitution. Three-tier pricing structure across defense-qualified, automotive-certified, and commercial-telecom levels reflects MIL-STD-883 testing cycles and FDA biocompatibility investments. Pricing pressure stems from silicon photonics integration in datacenter transceivers, where responsivity premiums no longer justify unit costs. Telecommunication operators exhibit highest price sensitivity; defense agencies accept substantial premiums for documented wafer-level provenance.
Supply Chain Analysis
Extended payment terms from Japanese crystal growth specialists to Irish datacenter transceiver manufacturers illustrate supplier-financing concentration in upstream III-V epitaxy. Supply concentrates in Japan, the United States, and Germany, with captive MOCVD reactor capacity at Hamamatsu and Broadcom limiting merchant market access. Raw material dependencies center on high-purity gallium metal, arsenic precursors, and specialized quartz reactor components. Single-source vulnerability in defense-qualified epitaxial wafer sourcing constitutes primary structural risk. Distribution runs through direct foundry relationships that Tier-1 Lidar integrators are establishing, bypassing legacy distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by automotive Lidar deployment timelines compressing procurement windows. Defense and datacenter capital cycles now align to pull volume through qualified supply channels.
For Market Incumbents: Harden captive crystal growth capabilities against domestic sourcing mandates tightening in United States defense procurement. Qualify alternative epitaxial sources in allied geographies before qualification timelines extend further. Lock in direct relationships with Tier-1 automotive OEMs in Germany to secure platform-level design wins before 2026 launches finalize.
For New Entrants and Emerging Players: Establish a beachhead in chip-scale packaging for wearable health monitors, where FDA biocompatibility requirements have not yet concentrated supply among incumbents. Target India's PLI-subsidized foundry clusters serving Middle East defense contractors with less stringent provenance documentation. Pursue foundry service models rather than competing with captive-integrated IDMs on avalanche photodiode designs.
For Investors and Strategic Acquirers: Pending amendments to defense procurement regulations reshapes the acquisition landscape toward domestic epitaxial wafer sourcing capabilities. Five-to-ten-year viability favors specialized foundries with MIL-STD-883 testing infrastructure and existing aerospace customer relationships. Acquisition target archetype: mid-cap defense-qualified foundries with underutilized MOCVD reactor capacity. Signal to watch: Tier-1 Lidar integrators disintermediating distributors to secure direct foundry relationships.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MOCVD Reactor Capacity | Captive epitaxial growth secures supply for defense-qualified avalanche photodiode production. |
| Domestic Wafer Sourcing Qualification | Alternative epitaxial sources satisfy tightening United States procurement regulations for sensitive applications. |
| Wafer-Level Packaging Convergence | CMOS readout circuit integration enables new form factors in wearable health monitors and automotive sensors. |
| REACH-Compliant Effluent Treatment Consolidation | Centralized processing facilities preserve European foundry access amid substance restrictions on GaAs chemicals. |
| Direct Foundry Relationship Establishment | Tier-1 Lidar integrators bypass distributors to secure documented provenance and compress procurement timelines. |
Research Methodology
A standing panel of MOCVD process engineers, defense procurement officers, Tier-1 automotive Lidar integrators, and datacenter transceiver procurement leads provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, FDA 510(k) optical device submissions, EPA enforcement records for RoHS-aligned restrictions, and METI industrial policy documents. Bottom-up shipment data from epitaxial wafer suppliers triangulated against top-down defense budget appropriations and automotive platform deployment schedules.
Scenario-bracketing framed projections across defense procurement acceleration, silicon photonics substitution velocity, and automotive Lidar adoption curves. Segmentation dimensions modeled encompass product type, sensitivity technology tier, application vertical, and end-user qualification requirements across the projection horizon. CAGRs derived from fitted growth curves applied to disclosed capital expenditure patterns and foundry capacity expansion announcements. Industry-specific inputs included MIL-STD-883 testing cycle durations and FDA Class IIIa laser product certification timelines.
Stress conditions across epitaxial wafer supply concentration, REACH substance restriction enforcement intensity, and defense domestic-sourcing mandate implementation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained automotive Lidar deployment and datacenter transceiver refresh cycles. Macroeconomic contraction, regulatory delay, or breakthrough silicon photonics performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
South Korea Optoelectronics Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Taiwan Optoelectronics Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Europe Wigig Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market