
 Radiation Detection Device Market | 2026-2036
Radiation Detection Device Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Detection Device Market Outlook
Modular sensor packaging is decoupling detector heads from readout electronics, letting buyers mix scintillation crystals with interchangeable digital backends. Thermo Fisher Scientific anchors this trend through its configurable radiation monitoring platforms. AMETEK, INC. leverages its semiconductor fabrication capabilities to produce solid-state detectors at scale. Mirion Technologies, Inc. dominates the nuclear power plant channel with integrated containment monitoring systems.
Radiation detection devices are instruments that measure ionizing radiation intensity through gas ionization, scintillation light emission, or solid-state charge collection, with sensitivity thresholds spanning microsieverts to grays depending on the sensor architecture. Their primary purpose is to protect personnel, secure facilities, and ensure regulatory compliance across environments where radioactive materials are present. Scintillation detectors lead the device type category due to superior energy resolution in spectroscopy applications. Solid-state technology captures the fastest expansion as silicon photomultipliers and cadmium zinc telluride crystals displace legacy photomultiplier tubes. Healthcare end users represent the deepest margin pool because hospitals pay premiums for calibrated dosimetry tied to ALARA programs.
The NRC enforces 10 CFR Part 20 standards for occupational radiation exposure, compelling employers to maintain personal dosimetry programs that refresh device fleets on fixed cycles. EPA RadNet specifications and FDA 21 CFR Subchapter J requirements for medical imaging equipment create overlapping compliance obligations that shape product design priorities. Stakeholders must monitor how the NRC's anticipated reactor license renewals and emerging small modular reactor deployments reshape demand for area monitors and portal detection systems.
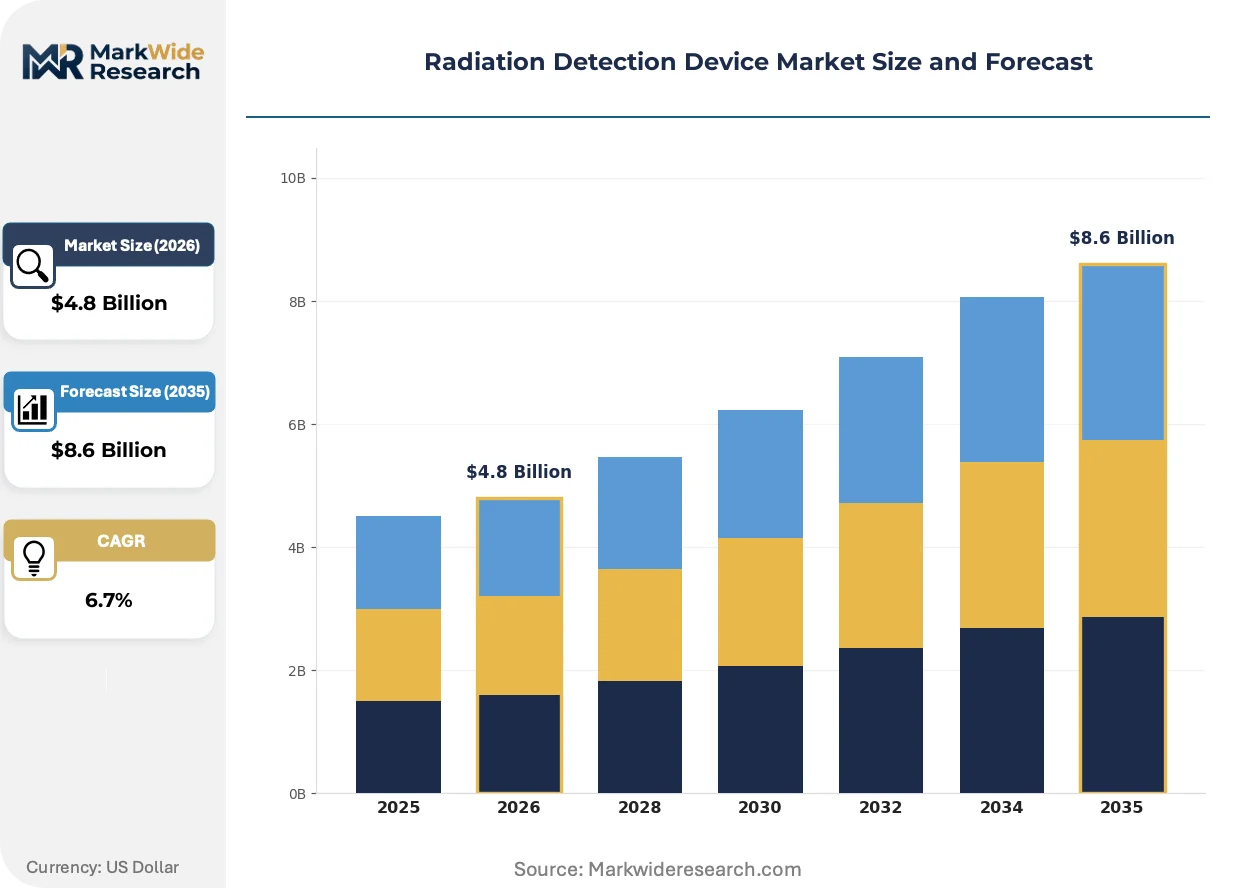
Market Dynamics
Modular sensor architectures are fragmenting procurement patterns across the radiation detection device market, enabling buyers to source detector crystals and digital backends from separate suppliers rather than accepting bundled systems. This decoupling is compressing margins for integrated-platform vendors while opening entry points for specialized component manufacturers.
Growth Catalysts
- 10 CFR Part 20 Compliance Cycles:The NRC's mandatory personnel dosimetry refresh schedules create predictable replacement demand across hospital networks and national laboratories in the United States.
- Silicon Photomultiplier Maturation:Solid-state photon counting is displacing vacuum-tube photomultipliers in scintillation readout chains, reducing detector footprint and power requirements for portable instruments.
- Small Modular Reactor Licensing:Advanced reactor deployments in the United States are expanding the installed base of containment area monitors and personnel portal detection systems.
Market Restraints
- Cadmium Zinc Telluride Supply Concentration:High-purity CZT crystal growth capacity clusters with a limited set of semiconductor foundries, creating input bottlenecks for premium spectroscopy instruments.
- Calibration Infrastructure Gaps:Certified reference source availability and accredited calibration laboratory density remain uneven across secondary and tertiary healthcare markets.
- Photomultiplier Tube Obsolescence Risk:Legacy vacuum-tube supply chains are contracting faster than solid-state replacement timelines in some high-radiation-tolerance applications.
Strategic Opportunities
- EPA RadNet Modernization:Federal environmental monitoring network upgrades are creating procurement windows for distributed sensor networks with cellular backhaul and cloud-native data architectures.
- ALARA Program Expansion:Healthcare systems are unbundling dosimetry services from equipment vendors, creating openings for independent service organizations with calibration and data analytics capabilities.
- Drone-Mounted Survey Integration:Unmanned aerial platforms are emerging as a channel for radiological survey instrumentation in decommissioning and emergency response applications.
Industry Challenges
- Radiation Safety Physicist Shortage:Qualified medical health physics professionals are scarce relative to expanding diagnostic imaging volumes, stretching hospital compliance staffing.
- Multi-Regulatory Certification Overlap:FDA 21 CFR Subchapter J, NRC 10 CFR Part 20, and EPA RadNet specifications impose divergent test protocols that extend product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Detection Device Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Geiger-Muller Counter, Scintillation Detector, Dosimeter, Ion Chamber Technology: Solid-State, Gas-Filled, Scintillation, Neutron Detection End User: Healthcare, Industrial Safety, Nuclear Power Plants, Environmental Monitoring Application: Radiation Therapy, Emergency Response, Research, Waste Management |
| Companies Covered | AMETEK, INC., Teledyne FLIR LLC, Thermo Fisher Scientific Inc., Landauer, Ludlum Measurements, Inc., Mirion Technologies, Inc., Fuji Electric Co., Ltd., ATOMTEX, Fortive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Detection Device Market Strategic Shifts
Digital signal processing and edge computing are migrating radiation detection intelligence from centralized laboratory instruments to field-deployable devices, compressing the latency between measurement and actionable insight across nuclear power, healthcare, and environmental monitoring applications.
Cadmium zinc telluride room-temperature semiconductor detectors are absorbing spectroscopy workloads previously reserved for cryogenically cooled germanium systems. Nuclear safeguards inspectors and environmental monitoring agencies are adopting CZT-based handheld identifiers for isotope-specific measurements in field conditions. This absorption is collapsing the performance gap between laboratory-grade and portable instrumentation, redrawing competitive boundaries across detector categories.
The EPA's RadNet modernization specifications are mandating IPv6 connectivity, encrypted data transmission, and API-first data architectures for environmental radiation monitors. Equipment vendors must reengineer legacy polling-based communication stacks to meet federal cybersecurity requirements. Deployment contracts in the United States are increasingly specifying zero-trust network segmentation for distributed sensor nodes.
Hospital procurement departments are consolidating dosimetry contracts under multi-year managed service agreements that bundle device supply, calibration logistics, and dose record management. This behavior shift is displacing transactional device sales with subscription-like commercial structures. The United States healthcare sector exhibits the most pronounced concentration of buying power into integrated service contracts.
Radiation Detection Device Market Segmentation
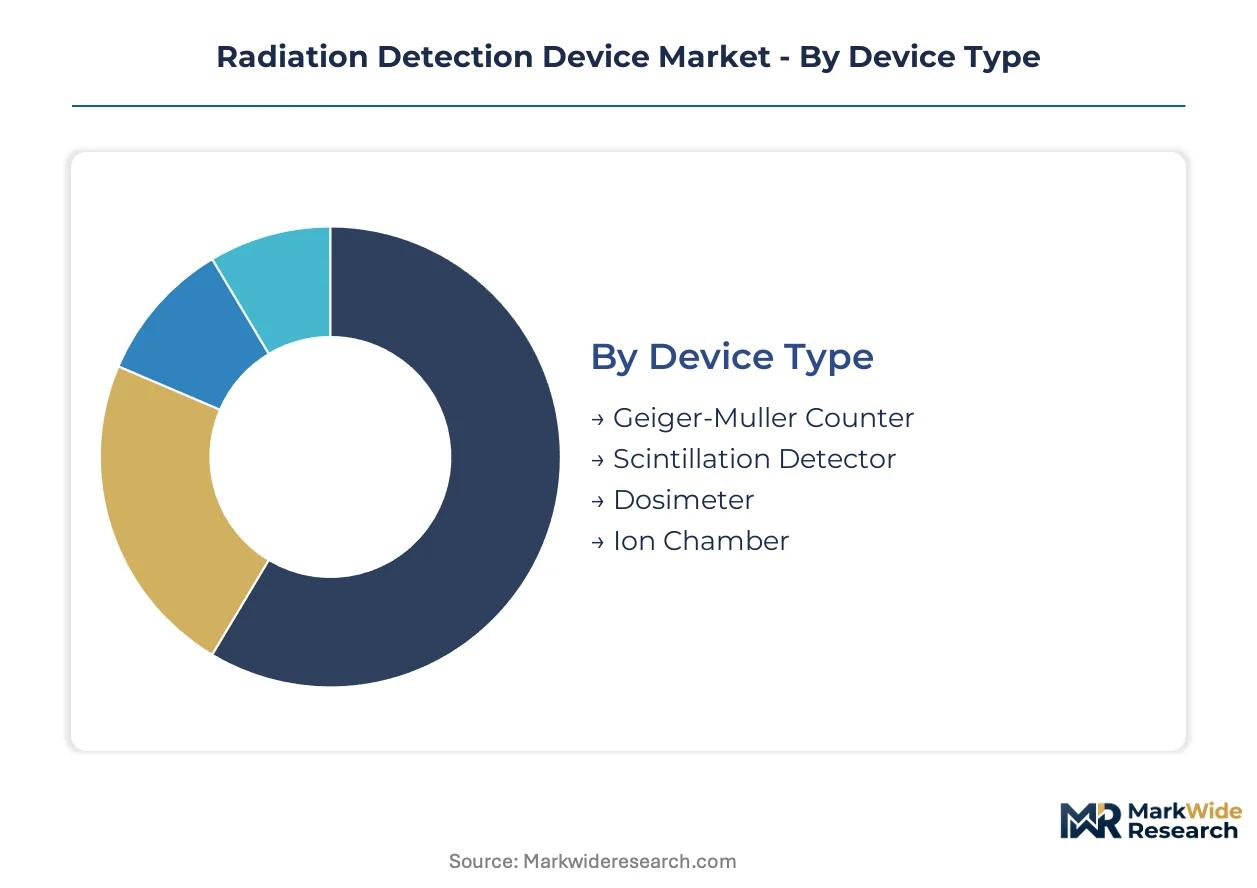
Radiation detection devices fragment across four distinct classification axes, each mapping to divergent performance specifications and procurement channels. Technology architecture determines sensitivity thresholds and operating environments. End-use verticals impose regulatory compliance frameworks that reshape product design priorities.
Device Type:
Detector physics and readout mechanisms define the functional envelope of each instrument category.
- Scintillation Detector:Crystals such as sodium iodide or lanthanum bromide convert gamma-ray energy into visible light pulses, enabling isotope-specific identification through spectroscopic analysis. Hospital networks in the United States deploy these for calibrated dosimetry tied to ALARA programs, paying premiums for energy resolution performance.
- Geiger-Muller Counter:Gas ionization tubes operating at high voltage produce discrete pulses across broad radiation ranges, sacrificing energy discrimination for simplicity and cost efficiency. Industrial safety officers favor these for contamination surveys where presence-absence detection suffices.
- Dosimeter:Personal monitoring badges and electronic dosimeters track cumulative exposure against regulatory limits. NRC 10 CFR Part 20 mandates drive fleet refresh cycles across hospital networks and national laboratories.
- Ion Chamber:Saturated gas volumes collect ion pairs proportional to dose rate, delivering absolute measurements for calibration transfer and high-dose-rate environments. Nuclear power plant health physics programs anchor demand for these reference-grade instruments.
Scintillation detectors lead on scale; solid-state readout chains are gaining share fastest through silicon photomultiplier displacement of vacuum tubes.
Technology:
Sensor material science and signal transduction methods determine portability, power budgets, and spectral fidelity.
- Scintillation:Mature crystal growth supply chains and established photodetector ecosystems sustain cost competitiveness across environmental monitoring and industrial safety channels.
- Solid-State:Cadmium zinc telluride and silicon-based detectors eliminate cryogenic cooling requirements, collapsing the performance gap between laboratory and field instrumentation. EPA RadNet modernization specifications favor these for distributed sensor networks.
- Gas-Filled:Proportional counters and Geiger-Muller tubes retain dominance in neutron detection hybrids and extreme-radiation-tolerance applications where semiconductor degradation risks exclude solid-state alternatives.
- Neutron Detection:Helium-3 proportional counters and boron-lined sensors address safeguards inspection and reactor containment monitoring, with supply constraints on helium-3 driving substitution research into boron carbide alternatives.
Scintillation platforms retain installed base dominance; solid-state architectures are climbing the fastest as CZT crystal quality improves.
End User:
Compliance obligations and consequence severity shape procurement sophistication and margin structures.
- Healthcare:Radiology departments and radiation oncology clinics operate under FDA 21 CFR Subchapter J and NRC 10 CFR Part 20 overlapping requirements, creating the deepest margin pool for calibrated, traceable dosimetry systems.
- Nuclear Power Plants:Containment area monitors, personnel portal detectors, and process radiation monitors sustain demand through NRC reactor oversight rules and anticipated license renewals.
- Environmental Monitoring:EPA RadNet specifications mandate IPv6 connectivity and encrypted transmission, reengineering procurement toward cloud-native data architectures.
- Industrial Safety:Manufacturing and materials processing facilities deploy contamination monitors and perimeter detection systems under OSHA workplace exposure guidelines.
Healthcare commands premium pricing; environmental monitoring is expanding most quickly through federal network modernization.
Application:
Use-case urgency and measurement precision requirements segment commercial opportunity.
- Radiation Therapy:Linear accelerator output verification and patient dose validation demand calibrated ion chambers and diode arrays with sub-percent accuracy.
- Emergency Response:First responder kits prioritize rapid deployment and ruggedized packaging over spectroscopic fidelity, with FEMA and state radiological health programs driving standardization.
- Research:National laboratories and university physics departments source high-purity germanium and advanced CZT systems for fundamental science and nuclear forensics.
- Waste Management:Decommissioning contractors and disposal site operators require assay systems for containerized waste characterization under NRC and Agreement State licensing.
Radiation therapy anchors revenue concentration; emergency response is gaining share fastest through drone-mounted survey integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiation detection instrumentation first achieved industrial scale through Manhattan Project laboratories in the United States, establishing calibration protocols and manufacturing standards that diffused to allied nuclear programs. This technical lineage concentrated production expertise in national laboratory corridors and university research clusters across North America, Europe, and East Asia.
United States
Hospital networks and national laboratories anchor procurement volumes through NRC-mandated dosimetry refresh cycles under 10 CFR Part 20. EPA RadNet modernization specifications are driving distributed sensor network deployments with encrypted cellular backhaul. The Tri-Valley corridor in California and Oak Ridge National Laboratory in Tennessee concentrate detector fabrication and calibration infrastructure.
Germany
Industrial safety officers in chemical processing and automotive manufacturing sustain demand for contamination monitors and perimeter detection systems. The country's national radiation protection regulator enforces occupational exposure limits that align with EU Basic Safety Standards directives. Bavaria's precision instrumentation cluster around Munich hosts specialized calibration laboratories serving Central European healthcare systems.
Japan
Post-Fukushima decommissioning operations and reactor restart authorizations are expanding the installed base of area monitors and personnel portal systems. METI oversight of nuclear facility safety mandates continuous environmental monitoring with traceable calibration chains. The Chubu region around Nagoya maintains concentrated expertise in scintillation crystal growth and photodetector assembly.
China
Expanding diagnostic imaging capacity and nuclear power construction are accelerating procurement of personal dosimetry and containment monitoring equipment. NMPA medical device registration requirements and MEE environmental radiation monitoring standards impose dual compliance frameworks. The Yangtze River Delta cluster around Shanghai hosts domestic detector manufacturers scaling solid-state sensor production.
United Kingdom
National laboratory decommissioning programs and healthcare ALARA initiatives sustain replacement demand for ion chambers and electronic dosimeters. The country's national radiation protection framework enforces occupational dose limits tied to EU-derived regulations. The Oxfordshire corridor retains concentrated expertise in nuclear safeguards instrumentation and spectroscopy system integration.
Radiation Detection Device Market Competitive Environment
Premium-margin players sit above commodity-margin players across calibration certification tiers, with traceable NIST- or PTB-accredited instruments commanding threefold pricing multiples over uncertified alternatives. The vendor base organizes into three strategic archetypes: integrated platform vendors bundling hardware and data services, specialized component suppliers selling interchangeable detector crystals and readout electronics, and managed service organizations unbundling dosimetry logistics from device supply. Dominant competitive moves include vertical integration into high-purity semiconductor crystal growth and strategic partnerships securing helium-3 alternatives for neutron detection channels.
Among North American instrumentation specialists, Thermo Fisher Scientific Inc. and Mirion Technologies, Inc. exemplify the integrated-platform archetype, while AMETEK, INC. occupies a position bridging component supply and system integration. These three entities represent contrasting approaches to the modular sensor decoupling trend reshaping procurement patterns across hospital networks and national laboratories.
| Leading Market Players |
|---|
| AMETEK, INC. |
| Teledyne FLIR LLC |
| Thermo Fisher Scientific Inc. |
| Landauer |
| Ludlum Measurements, Inc. |
| Mirion Technologies, Inc. |
| Fuji Electric Co., Ltd. |
| ATOMTEX |
| Fortive |
| Others |
Value Chain & Pricing Dynamics
Captive crystal growth operations at semiconductor foundries in the United States and Japan anchor both supply security and pricing power for premium spectroscopy instruments. These vertically integrated manufacturing choices insulate vendors from CZT input volatility while enabling NIST-traceable certification premiums that uncertified competitors cannot match.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with NIST-accredited calibration and EPA RadNet cybersecurity compliance separating premium tiers from uncertified alternatives. Price differentiation rests on traceability grade and after-sales service bundling, not hardware specifications alone. Cost compression in the economy tier is intensifying because hospital procurement departments are consolidating dosimetry contracts under multi-year managed service agreements. Healthcare systems exhibit the least price sensitivity due to ALARA program liability exposure, while industrial safety officers in secondary markets drive the hardest volume negotiations.
Supply Chain Analysis
Specialized radiation safety physicists and certified calibration technicians remain scarce relative to expanding diagnostic imaging volumes across the Tri-Valley corridor and Oak Ridge manufacturing clusters. High-purity cadmium zinc telluride crystal growth concentrates in the United States and Japan, while scintillation crystal finishing feeds from the Chubu region around Nagoya. Single-source vulnerability on helium-3 for neutron detection channels creates supply risk as legacy vacuum-tube photomultiplier supply chains contract. Distribution runs through direct hospital procurement committees, national laboratory contracting officers, and integrated service organizations unbundling logistics from device supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hospital networks and national laboratories are consolidating procurement around traceable, cybersecurity-hardened instrumentation that satisfies overlapping NRC, EPA, and FDA mandates.
For Market Incumbents: Anchor market position through captive CZT crystal growth investments that secure input supply while blocking uncertified competitors from premium spectroscopy segments. Deepen backward integration into silicon photomultiplier fabrication to capture solid-state displacement margins as vacuum-tube photomultiplier obsolescence accelerates. Defend against modular sensor decoupling by bundling calibration logistics and dose record management under multi-year service contracts that raise switching costs. For New Entrants and Emerging Players: Launch via independent service organization models that unbundle dosimetry logistics from hardware supply, targeting hospital networks in secondary and tertiary healthcare markets where calibration infrastructure gaps create white-space opportunity. Penetrate drone-mounted radiological survey instrumentation for decommissioning and emergency response applications, where unmanned aerial platform integration remains underdeveloped relative to handheld and fixed-installation categories. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration certification tiers fragment competitive returns, with NIST- or PTB-accredited instrument vendors commanding sustainable pricing multiples over commodity alternatives. Target acquisition profiles centered on specialized component manufacturers with CZT crystal growth capabilities or helium-3 alternative technologies for neutron detection channels. Monitor EPA RadNet modernization procurement windows and small modular reactor licensing progress as inflection indicators for area monitor and portal detection system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CZT Crystal Growth | Captive high-purity semiconductor supply secures spectroscopy margins against input bottlenecks. |
| Silicon Photomultiplier Platform Migration | Solid-state photon counting reduces detector footprint for portable EPA RadNet field deployments. |
| Multi-Year Managed Service Contracting | Subscription-like structures displace transactional sales and raise hospital network switching costs. |
| Drone-Mounted Survey System Development | Unmanned aerial platforms open decommissioning and emergency response channels beyond handheld instruments. |
| Helium-3 Alternative Technology Investment | Boron carbide neutron detection substitutes address safeguards inspection supply constraints. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with hospital radiation safety officers, NRC licensing specialists, EPA environmental monitoring program managers, and biomedical engineers at national laboratories with secondary validation against FDA 21 CFR Subchapter J filings, NRC reactor oversight reports, EPA RadNet technical specifications, and hospital procurement database trends. Bottom-up demand modeling across device type, technology, end user, and application segments triangulated against top-down market sizing from trade flow analysis.
Segment-weighting approaches distributed value and volume across scintillation, solid-state, gas-filled, and neutron detection technology categories, with healthcare, nuclear power, environmental monitoring, and industrial safety end-user verticals receiving distinct growth assumptions over the projection horizon. CAGRs derived from replacement cycle analysis under 10 CFR Part 20 compliance schedules, EPA RadNet modernization procurement timelines, and small modular reactor deployment trajectories, with silicon photomultiplier maturation and CZT crystal quality improvement curves informing technology transition rates.
Several conditions sit outside the modeled scope, including unanticipated NRC regulatory revisions, abrupt helium-3 supply disruptions, and geopolitical restrictions on semiconductor fabrication equipment exports. Forecasts reflect documented assumptions about compliance cycle regularity and federal environmental monitoring network upgrade continuity. Practitioners should monitor NRC reactor license renewal announcements, EPA cybersecurity specification updates, and CZT foundry capacity expansion announcements for early signals of demand inflection or supply constraint easing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Global Gas Detection System Market
Detection and Regulation Devices
Underwater Signaling Devices Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Arc Fault Detection Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Global Gas Leak Detectors Market
Detection and Regulation Devices
Infrared Detector Market
Detection and Regulation Devices
Digital Vacuum Regulators Market
Detection and Regulation Devices
Indeflator Devices Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Signaling Devices Market
Detection and Regulation Devices
Negative Temperature Coefficient (NTC) Thermistor Market
Detection and Regulation Devices
Global a-Si X-Ray Flat Panel Detectors Market
Detection and Regulation Devices
Explosive Detectors Market