
 IPC Soc Front-End Chip Market | 2026-2036
IPC Soc Front-End Chip Market Size, Share, and Industry Trends Forecast 2026-2036
IPC Soc Front-End Chip Market Insights
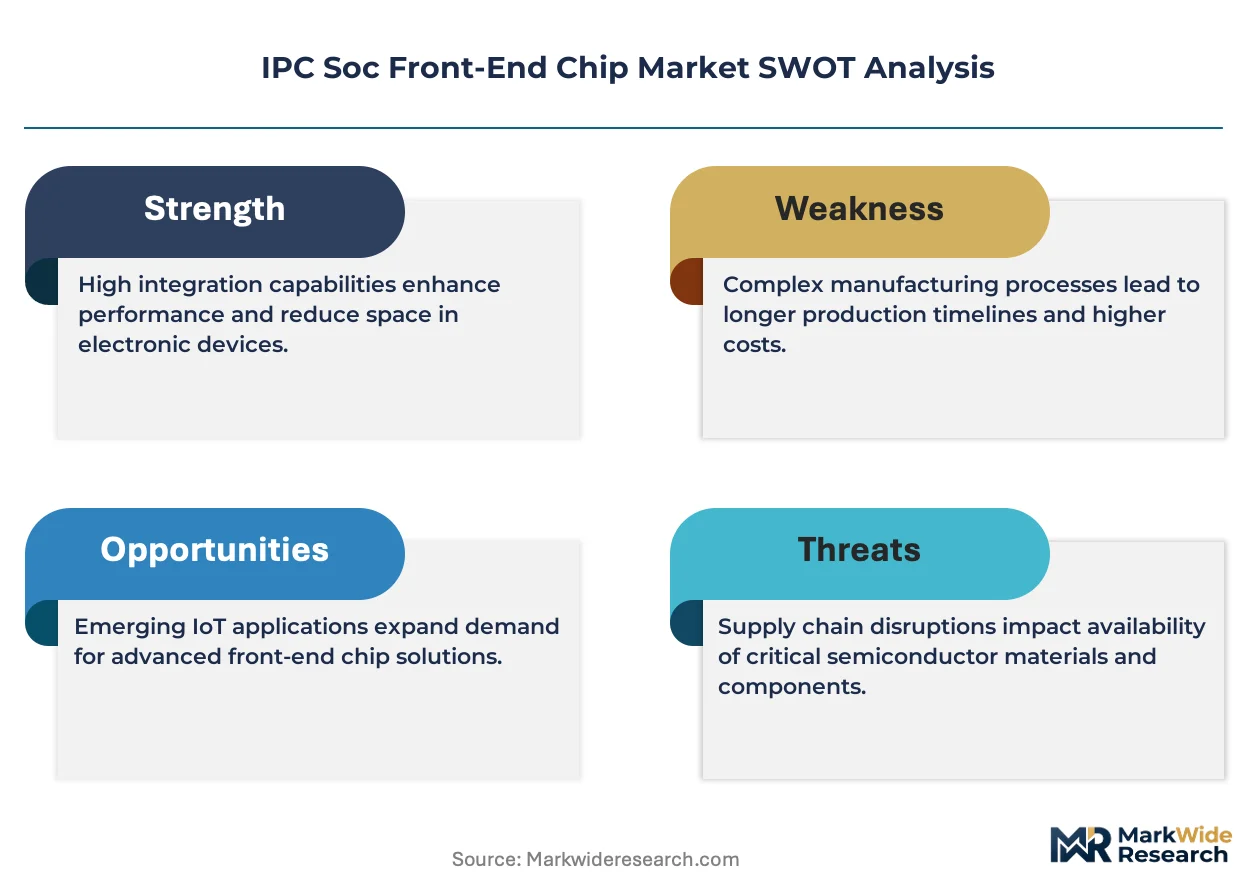
Taiwanese foundry capacity allocation is decoupling from legacy consumer SoC commitments as IPC-grade wafer starts claim dedicated slots at mature-node fabs. Hisilicon leverages in-house ISP architectures to anchor domestic supply chains for 4K/8K video encoding. Ambarella competes through sub-5W AI inference silicon purpose-built for battery-powered edge cameras. Texas Instruments sustains industrial temperature-grade portfolios that dominate outdoor and perimeter security deployments.
IPC SoC front-end chips integrate image signal processors, neural network accelerators, and multi-stream video codecs onto monolithic dies fabricated at 22nm to 40nm process nodes. These devices perform real-time de-warping, noise reduction, and object detection for networked surveillance endpoints. CMOS sensor interface compatibility and H.265 encoding efficiency define the core value proposition for OEMs. Digital chip variants command the largest revenue pool due to their prevalence in AI-enabled camera modules, while mixed-signal designs retain margin strength in analog-dense PTZ and thermal fusion systems. Automotive end-use applications represent the fastest-expanding demand corridor as ADAS surround-view and cabin monitoring functions adopt IPC-derived silicon architectures.
China's MIIT mandates GB standard compliance for network video products, while the EU AI Act imposes risk-classification obligations on biometric-capable edge devices. NHTSA guidelines in the United States shape automotive-grade reliability requirements for camera modules migrating from security to mobility applications. Stakeholders must monitor foundry allocation shifts between consumer and industrial nodes while calibrating R&D bets across on-device AI and cloud-native analytics pipelines.
Market Dynamics
Foundry allocation battles between consumer electronics and industrial silicon are compressing wafer availability for IPC-grade SoCs, forcing OEMs into multi-year supply commitments that reshape procurement risk profiles across the surveillance ecosystem.
Growth Catalysts
- MIIT chip self-sufficiency mandates:China's domestic procurement quotas redirect foundry capacity toward indigenous IPC SoC designs, accelerating local ISP and NPU architecture development.
- Smart city surveillance clusters:Municipal deployments in Shenzhen and Hangzhou concentrate demand for 4K/8K encoding silicon within integrated hardware-software ecosystems.
- Automotive cabin monitoring:ADAS surround-view functions migrate security-derived silicon architectures into vehicle platforms, opening a parallel demand corridor.
Market Restraints
- Mature-node wafer scarcity:22nm to 40nm process capacity faces allocation pressure from automotive and industrial MCU demand, extending lead times for IPC-grade lots.
- EU AI Act biometric restrictions:Risk-classification obligations on edge devices with facial recognition capabilities impose compliance burdens that slow European deployment timelines.
- Analog PTZ component dependency:Mixed-signal designs for thermal fusion systems retain captive supply relationships with specialized foundries, limiting second-source flexibility.
Strategic Opportunities
- Battery-powered edge AI:Sub-5W inference silicon for solar-enabled perimeter cameras addresses off-grid surveillance gaps in rural India and Southeast Asian plantation security.
- Industrial temperature-grade portfolios:Extended thermal range specifications for outdoor desert and arctic deployments capture premium pricing in oilfield and border monitoring.
- GB standard compliance services:Certification consulting bundled with SoC reference designs creates recurring revenue streams as MIIT mandates tighten network video product requirements.
Industry Challenges
- ISP-NPU co-verification complexity:Real-time de-warping and object detection pipelines require specialized firmware talent scarce outside Yangtze River Delta design clusters.
- Multi-codec legacy integration:H.265 migration stalls in installed-base upgrades where H.264 DVR backhaul infrastructure persists in municipal and retail security networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IPC Soc Front-End Chip Market |
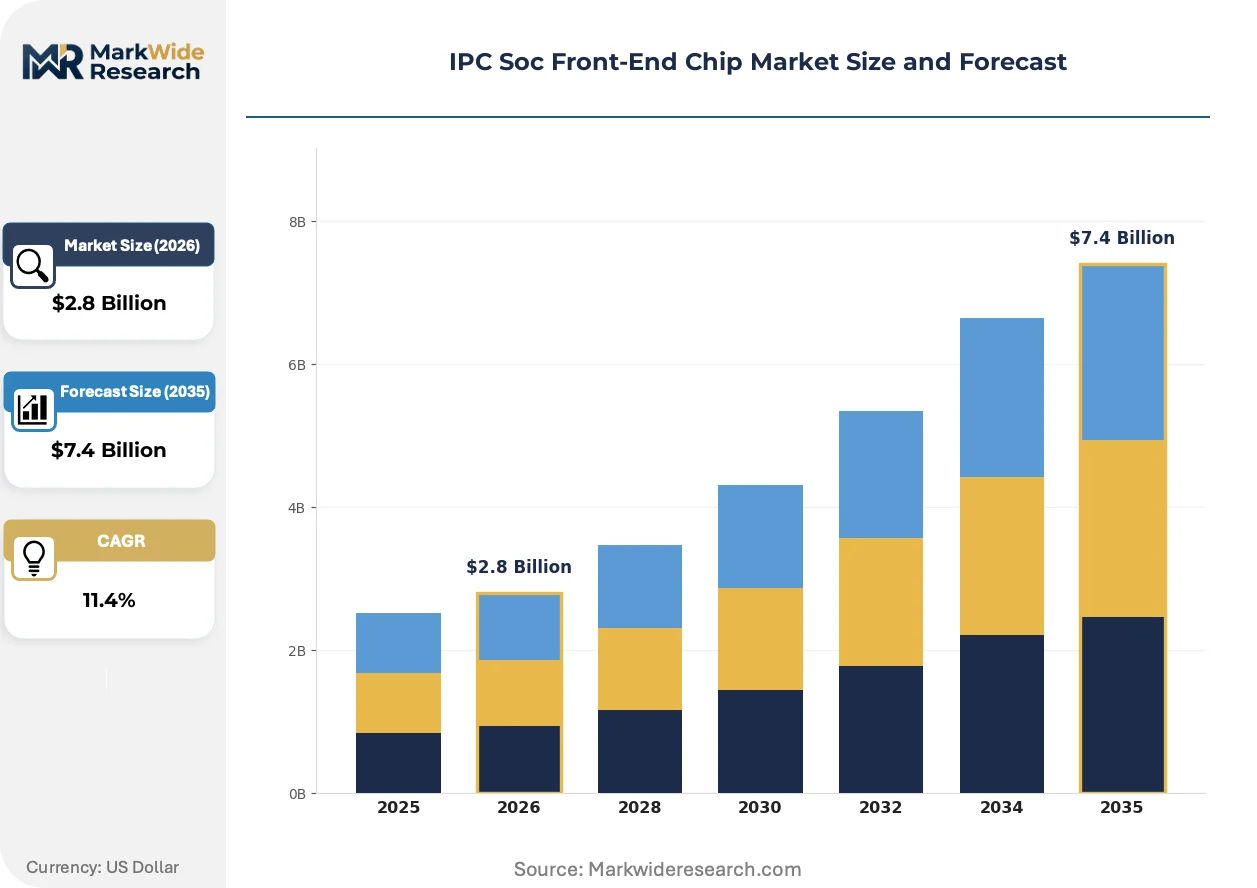
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Chips, Digital Chips, Mixed-Signal Chips, RF Chips End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment Technology: CMOS, GaN, SiGe, BiCMOS Application: Mobile Devices, IoT Devices, Networking Equipment, Medical Devices |
| Companies Covered | Hisilicon, Ambarella, Texas Instruments, Beijing Junzheng, Fullhan, Goke, Intel, Qualcomm, MediaTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IPC Soc Front-End Chip Market Trends and Innovations
Silicon architectures are fragmenting into specialized subsystems as AI inference workloads displace generic DSP blocks, while regulatory pressure on biometric edge processing forces hardware-software decoupling strategies.
Neural network accelerators are modularizing into discrete chiplets that interface with host SoCs through standardized die-to-die interconnects. Automotive tier-1 suppliers adopt this architecture for cabin monitoring systems to swap NPU generations without respinning entire camera modules. The approach compresses qualification cycles and enables field-upgradable inference capability.
EU AI Act risk-classification obligations are forcing biometric-capable edge devices into hardware-isolated processing domains. OEMs respond by partitioning face-detection pipelines onto physically separate secure enclaves with audit-logged outputs. Surveillance camera shipments into European smart city tenders now require documented conformity with these architectural mandates.
System integrators in the Yangtze River Delta are consolidating procurement around module houses that co-locate firmware customization with fabless design teams. This disintermediates traditional distributor channels and compresses specification-to-sample cycles for 4K encoding platforms. The model concentrates in Hangzhou and Suzhou where CMOS sensor, lens, and SoC vendors maintain joint development facilities.
IPC Soc Front-End Chip Market Segmentation
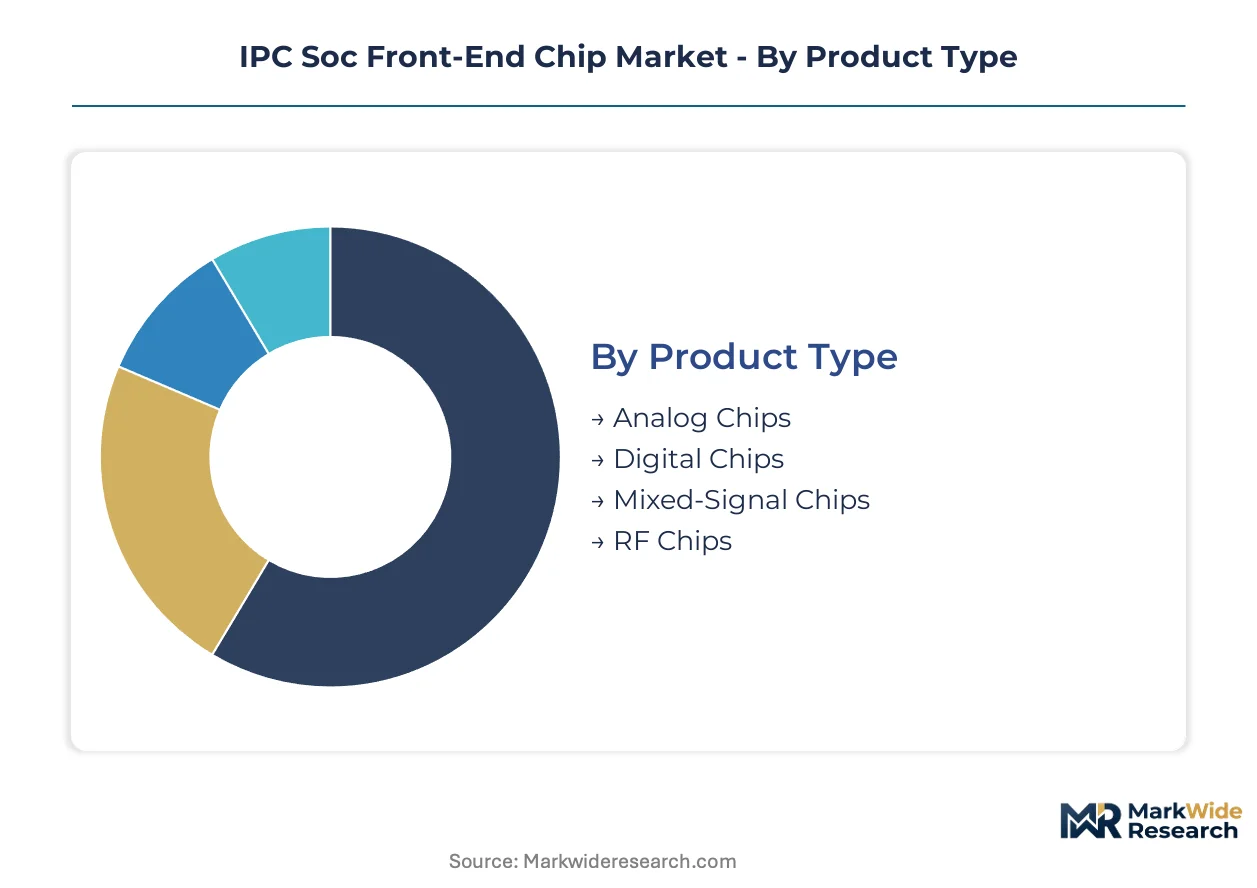
IPC SoC front-end chips fragment across four intersecting dimensions that determine foundry node selection, thermal qualification requirements, and customer procurement patterns. Each segmentation axis carries distinct margin profiles and supply chain constraints that shape vendor positioning strategies.
Product Type:
Customization intensity varies from fully standardized digital blocks to application-specific mixed-signal architectures requiring co-design with sensor partners.
- Digital Chips:Monolithic dies integrate ISP, NPU, and multi-stream H.265 codecs at 22nm to 40nm nodes. Demand concentrates in Shenzhen and Hangzhou smart city deployments where 4K/8K encoding drives procurement of AI-enabled camera modules. MIIT domestic procurement quotas accelerate local fabless design development for these high-volume variants.
- Mixed-Signal Chips:Analog-dense architectures combine precision sensor interfaces with digital processing for PTZ and thermal fusion systems. Automotive cabin monitoring applications in Germany and Japan adopt these for surround-view cameras requiring extended temperature ranges and low-noise signal paths. Specialized foundry relationships limit second-source flexibility.
- Analog Chips:Discrete signal conditioning and power management blocks serve legacy surveillance infrastructure upgrades.
- RF Chips:Wireless connectivity subsystems for battery-powered edge cameras in off-grid plantation security across rural India and Southeast Asia.
Leading the category by volume: Digital Chips. Expanding most quickly: Mixed-Signal Chips.
End User:
Application maturity spans from commoditized consumer volumes to emerging automotive qualification requirements.
- Automotive:ADAS surround-view and cabin monitoring functions migrate security-derived silicon architectures into vehicle platforms. NHTSA reliability guidelines shape camera module specifications as tier-1 suppliers adopt chiplet-based NPU architectures for field-upgradable inference.
- Industrial Equipment:Oilfield and border monitoring deployments in desert and arctic climates demand extended thermal range specifications. Texas Instruments dominates this segment with industrial temperature-grade portfolios that command premium pricing for outdoor perimeter security.
- Consumer Electronics:Home security cameras and video doorbells drive high-volume, cost-optimized SoC procurement.
- Telecommunications:Base station-integrated surveillance and edge computing nodes for smart city backhaul infrastructure.
Highest margin concentration: Industrial Equipment. Steepest volume trajectory: Automotive.
Technology:
Process selection trades off integration density against analog performance and power efficiency.
- CMOS:Dominant platform for 22nm to 40nm IPC SoC fabrication enabling high-density ISP and NPU integration. Yangtze River Delta foundries allocate mature-node capacity to domestic designs under MIIT self-sufficiency mandates.
- GaN:Emerging for high-efficiency power management in solar-enabled perimeter cameras requiring sub-5W operation.
- SiGe:Specialized RF front-ends for millimeter-wave security sensors in airport and critical infrastructure screening.
- BiCMOS:Precision analog interfaces for thermal imaging fusion systems in mixed-signal PTZ architectures.
Widest deployment base: CMOS. Fastest process adoption: GaN for energy-harvesting edge devices.
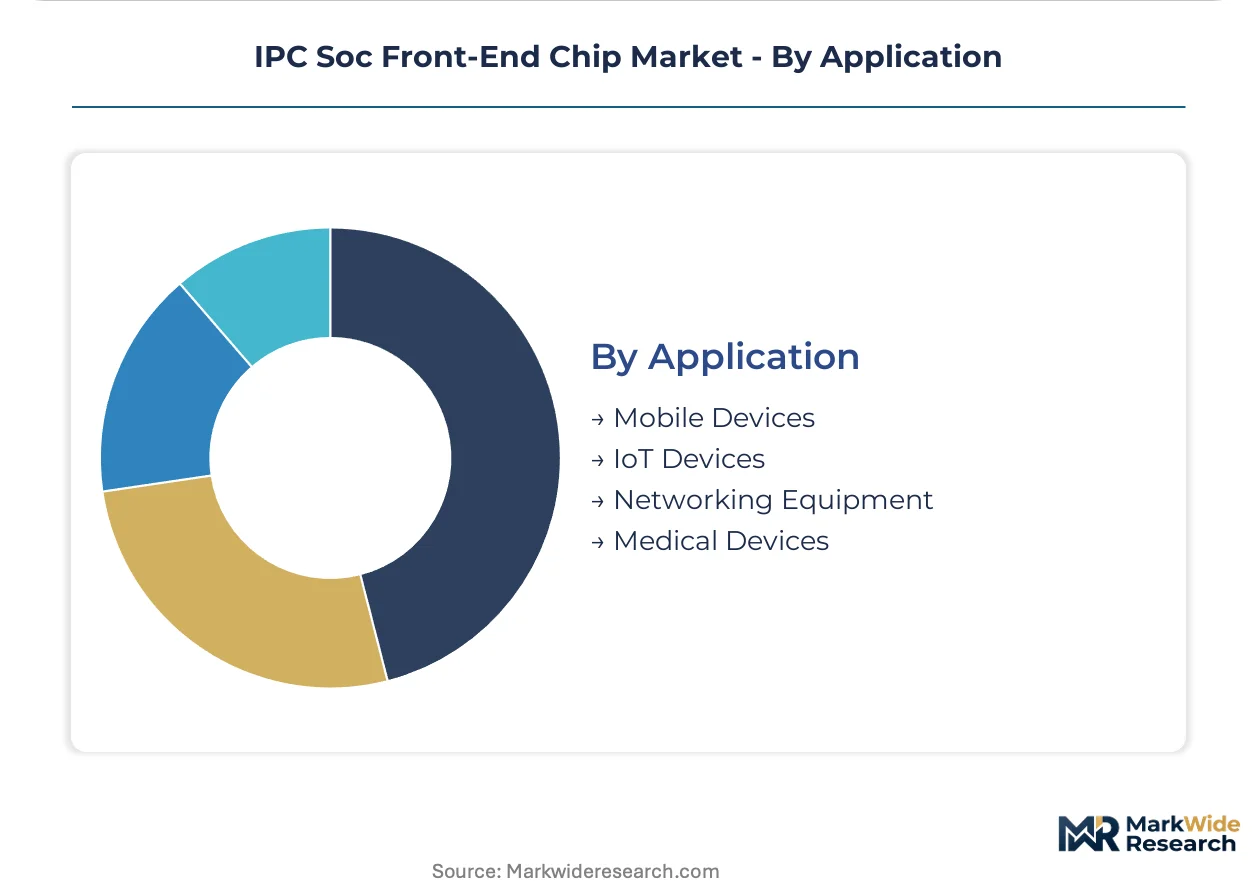
Application:
End-use fragmentation reflects divergent power, form factor, and regulatory constraints across device categories.
- Networking Equipment:Enterprise NVR and edge gateway systems aggregate multi-channel video streams with on-device analytics. EU AI Act risk-classification obligations force hardware-isolated processing domains with audit-logged outputs for biometric-capable deployments.
- IoT Devices:Battery-powered and solar-enabled cameras for off-grid surveillance in rural India and Southeast Asian plantation security. Ambarella competes through sub-5W AI inference silicon purpose-built for these energy-constrained endpoints.
- Mobile Devices:Smartphone-integrated security and video conferencing subsystems.
- Medical Devices:Remote patient monitoring cameras with privacy-preserving edge processing for HIPAA-compliant healthcare deployments.
Largest revenue pool: Networking Equipment. Fastest application expansion: IoT Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon feedstock from the Yangtze River Delta anchors procurement gravity for IPC SoC front-end chips. Foundry capacity allocation across mature nodes redirects toward industrial silicon as consumer electronics commitments recede.
China
Shenzhen and Hangzhou municipal surveillance deployments concentrate demand for 4K/8K encoding silicon. MIIT chip self-sufficiency mandates redirect foundry capacity toward domestic ISP and NPU architectures. The Yangtze River Delta cluster integrates CMOS sensor vendors, lens manufacturers, and fabless design teams within joint development facilities.
United States
NHTSA automotive-grade reliability requirements shape camera module specifications for ADAS surround-view systems. Oilfield and border monitoring in desert climates sustain procurement of industrial temperature-grade portfolios. Texas-based semiconductor operations anchor outdoor perimeter security deployments across North American infrastructure.
Germany
Automotive tier-1 suppliers adopt chiplet-based NPU architectures for cabin monitoring systems requiring field-upgradable inference. EU AI Act risk-classification obligations impose hardware-isolated processing domains with audit-logged outputs. Bavarian industrial automation clusters integrate surveillance-derived silicon into factory-floor monitoring networks.
Japan
Surround-view camera qualification for vehicle platforms drives migration of security-derived architectures into mobility applications. METI industrial standards shape extended thermal range specifications for precision manufacturing environments. Kansai-region electronics manufacturing concentrates mixed-signal design expertise for thermal fusion systems.
South Korea
Memory semiconductor ecosystems supply high-bandwidth interfaces for multi-stream video encoding pipelines. MFDS medical device regulations influence remote patient monitoring camera designs with privacy-preserving edge processing. Seoul Capital Area system integrators consolidate procurement around module houses with co-located firmware customization capabilities.
IPC Soc Front-End Chip Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue automotive qualification and energy-harvesting edge applications. The vendor base stratifies across three maturity levels: legacy surveillance silicon suppliers, automotive-qualified tier-1 partners, and fabless specialists targeting MIIT domestic procurement quotas. Two dominant competitive moves reshape positioning: backward integration into captive ISP architectures and strategic partnerships with Yangtze River Delta module houses for firmware co-development.
Among China-based fabless designers, Hisilicon and Beijing Junzheng exemplify the domestic procurement tier accelerated by MIIT self-sufficiency mandates. Ambarella occupies a position within the sub-5W inference segment purpose-built for battery-powered edge cameras. Texas Instruments anchors the industrial temperature-grade portfolio tier dominating outdoor and perimeter security deployments.
| Leading Market Players |
|---|
| Hisilicon |
| Ambarella |
| Texas Instruments |
| Beijing Junzheng |
| Fullhan |
| Goke |
| Intel |
| Qualcomm |
| MediaTek |
| Others |
Pricing and Supply Chain Analysis
Industrial-grade certification tiers separate extended-temperature automotive silicon from cost-optimized consumer modules, a divergence that manifests in both pricing premiums and foundry allocation strategies. MIIT domestic procurement quotas in China and EU AI Act compliance requirements in Europe create parallel certification ladders that reshape buyer-seller negotiations and wafer commitment structures.
Pricing Analysis
Warranty and field-service bundling separate premium automotive-grade contracts from stripped-down consumer module transactions. Three-tier pricing structure across industrial-temperature, commercial-grade, and economy IoT tiers reflects foundry node allocation and certification investment. Cost compression in the commercial-grade tier intensifies because Yangtze River Delta module houses consolidate procurement around co-located firmware partners. Consumer electronics OEMs exhibit the highest price sensitivity, while automotive tier-1 suppliers prioritize qualification stability over unit cost.
Supply Chain Analysis
Photoresist and specialty chemical supply for mature-node fabrication rests on Japanese producers Shin-Etsu and JSR, creating input concentration at 22nm to 40nm process nodes. Taiwan, South Korea, and China dominate foundry capacity for IPC-grade SoCs, drawing from silicon wafer feedstock anchored in the Yangtze River Delta cluster. Single-source vulnerability in analog PTZ component supply limits second-source flexibility for mixed-signal designs. Distribution runs through module houses in Shenzhen and Hangzhou that co-locate with fabless design teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IPC SoC market sits in a chiplet-architecture transition phase as discrete neural network accelerators replace monolithic NPU blocks for field-upgradable inference. Legacy monolithic designs face displacement from automotive cabin monitoring and smart city deployments requiring generation-swappable silicon.
For Market Incumbents: Anchor industrial temperature-grade portfolios through extended-thermal-range qualification investments that defend margin position against commodity consumer silicon. Foundry allocation battles between automotive MCU and IPC-grade demand threaten wafer availability; secure multi-year supply commitments at 28nm and 40nm nodes. Backward integration into captive ISP architectures creates differentiation against fabless competitors chasing MIIT domestic procurement quotas. For New Entrants and Emerging Players: Launch via solar-enabled perimeter camera module partnerships targeting rural India and Southeast Asian plantation security gaps. Battery-powered edge AI represents the most penetrable white-space segment, with sub-5W inference silicon demand outpacing established supplier capacity. A certification-consulting bundling strategy with GB standard compliance services creates recurring revenue streams as MIIT mandates tighten network video product requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in automotive-qualified tier-1 supplier acquisitions and MIIT-mandated domestic fabless rollup opportunities. Long-term viability favors chiplet-architecture specialists with modular NPU roadmaps over legacy monolithic designers facing respin cost inflation. Watch NHTSA reliability guideline updates as the critical inflection signal for camera module qualification requirements migrating from security to mobility applications.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet-Based NPU Modularization | Automotive tier-1 suppliers compress qualification cycles through field-upgradable inference architectures. |
| GB Standard Compliance Services | Certification consulting bundled with SoC reference designs captures recurring revenue under tightening MIIT mandates. |
| Yangtze River Delta Module House Partnerships | Co-located firmware customization compresses specification-to-sample cycles for 4K encoding platforms. |
| Industrial Temperature-Grade Portfolio Expansion | Extended thermal range specifications command premium pricing in oilfield and arctic border monitoring deployments. |
| Sub-5W AI Inference Silicon Development | Ambarella's battery-powered edge architecture addresses off-grid surveillance gaps in rural India and Southeast Asia. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fabless design executives, foundry procurement managers, automotive tier-1 supplier engineers, and smart city system integrators validated demand assumptions. SEC 10-K disclosures, MIIT GB standard documentation, and EU AI Act implementation guidance provided secondary triangulation. Bottom-up wafer allocation models and top-down municipal procurement budgets were reconciled across the analysis window.
Data-stream reconciliation across foundry capacity reports, CMOS sensor shipment manifests, and camera module export statistics informed the quantitative framework. Segmentation dimensions modeled include product type, end-use application, process technology node, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical procurement trajectories. Automotive ADAS adoption curves and smart city deployment pipelines served as industry-specific forecast inputs throughout the projection horizon.
Foundry allocation shifts between consumer and industrial nodes, EU AI Act enforcement variance across member states, and NHTSA reliability guideline updates are the dominant revision risks for IPC SoC demand trajectories. Forecasts reflect documented assumptions about mature-node capacity expansion and domestic procurement quota implementation timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
IoT Processor Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Automotive Gateway Chips Market
Chipset and Processors
Japan Microprocessor (MPU) Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Surgical Chips Market
Chipset and Processors
X86 Architecture CPU Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
Germany Data Center Processor Market
Chipset and Processors
Electric Vehicle Silicon Chip Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Auto Chip Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Latin America Neuromorphic Chip Market