
 Synchronous Condenser Market | 2026-2036
Synchronous Condenser Market Size, Share, and Industry Trends Forecast 2026-2036
Synchronous Condenser Market Insights
Buyer concentration among power transmission operators is recalibrating procurement patterns across the synchronous condenser landscape. Siemens Energy leverages its manufacturing scale to dominate large-utility contracts in Europe. GE Vernova anchors its position through in-house production of high-inertia rotor assemblies. ABB competes on grid-integration expertise, particularly in substation automation bundled with condenser deployments.
A synchronous condenser is a synchronous motor running without mechanical load, whose field excitation adjusts to absorb or generate reactive power for grid stabilization; units typically operate at 3,000 or 3,600 RPM with hydrogen cooling to manage rotor thermal limits in continuous duty. Salient pole designs occupy the majority of new installations due to lower capital cost and simpler maintenance profiles for grid-support applications. Round rotor configurations lead in high-speed, high-inertia segments where transient stability margins determine equipment selection. Reactive power compensation applications are expanding fastest as inverter-based generation displaces conventional synchronous machines.
FERC Order 2023 in the United States and EU Network Codes under ENTSO-E are tightening inertia and short-circuit level requirements that directly expand synchronous condenser procurement. The EPA's evolving rules on thermal plant retirements accelerate replacement demand for rotating grid-stabilizing assets. Grid operators and equipment suppliers must monitor regulatory divergence between jurisdictions where inertia mandates are prescriptive versus those relying on market-based ancillary services.
Market Dynamics
The phase-out of thermal generation across Europe is stripping grid inertia from power systems faster than inverter-based resources can replace it, forcing transmission operators to procure rotating stabilizing assets through emergency procurement channels.
Growth Catalysts
- FERC Order 2023:The United States Federal Energy Regulatory Commission's mandate for minimum inertia and short-circuit ratio requirements is compelling regional transmission organizations to contract synchronous condenser installations ahead of coal plant retirements.
- Germany's reactive power deficit:The accelerated nuclear and coal exit has collapsed synchronous generation capacity in the country's northern regions, where offshore wind concentration now exceeds grid-stabilizing capability.
- Salient pole design advances:Improved manufacturing tolerances for laminated pole shoes are reducing capital costs for grid-support applications below round rotor alternatives.
Market Restraints
- Copper and electrical steel volatility:Rotor winding materials and core laminations constitute 35-40% of unit manufacturing cost, exposing project economics to commodity swings that fixed-price EPC contracts cannot absorb.
- Specialized forging concentration:High-inertia rotor forgings rely on a concentrated supplier base in Central Europe and Japan, creating single-source vulnerability for projects above 200 MVAR rating.
- Grid-forming inverter substitution:Advanced power electronics with synthetic inertia algorithms are capturing procurement budgets in markets without prescriptive short-circuit ratio mandates.
Strategic Opportunities
- Australia's weak grid zones:Remote mining operations and renewable energy zones in Queensland and Western Australia lack sufficient fault current, creating demand for transportable condenser modules.
- EU Green Deal integration:The European Commission's REPowerEU facility is classifying synchronous condensers as critical grid infrastructure eligible for accelerated permitting and financing.
- Digital twin convergence:Real-time thermal modeling combined with predictive maintenance algorithms is enabling performance guarantees that reduce buyer risk perception.
Industry Challenges
- Field winding expertise erosion:The retirement of engineers trained on large synchronous machine design is compressing project execution timelines as utilities demand faster commissioning.
- Hydrogen cooling certification:Pressure vessel codes for direct-cooled rotors require site-specific safety approvals that add 8-14 months to project schedules in jurisdictions without harmonized standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synchronous Condenser Market |
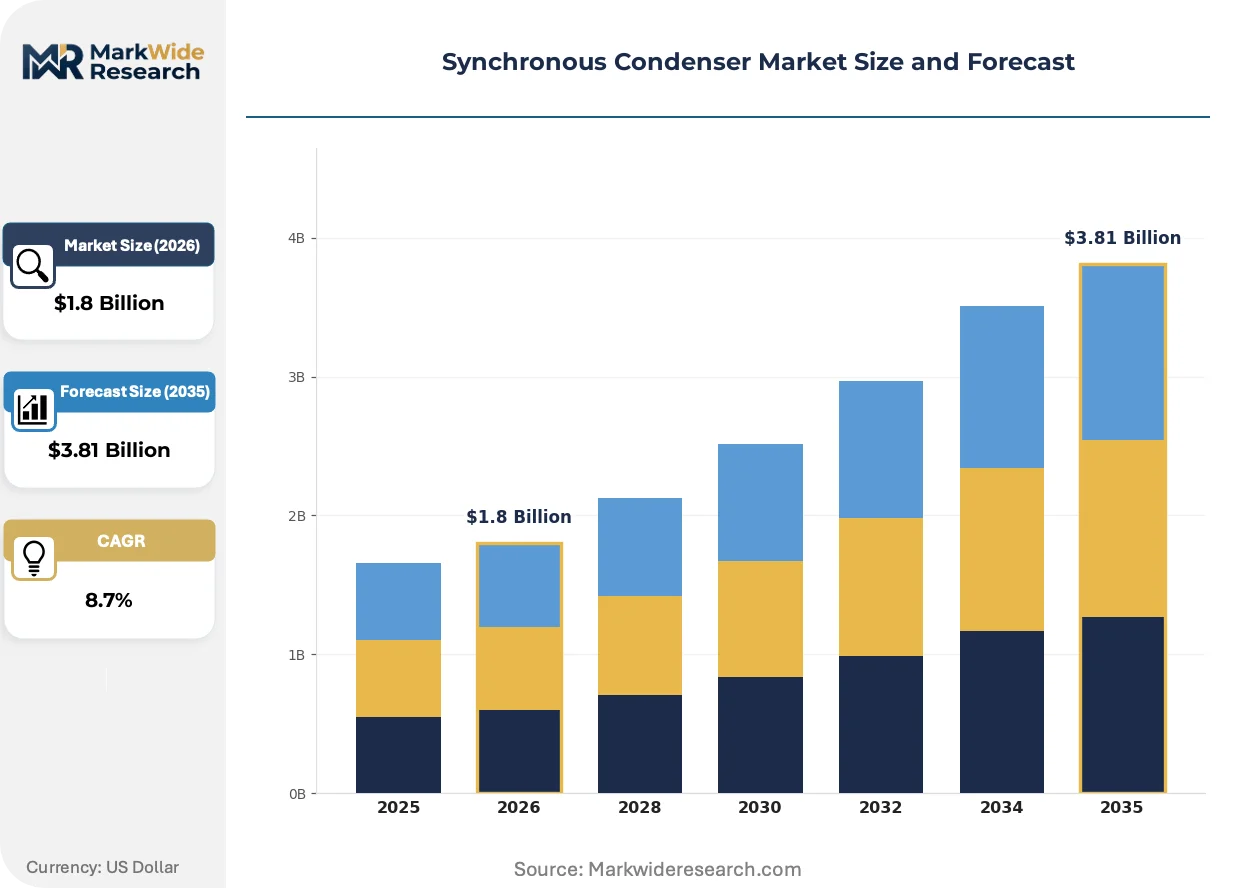
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salient Pole, Round Rotor, Brushless Exciter, Brush Exciter Application: Grid Stabilization, Reactive Power Compensation, Voltage Regulation, Power Factor Correction Installation Type: Land-Based, Floating Platform, Offshore Platform, Substation Integration End User: Utilities, Power Transmission Operators, Renewable Energy Farms, Industrial Facilities |
| Companies Covered | ABB, Siemens Energy, GE Vernova, Eaton, WEG, Andritz, Ansaldo Energia, Mitsubishi Electric, Hitachi Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synchronous Condenser Market Trends and Innovations
Grid modernization programs are redefining how rotating stabilizing assets integrate with digital control systems, shifting procurement criteria from hardware specifications to system-level performance guarantees.
Brushless excitation systems with permanent magnet pilot exciters are automating voltage regulation response times below 100 milliseconds. Transmission operators in Scandinavia are specifying these configurations for high-renewable penetration zones. The technology is automating field current adjustments that previously required manual intervention during grid disturbances.
ENTSO-E's Network Code on Requirements for Generators is mandating fault ride-through capabilities that exceed what static compensation can deliver. This regulatory pressure is redirecting reactive power procurement budgets toward rotating machines in member states with high wind penetration. German and Danish grid operators are now embedding these requirements into connection agreements for new renewable projects.
Power purchase agreements with merchant renewable developers are increasingly unbundling ancillary service obligations from energy revenue streams. Developers in Spain and Italy are contracting synchronous condenser capacity separately through transmission system operator auctions. This contractual separation is most visible in markets where renewable curtailment risk has shifted from grid codes to commercial negotiations.
Synchronous Condenser Market Segmentation
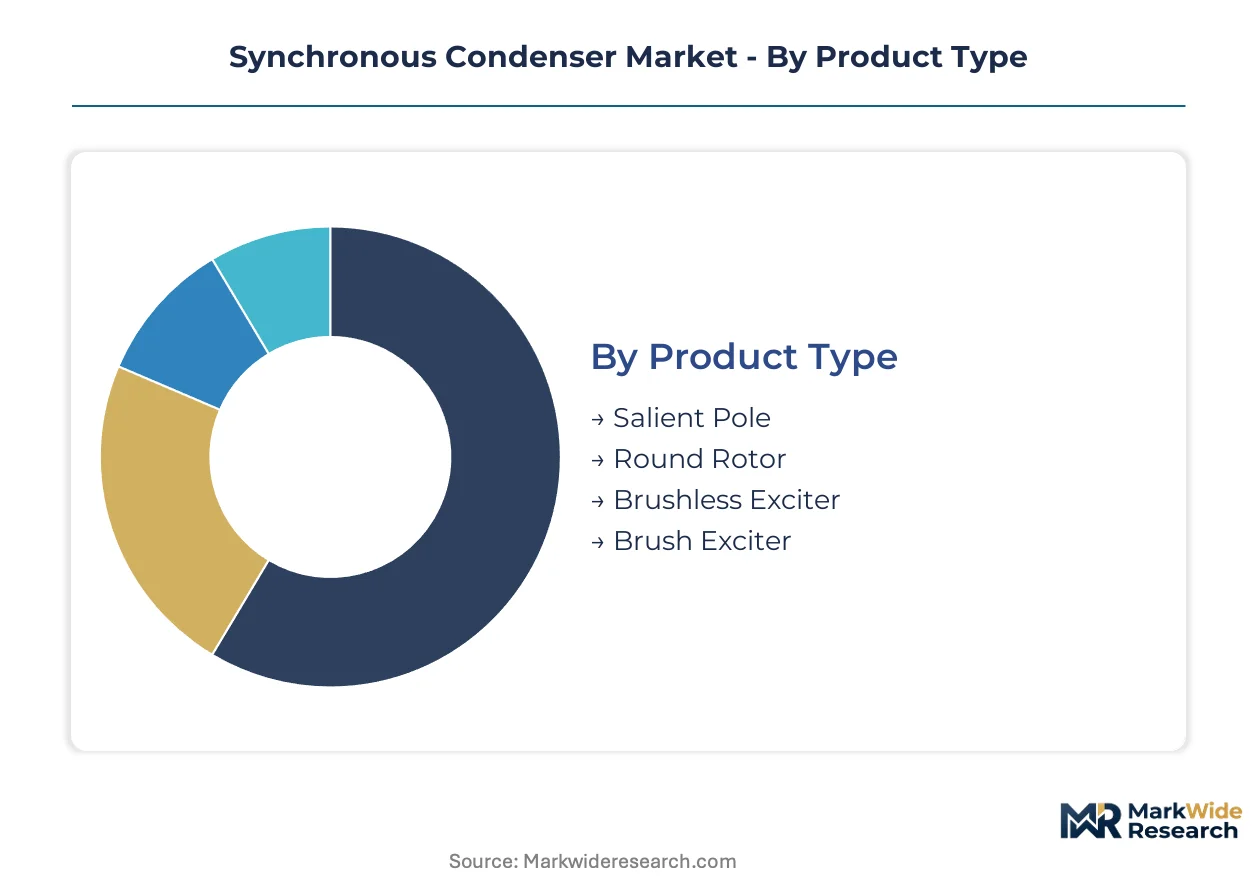
Synchronous condenser procurement varies sharply by rotor architecture, grid function, and deployment environment. Equipment specification determines cooling requirements, inertia characteristics, and integration complexity across transmission networks.
Product Type:
Rotor geometry and excitation topology define thermal performance, maintenance intervals, and capital cost structure.
- Salient Pole:Laminated steel pole shoes with projecting magnetic poles deliver lower manufacturing cost and simplified field winding access. German transmission operators specify these designs for onshore grid-support installations where capital efficiency outweighs transient response requirements.
- Round Rotor:Cylindrical forged steel construction with distributed windings enables higher rotational speeds and greater kinetic energy storage. High-inertia applications in the United States favor this configuration where fault current contribution and transient stability margins determine equipment selection.
- Brushless Exciter:Permanent magnet pilot exciters eliminate slip-ring maintenance and accelerate voltage regulation response below 100 milliseconds.
- Brush Exciter:Conventional slip-ring assemblies with carbon brushes remain specified for retrofit projects where existing infrastructure limits excitation system redesign.
Mature deployment sits with Brush Exciter configurations. Newer deployment is concentrated in Brushless Exciter systems.
Application:
Grid service requirements segment procurement by response speed, continuous duty cycle, and reactive power magnitude.
- Reactive Power Compensation:Continuous VAR absorption or generation to offset inverter-based generation displacement of conventional synchronous machines. Offshore wind concentration in Denmark and Germany is expanding this application fastest as grid codes mandate minimum short-circuit ratios.
- Grid Stabilization:Inertial response and fault current contribution during frequency excursions and voltage disturbances. Australian transmission operators in Queensland specify condensers for weak grid zones where remote mining loads and renewable energy zones strain stability margins.
- Voltage Regulation:Dynamic reactive power injection to maintain bus voltage within operational bands during load fluctuations.
- Power Factor Correction:Static or switched capacitive support for industrial loads with lagging power factors.
Mature deployment sits with Power Factor Correction. Newer deployment is concentrated in Reactive Power Compensation.
Installation Type:
Physical deployment constraints determine cooling system architecture, foundation requirements, and transport logistics.
- Substation Integration:Direct connection to high-voltage switchyard buses with integrated transformer and protection systems. This configuration dominates European procurement where existing transmission infrastructure accommodates rotating machine additions without greenfield civil works.
- Land-Based:Greenfield installations with dedicated foundations, hydrogen cooling infrastructure, and auxiliary systems. The United States employs this approach for FERC Order 2023 compliance projects sited near retiring coal plants.
- Floating Platform:Barge-mounted condensers with self-contained cooling and control systems for rapid relocation.
- Offshore Platform:Fixed steel jacket installations serving offshore wind collector platforms.
Mature deployment sits with Land-Based installations. Newer deployment is concentrated in Substation Integration.
End User:
Buyer sophistication, procurement scale, and technical specification authority vary across institutional categories.
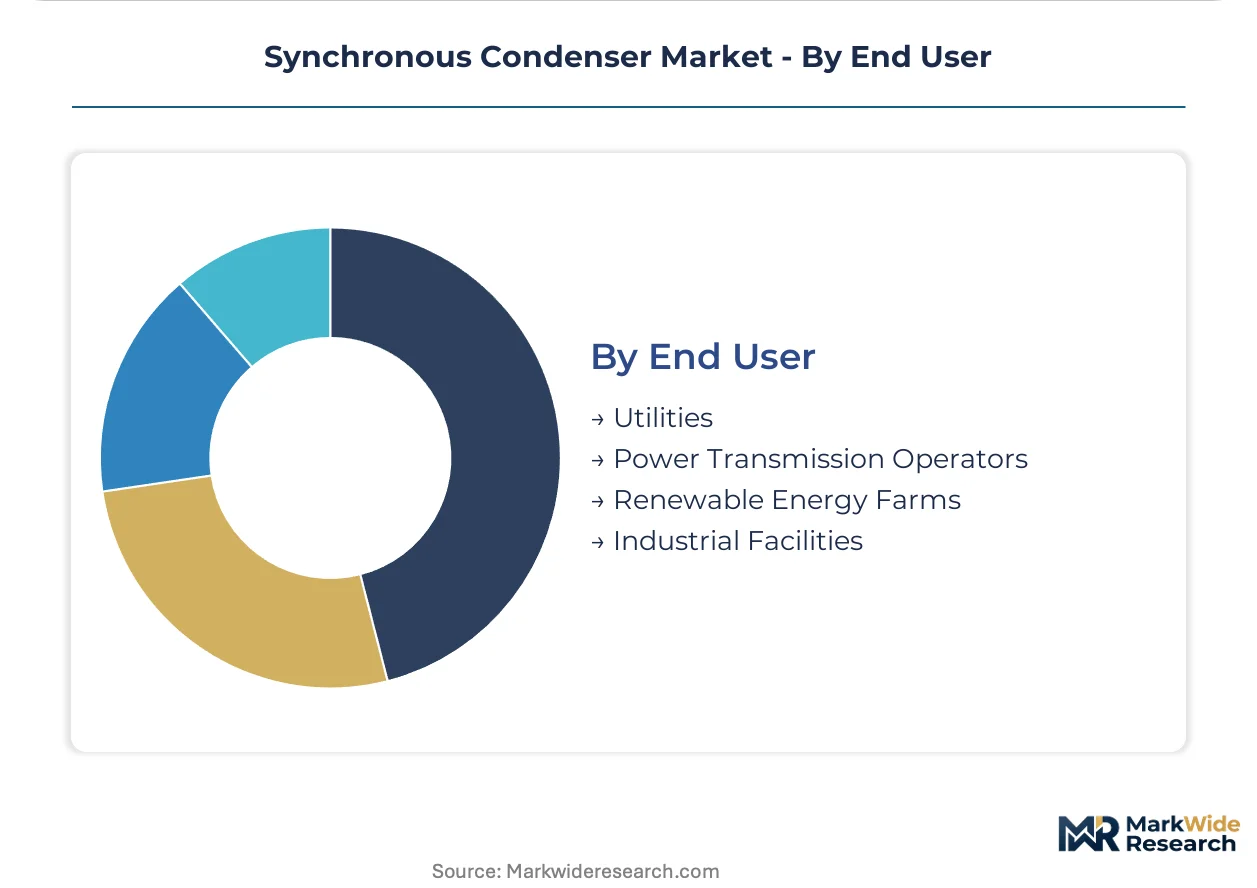
- Power Transmission Operators:Regional and national grid entities with mandatory reliability standards and rate-base financing. ENTSO-E members in Germany, Denmark, and Spain are expanding synchronous condenser fleets to satisfy network code requirements for minimum inertia and short-circuit levels.
- Renewable Energy Farms:Merchant wind and solar developers contracting ancillary services separately from energy revenue streams. Spanish and Italian developers now procure condenser capacity through transmission system operator auctions to satisfy unbundled grid support obligations.
- Utilities:Vertically integrated generators with legacy thermal plant expertise transitioning toward grid stabilization services.
- Industrial Facilities:Large manufacturing loads with internal power quality requirements and captive generation.
Mature deployment sits with Utilities. Newer deployment is concentrated in Power Transmission Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transmission system operators in Germany, the United States, and Australia are driving synchronous condenser procurement through regulatory mandates and grid stability deficits. Demand concentrates where thermal plant retirements outpace rotating machine replacement.
Germany
Offshore wind expansion in the North Sea has collapsed synchronous generation capacity below grid-stabilizing thresholds in Schleswig-Holstein and Lower Saxony. The EU Green Deal's REPowerEU facility classifies synchronous condensers as critical infrastructure eligible for accelerated permitting. Siemens Energy anchors manufacturing supply from its Mülheim facility to serve ENTSO-E network code compliance projects.
United States
FERC Order 2023 mandates minimum inertia and short-circuit ratio requirements across regional transmission organizations in Texas, California, and the PJM interconnection. The EPA's evolving thermal plant retirement rules accelerate replacement demand for rotating stabilizing assets near retiring coal facilities in Wyoming and West Virginia. GE Vernova leverages its Schenectady manufacturing base to anchor utility-scale contracts.
Australia
Remote mining operations and renewable energy zones in Queensland and Western Australia lack sufficient fault current for grid stability. The Australian Energy Market Operator's weak grid zone classifications direct transmission investment toward transportable condenser modules. ABB supplies grid-integration expertise for substation automation bundled with condenser deployments in the Pilbara region.
United Kingdom
North Sea offshore wind concentration around Dogger Bank strains reactive power reserves in northeastern England. National Grid ESO's stability pathfinder contracts procure synchronous condensers as ancillary services separate from energy markets. Hitachi Energy delivers grid stabilization equipment from its Stafford facility to meet fault ride-through requirements under GB grid codes.
Japan
Grid interconnection standards under METI's electricity system reform mandate short-circuit ratio maintenance as renewable penetration rises in Hokkaido and Kyushu. Mitsubishi Electric anchors domestic supply chains for high-inertia round rotor configurations serving utility procurement. Regional utilities in Tohoku specify hydrogen-cooled units for continuous reactive power duty.
Synchronous Condenser Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital twin integration and modular platform architectures. The vendor base clusters around three strategic archetypes: integrated energy conglomerates with captive rotating machine expertise, specialized electrical equipment manufacturers with grid automation capabilities, and industrial conglomerates diversifying from adjacent power sectors. Competitive positioning hinges on manufacturing scale for rotor forgings and excitation system integration depth. Dominant moves include backward integration into high-inertia forging supply and strategic partnerships for hydrogen cooling certification acceleration.
Among integrated energy conglomerates, Siemens Energy and GE Vernova exemplify scale-driven positioning through in-house production of critical rotating components. ABB occupies a differentiated position emphasizing grid-integration software and substation automation bundled with hardware deployments. These three anchors represent distinct competitive vectors: manufacturing scale, rotor assembly integration, and system-level digital control expertise.
| Leading Market Players |
|---|
| ABB |
| Siemens Energy |
| GE Vernova |
| Eaton |
| WEG |
| Andritz |
| Ansaldo Energia |
| Mitsubishi Electric |
| Hitachi Energy |
| Others |
Pricing and Supply Chain Analysis
FERC Order 2023's mandatory inertia specifications are compressing procurement timelines for regional transmission organizations, forcing manufacturers to absorb commodity volatility through fixed-price EPC contracts that squeeze margins on rotor forging and hydrogen cooling packages.
Pricing Analysis
Volume contracts from German transmission operators command 15-20% discounts against spot procurement, while margin protection concentrates in aftermarket service bundling and digital twin performance guarantees. Three-tier pricing structure across premium high-inertia round rotors, standard salient pole configurations, and economy brush-exciter retrofits reflects certification grade and cooling complexity. Cost compression in the economy tier is intensifying because copper and electrical steel exposure cannot be hedged across 24-month manufacturing cycles. Renewable energy farms exhibit highest price sensitivity due to unbundled ancillary service obligations, whereas power transmission operators prioritize technical compliance over unit cost.
Supply Chain Analysis
Refurbishment flows for retired thermal generator rotors are extending forging supply through remanufacturing channels in Germany, Japan, and the Czech Republic, reducing new-capital demand for projects below 150 MVAR rating. Manufacturing draws from concentrated electrical steel laminations sourced from Austria and Japan, copper windings from Chilean concentrate, and specialized hydrogen cooling vessels from Korean pressure-fabrication specialists. Single-source vulnerability for forgings above 200 MVAR rating creates procurement risk when lead times stretch beyond 18 months. Distribution runs through EPC consortiums bundling civil works, transformer integration, and grid-connection automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation is accelerating as commodity volatility and specialized engineering expertise requirements force smaller electrical equipment manufacturers toward exit or acquisition by integrated energy conglomerates.
For Market Incumbents:Acquire field-winding engineering talent pools before demographic retirement eliminates project execution capability. Siemens Energy and GE Vernova should deepen backward integration into hydrogen cooling vessel fabrication to reduce certification timeline exposure. Grid-forming inverter substitution in markets without prescriptive short-circuit mandates represents the primary displacement threat requiring defensive R&D investment in synthetic inertia integration.
For New Entrants and Emerging Players:Remote mining operators in Western Australia and Queensland present underserved demand for transportable condenser modules with rapid deployment specifications. Modular platform architectures with self-contained cooling and control systems offer the most penetrable entry vector against established manufacturers optimized for utility-scale fixed installations. Go-to-market positioning should emphasize rental and lease structures that transfer commissioning risk from capital-constrained buyers.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized forging houses possessing certified hydrogen cooling expertise given FERC and ENTSO-E regulatory momentum. Long-term viability across the next decade hinges on positioning within regulatory jurisdictions mandating rotating machine inertia rather than market-based ancillary services. Monitor EPA thermal plant retirement announcements and EU REPowerEU facility disbursement velocity as inflection indicators for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rotor Forging | Captive supply of high-inertia forgings insulates margin from Central European supplier concentration. |
| Hydrogen Cooling Certification Acceleration | Compressed approval timelines under harmonized pressure-vessel codes unlock project execution speed advantages. |
| Digital Twin Performance Guarantees | Predictive thermal modeling reduces buyer risk perception and enables outcome-based contracting structures. |
| Modular Transportable Platform Development | Barge-mounted and skid-based configurations access Australian weak-grid zones and emergency procurement channels. |
| Grid-Forming Inverter Partnership | Hybrid offerings combining synthetic and rotating inertia defend against power electronics substitution in permissive regulatory markets. |
Research Methodology
Multi-period observation of FERC Order 2023 implementation timelines, ENTSO-E network code adoption patterns, and German transmission operator procurement cycles anchored the trend analysis, supplemented by interviews with utility planning officers, EPC contractors, grid operators, and aftermarket service directors. Secondary validation drew from FERC filings, EIA generator retirement databases, IEA power system transformation reports, and EU REPowerEU facility disbursement records. Bottom-up unit deployment tracking across 12 national markets was triangulated against top-down transmission investment forecasts from regional system operators.
Segment-weighting applied rotor architecture splits, cooling system configurations, and installation type distributions across the projection horizon. CAGRs were derived from regression analysis of historical deployment velocity against regulatory mandate implementation schedules. Industry-specific forecast inputs included thermal plant retirement announcements under EPA rules, offshore wind connection timelines in the North Sea, and weak-grid zone classifications from the Australian Energy Market Operator.
Revisions become necessary when commodity price volatility exceeds hedging capacity, hydrogen cooling certification harmonization stalls, or grid-forming inverter performance crosses synthetic inertia thresholds that satisfy prescriptive short-circuit requirements. Practitioners should monitor FERC enforcement consistency, EU Green Deal financing velocity, and field-winding engineering graduation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Global Rectifier Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
Hybrid Inverters Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Global Inverter Market
Power Systems
Liquid Cooling Systems Market
Power Systems
Telecom Battery Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Micro-Inverter Market
Power Systems
Voltage Regulators Market
Power Systems
Batteries for Semiconductor Market
Power Systems
Buck-Boost Controller Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market