
 Ophthalmology EMR Software Market | 2026-2036
Ophthalmology EMR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmology EMR Software Market Intelligence
Subscription-based software-defined feature layers is hardening as the core revenue mechanism in ophthalmology EMR platforms. NextGen Healthcare leverages cloud-native architecture to anchor multi-specialty practices seeking unified workflows. athenahealth competes through network-enabled revenue cycle services that extend beyond documentation into billing optimization. ModMed specializes in specialty-specific templates that differentiate its platform for ophthalmology-specific clinical encounters.
Ophthalmology EMR software constitutes digital health record systems engineered for ocular care workflows, incorporating optical coherence tomography integration, visual field data parsing, and refractive surgery planning modules to support diagnostic precision and regulatory documentation. Cloud-based deployment leads product type segmentation due to lower capital barriers and automatic update cycles, while on-premise installations retain presence in hospital systems with stringent data sovereignty requirements. Web-based deployment dominates accessibility channels, though mobile application interfaces represent the fastest-growing segment as point-of-care documentation expands into examination lanes and surgical prep areas.
FDA 21 CFR Part 820 quality system regulations and ONC Health IT Certification criteria govern software validation and interoperability standards for U.S. ophthalmology EMR vendors, while HIPAA security rules shape data architecture requirements for patient information exchange. The EU MDR and GDPR impose additional compliance burdens for vendors serving European ophthalmology practices through cross-border data processing and clinical device integration. Stakeholders must monitor evolving interoperability mandates and specialty-specific template certification pathways as determinants of competitive viability.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for ophthalmology practices, while ONC interoperability mandates force vendors to restructure certification pathways around API-first data exchange standards.
Growth Catalysts
- ONC Cures Act Final Rule:Federal interoperability mandates accelerate vendor certification cycles and open data liquidity across ophthalmology networks, forcing platform upgrades that expand addressable market for compliant solutions.
- Optical coherence tomography integration:Diagnostic device connectivity requirements pull EMR vendors toward deeper imaging workflow embedding, creating stickier platform relationships with retinal specialists and glaucoma practices.
- United States hospital network consolidation:Multi-site ophthalmology groups demand unified electronic records across ambulatory surgery centers and satellite clinics, concentrating procurement authority at regional health system level.
Market Restraints
- HIPAA security architecture costs:Encryption-at-rest and audit trail requirements impose infrastructure overhead that disadvantages smaller vendor entrants and raises total cost of ownership for independent practices.
- Legacy data migration friction:Decades of unstructured ophthalmology records in proprietary formats create switching costs that cement incumbent positions and elongate replacement cycles.
- EU MDR clinical device classification:Software modules interfacing with diagnostic hardware face re-certification burdens that delay European market entry and fragment development roadmaps.
Strategic Opportunities
- Mobile point-of-care documentation:Examination lane tablet interfaces and surgical prep area access represent underdeveloped workflow layers where first-movers capture physician preference.
- Refractive surgery planning module expansion:LASIK and cataract lens selection algorithms create specialty-specific differentiation that general EMR platforms cannot replicate without deep domain investment.
- India outpatient eye care digitization:National health stack interoperability standards and growing private clinic chains create greenfield deployment opportunities outside saturated Western markets.
Industry Challenges
- Ophthalmology informatics specialist scarcity:Practices lack internal expertise to configure optical device integrations and template customizations, forcing vendor-dependent implementation models that strain support capacity.
- Multi-vendor diagnostic interoperability:Proprietary DICOM extensions and non-standard visual field data formats require costly adapter development for each device manufacturer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmology EMR Software Market |
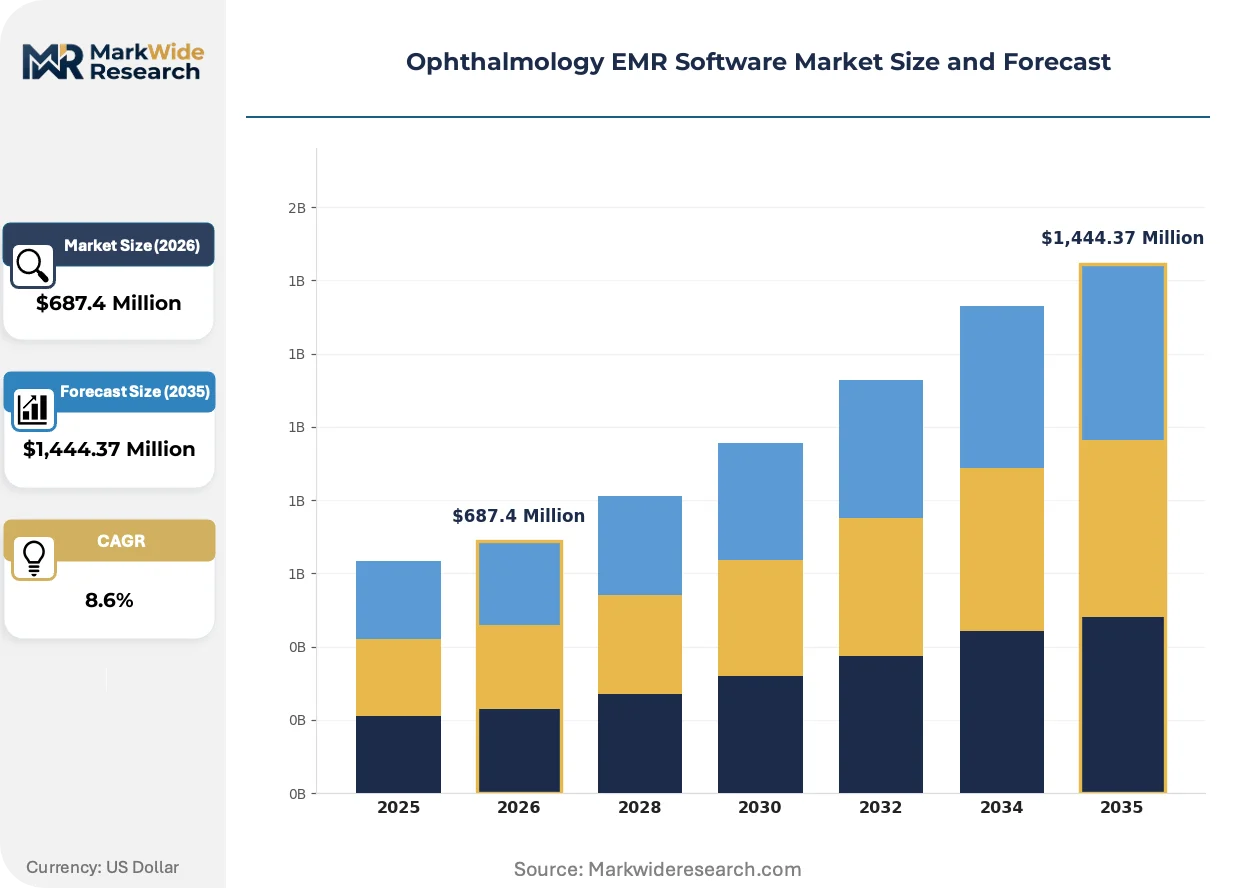
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,444.37 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Standalone Deployment: Web-Based, Mobile Application, Client-Server, Desktop Application End User: Private Practice, Hospital, Ambulatory Surgery Center, Research Institution Functionality: Patient Management, Billing, Clinical Documentation, Appointment Scheduling |
| Companies Covered | NextGen Healthcare, AdvancedMD, Nextech, Compulink Healthcare Solutions, ChartLogic, ModMed, athenahealth, EyeMD EMR, eClinicalWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmology EMR Software Market Strategic Shifts & Innovations
Artificial intelligence inference engines are embedding directly into ophthalmology EMR workflows, compressing diagnostic interpretation timelines and restructuring how practices allocate clinical labor across screening and referral decisions.
Machine learning-based diabetic retinopathy screening is absorbing image analysis workloads previously handled by human graders, enabling primary care networks and tele-ophthalmology platforms to expand screening volume without proportional specialist hiring. Rural health systems and federally qualified health centers adopt these modules fastest, using automated severity scoring to triage referral urgency. The technology is absorbing routine diagnostic tasks and compressing the value chain between image capture and treatment initiation.
EU AI Act risk classification rules impose conformity assessment obligations on diagnostic algorithms integrated with EMR platforms, forcing vendors to restructure quality management systems and maintain algorithm change logs. Medium-risk AI systems face notified body scrutiny that lengthens time-to-market for European deployments. Ophthalmology screening modules fall under this tier, prompting vendors to segregate EU and US product roadmaps or pursue harmonized development practices.
Subscription pricing for specialty-specific template libraries is displacing perpetual license models, aligning vendor revenue with ongoing configuration support rather than upfront implementation. Ophthalmology groups prefer this structure for optical coherence tomography reporting modules and surgical planning tools that require quarterly updates. United States multi-specialty practices lead this transition, negotiating enterprise agreements that bundle documentation templates with revenue cycle management services.
Ophthalmology EMR Software Market Segmentation
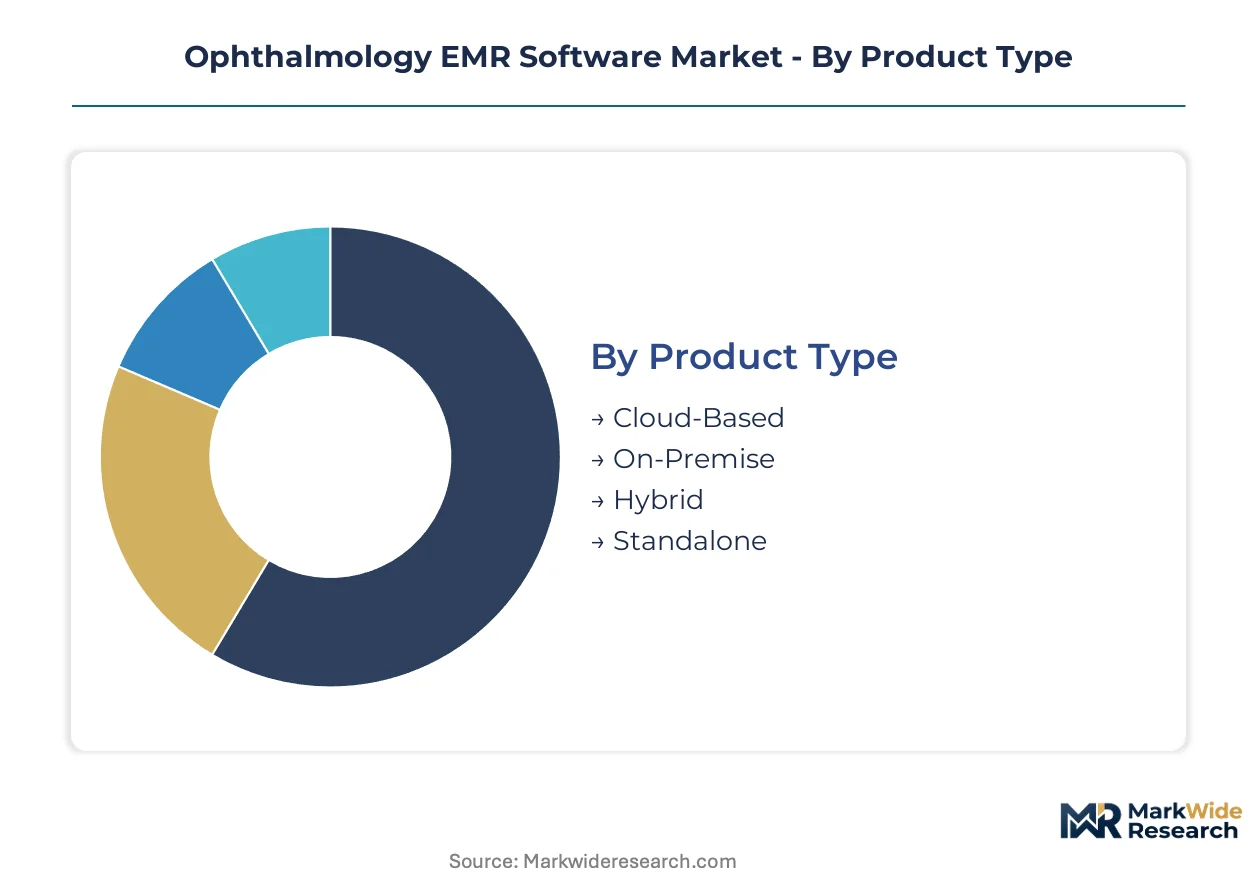
Ophthalmology EMR segmentation reveals how certification burdens concentrate in device-integrated modules versus lightweight scheduling tools. Deployment choices determine whether practices absorb HIPAA infrastructure costs or delegate security to cloud vendors.
Product Type:
FDA 21 CFR Part 820 quality system regulations and ONC Health IT Certification criteria impose tiered validation requirements across deployment architectures, with cloud-native platforms facing streamlined audits compared to on-premise installations requiring full infrastructure certification.
- Cloud-Based:Multi-tenant architectures with automatic security patching eliminate capital expenditure for independent practices. Hospital networks in the United States favor these platforms for rapid multi-site rollouts without data center construction. ONC Cures Act API mandates are accelerating vendor certification cycles for compliant cloud offerings.
- On-Premise:Local server installations with complete data sovereignty meet stringent institutional review board requirements at academic medical centers. HIPAA encryption-at-rest and audit trail specifications demand dedicated IT infrastructure that elevates total cost of ownership. Research institutions with proprietary imaging datasets retain preference for air-gapped deployments.
- Hybrid:Split architectures segregate PHI-sensitive records on local servers while pushing analytics workloads to cloud environments. This configuration appeals to multi-location practices seeking disaster recovery without full infrastructure duplication.
- Standalone:Single-workstation installations without network dependencies serve solo practitioners in rural markets with unreliable connectivity. Limited interoperability restricts device integration but minimizes compliance surface area.
Cloud-Based sits at the top of the volume ranking, with Hybrid climbing the fastest as practices balance sovereignty against scalability.
Deployment:
Cost tier differentiation separates enterprise web portals from lightweight mobile interfaces, with subscription pricing stratifying across implementation complexity and support entitlements.
- Web-Based:Browser-accessible platforms with responsive design dominate ambulatory surgery center workflows where workstation mobility matters. United States hospital networks negotiate enterprise licenses bundling web access with revenue cycle services.
- Mobile Application:Native iOS and Android interfaces enable point-of-care documentation in examination lanes and surgical prep areas. Retinal specialists capture optical coherence tomography annotations at the device, compressing interpretation timelines.
- Client-Server:Thick-client architectures with local processing persist in legacy installations where bandwidth constraints prevent cloud migration. These deployments require dedicated IT maintenance contracts that strain smaller practice budgets.
- Desktop Application:Single-machine installations with offline capability serve satellite clinics in connectivity-limited geographies. Update cycles depend on manual patch application, creating security lag versus automatic cloud updates.
Web-Based captures the broadest installed base, while Mobile Application gains share fastest as tablet documentation displaces workstation-bound workflows.
End User:
Application intensity varies sharply across customer type, with hospital procurement committees demanding interoperability certifications that private practices rarely specify.
- Private Practice:Solo and small-group ophthalmologists prioritize template customization for refractive surgery workflows and optical device integration. Subscription pricing with quarterly template updates aligns vendor revenue with ongoing configuration support.
- Hospital:Integrated delivery networks mandate enterprise-wide electronic records spanning ambulatory surgery centers and satellite clinics. Multi-site consolidation concentrates procurement authority at regional health system level, favoring vendors with proven interoperability.
- Ambulatory Surgery Center:High-volume cataract and LASIK facilities require surgical planning modules with lens selection algorithms and outcome tracking. These specialized workflows demand deeper domain investment than general EMR platforms provide.
- Research Institution:Academic medical centers with institutional review board oversight need audit trails and data export capabilities for clinical trial submissions. Air-gapped deployments with custom DICOM adapters serve proprietary imaging studies.
Hospital deployments command the largest contract values, with Ambulatory Surgery Center procurement expanding most quickly as outpatient surgical volume shifts from inpatient settings.
Functionality:
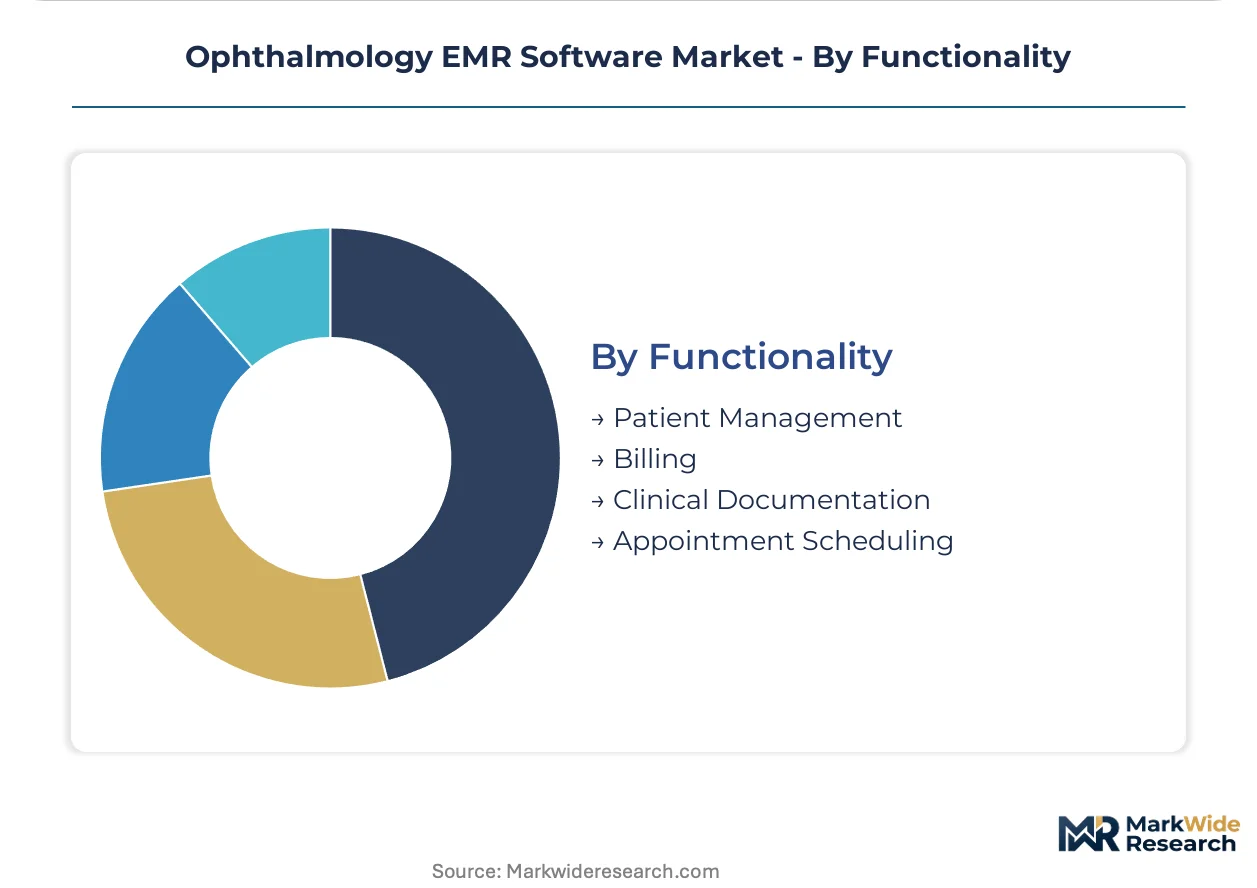
Margin concentration follows workflow criticality, with clinical documentation modules commanding premium pricing against commoditized scheduling tools.
- Patient Management:Demographic tracking, referral coordination, and care team communication form the foundational data layer. These capabilities are table stakes across all vendor tiers.
- Billing:Revenue cycle management with ophthalmology-specific coding for surgical procedures and diagnostic tests reduces claim denial rates. athenahealth and similar vendors compete through network-enabled billing optimization extending beyond documentation.
- Clinical Documentation:Specialty-specific templates for slit-lamp findings, visual field interpretation, and surgical planning represent the highest-value differentiation. Optical coherence tomography integration and refractive surgery modules create stickier platform relationships.
- Appointment Scheduling:Calendar optimization with automated recall systems for chronic disease monitoring improves practice efficiency. These tools face commoditization as standalone scheduling platforms encroach.
Clinical Documentation generates the highest per-module revenue, with Billing functionality showing steepest expansion trajectory as practices outsource revenue cycle complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates ophthalmology EMR procurement authority through consolidated hospital networks, while Germany anchors European demand through its dense network of specialized eye clinics and stringent data sovereignty requirements.
United States
Multi-site ophthalmology groups and ambulatory surgery centers drive cloud-native platform procurement, with regional health systems centralizing electronic records across satellite clinics. The ONC Cures Act Final Rule mandates API-first interoperability standards that reshape vendor certification cycles. The Boston-Cambridge corridor hosts concentrated tele-ophthalmology innovation clusters where AI-enabled screening modules integrate with EMR workflows.
Germany
Specialized Augenkliniken and university eye hospitals prioritize on-premise deployments with complete data sovereignty under GDPR and BSI IT-Grundschutz frameworks. The EU MDR imposes clinical device classification burdens on software modules interfacing with diagnostic hardware. The Rhine-Main metropolitan region around Frankfurt maintains dense concentrations of refractive surgery centers digitizing surgical planning workflows.
India
Private ophthalmology chains and vision centers in tier-2 cities drive greenfield EMR adoption as outpatient eye care digitization accelerates. The Ayushman Bharat Digital Mission establishes national health stack interoperability standards that reshape vendor deployment strategies. The Chennai-Bengaluru corridor hosts expanding networks of cataract specialty hospitals implementing cloud-based practice management systems.
Japan
Aging demographics and glaucoma screening program expansion pull EMR vendors toward diagnostic device integration for retinal specialists. PMDA software as medical device guidelines and JIS quality management standards govern validation requirements for AI-embedded platforms. The Osaka-Kobe medical device cluster concentrates ophthalmology informatics development for Asia-Pacific market entry.
United Kingdom
NHS England's digital transformation programs and federated data platforms reshape procurement for hospital eye services and community optometry networks. NHSX interoperability standards and UK GDPR compliance requirements filter vendor participation in public tenders. The London-Oxford-Cambridge golden triangle anchors academic medical center deployments with institutional review board oversight for clinical trial data management.
Ophthalmology EMR Software Market Key Industry Players
Top-tier vendors anchor multi-specialty health system contracts, while mid-tier specialists capture independent ophthalmology practices through template customization. The vendor base stratifies across three strategic archetypes: cloud-native platforms with revenue cycle services, specialty-specific documentation specialists, and legacy client-server installations serving research institutions. Competitive moves concentrate on API-first interoperability certification and mobile point-of-care documentation expansion.
Within the specialty-specific tier, NextGen Healthcare, ModMed, and athenahealth occupy positions that exemplify divergent architectural bets. NextGen Healthcare represents the multi-specialty consolidation play, anchoring unified workflows across ambulatory networks. ModMed sits within the domain-deep specialization vector, embedding ophthalmology-specific encounter templates and optical device integrations. athenahealth exemplifies the network-enabled services archetype, extending platform stickiness through billing optimization that transcends documentation functionality.
| Leading Market Players |
|---|
| NextGen Healthcare |
| AdvancedMD |
| Nextech |
| Compulink Healthcare Solutions |
| ChartLogic |
| ModMed |
| athenahealth |
| EyeMD EMR |
| eClinicalWorks |
| Others |
Cost & Logistics Intelligence
HIPAA encryption-at-rest infrastructure costs cascade through ophthalmology EMR vendor pricing tiers, with cloud-native platforms absorbing compliance overhead into subscription rates while on-premise installations pass capital expenditure directly to hospital procurement committees. This cost structure stratifies buyer access, concentrating premium functionality within health system budgets and pushing independent practices toward lighter-weight SaaS tiers.
Pricing Analysis
Capacity additions in India are reshaping price floors for cloud-based ophthalmology EMR platforms as domestic vendors compete with established United States players. Subscription pricing stratifies across premium, standard, and economy tiers, with differentiation driven by ONC certification level and optical device integration depth. Pricing pressure stems from open-source interoperability frameworks commoditizing basic scheduling modules. Ambulatory surgery centers exhibit highest price sensitivity due to procedure-volume volatility, while academic medical centers prioritize certification compliance over cost.
Supply Chain Analysis
ONC Health IT Certification and FDA 21 CFR Part 820 quality system requirements gate vendor participation in United States procurement channels, elevating compliance costs that filter through to end-user pricing. Software development concentrates in the United States, India, and Germany, with cloud infrastructure drawing from hyperscaler networks anchored in Virginia, Mumbai, and Frankfurt. Supply chain risk centers on single-source dependency for optical coherence tomography DICOM adapter development. Distribution runs through direct enterprise sales teams for hospital networks and channel partners for independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ophthalmology EMR procurement has shifted toward premium specifications as ONC Cures Act interoperability mandates disqualify non-compliant platforms from hospital network tenders, compressing viable vendor sets to certified specialists.
For Market Incumbents: Lock in multi-site health system contracts through API-first architecture investments that accelerate ONC certification cycles. Acquire mobile point-of-care documentation specialists before emerging entrants capture examination lane workflows. Defensive consolidation around optical device integration depth counters general EMR platform encroachment into specialty workflows. For New Entrants and Emerging Players: Begin with ambulatory surgery center surgical planning modules where domain-specific algorithms create differentiation incumbents cannot replicate without roadmap disruption. India's tier-2 city private ophthalmology chains offer the most penetrable geography, with Ayushman Bharat Digital Mission interoperability standards lowering certification barriers. A device-integrated go-to-market angle bypasses commoditized scheduling competition. For Investors and Strategic Acquirers: Consolidation pressure builds where ophthalmology informatics specialist scarcity forces vendor-dependent implementation models that strain support capacity. Five-to-ten year viability favors platforms with proven multi-site hospital network deployments and recurring template subscription revenue. Acquisition targets should demonstrate optical coherence tomography integration depth and mobile documentation readiness. The signal to watch is ONC certification backlog length as indicator of vendor competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| ONC Certification Acceleration | Faster API-first interoperability validation expands hospital network addressable market before competitors complete compliance cycles. |
| Mobile Point-of-Care Expansion | Native iOS and Android interfaces capture physician preference in examination lanes where workstation documentation creates workflow friction. |
| Optical Device Integration Deepening | Proprietary DICOM adapters for retinal imaging systems create switching costs that cement incumbent positions against general EMR encroachment. |
| India Market Entry Partnership | Collaboration with domestic health stack integrators navigates Ayushman Bharat interoperability requirements for greenfield deployment acceleration. |
| AI Screening Module Development | Machine learning diabetic retinopathy algorithms absorb diagnostic workloads that expand primary care screening volume without specialist hiring. |
Research Approach
Multiple input streams — structured interviews with ophthalmology practice administrators, hospital IT procurement officers, and EMR platform product managers — were reconciled against secondary validation from FDA 510(k) filings, ONC certification databases, and hospital GPO contract disclosures. Bottom-up triangulation across deployment model, end-user type, and functionality segmentation anchored volume estimates, while top-down cross-checks against health system IT expenditure patterns ensured consistency.
Historical revenue trajectories were cross-referenced against panel input from cloud infrastructure providers and optical device manufacturers to calibrate growth assumptions across the projection horizon. Segmentation modeling incorporated deployment architecture, organization size tier, vertical specialization depth, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted trend analysis adjusted for interoperability mandate implementation timelines and AI module adoption curves.
Caveats apply where ONC rulemaking revisions or EU AI Act risk reclassifications could materially shift the outlook for diagnostic algorithm deployment. Forecasts reflect assumptions around hospital network consolidation pace and outpatient surgical volume migration. A model refresh is warranted upon material change in ONC certification backlog processing speed or hyperscaler data sovereignty policy shifts affecting cross-border EMR hosting.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Donor Management Software Market
Medical Information Systems
US Medical Coding Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
ICD-10 Market
Medical Information Systems
Hospital Information Systems Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Master Patient Index Software Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
Case Coder Market
Medical Information Systems
Global Clinical Documentation Improvement Market