
 Global Healthcare Information Systems Market | 2026-2036
Global Healthcare Information Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Information Systems Market Foresight
HIPAA interoperability mandates are repositioning the competitive landscape for new entrants. Epic Systems Corporation leverages its dominant installed base across academic medical centers to sustain pricing power. Cerner Corporation anchors its position through deep integration with revenue cycle workflows.
Healthcare information systems comprise software architectures that capture, store, manage, and transmit patient health data across clinical and administrative functions, typically operating through HL7 FHIR protocols and requiring sub-100-millisecond response times for real-time clinical alerts. Their primary purpose is to reduce medical errors, streamline care coordination, and optimize operational throughput across provider organizations. Electronic Health Records occupy the largest share of product-type spending, while Cloud-Based deployments are expanding fastest as hospitals shed capital-intensive on-premise infrastructure. Patient Care Management applications command the deepest margin pools due to longitudinal data monetization opportunities.
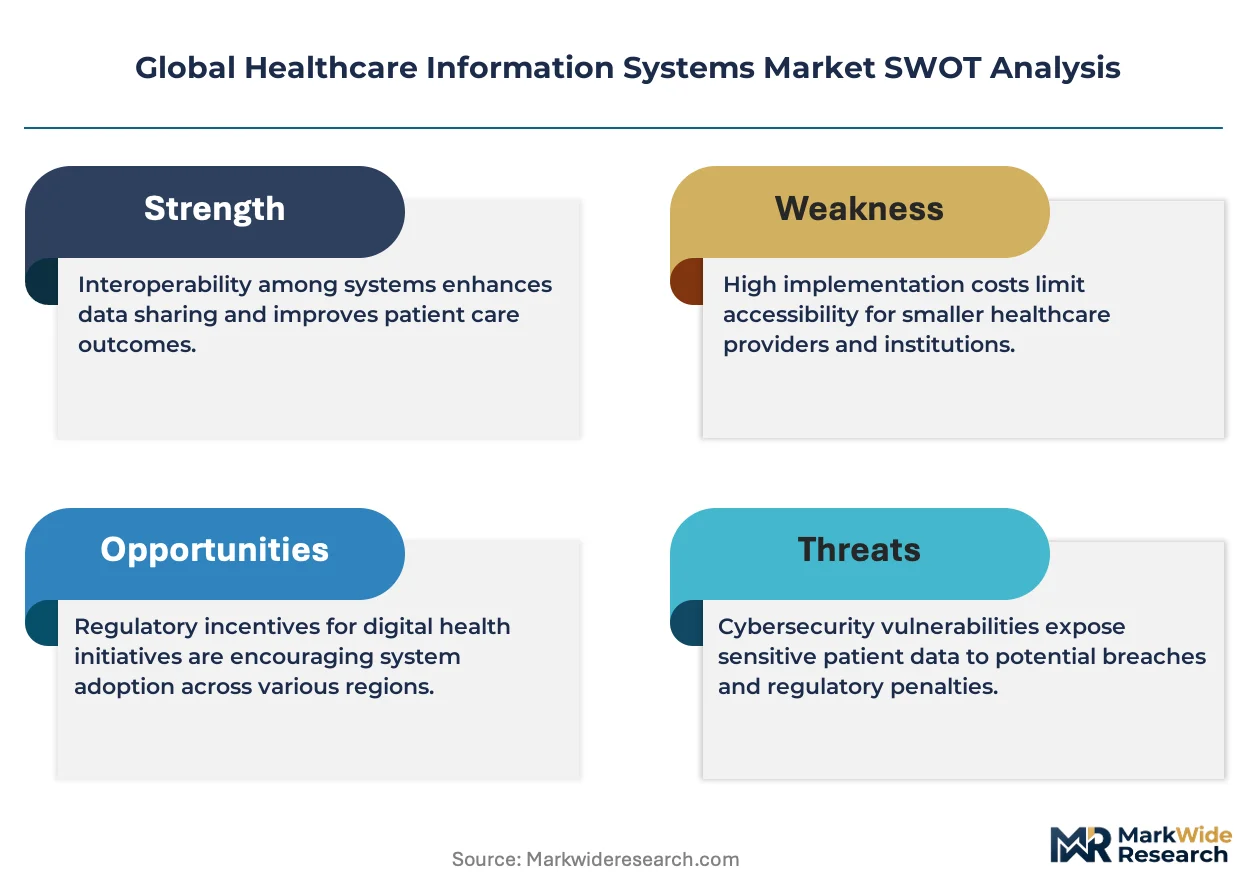
FDA software-as-medical-device oversight, EU MDR cybersecurity annexes, and India's Digital Information Security in Healthcare Act are collectively elevating compliance costs for cross-border vendors. These frameworks shape demand by disqualifying uncertified platforms from reimbursement eligibility and public procurement channels. Stakeholders must monitor how evolving liability standards for AI-embedded diagnostic modules reshape vendor risk profiles and customer switching costs.
Market Dynamics
FDA software-as-medical-device oversight and Germany's Digital Healthcare Act digitization mandates are compressing vendor certification timelines while forcing hospital procurement toward integrated platforms. This regulatory tightening is reshaping competitive entry barriers across developed markets.
Growth Catalysts
- HL7 FHIR protocol standardization:The interoperability framework is accelerating data exchange capabilities between previously siloed hospital departments and external care networks.
- Cloud migration imperatives:Hospital IT departments are shedding capital-intensive on-premise server farms in favor of subscription-based infrastructure models.
- India's Digital Information Security in Healthcare Act:The data localization mandate is creating certified vendor demand across South Asian hospital networks.
Market Restraints
- EU MDR cybersecurity annex compliance:Cross-border vendors face elevated validation costs for clinical decision support modules entering European procurement channels.
- Specialized health informatics talent scarcity:Shortages of professionals fluent in both clinical workflows and FHIR implementation are extending deployment timelines.
- Legacy system technical debt:Proprietary data formats in decades-old hospital databases resist standardized extraction without expensive middleware layers.
Strategic Opportunities
- Remote patient monitoring convergence:Wearable device data streams and EHR platforms are creating longitudinal care monetization opportunities outside acute settings.
- Saudi Arabia's healthcare privatization:Greenfield hospital construction is bypassing legacy infrastructure constraints entirely.
- AI-embedded diagnostic modules:Machine learning classification tools are opening new reimbursement categories for predictive analytics in oncology workflows.
Industry Challenges
- Sub-100-millisecond alert latency requirements:Real-time clinical decision support demands edge computing investments that strain rural hospital budgets.
- Multi-jurisdiction liability fragmentation:AI diagnostic module errors trigger conflicting malpractice standards across state and national borders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Information Systems Market |
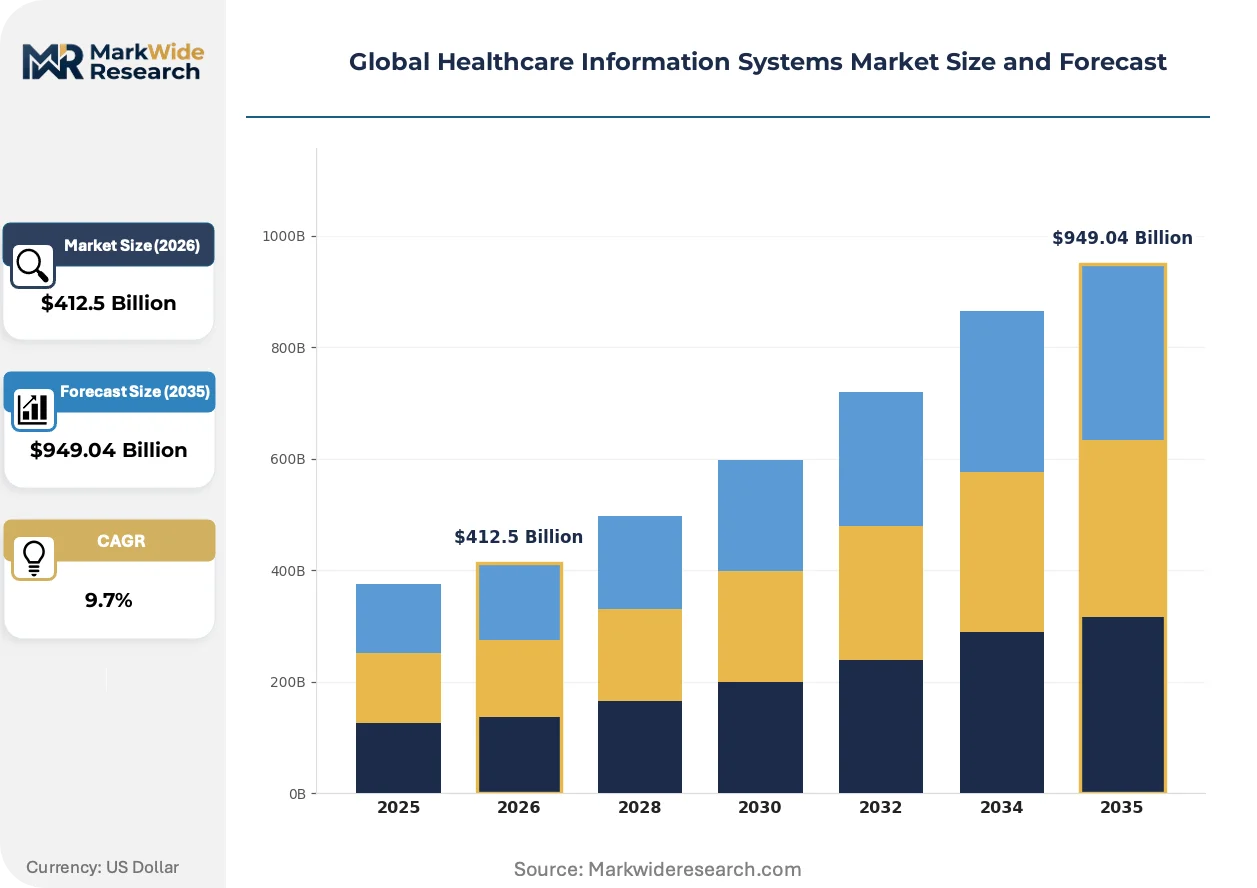
| Market Size in 2026 | $412.5 Billion |
| Market Size in 2035 | $949.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Radiology Information Systems, Laboratory Information Systems, Pharmacy Information Systems, Patient Management Systems Application: Patient Care Management, Clinical Decision Support, Medical Imaging, Drug Administration, Revenue Cycle Management End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Pharmacies, Rehabilitation Centers Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based, Mobile Platform |
| Companies Covered | Epic Systems Corporation, Oracle Health, Cerner Corporation, GE Healthcare, Philips Healthcare, McKesson Corporation, athenahealth, NextGen Healthcare, Allscripts Healthcare Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Information Systems Market Shifts & Advancements
Healthcare information architecture is fragmenting from monolithic suites into composable microservices. This decomposition is enabling faster feature deployment while complicating vendor accountability for system-wide failures.
Microservices-based EHR architecture is modularizing patient data management into discrete, interoperable components. Academic medical centers in the United States are piloting containerized deployments that isolate billing, clinical documentation, and pharmacy modules. This modularization is compressing upgrade cycles from multi-year implementations to quarterly feature releases.
The EU AI Act risk classification framework is imposing conformity assessment obligations on clinical decision support tools. High-risk diagnostic algorithms now require notified body certification before European market entry. German hospital procurement offices are prioritizing CE-marked AI modules to preempt liability exposure under the new liability directives.
Subscription-based platform economics are displacing perpetual license arrangements in North American health system contracting. Hospital finance committees favor operational expenditure models that align vendor payments with utilization metrics. This shift is most visible among mid-sized community hospital networks seeking to preserve capital reserves for clinical staffing.
Global Healthcare Information Systems Market Segmentation
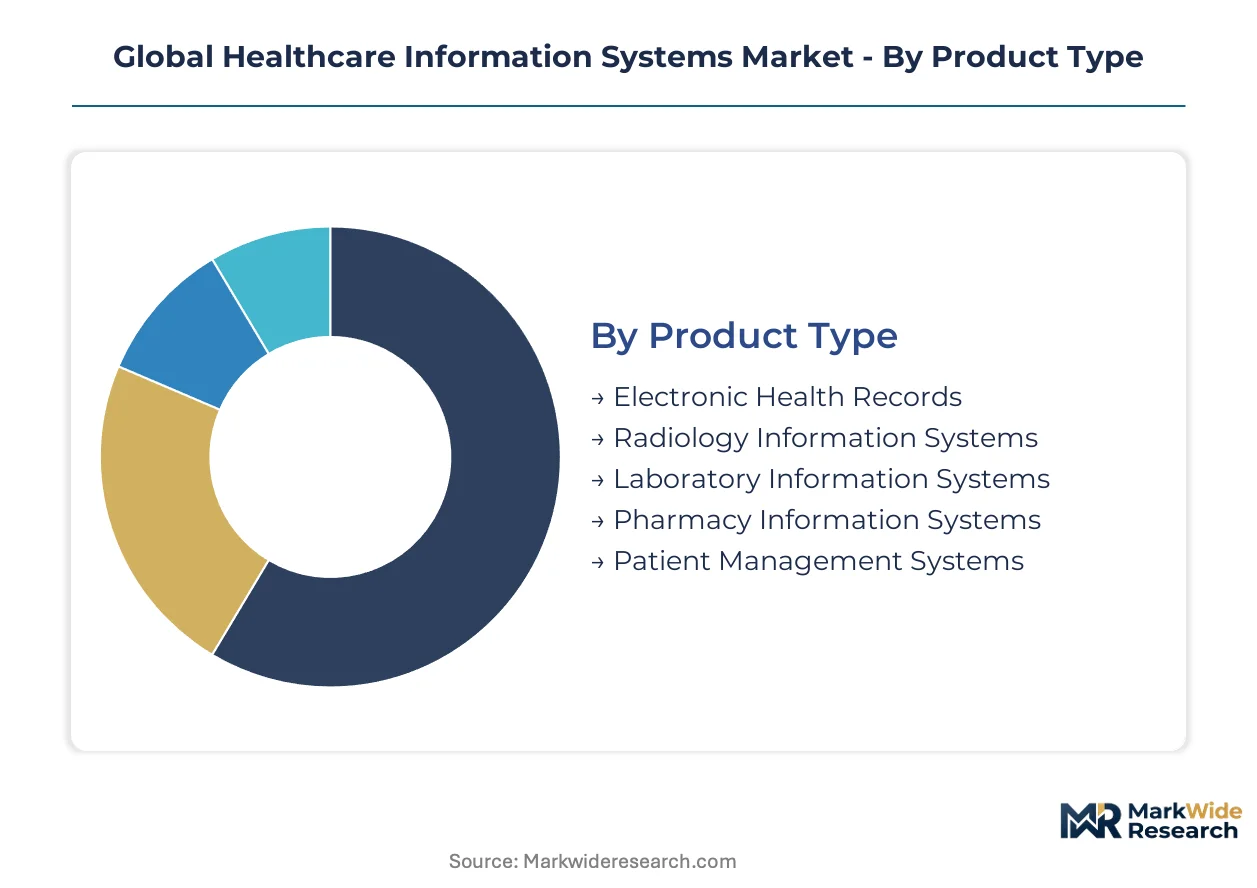
Healthcare information systems fragment across four structural dimensions that determine procurement priorities and vendor positioning. Product type and deployment mode shape capital allocation, while application focus and end-user scale dictate functionality requirements and integration complexity.
Product Type:
Hospital procurement committees differentiate platforms by clinical workflow depth versus administrative breadth.
- Electronic Health Records:Centralized repositories capturing longitudinal patient data across encounters, coded in HL7 FHIR formats. Demand concentrates in academic medical centers consolidating multi-site networks under unified data architectures. Germany's Digital Healthcare Act mandates are accelerating replacement of fragmented departmental systems.
- Radiology Information Systems:Workflow engines managing imaging orders, modality scheduling, and diagnostic report distribution. PACS integration requirements in diagnostic laboratories are driving specialized vendor selection criteria distinct from general EHR procurement.
- Laboratory Information Systems:Specimen tracking and result management platforms bridging analyzers with clinical records.
- Pharmacy Information Systems:Medication order verification and inventory control modules with FDA software-as-medical-device validation overlays.
- Patient Management Systems:Administrative scheduling and registration platforms with lighter clinical functionality.
Volume sits with Electronic Health Records; growth tilts toward Radiology Information Systems.
Application:
Functional modules align with reimbursement categories and liability exposure profiles.
- Patient Care Management:Longitudinal coordination tools tracking chronic disease progression across settings. Monetization opportunities outside acute care are deepening margin pools in United States accountable care organizations.
- Clinical Decision Support:Real-time alert engines requiring sub-100-millisecond response times for medication interaction warnings. FDA software-as-medical-device oversight is tightening validation protocols for algorithmic diagnostic recommendations.
- Medical Imaging:AI-augmented interpretation tools with EU AI Act conformity assessment obligations.
- Drug Administration:Barcode verification and infusion pump integration modules.
- Revenue Cycle Management:Claims processing and denial management workflows anchoring Cerner's competitive position through deep integration.
Revenue concentrates in Revenue Cycle Management; steepest expansion trajectory belongs to Clinical Decision Support.
End User:
Scale determines integration complexity and customization requirements.
- Hospitals:Multi-departmental platforms requiring 24/7 uptime guarantees and disaster recovery protocols. North American hospital networks are accelerating procurement of integrated suites over best-of-breed point solutions.
- Ambulatory Care Centers:Lighter deployments prioritizing interoperability with hospital-affiliated EHRs over standalone functionality.
- Diagnostic Laboratories:Specialized LIS-RIS integration with high-throughput specimen processing requirements.
- Pharmacies:Retail chain deployments emphasizing inventory optimization and prescriber connectivity.
- Rehabilitation Centers:Functional outcome tracking with distinct regulatory reporting obligations.
Procurement volume clusters in Hospitals; fastest share gains emerge in Ambulatory Care Centers.
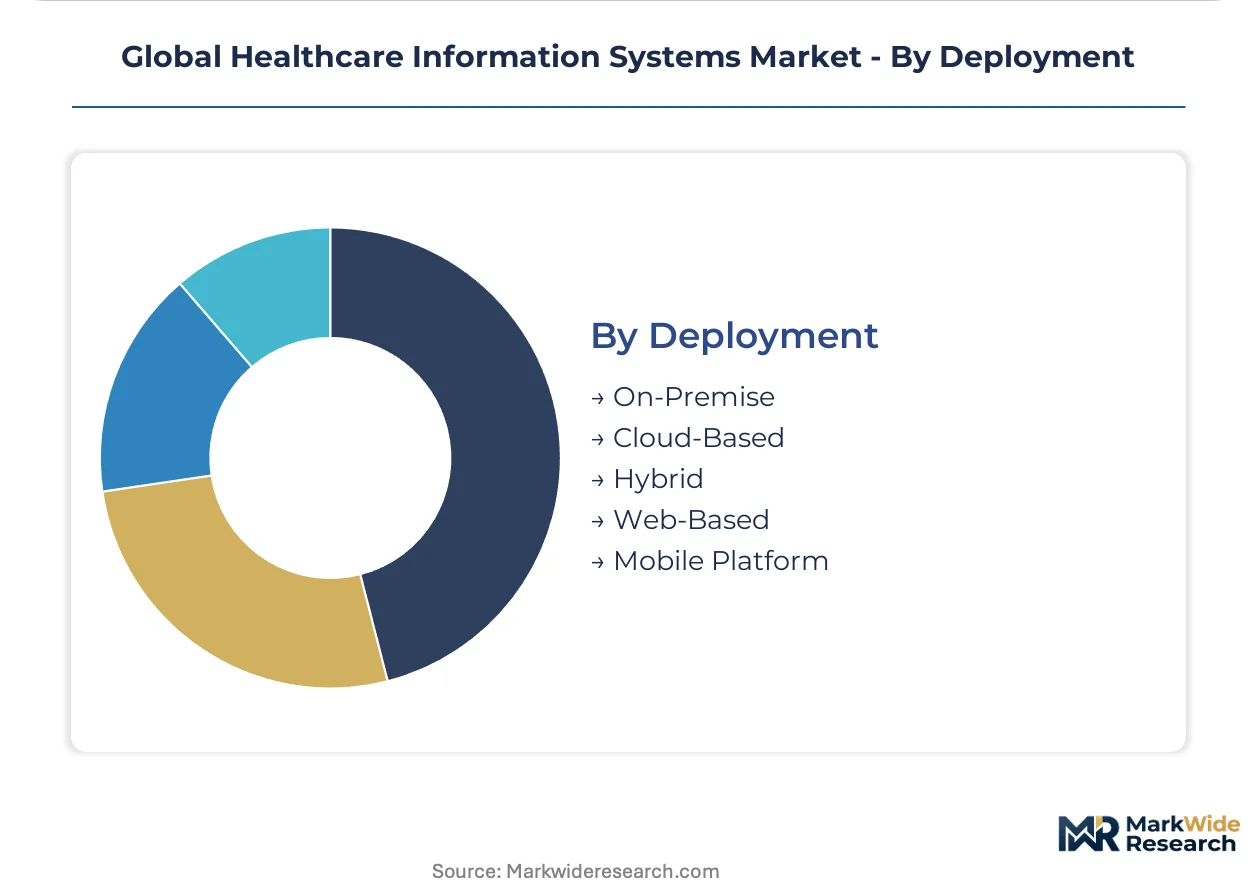
Deployment:
Infrastructure ownership models separate capital-constrained from operationally flexible buyers.
- Cloud-Based:Subscription architectures shedding server farm capital expenditures for operational expenditure alignment. Mid-sized United States community hospital networks favor this model to preserve clinical staffing reserves.
- On-Premise:Captive infrastructure retaining full data sovereignty for security-sensitive institutions. India's Digital Information Security in Healthcare Act localization mandates are sustaining demand despite migration pressures.
- Hybrid:Split architectures isolating protected data on-premise while leveraging cloud analytics.
- Web-Based:Browser-delivered functionality with lighter client-side requirements.
- Mobile Platform:Point-of-care access modules with offline synchronization capabilities.
Installed base remains On-Premise; expansion is concentrating fastest in Cloud-Based deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India scheme and Special Economic Zones in Bengaluru and Hyderabad are concentrating health-tech development. Germany's hospital digitization mandates under the Digital Healthcare Act are forcing legacy system replacements. The United States maintains dominant procurement volumes through academic medical center consolidation.
United States
Academic medical centers in Boston and the Research Triangle are consolidating multi-site networks under unified EHR architectures. HIPAA interoperability mandates are repositioning competitive entry barriers for new vendors. Epic Systems Corporation leverages its dominant installed base across Mayo Clinic and Cleveland Clinic to sustain pricing power.
Germany
The Digital Healthcare Act mandates are accelerating replacement of fragmented departmental systems in university hospitals. EU MDR cybersecurity annexes are elevating validation costs for clinical decision support modules entering procurement channels. Berlin and Munich hospital networks are prioritizing CE-marked platforms to preempt liability exposure.
India
The Digital Information Security in Healthcare Act data localization mandate is creating certified vendor demand across South Asian hospital networks. Hyderabad's health-tech corridor and Bengaluru's IT clusters are hosting development centers for FHIR-compliant platforms. Apollo Hospitals and Max Healthcare are piloting cloud-based deployments in tier-1 cities.
Saudi Arabia
Healthcare privatization is bypassing legacy infrastructure constraints through greenfield hospital construction in Riyadh and Jeddah. The Ministry of Health's Vision 2030 digital health initiatives are mandating integrated platform procurement for new facilities. NEOM's cognitive city project is specifying AI-embedded diagnostic modules from inception.
Japan
METI's healthcare digitization subsidies are accelerating cloud migration among mid-sized regional hospitals. Osaka and Nagoya medical districts are consolidating previously siloed departmental systems. PMDA software-as-medical-device guidance is tightening validation protocols for clinical decision support algorithms.
Global Healthcare Information Systems Market Competitive Landscape
United States producers anchor the premium tier through dominant installed bases across academic medical centers; European specialists hold regulatory certification advantages under EU MDR and AI Act frameworks. The vendor landscape exhibits concentrated oligopoly characteristics at the top, with fragmentation increasing among mid-tier ambulatory specialists. Three archetypes dominate: integrated suite providers, best-of-breed point solution vendors, and cloud-native platform entrants. Consolidation through hospital network M&A and strategic cloud partnerships represent the dominant competitive vectors reshaping positioning.
Within the integrated suite tier, Epic Systems Corporation and Cerner Corporation exemplify contrasting defensive strategies. Epic leverages its dominant academic medical center footprint to sustain pricing power through high switching costs, while Cerner anchors its position through deep revenue cycle workflow integration. Oracle Health occupies a transitional position following its acquisition trajectory, representing the platform consolidation archetype that is displacing perpetual license arrangements with subscription economics. Cloud-native specialists such as athenahealth sit within the ambulatory-focused segment, capitalizing on mid-sized community hospital preferences for operational expenditure models.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| Cerner Corporation |
| GE Healthcare |
| Philips Healthcare |
| McKesson Corporation |
| athenahealth |
| NextGen Healthcare |
| Allscripts Healthcare Solutions |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-validated clinical decision support modules and uncertified workflow tools manifests in both pricing premiums and supply chain sourcing strategies. Hospital procurement committees in Germany and the United States pay substantial premiums for CE-marked and FDA-cleared platforms while channeling volume through authorized implementation partners with direct vendor relationships.
Pricing Analysis
Short lead-time premiums dominate pricing for clinical decision support modules requiring sub-100-millisecond alert latency, with hospitals paying subscription premiums for guaranteed edge computing deployment. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with full FHIR integration from mid-sized community hospitals with lighter configurations. Cost compression in the standard tier is intensifying because cloud-native entrants are undercutting legacy perpetual-license incumbents. Ambulatory care centers exhibit highest price sensitivity due to capital constraints, while academic medical centers show lowest sensitivity given bundled research funding.
Supply Chain Analysis
Single-source vulnerability sits with United States-based hyperscaler cloud infrastructure for real-time clinical alert processing. Software development concentrates in India, the United States, and Germany, with implementation services drawing from specialized health informatics talent pools in Bengaluru, Boston, and Berlin. Raw material dependencies include semiconductor components for edge computing hardware, proprietary FHIR middleware licenses, and certified cybersecurity audit services. Tariff exposure runs through cross-border data localization requirements under India's Digital Information Security in Healthcare Act. Distribution runs through hospital GPO contracts and direct enterprise sales teams with named account executives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play. EU MDR cybersecurity annex compliance costs are forcing sub-scale vendors toward strategic exits or acquisition.
For Market Incumbents: Deploy backward integration into cloud infrastructure to capture margin pools currently flowing to hyperscalers. Cerner's revenue cycle workflow anchoring and Epic's academic medical center lock-in demonstrate how deep integration creates switching cost moats. Counter the threat from cloud-native ambulatory specialists by accelerating quarterly release cycles for modular microservices architectures. For New Entrants and Emerging Players: AI-embedded diagnostic modules with EU AI Act pre-certification offer the most penetrable wedge for European hospital procurement. Target Saudi Arabia's greenfield hospital construction under Vision 2030, where legacy system displacement is unnecessary. Pursue a channel partnership strategy with regional system integrators possessing existing hospital relationships rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native platform specialists given the shift from perpetual licenses to subscription economics across mid-sized United States community hospital networks. Long-term viability favors vendors with FHIR-native architectures and multi-jurisdiction regulatory certifications already in place. Watch for FDA software-as-medical-device guidance expansions covering additional diagnostic algorithm categories as the inflection signal for accelerated M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Epic and Cerner are consolidating best-of-breed point solutions into unified suites to reduce hospital vendor management burden. |
| CE Marking Pathway | EU AI Act conformity assessments for clinical decision support algorithms are becoming mandatory for German hospital procurement eligibility. |
| Hospital System Partnership | Long-term EHR contracts with academic medical centers lock in decades of recurring revenue and limit competitor access. |
| Software Companion Development | FDA software-as-medical-device validation for AI diagnostic modules opens new reimbursement categories in oncology workflows. |
| Reimbursement Strategy | Accountable care organization contracts in the United States reward longitudinal patient care management platform adoption. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare reimbursement data underwrites the qualitative findings. Primary interviews with hospital purchasing committee members, biomedical engineers, health informatics directors, and GPO contracts managers were combined with secondary validation from FDA software-as-medical-device guidance documents, EU MDR cybersecurity annexes, and hospital digitization mandate filings. Bottom-up vendor revenue triangulation against top-down addressable market sizing anchored the segmentation splits.
Comparable-period anchoring to historical EHR adoption curves and cloud migration trajectories in adjacent enterprise software categories structured the projection framework. The forecast models deployment mode, organization size, application focus, and regional regulatory cluster across the analysis window. CAGRs were derived from segment-level growth rate convergence analysis. FHIR protocol adoption velocity and AI-embedded diagnostic module reimbursement expansion served as key healthcare-specific forecast inputs.
Several conditions sit outside the modeled scope, including single-country regulatory reversals, hyperscaler cloud service discontinuations, and hospital network bankruptcy cascades. Forecasts reflect documented assumptions about continued HIPAA interoperability mandate enforcement and EU AI Act implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Healthcare Mobile Computers Market
Medical Information Systems
Global Allergy EMR Software Market
Medical Information Systems
Critical Care Information Systems Market
Medical Information Systems
Global Medical Document Management Systems Market
Medical Information Systems
Donor Management Software Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Artificial Intelligence in Medical Software Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
Global Medical Scheduling Software Market
Medical Information Systems
Global Oncology Information System Market
Medical Information Systems
Medical Talent Management IT Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
Dentistry EMR Software Market