
 Case Coder Market | 2026-2036
Case Coder Market Size, Share, and Industry Trends Forecast 2026-2036
Case Coder Market Analysis
Equipment leasing and managed service contracts are fragmenting capital barriers for mid-sized healthcare providers seeking case coding automation. Videojet Technologies leverages its industrial printing heritage to sustain channel relationships with packaging-integrated healthcare labeling systems. Markem Imaje anchors European market presence through pharmaceutical serialization compliance. Linx Printing Technologies competes on thermal inkjet specialization for high-speed carton marking in pharmaceutical distribution.
A case coder is an automated marking system that applies variable data—batch codes, expiration dates, barcodes, and traceability identifiers—directly onto corrugated shipping containers, cases, and cartons using non-contact technologies such as thermal inkjet, piezoelectric drop-on-demand, or laser ablation at speeds exceeding 300 meters per minute. Its primary commercial purpose is to ensure supply chain traceability, regulatory serialization compliance, and inventory accuracy without disrupting automated packaging line throughput. Integrated solutions command the dominant revenue share as healthcare manufacturers prioritize ERP-connected coding workflows that eliminate manual data re-entry. Cloud-based systems represent the fastest-expanding segment, with SaaS deployment models enabling real-time code verification and centralized template management across multi-facility hospital networks. Standalone software retains relevance among smaller legal firms and research institutions with limited IT infrastructure.
FDA serialization mandates under the Drug Supply Chain Security Act shape pharmaceutical case coding requirements, while HIPAA privacy rules govern how healthcare providers transmit coded patient data through automated systems. The Centers for Medicare and Medicaid Services continually revises reimbursement coding guidelines, forcing providers to upgrade case coder logic to prevent claim rejection. Stakeholders must weigh total cost of ownership against compliance exposure when selecting between on-premise autonomy and SaaS agility for their coding infrastructure.
Market Dynamics
Healthcare manufacturers face mounting pressure to synchronize case coding systems with enterprise resource planning platforms, eliminating manual data bridges that create serialization errors and compliance exposure during high-volume pharmaceutical distribution.
Growth Catalysts
- Drug Supply Chain Security Act:FDA serialization mandates compel pharmaceutical manufacturers to deploy automated case coding infrastructure for track-and-trace compliance across distribution networks.
- Cloud-based SaaS deployment:Multi-facility hospital networks adopt centralized template management to reduce IT overhead and accelerate code verification across dispersed operations.
- Thermal inkjet specialization:High-speed carton marking requirements in pharmaceutical distribution drive equipment upgrades that sustain throughput above 300 meters per minute.
Market Restraints
- Total cost of ownership compression:Mid-sized physician practice groups defer capital investment despite compliance pressure, stretching replacement cycles for legacy coding equipment.
- ICD-10 transition friction:Centers for Medicare and Medicaid Services reimbursement guideline revisions force repeated logic upgrades, creating recurring engineering costs for installed base maintenance.
- Legacy system entrenchment:Research institutions and smaller legal firms with limited IT infrastructure resist cloud migration, fragmenting addressable market development.
Strategic Opportunities
- Equipment leasing proliferation:Managed service contracts fragment capital barriers for mid-sized healthcare providers seeking automation without upfront hardware acquisition.
- Real-time verification convergence:Integration of machine vision with thermal inkjet systems enables automatic rejection of misprinted cartons before palletization.
- HIPAA-aligned data transmission:Privacy rule compliance creates specification demand for encrypted coding workflows in patient-facing healthcare logistics.
Industry Challenges
- Revenue cycle management integration:Hospital IT departments struggle to bridge case coder outputs with billing systems, creating claim denial risks that erode automation ROI.
- Multi-standard harmonization:Manufacturers serving both pharmaceutical serialization and general healthcare logistics must maintain parallel coding logic for FDA, HIPAA, and state-level requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Case Coder Market |
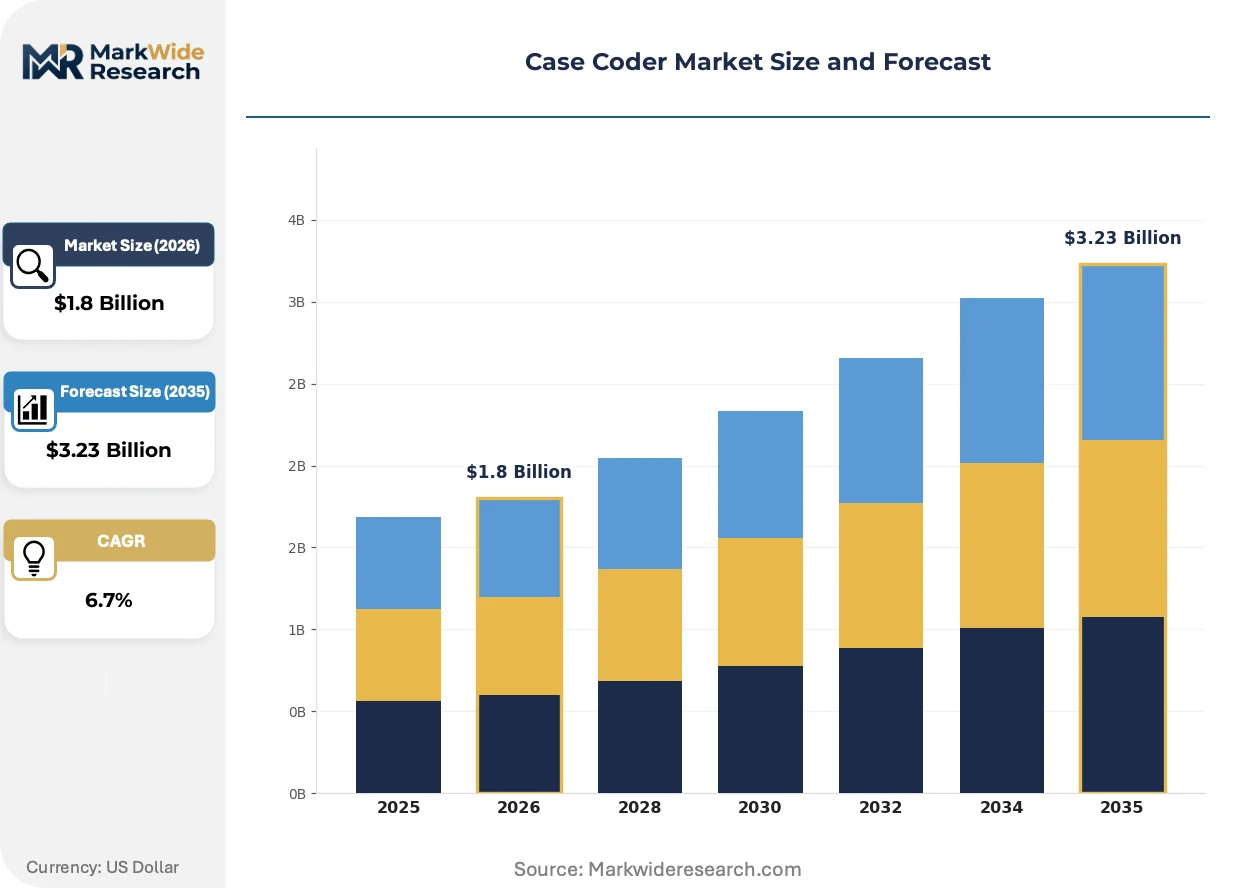
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Integrated Solution, Cloud-based System, Desktop Application End User: Healthcare Providers, Insurance Companies, Legal Firms, Research Institutions Deployment Model: On-Premise, SaaS, Hybrid, Managed Service Feature: Automated Coding, Customizable Reports, Real-time Analytics, User-friendly Interface |
| Companies Covered | Videojet Technologies, Inc., Markem Imaje Corporation, Linx Printing Technologies, SPG Packaging UK Ltd, Squid Ink, Interactive Coding Equipment (ICE), Superior Case Coding, Zanasi S.r.l., Kiwi Coders Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Case Coder Market Emerging Trajectories
Automation architectures are converging around cloud-native deployment models that compress the gap between production-line coding and enterprise data governance. Three developments define this transition.
Thermal inkjet systems are hybridizing with piezoelectric drop-on-demand modules to enable substrate-agnostic marking across corrugated, coated cartons, and flexible films without line changeover. Pharmaceutical contract packagers in high-mix environments adopt these dual-technology printheads to reduce downtime between batch runs. Equipment OEMs are compressing their product roadmaps around this hybrid architecture, marginalizing single-technology platforms.
EMA pharmaceutical serialization guidelines are tightening alignment with FDA Drug Supply Chain Security Act requirements, creating transatlantic regulatory convergence that simplifies multi-region packaging strategies. European manufacturers exporting to United States markets must now validate coding systems against both EMA and FDA traceability standards. This dual-compliance burden favors integrated solution vendors with pre-validated software templates.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance contracts into subscription-based code verification and remote diagnostics tiers. Pharmaceutical distributors in Germany and Switzerland now procure coding hardware separately from cloud-based template management and compliance reporting. This procurement model compression shifts vendor revenue toward recurring software streams and away from capital equipment margins.
Case Coder Market Segmentation
Case coder procurement patterns diverge sharply across healthcare, insurance, and legal verticals, with each end-use imposing distinct compliance architectures and integration requirements. Understanding these segment boundaries clarifies why vendor pricing strategies and service models must adapt to deployment scale rather than assume uniform automation demand.
Product Type:
After-sales service intensity varies dramatically by product architecture, with cloud-based systems demanding continuous remote monitoring while standalone software requires minimal vendor touchpoints beyond periodic updates.
- Cloud-based System:Multi-tenant SaaS architectures enable centralized template management across hospital networks, with subscription revenue models shifting vendor economics toward recurring service streams. Demand concentrates among United States health systems facing HIPAA-mandated audit trails and FDA serialization requirements under the Drug Supply Chain Security Act.
- Integrated Solution:ERP-connected coding workflows eliminate manual data re-entry between production lines and enterprise systems, commanding premium pricing from pharmaceutical manufacturers. United States hospital procurement teams prioritize these configurations to reduce claim denial exposure during high-volume distribution cycles.
- Standalone Software:Lightweight deployments suit smaller legal firms and research institutions with constrained IT infrastructure and limited integration requirements.
- Desktop Application:Single-workstation licensing retains relevance among boutique insurance adjusters and independent medical coding contractors.
By volume, Integrated Solution leads. By growth pace, Cloud-based System is expanding most quickly.
End User:
Customer scale determines deployment complexity, with enterprise health systems demanding multi-facility orchestration while independent practices accept simpler configurations.
- Healthcare Providers:Hospital systems and physician practice groups deploy case coders to synchronize clinical documentation with billing workflows, reducing revenue cycle friction. United States providers face mounting pressure from Centers for Medicare and Medicaid Services reimbursement guideline revisions that force repeated logic upgrades.
- Insurance Companies:Payers leverage automated coding to accelerate claim adjudication and detect provider submission patterns that trigger manual review. Demand clusters among large commercial insurers in the United States seeking to compress processing costs per claim.
- Legal Firms:Medical malpractice and personal injury practices use coding systems to reconstruct treatment timelines from fragmented clinical records.
- Research Institutions:Academic medical centers apply case coders to standardize phenotyping data for multi-site clinical trials with limited IT infrastructure budgets.
Healthcare Providers dominate absolute deployment count. Insurance Companies are climbing the fastest as prior authorization automation expands.
Deployment Model:
Capital availability shapes model selection, with mid-sized providers gravitating toward consumption-based alternatives that defer hardware ownership.
- SaaS:Browser-accessible coding platforms with centralized compliance updates reduce internal IT burden for multi-location health networks. United States pharmaceutical distributors adopt these configurations to satisfy FDA track-and-trace mandates without maintaining dedicated infrastructure teams.
- Managed Service:Equipment leasing bundled with remote diagnostics and template management fragments capital barriers for mid-sized physician groups. Demand concentrates among United States ambulatory surgery centers and specialty clinics seeking automation without upfront acquisition costs.
- On-Premise:Self-hosted installations retain favor among research institutions with stringent data sovereignty requirements.
- Hybrid:Split architectures accommodate organizations transitioning between legacy on-premise systems and cloud-native replacements.
On-Premise retains the largest installed base. SaaS is gaining share fastest as hospital consolidation accelerates.
Feature:
Functional sophistication correlates directly with pricing tier, creating clear segmentation between compliance-minimum and premium-analytics offerings.
- Automated Coding:Rules engines that map clinical documentation to standardized code sets—ICD-10, CPT, HCPCS—without human intervention form the core value proposition. United States health systems prioritize these capabilities to address ICD-10 transition friction and reduce claim rejection rates.
- Real-time Analytics:Dashboards surfacing coding accuracy metrics, denial patterns, and revenue impact enable proactive revenue cycle management. Demand concentrates among United States hospital finance departments seeking to quantify automation ROI against compliance exposure.
- Customizable Reports:Template-driven output generation supports payer-specific submission formats and internal audit requirements.
- User-friendly Interface:Reduced training burden accelerates adoption among clinical staff without dedicated coding certification.
Automated Coding leads by deployment penetration. Real-time Analytics shows the steepest expansion trajectory as value-based contracting intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in India by a factor reflecting FDA serialization mandates versus emerging-market compliance lag. German and Swiss manufacturers extract premiums from transatlantic regulatory convergence. Chinese domestic suppliers compete on throughput economics for Asia-Pacific pharmaceutical contract packaging.
United States
Hospital systems and physician practice groups drive demand for automated coding systems that synchronize clinical documentation with billing workflows. FDA Drug Supply Chain Security Act mandates compel pharmaceutical manufacturers to deploy track-and-trace infrastructure. The Boston-Cambridge pharmaceutical cluster concentrates serialization validation services for multi-facility health networks.
Germany
Pharmaceutical exporters to United States markets must validate coding systems against dual EMA-FDA traceability standards. The country's national pharmaceutical regulator enforces serialization guidelines tightening alignment with transatlantic requirements. The Rhine-Main industrial corridor hosts contract packagers adopting hybrid thermal inkjet-piezoelectric systems for high-mix environments.
Switzerland
Swissmedic pharmaceutical serialization rules create specification demand for encrypted coding workflows in cross-border distribution. Pharmaceutical distributors in Basel and Zurich procure hardware separately from cloud-based template management under subscription models. The Basel-Land pharma manufacturing belt concentrates track-and-trace system integration expertise.
China
NMPA pharmaceutical traceability requirements are elevating compliance requirements for domestic and export-oriented manufacturers. The national medical products administration mandates serialization infrastructure upgrades across distribution networks. The Yangtze River Delta pharmaceutical contract packaging hub adopts high-speed carton marking systems exceeding 300 meters per minute.
India
CDSCO pharmaceutical serialization guidelines are compressing replacement cycles for legacy coding equipment among export-oriented manufacturers. The national pharmaceutical regulator enforces track-and-trace compliance for formulations destined for regulated markets. The Hyderabad-Visakhapatnam pharmaceutical belt concentrates coding system validation services for United States-bound generics.
Case Coder Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying printheads, controllers, and verification modules. The vendor base clusters around three strategic archetypes: industrial printing heritage players leveraging channel relationships with packaging-integrated healthcare labeling systems; pharmaceutical serialization specialists anchoring European market presence through compliance-focused offerings; and thermal inkjet pure-plays competing on high-speed throughput for distribution environments. Competitive moves concentrate on equipment-plus-software bundling and managed service contract proliferation that fragments capital barriers for mid-sized providers.
Within the industrial printing heritage tier, Videojet Technologies, Inc. and Markem Imaje Corporation exemplify platform integrators that have extended packaging line relationships into healthcare serialization compliance. Linx Printing Technologies occupies a position among thermal inkjet specialists addressing high-speed pharmaceutical distribution requirements. These three anchors represent divergent strategic postures: full-stack system integration versus component-level speed optimization versus regional compliance anchoring.
| Leading Market Players |
|---|
| Videojet Technologies, Inc. |
| Markem Imaje Corporation |
| Linx Printing Technologies |
| SPG Packaging UK Ltd |
| Squid Ink |
| Interactive Coding Equipment (ICE) |
| Superior Case Coding |
| Zanasi S.r.l. |
| Kiwi Coders Corporation |
| Others |
Supply Flow & Price Mechanics
FDA serialization mandates under the Drug Supply Chain Security Act create a regulatory chokepoint that determines both pricing tier spreads and supply chain shape, compressing margins for non-compliant vendors while elevating premiums for pre-validated integrated solutions.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical manufacturers paying premiums for ERP-connected coding workflows while mid-sized physician groups defer capital investment. Price differentiation hinges on FDA validation status and after-sales service bundling, with subscription SaaS models gaining traction against perpetual licenses. Cost compression in the economy tier is intensifying because equipment leasing proliferation fragments upfront revenue recognition. Hospital systems show least price sensitivity due to claim denial exposure, while independent legal firms and research institutions resist premium tiers.
Supply Chain Analysis
Thermal inkjet printheads and piezoelectric controllers draw from concentrated manufacturing bases in Germany, Switzerland, and Japan, with specialized ink formulations sourcing from chemical suppliers in the United States and Netherlands. Raw material dependencies center on semiconductor-grade substrates, precision nozzles, and UV-curable inks. Single-source vulnerability runs through European pharmaceutical serialization component suppliers validated against dual EMA-FDA standards. Distribution runs through packaging-integrated healthcare labeling system channels anchored by industrial printing heritage players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native coding platforms threaten traditional equipment-plus-software bundling, forcing incumbents to defend recurring revenue streams against SaaS substitution before hospital consolidation locks in vendor relationships.
For Market Incumbents: Insulate installed base relationships by embedding remote diagnostics and template management into multi-year managed service contracts that raise switching costs. Deepen backward integration into thermal inkjet printhead manufacturing to capture margin from component suppliers and accelerate hybrid architecture roadmaps. Prioritize FDA pre-validation investments that compress pharmaceutical customer procurement cycles. For New Entrants and Emerging Players: Pursue white-space opportunities in mid-sized ambulatory surgery centers and specialty clinics underserved by capital-intensive integrated solutions. Target equipment leasing proliferation as the most penetrable deployment model, offering consumption-based alternatives that defer hardware ownership. Lead with HIPAA-aligned encrypted coding workflows as a differentiated go-to-market angle against legacy vendors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with pre-validated compliance templates over component specialists facing margin compression. Long-term viability rests on recurring software revenue streams displacing capital equipment margins across the analysis window. Monitor hospital network consolidation velocity as the primary inflection indicator for vendor concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Printhead Architecture Development | Dual thermal inkjet-piezoelectric modules reduce downtime between pharmaceutical batch runs. |
| Cloud-Native SaaS Migration | Centralized template management satisfies FDA track-and-trace mandates without dedicated infrastructure teams. |
| Managed Service Contract Proliferation | Equipment leasing fragments capital barriers for mid-sized physician practice groups seeking automation. |
| EMA-FDA Dual Compliance Validation | Pre-validated software templates capture European pharmaceutical exporters to United States markets. |
| Machine Vision Integration | Real-time code verification enables automatic rejection of misprinted cartons before palletization. |
Methodological Framework
A standing panel of hospital procurement managers, pharmaceutical packaging engineers, GPO contracts managers, and biomedical equipment specialists provided ongoing calibration across primary interviews and secondary validation. Data synthesis combined FDA Drug Supply Chain Security Act filings, CMS reimbursement guideline revisions, hospital procurement databases, and GPO contract records with bottom-up equipment shipment analysis and top-down healthcare IT spending estimates.
Scenario-bracketing around ICD-10 transition friction and cloud adoption velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, deployment model, end-user scale, and regional regulatory cluster intensity. CAGRs were derived from equipment replacement cycle analysis and SaaS subscription revenue trajectories, with pharmaceutical serialization mandate deadlines and hospital consolidation patterns serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles and reimbursement rate compression would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement continuity and cloud infrastructure reliability that may require revision. Cross-checking against hospital IT budget disclosures and pharmaceutical packaging line investment announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Healthcare ERP Market
Medical Information Systems
Healthcare Information Governance Solution Market
Medical Information Systems
India EMR (Electronic Medical Records) Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
AI in Medical Billing Market
Medical Information Systems
Global Computerized Physician Order Entry Market
Medical Information Systems
Ophthalmology EMR Software Market
Medical Information Systems
Medical Information Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
AI Medical Service Market
Medical Information Systems
Medical Simulation Software Market
Medical Information Systems
Global Laboratory Information Management System for Forensic Science Market
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
Hospital Information Systems Market