
 Healthcare Information Governance Solution Market | 2026-2036
Healthcare Information Governance Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Information Governance Solution Market Foresight
The EU AI Act is pivoting healthcare data governance toward algorithmic accountability requirements across European clinical networks. IBM leverages its hybrid cloud architecture to sustain enterprise-grade governance deployments for multi-site hospital systems. Oracle anchors its position through integrated electronic health record pipelines that compete on interoperability depth with legacy infrastructure.
Healthcare Information Governance Solutions encompass policy frameworks, technical controls, and audit mechanisms that enforce data quality, retention compliance, and access security across clinical and administrative health records. These systems typically integrate metadata tagging engines, automated classification protocols, and chain-of-custody tracking to ensure regulatory defensibility and operational continuity. Cloud-Based Solutions lead technology adoption as health systems migrate off aging on-premise data warehouses, while AI-Driven Tools represent the fastest-expanding segment as natural language processing automates unstructured clinical document review. Data Security commands the largest product-type margin pool given the premium pricing attached to breach-prevention and encryption-at-rest capabilities.
FDA 21 CFR Part 11, HIPAA, and GDPR collectively shape product certification requirements and cross-border data transfer protocols for healthcare information governance vendors. The EU AI Act introduces additional conformity obligations for clinical decision-support algorithms that process protected health information. Stakeholders must monitor evolving interoperability mandates from ONC and emerging state-level privacy statutes that fragment compliance baselines across jurisdictional boundaries.
Market Dynamics
HIPAA Security Rule enforcement and the EU AI Act are compressing procurement timelines for automated compliance infrastructure across hospital systems and clinical networks.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail mandates in the United States are forcing pharmaceutical manufacturers to upgrade document management systems with embedded governance controls.
- Cloud migration:Integrated delivery networks are retiring on-premise data warehouses and adopting cloud-native governance suites to reduce infrastructure overhead.
- Natural language processing:AI-driven clinical document classification is automating unstructured data review, cutting manual audit preparation time for compliance teams.
Market Restraints
- Encryption-at-rest licensing:Premium data security modules carry per-petabyte pricing that strains mid-sized hospital IT budgets.
- Legacy system entrenchment:Decades-old electronic health record architectures in the United States create integration friction that slows governance platform deployment.
- Interoperability standard fragmentation:Competing HL7 FHIR implementation guides across state health information exchanges force vendors to maintain multiple certification tracks.
Strategic Opportunities
- GDPR Article 30 gap:European clinical networks lack automated processing activity registers, creating demand for governance tools with built-in record-of-processing automation.
- Remote patient monitoring data streams:Wearable-generated continuous health data requires new retention and consent management frameworks that legacy platforms cannot handle.
- State-level privacy statutes:California's Consumer Privacy Act and emerging equivalents in Virginia and Colorado are fragmenting compliance baselines and driving demand for jurisdiction-aware policy engines.
Industry Challenges
- Clinical informatics talent scarcity:Health systems struggle to hire staff who bridge both HIPAA technical safeguards and cloud architecture administration.
- FHIR R4 certification timelines:ONC interoperability mandates require 12-18 month validation cycles that delay product launches and compress vendor R&D windows.
- Chain-of-custody verification:Multi-site hospital systems face operational complexity in maintaining audit-ready data lineage across federated cloud deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Information Governance Solution Market |
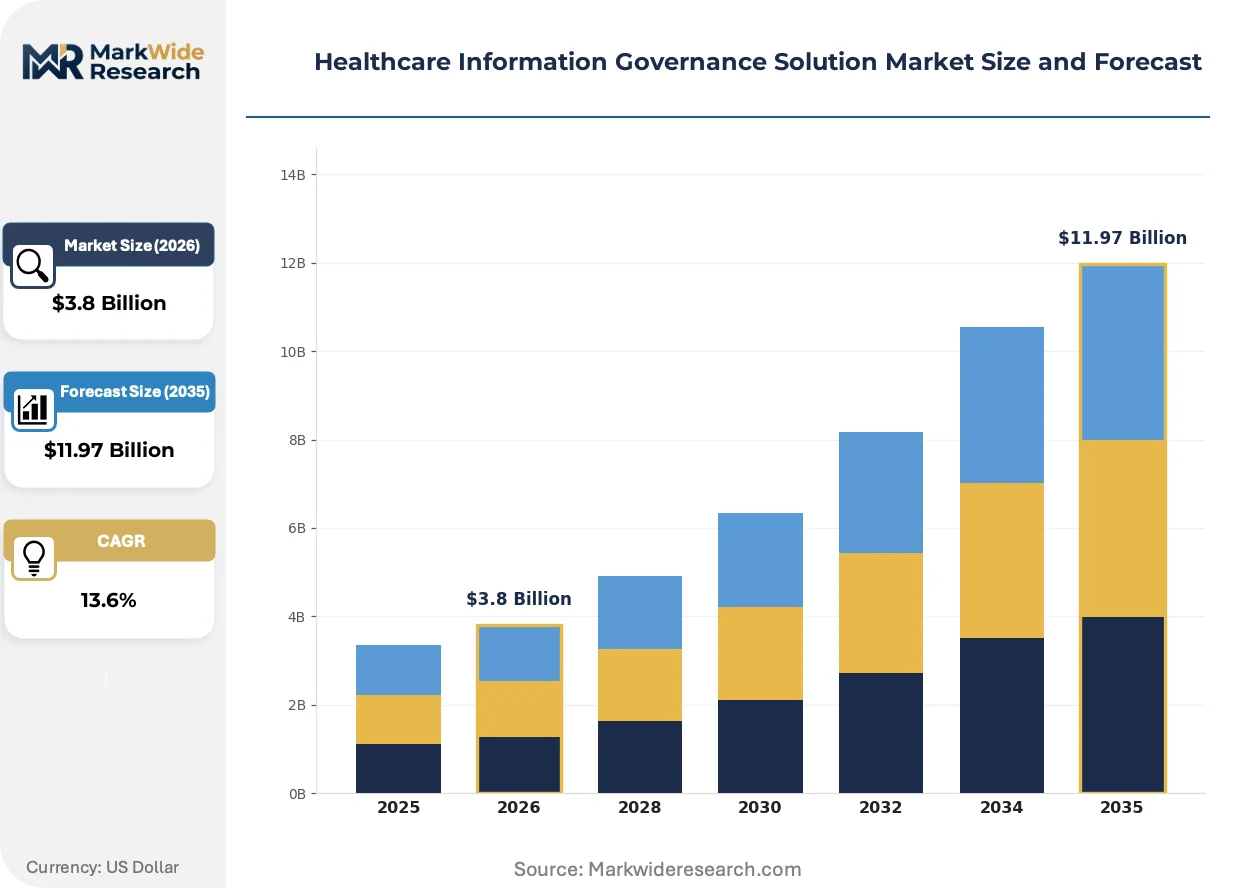
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Management, Compliance Tracking, Risk Assessment, Data Security Technology: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, AI-Driven Tools Application: Patient Records, Clinical Trials, Regulatory Compliance, Financial Auditing End User: Healthcare Providers, Insurance Companies, Research Institutions, Pharmaceutical Firms |
| Companies Covered | IBM, Oracle, McKesson Corporation, Optum, Veradigm, athenahealth, Cognizant, GE Healthcare, Epic Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Information Governance Solution Market Shifts & Advancements
Algorithmic accountability requirements and cloud-native architecture adoption are restructuring how clinical networks procure, deploy, and audit information governance infrastructure.
Zero-trust security architectures are consolidating access control decisions for protected health information across hybrid cloud environments. Large hospital systems in the United States are mandating microsegmentation for all clinical data flows, compressing vendor evaluation criteria around identity-aware proxy capabilities. This consolidation is eliminating point-solution security vendors that lack native integration with major cloud identity providers.
The EU AI Act's risk-classification framework for clinical decision-support systems is forcing algorithmic impact assessments into standard procurement workflows. European clinical networks must now document training data provenance and model performance drift before deploying diagnostic algorithms. High-risk AI applications in radiology and pathology are seeing extended legal review cycles that favor governance platforms with pre-built conformity documentation templates.
Subscription-based governance-as-a-service models are displacing perpetual license structures in mid-market health system procurement. Chief information officers now prioritize operational expenditure predictability over capital ownership, particularly for encryption key management and automated retention policy enforcement. This shift is most pronounced among regional hospital alliances in Germany and the Netherlands that pool governance infrastructure across member institutions.
Healthcare Information Governance Solution Market Segmentation
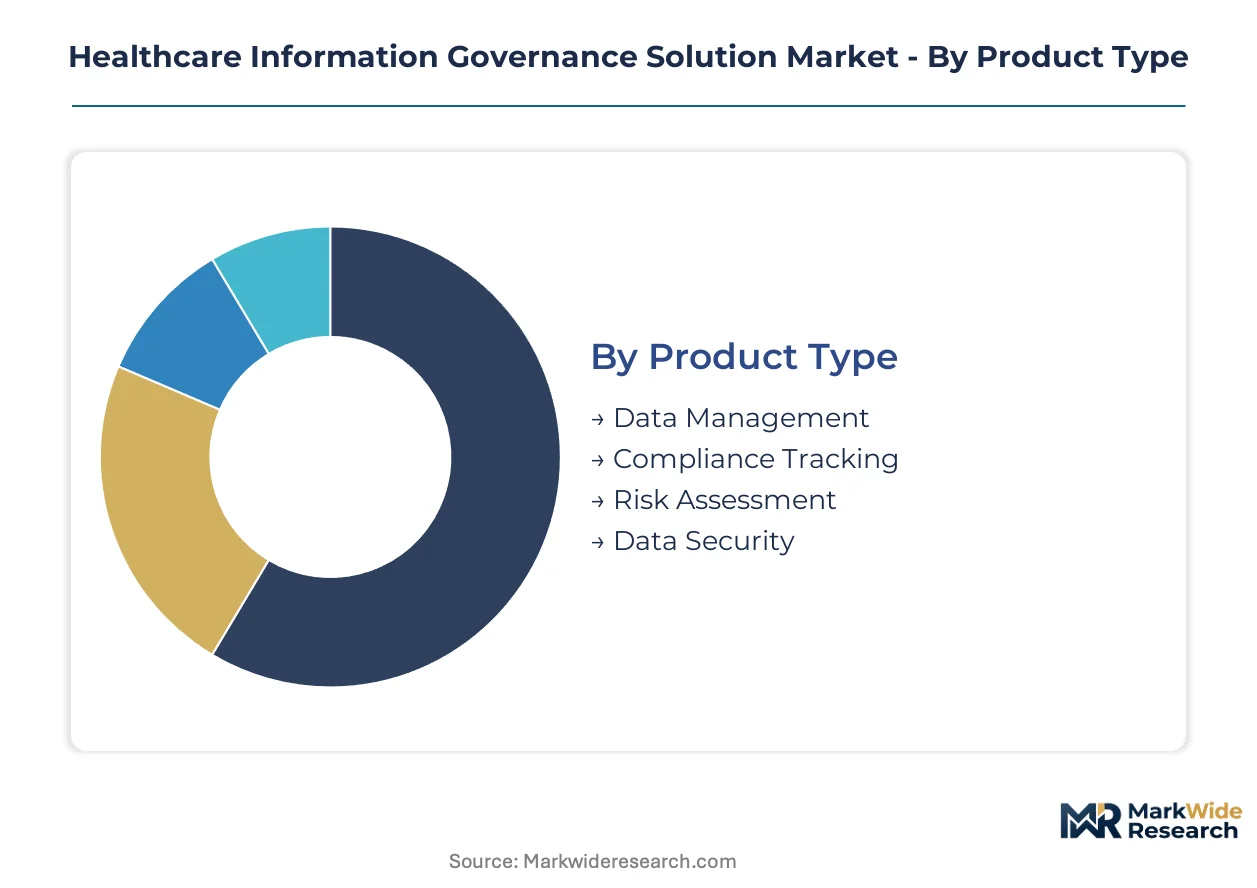
Healthcare information governance solutions fragment across four critical dimensions that determine procurement priorities, integration complexity, and compliance architecture. Product type and technology choices dominate initial vendor selection, while application scope and end-user category shape deployment scale and policy engine configuration.
Product Type:
Standardization dominates data management and security modules, while compliance tracking and risk assessment demand heavier customization to match jurisdictional rule sets.
- Data Management:Metadata tagging engines and automated classification protocols form the technical backbone for health record organization. United States hospital systems prioritize these capabilities to satisfy HIPAA Security Rule audit requirements while reducing manual data stewardship overhead.
- Data Security:Encryption-at-rest modules, identity-aware proxies, and breach-prevention systems command premium pricing per petabyte. Mid-sized hospital IT budgets strain under licensing costs, driving demand for subscription-based governance-as-a-service alternatives.
- Compliance Tracking:Automated policy enforcement engines with jurisdiction-aware rule sets. European clinical networks require built-in EU AI Act conformity documentation.
- Risk Assessment:Predictive analytics for data lineage anomalies and access pattern violations. Pharmaceutical manufacturers deploy these for FDA 21 CFR Part 11 audit readiness.
Most installed capacity flows through Data Management. Expansion is steepest in Data Security.
Technology:
Cost tier stratification separates capital-intensive on-premise deployments from operational expenditure models favoring cloud-native and hybrid architectures.
- Cloud-Based Solutions:Native governance suites with automated retention policy enforcement and encryption key management delivered as subscription services. Integrated delivery networks across Germany and the Netherlands pool these across member institutions to achieve operational expenditure predictability.
- AI-Driven Tools:Natural language processing engines that automate unstructured clinical document classification and review. Compliance teams cut manual audit preparation time significantly while satisfying emerging algorithmic accountability mandates.
- Hybrid Solutions:Federated architectures bridging on-premise legacy systems with cloud-native policy engines. Multi-site hospital systems deploy these to maintain chain-of-custody verification across distributed infrastructure.
- On-Premise Solutions:Aging data warehouse governance modules with embedded audit trail capabilities. United States health systems with decades-old electronic health record architectures retain these for integration continuity.
Procurement volume concentrates in Cloud-Based Solutions. AI-Driven Tools are climbing the fastest as clinical networks automate document review workflows.
Application:
Customer type determines application priority, with providers and pharmaceutical firms driving divergent functional requirements across the four use cases.
- Patient Records:Policy frameworks governing protected health information access, retention, and interoperability across care transitions. HIPAA technical safeguards and state-level privacy statutes fragment implementation requirements in the United States.
- Regulatory Compliance:Cross-border data transfer protocols and conformity documentation for multi-jurisdictional operations. GDPR Article 30 processing activity registers and EU AI Act risk-classification frameworks shape European deployments.
- Clinical Trials:Chain-of-custody tracking for investigational data with embedded electronic signature and audit trail capabilities. FDA 21 CFR Part 11 mandates force pharmaceutical manufacturers toward validated document management systems.
- Financial Auditing:Revenue cycle data integrity controls and administrative health record governance. Insurance companies demand these for fraud detection and claims processing accuracy.
Deployment scale peaks in Patient Records. Regulatory Compliance is gaining share fastest as algorithmic accountability requirements proliferate.
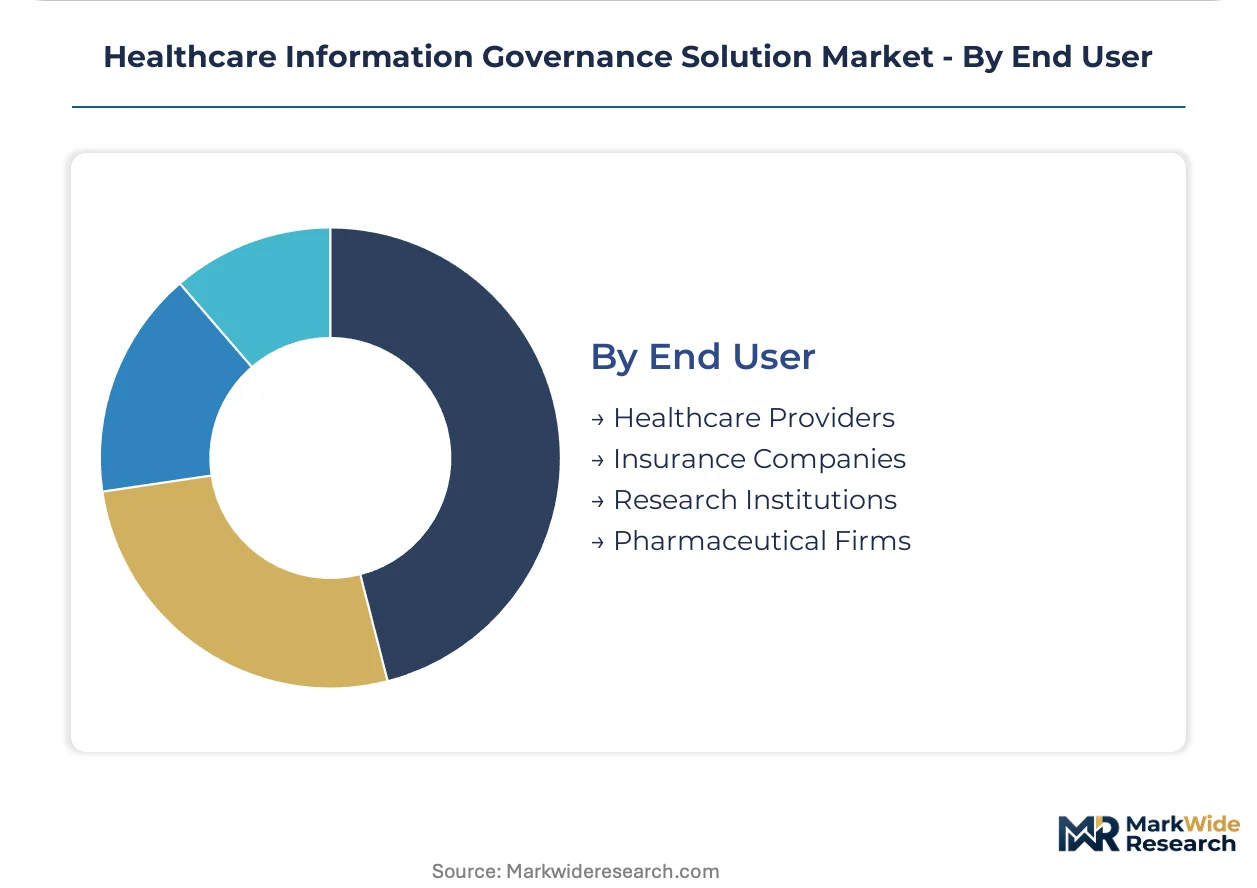
End User:
Margin concentration varies sharply, with pharmaceutical firms and research institutions accepting premium pricing for specialized validation capabilities that healthcare providers resist.
- Healthcare Providers:Hospital systems and clinical networks requiring integrated governance across administrative and clinical data streams. Zero-trust security architectures and microsegmentation mandates in large United States systems compress vendor evaluation criteria.
- Pharmaceutical Firms:Document management systems with embedded governance controls for FDA 21 CFR Part 11 compliance. Electronic signature and audit trail mandates force upgrades from legacy quality management platforms.
- Insurance Companies:Claims data governance and member privacy management frameworks. State-level privacy statutes in California, Virginia, and Colorado drive demand for jurisdiction-aware policy engines.
- Research Institutions:Multi-site data sharing agreements and consent management for secondary research use. Academic medical centers balance open science objectives against GDPR and HIPAA constraints.
Revenue concentration sits with Healthcare Providers. Pharmaceutical Firms show the steepest expansion trajectory as FDA enforcement intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Healthcare Information Governance Solution Market traces its commercial roots to the United States, where HIPAA enforcement in the late 1990s created the first structured demand for automated compliance infrastructure among hospital systems and pharmaceutical manufacturers.
United States
Hospital procurement of cloud-native governance suites accelerates following the 2023 HIPAA Security Rule updates, with integrated delivery networks retiring legacy on-premise data warehouses. FDA 21 CFR Part 11 mandates force pharmaceutical manufacturers toward validated document management systems with embedded electronic signature capabilities. The Boston-Cambridge corridor anchors biotech cluster demand for clinical trial data governance platforms.
Germany
Regional hospital alliances pool governance infrastructure across member institutions to achieve operational expenditure predictability for encryption key management. The EU AI Act's risk-classification framework forces algorithmic impact assessments into standard procurement workflows for diagnostic algorithms. The Rhine-Ruhr metropolitan region concentrates deployment of hybrid cloud architectures bridging legacy systems with cloud-native policy engines.
United Kingdom
NHS trusts prioritize automated retention policy enforcement as patient data volumes expand across federated care networks. GDPR Article 30 processing activity register requirements drive demand for built-in record-of-processing automation among clinical networks. London's academic medical centers balance open science objectives against data protection constraints for multi-site research data sharing agreements.
Japan
Medical device manufacturers invest in chain-of-custody tracking systems to satisfy PMDA quality management system requirements for software as a medical device. METI guidance on healthcare data utilization promotes standardization of anonymization protocols for secondary research use. The Kansai region's pharmaceutical manufacturing belt generates concentrated demand for FDA-aligned audit trail capabilities in export-oriented operations.
India
IT services hubs in Bengaluru and Hyderabad develop governance implementation capabilities for North American and European health system clients. CDSCO's evolving digital health regulatory framework creates domestic compliance infrastructure requirements for telemedicine platforms and electronic health record vendors. The National Health Authority's Ayushman Bharat Digital Mission drives standardization of health data exchange protocols across public and private provider networks.
Healthcare Information Governance Solution Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light software specialists across deployment models, with cloud-native suites displacing perpetual-license architectures in procurement conversations. The vendor base stratifies across three tiers: enterprise technology conglomerates with hybrid cloud portfolios, healthcare-focused software vendors with deep electronic health record integration, and specialized compliance automation firms with jurisdiction-specific policy engines. Dominant competitive moves include strategic partnerships between governance platforms and major cloud identity providers, plus portfolio diversification into AI-driven clinical document classification.
Within the enterprise technology tier, IBM and Oracle occupy anchor positions through contrasting architectural approaches—IBM leverages hybrid cloud infrastructure for multi-site hospital system deployments, while Oracle competes on interoperability depth with integrated electronic health record pipelines. Epic Systems Corporation exemplifies the healthcare-native specialist archetype, with governance capabilities embedded within dominant clinical workflow platforms. McKesson Corporation represents the vertically integrated healthcare services model, where data governance functions align with pharmaceutical distribution and care management operations.
| Leading Market Players |
|---|
| IBM |
| Oracle |
| McKesson Corporation |
| Optum |
| Veradigm |
| athenahealth |
| Cognizant |
| GE Healthcare |
| Epic Systems Corporation |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up compliance automation specialists now control significant market share across cloud-native governance suites, compressing pricing discipline through portfolio company cross-selling while concentrating supply relationships with hyperscale cloud infrastructure providers. This ownership pattern feeds directly into procurement behavior: hospital systems face bundled pricing pressure from integrated delivery networks that pool governance infrastructure across member institutions.
Pricing Analysis
Subscription-based governance-as-a-service models dominate procurement conversations, with three-tier pricing structure across premium, standard, and economy levels anchored to encryption-at-rest module depth and jurisdiction-aware policy engine sophistication. Price differentiation hinges on HIPAA Security Rule certification tier and FHIR R4 implementation guide coverage, with mid-sized hospital IT budgets showing acute sensitivity to per-petabyte licensing. Cost compression in the standard tier is intensifying because cloud-native entrants are undercutting legacy on-premise vendors on operational expenditure predictability.
Supply Chain Analysis
Single-source vulnerability sits with United States-based hyperscale cloud infrastructure providers that host the majority of hospital system governance deployments. Software development draws from India, Ireland, and Poland for NLP engine talent and compliance automation engineering. Supply chain risk centers on regulatory restriction: EU AI Act conformity documentation requirements threaten to fragment certification tracks. Distribution runs through direct enterprise sales teams and channel partners embedded within major electronic health record ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare information governance solutions constitute a late-cycle quality story as hospital procurement committees prioritize algorithmic accountability documentation and zero-trust security architectures over basic compliance checklists. Demand is shifting toward premium specifications that bundle EU AI Act risk-classification templates with automated retention policy enforcement.
For Market Incumbents: Acquire specialized NLP engine capabilities to defend against cloud-native entrants automating clinical document classification at lower price points. Consolidate channel control through deeper integration with Epic Systems and Oracle electronic health record pipelines. Capacity addition in Germany and the Netherlands addresses regional hospital alliance demand for pooled governance infrastructure. For New Entrants and Emerging Players: Regional hospital alliances in secondary United States markets represent an underserved buyer archetype with limited internal clinical informatics talent and strained IT budgets. The most penetrable segment is compliance tracking modules for state-level privacy statute fragmentation. A direct-to-CIO go-to-market angle emphasizing operational expenditure predictability over capital ownership resonates with mid-market health systems. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid solution vendors with federated architecture expertise but limited brand recognition in multi-site hospital systems. Long-term viability over a five-to-ten year window depends on FHIR R4 certification depth and cloud identity provider integration breadth. The signal to watch is FDA enforcement intensity against pharmaceutical manufacturers for 21 CFR Part 11 audit trail deficiencies.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Hospital systems retire on-premise data warehouses to reduce infrastructure overhead and accelerate HIPAA compliance audits. |
| EU AI Act Conformity Documentation | European clinical networks require pre-built risk-classification templates for diagnostic algorithm procurement workflows. |
| Zero-Trust Security Architecture Integration | Large United States systems mandate microsegmentation, compressing vendor evaluation around identity-aware proxy capabilities. |
| NLP Engine Acquisition | Automated unstructured clinical document review cuts manual audit preparation time for compliance teams. |
| Regional Hospital Alliance Partnership | Pooled governance infrastructure across member institutions achieves operational expenditure predictability for encryption key management. |
Research Methodology
Multiple input streams — hospital CIO interviews, pharmaceutical regulatory affairs director consultations, GPO contracts managers, and cloud infrastructure procurement officers — were reconciled against secondary validation from FDA 510(k) filings, CMS Medicare cost reports, hospital procurement databases, and hyperscaler healthcare vertical revenue disclosures. Bottom-up triangulation across deployment scale estimates and top-down cross-checks against integrated delivery network IT expenditure patterns anchored market sizing.
Data-stream reconciliation fed analytical frameworks spanning product type, technology architecture, application scope, and end-user category across the projection horizon. CAGRs were derived from segment-specific adoption curves weighted by regulatory enforcement intensity and cloud migration velocity. Forecast inputs included HIPAA Security Rule audit frequency trends and EU AI Act implementation timelines for clinical decision-support systems.
Underlying measurement precision varies by segment; cloud-based solutions and AI-driven tools carry tighter precision than aging on-premise installations with opaque renewal patterns. Forecasts reflect assumptions around FDA 21 CFR Part 11 enforcement continuity and state-level privacy statute proliferation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Healthcare Information Software Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
Medical Information Market
Medical Information Systems
AI in Medical Coding Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Medical Software Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Electronic Medical Record Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Ambulatory Software Market
Medical Information Systems
Global Healthcare Software As a Service Market
Medical Information Systems
Urology EMR Software Market
Medical Information Systems
Medical Alert Systems Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
Master Patient Index Software Market